
 Flip Chip Market | 2026-2036
Flip Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Flip Chip Market Intelligence
The move toward ultra-fine pitch interconnects is rotating the market toward higher-value applications. Taiwan Semiconductor Manufacturing Company (TSMC) leads the industry with its integrated fan-out and advanced packaging capabilities. Amkor Technology Inc. specializes in providing outsourced semiconductor assembly and test (OSAT) services for a diverse global client base. Intel Corporation leverages its captive supply of flip chips to optimize performance and integration in its own high-performance processor architectures.
A flip chip is a method for interconnecting semiconductor devices where a die is inverted and mounted directly onto a substrate or another die. This process utilizes solder bumps deposited on chip pads, creating shorter electrical paths and superior thermal performance compared to traditional wire bonding. While the consumer electronics application segment remains a high-volume driver, the data centers segment offers significantly higher margins for advanced packages. Thermocompression technology is gaining share for applications requiring the finest pitch and highest reliability.
Material composition in flip chip manufacturing is governed by regulations like the EU's RoHS directive, restricting specific hazardous substances. In the United States, the EPA sets standards for chemical usage in semiconductor fabrication, while China's GB standards influence component specifications. Key strategic decisions for OEMs will center on balancing the capital costs of in-house advanced packaging against reliance on specialized outsourced assembly and test providers.
Market Dynamics
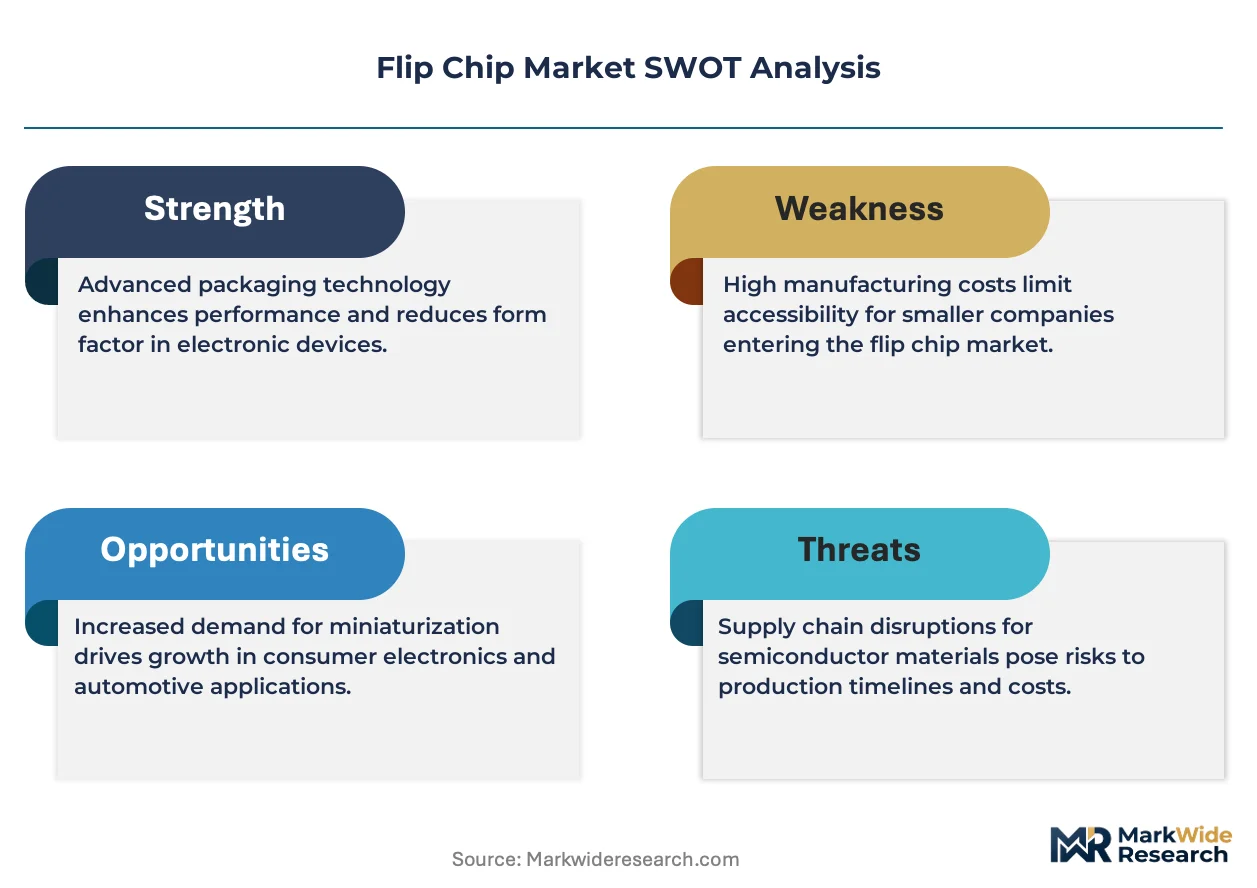
The central dynamic in the flip chip market is the bifurcation of demand between high-volume, cost-sensitive consumer electronics and high-margin, performance-driven applications like data centers. This split forces suppliers to manage distinct technology roadmaps and investment strategies simultaneously.
Growth Catalysts
- Micro-Bump Technology:The adoption of copper pillar and micro-bump interconnects enables significantly higher I/O density and superior electrical performance, which is essential for next-generation processors used in artificial intelligence and high-performance computing.
- Data Center Expansion:Intense demand from hyperscale data centers for faster, more power-efficient processors and accelerators directly stimulates the market for advanced flip chip packages that offer improved thermal dissipation and signal integrity.
- Semiconductor Policies:Government initiatives in the United States and Europe aimed at onshoring semiconductor manufacturing provide incentives for building domestic advanced packaging capacity, supporting regional market expansion and supply chain diversification.
Market Restraints
- High Capital Costs:The equipment required for advanced flip chip processes, such as thermocompression bonders and inspection tools for ultra-fine pitches, represents a significant capital investment, creating a high barrier to entry for smaller firms.
- Process Complexity:Achieving high yields with sub-20-micron pitch interconnects is technically challenging, requiring stringent process control and materials science expertise, which can limit production scalability and increase manufacturing costs.
- Geographic Concentration:The heavy concentration of leading-edge packaging and testing services in Taiwan and South Korea exposes the global supply chain to significant geopolitical risks and potential disruptions.
Strategic Opportunities
- Automotive Electronics:The increasing complexity of ADAS, infotainment, and vehicle control units creates a substantial opportunity for high-reliability flip chip packages that can withstand harsh automotive operating environments.
- Hybrid Bonding:The development of die-to-wafer and wafer-to-wafer hybrid bonding presents a long-term opportunity to move beyond solder-based interconnects, offering a path to even greater I/O density and performance for future chiplet architectures.
- OSAT Diversification:Fabless semiconductor companies and OEMs are actively seeking to qualify new outsourced assembly and test (OSAT) partners in alternative geographies like Southeast Asia or North America to build more resilient supply chains.
Industry Challenges
- Specialized Talent Scarcity:A shortage of packaging engineers and technicians with expertise in next-generation materials and processes, including thermocompression and hybrid bonding, constrains the pace of innovation and production ramp-ups.
- Lack of Standardization:The absence of universal standards for chiplet interfaces and die-to-die communication protocols complicates the integration of components from different vendors, slowing the development of a robust multi-vendor ecosystem.
- Regulatory Compliance:Manufacturers must navigate a complex web of materials regulations, such as the EU's RoHS and REACH directives, which dictate the chemical composition of solders and underfills, adding to qualification time and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flip Chip Market |
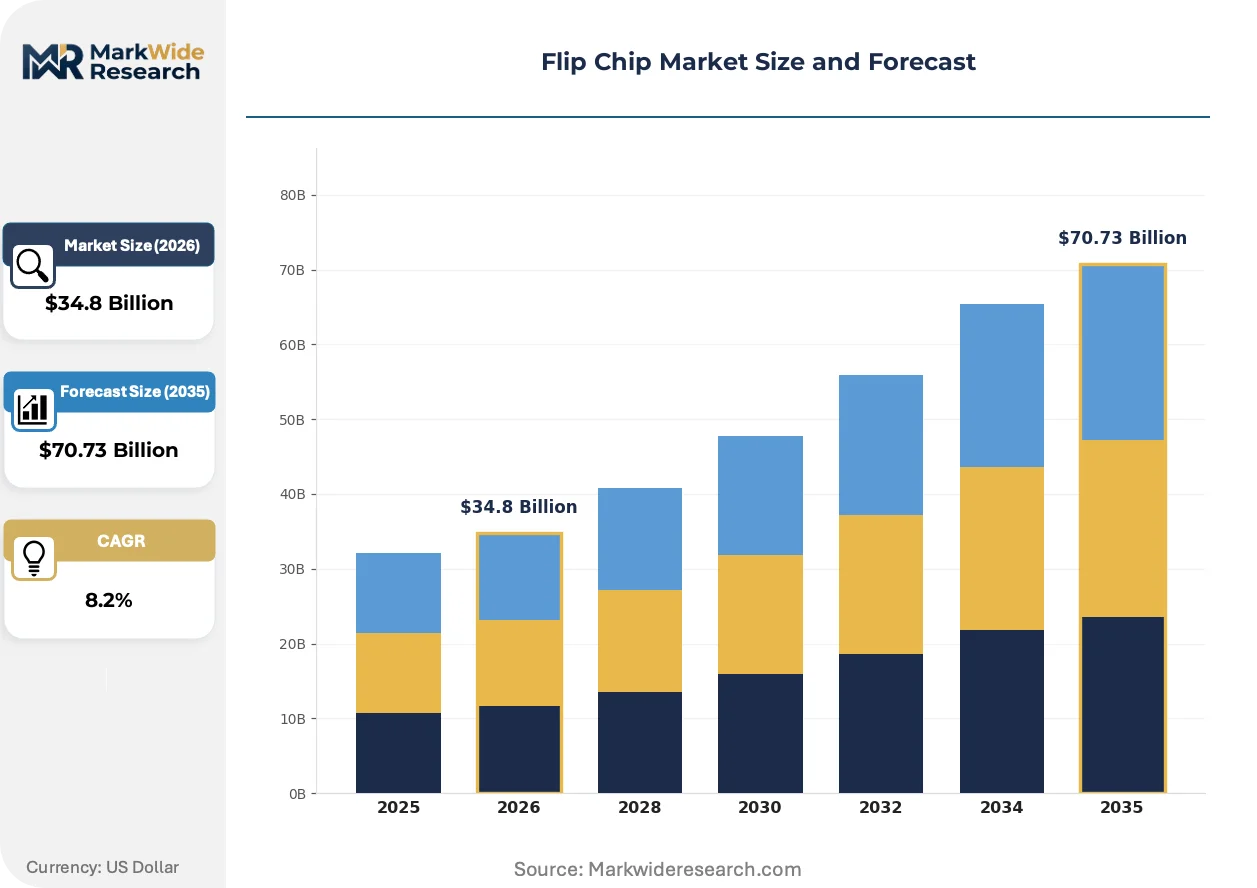
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $70.73 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Density Interconnect, Standard Flip Chip, Ultra-Fine Pitch, Wafer-Level Package, Fan-Out Package Technology: Thermocompression, Thermosonic, Electroplating, Anisotropic Conductive Film, Micro-Bump Technology Application: Consumer Electronics, Telecommunications Equipment, Data Centers, Aerospace Systems, Military Electronics End User: OEMs, Tier-1 Suppliers, Electronic Manufacturing Services, Semiconductor Foundries |
| Companies Covered | Intel Corporation, Chipbond Technology Corporation, Taiwan Semiconductor Manufacturing Company (TSMC), Siliconware Precision Industries Co. Ltd., UTAC Holdings Ltd, Amkor Technology Inc., Samsung Electronics Co. Ltd., Advanced Micro Devices Inc., ASE Technology Holding Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flip Chip Market Strategic Shifts & Innovations
The evolution of packaging technology is defined by the industry's push toward heterogeneous integration. This approach uses flip chip and other advanced methods to combine multiple specialized chiplets into a single, powerful system-in-package, overcoming the physical limits of monolithic die scaling.
Thermocompression bonding (TCB) is a precise assembly process that uses heat and force to create reliable interconnects. It is being adopted by manufacturers of high-performance computing chips and AI accelerators that require extremely fine pitch connections. For high-value applications where density and electrical integrity are critical, TCB is displacing traditional mass reflow soldering techniques.
Environmental regulations, particularly the EU's RoHS directive, govern material composition in semiconductor packaging. This rule restricts the use of lead and other hazardous substances in solder bumps, compelling a market-wide shift to lead-free solder alloys like tin-silver-copper (SAC). The consumer electronics and automotive segments are most affected, requiring extensive requalification of materials and processes to ensure compliance for market access in Europe.
A strategic shift in procurement models is underway as device manufacturers move away from single-source dependencies for advanced packaging. This change disrupts exclusive relationships with top-tier foundries and OSATs, promoting a multi-sourcing approach to mitigate supply chain risks. This pattern is most pronounced among large-volume customers in the smartphone and data center sectors who prioritize supply resilience alongside technological capability.
Flip Chip Market Segmentation
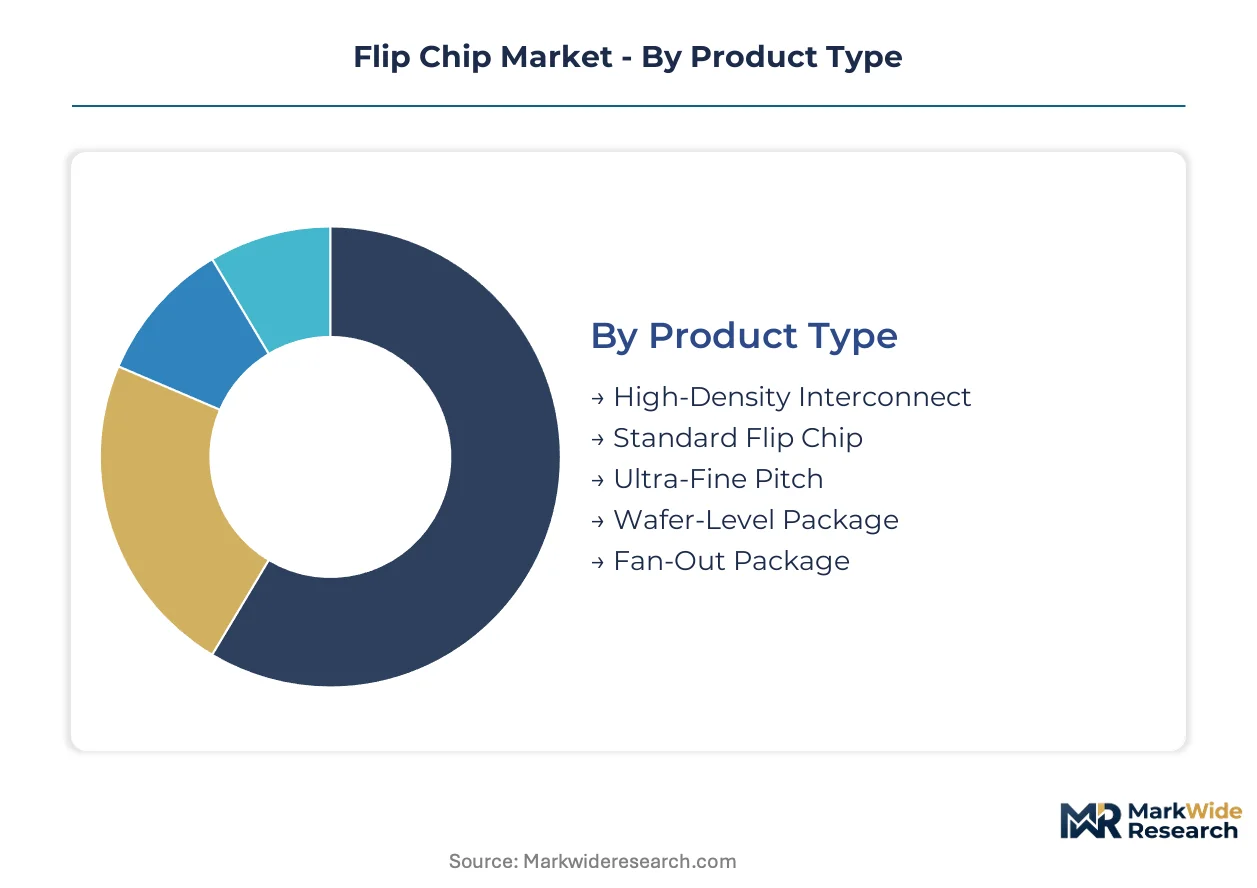
The flip chip market segments across diverse product types, technologies, applications, and end-users, each presenting unique demands and growth trajectories. Understanding these distinct segments is crucial for identifying areas of concentrated investment and technological advancement. This detailed segmentation highlights the varied requirements driving innovation across the semiconductor industry.
Product Type:
The various product types of flip chips are distributed through specialized fabrication and assembly channels, each optimized for different performance and cost requirements.
- Ultra-Fine Pitch:This category includes flip chips with interconnect pitches typically below 40 microns, enabling higher I/O density and enhanced electrical performance for advanced processors. Demand concentrates in high-performance computing and AI accelerators, driven by the need for maximum data throughput.
- Fan-Out Package:These packages extend the die area with a re-distribution layer, allowing for more I/O connections and integration of multiple dies into a single package. The telecommunications and data center segments drive demand, seeking miniaturization and improved thermal management for complex systems.
- High-Density Interconnect:These flip chips feature interconnects with pitches ranging from 40 to 150 microns, offering a balance of performance and cost.
- Standard Flip Chip:This segment includes conventional flip chip designs with pitches above 150 microns, widely used in consumer electronics for cost-effective integration.
- Wafer-Level Package:These packages are fabricated directly on the wafer before dicing, enabling smaller form factors and reduced manufacturing costs for mobile devices.
By volume, Standard Flip Chip leads the market. By growth pace, Ultra-Fine Pitch represents the fastest-growing trajectory.
Technology:
Different flip chip bonding technologies are selected based on the required performance, reliability, and cost-margin trade-offs for specific applications.
- Thermocompression:This precise bonding method uses heat and force to create robust interconnects, suitable for ultra-fine pitch applications requiring high reliability and electrical integrity. High-end computing and automotive electronics drive its adoption due to stringent performance and environmental demands.
- Micro-Bump Technology:This technology utilizes extremely small solder bumps, typically copper pillars, to achieve very high I/O densities and superior electrical characteristics. Data centers and AI hardware demand this technology for next-generation processors and memory integration.
- Thermosonic:This bonding technique combines heat, pressure, and ultrasonic energy to create interconnections, often used for fine-pitch applications in various consumer devices.
- Electroplating:This process forms solder bumps directly on the wafer using electrochemical deposition, offering cost-effective production for high-volume flip chip manufacturing.
- Anisotropic Conductive Film:This material contains conductive particles that establish electrical connections only in the vertical direction when compressed, simplifying assembly for display drivers and sensors.
Thermocompression technology demonstrates increasing maturity for high-performance applications, while Micro-Bump Technology continues to drive innovation in density.
Application:
The volume and performance demands across various application segments dictate the specific flip chip configurations and packaging solutions employed.
- Data Centers:This segment demands high-performance, power-efficient flip chips for processors, accelerators, and memory modules, crucial for hyperscale operations. The intense demand for faster data processing and improved thermal management drives continuous innovation in advanced packaging solutions.
- Consumer Electronics:This segment represents a high-volume driver for flip chips used in smartphones, tablets, and wearable devices, prioritizing miniaturization and cost-effectiveness. Miniaturization and extended battery life are critical design considerations for these devices.
- Telecommunications Equipment:Flip chips are essential for high-frequency and high-bandwidth components in 5G infrastructure, routers, and network switches.
- Aerospace Systems:This application requires highly reliable and robust flip chips that can withstand extreme temperatures and harsh operating environments.
- Military Electronics:Flip chips are integrated into defense systems and avionics, demanding stringent quality, security, and long-term reliability standards.
Data centers exhibit a concentrated demand for advanced flip chips, while consumer electronics drive broad-based adoption.
End User:
Different end-user types engage with the flip chip market at various stages of the value chain, influencing design, manufacturing, and procurement decisions.
- Semiconductor Foundries:These entities specialize in the fabrication of integrated circuits and often integrate advanced packaging services, including flip chip assembly, to offer comprehensive solutions. Taiwan Semiconductor Manufacturing Company represents a key player driving innovation in this segment.
- OEMs:Original Equipment Manufacturers design and sell finished products, making strategic decisions about integrating flip chips, balancing in-house advanced packaging capabilities against reliance on outsourced services. Intel Corporation leverages captive flip chip supply for its high-performance processors.
- Tier-1 Suppliers:These companies provide critical components and modules to OEMs, often incorporating flip chips into their sub-assemblies for automotive or industrial applications.
- Electronic Manufacturing Services:EMS providers offer manufacturing and assembly services for electronic components, including flip chip integration, to a diverse client base.
OEMs prioritize cost-effectiveness for high-volume products, while Semiconductor Foundries focus on advanced process development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global flip chip market exhibits a complex interplay between technology export hubs and regions with significant domestic demand. Advanced packaging solutions often originate in specialized manufacturing centers, while consumption is distributed across major electronics and data center markets. This dynamic shapes investment in new fabrication capabilities and supply chain resilience initiatives worldwide.
United States
United States demand for flip chips stems from its robust high-performance computing and artificial intelligence accelerator sectors. The CHIPS Act provides significant incentives for building domestic semiconductor manufacturing and advanced packaging capacity. Silicon Valley in California drives continuous innovation in flip chip design and application for next-generation processors.
China
China's vast consumer electronics market and expanding data center infrastructure generate substantial demand for flip chips. National GB standards influence component specifications, ensuring compliance for products sold within the country. The Yangtze River Delta region, particularly around Shanghai, concentrates significant semiconductor assembly and test operations, supporting domestic production.
South Korea
South Korea's leadership in memory chips and mobile devices fuels its demand for advanced flip chip packaging. Government initiatives actively support research and development in advanced packaging technologies and manufacturing capabilities. Gyeonggi Province hosts major memory and logic semiconductor foundries, driving innovation in flip chip integration and production.
Taiwan
Taiwan's semiconductor foundries represent a major concentration of flip chip manufacturing and innovation. Local policies foster a competitive environment, attracting continuous investment in advanced packaging and research and development. Hsinchu Science Park remains a global hub for leading-edge semiconductor foundries, driving the development of ultra-fine pitch interconnects.
Germany
Germany's robust automotive electronics and industrial automation sectors create specific demand for high-reliability flip chip packages. The EU's RoHS directive strictly governs material composition, influencing solder and underfill choices for market access. Dresden, often called 'Silicon Saxony,' specializes in automotive and industrial semiconductor manufacturing, including advanced packaging.
Flip Chip Market Key Industry Players
Listed leaders compete with private specialists across the flip chip market's technology and application spectrum. The market structure features both highly consolidated segments, particularly in advanced packaging services, and more fragmented areas for niche applications. Strategic archetypes include integrated device manufacturers, pure-play foundries, and outsourced assembly and test providers. Capacity expansion and strategic partnerships remain dominant competitive moves across the industry.
Integrated device manufacturers like Intel Corporation exemplify the captive supply model, optimizing flip chip integration for their own high-performance processor architectures. Pure-play foundries such as Taiwan Semiconductor Manufacturing Company (TSMC) represent the leading-edge technology providers, driving innovation in ultra-fine pitch interconnects and advanced packaging capabilities. Outsourced semiconductor assembly and test (OSAT) specialists like Amkor Technology Inc. occupy a critical position, providing diverse packaging services to a global client base, supporting varied customer needs across multiple end-use segments.
| Leading Market Players |
|---|
| Intel Corporation |
| Chipbond Technology Corporation |
| Taiwan Semiconductor Manufacturing Company (TSMC) |
| Siliconware Precision Industries Co. Ltd. |
| UTAC Holdings Ltd |
| Amkor Technology Inc. |
| Samsung Electronics Co. Ltd. |
| Advanced Micro Devices Inc. |
| ASE Technology Holding Co. Ltd. |
| Others |
Cost & Logistics Intelligence
The immense capital investment required for advanced flip chip manufacturing shapes both supply concentration and the underlying price floors for packaging services. This dynamic necessitates strategic partnerships and long-term contracts to ensure supply stability and manage pricing volatility across diverse application segments.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing models for high-reliability flip chips, often involving multi-year agreements. Price differentiation stems from performance specifications, such as ultra-fine pitch density, and stringent certification levels for automotive or military use. Pricing softness primarily affects the high-volume consumer electronics segment, driven by intense competition and cost optimization pressures. Data centers and automotive electronics exhibit lower price sensitivity due to performance and reliability requirements.
Supply Chain Analysis
The heavy concentration of leading-edge packaging and testing services in Taiwan and South Korea exposes the global supply chain to significant geopolitical risks. Raw material dependencies include specialized silicon wafers, advanced solder alloys, and underfill materials. Geopolitical disruptions or trade restrictions represent a structural supply chain risk. Distribution runs through direct sales channels to major integrated device manufacturers and fabless companies, alongside specialized outsourced semiconductor assembly and test providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a substitution defense, as hybrid bonding presents a long-term threat to traditional solder-based interconnects.
For Market Incumbents:Consolidate R&D efforts in advanced packaging materials and process technologies, particularly for thermocompression bonding. Expand advanced packaging capacity in diversified geographies like the United States or Europe to mitigate geopolitical risks. Proactively invest in hybrid bonding development to secure future competitive positioning against emerging integration methods. This strategy defends against the rapid adoption of alternative interconnect solutions by leading foundries.
For New Entrants and Emerging Players:Certification fast-track for automotive-grade flip chips in Europe offers a viable entry point for specialized providers. Target underpenetrated segments requiring high-reliability packages, such as industrial IoT or medical devices. A go-to-market angle focusing on niche, high-performance applications with stringent quality requirements can bypass direct competition with high-volume players. Specialize in advanced materials science for fine-pitch interconnects.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized OSATs with proprietary advanced packaging intellectual property and established customer relationships. Long-term viability for flip chip technology remains robust due to the increasing adoption of chiplet architectures and heterogeneous integration. Acquisition targets should include firms demonstrating expertise in thermocompression bonding or advanced micro-bump technologies. The signal to watch is increased government funding for domestic advanced packaging infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in New Geographies | Diversifies manufacturing footprint, reducing reliance on concentrated regions for critical supply. |
| R&D Investment in Advanced Materials | Enables higher interconnect density and improved electrical performance for next-generation processors. |
| Strategic Partnerships with Fabless Companies | Fosters co-development of custom packaging solutions tailored to specific high-performance computing needs. |
| Attainment of Automotive-Grade Certifications | Unlocks access to the high-reliability, growing automotive electronics application segment. |
| Process Optimization for Thermocompression Bonding | Improves yield rates and reduces manufacturing costs for ultra-fine pitch AI accelerators. |
Research Approach
Two parallel data streams informed the analysis: extensive primary market conversations and rigorous secondary research. Primary insights were gathered from semiconductor foundry executives, OEM procurement specialists, advanced packaging engineers, and OSAT operations managers. Secondary data sources included company 10-K filings, government technology reports, industry consortium publications, and patent databases, triangulated with bottom-up and top-down approaches.
The comprehensive analytical framework projects market trajectories across the analysis window, considering various product types, bonding technologies, end-use applications, and key geographic regions. Compound annual growth rates were derived from historical trends and future demand projections, integrating market dynamics and technological advancements. Key forecast inputs included global semiconductor capital expenditure and data center expansion rates.
Decision-makers should treat outputs as directional under current geopolitical stability and technological roadmap assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions regarding material supply chain resilience and regulatory consistency. Practitioners should keep alternative scenarios live as macroeconomic conditions and technological advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
Embedded Multimedia Card Market
Semiconductor Devices
Ferroelectric FET Market
Semiconductor Devices
DNA Chip Market
Semiconductor Devices
T-Con Board Market
Semiconductor Devices
Silicon on Insulator Market
Semiconductor Devices
MBE Components Market
Semiconductor Devices
Leadframes Market
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
Pcie Switches Market
Semiconductor Devices
Non-Volatile Dual in-Line Memory Module Market
Semiconductor Devices
Japan Semiconductor Diode Market
Semiconductor Devices
Asia Pacific Motherboard Market
Semiconductor Devices
Global Power MOSFET Market
Semiconductor Devices
North America Silicon Carbide Wafers Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market