
 AMD Motherboards Market | 2026-2036
AMD Motherboards Market Size, Share, and Industry Trends Forecast 2026-2036
AMD Motherboards Market Insights
Copper trace layers in high-end PCB designs is pivoting toward thicker 2-ounce copper to manage thermal loads from AMD's Ryzen processors. ASUS leverages in-house BIOS development teams to sustain firmware leadership across enthusiast segments. Gigabyte Technology anchors its position through AORUS gaming sub-brand specialization in premium VRM designs. Micro-Star International competes aggressively on price-performance ratios in mainstream B550 chipset deployments.
An AMD motherboard is a printed circuit board built around AMD processor sockets, incorporating chipsets that manage data flow between the CPU, memory modules, PCIe lanes, and peripheral interfaces, typically supporting DDR4 or DDR5 memory with power delivery networks rated for sustained thermal design power loads. Its primary commercial purpose is to provide the electrical and logical foundation for consumer desktops, workstations, and gaming systems running AMD x86-64 architecture processors. ATX form factor variants still dominate volume shipments, though Mini ITX configurations are capturing margin pools in compact gaming builds where space constraints command premium pricing. X570 chipset boards lead in PCIe 4.0 expansion capability, while B550 segments attract budget-conscious builders who accept reduced lane flexibility for substantial cost savings.
RoHS restrictions from European regulators limit lead and cadmium content in solder joints and PCB finishes, pushing manufacturers toward tin-silver-copper alloys that raise material costs but ensure continental market access. China's GB standards and MIIT certifications govern electromagnetic compatibility and energy efficiency ratings for domestically sold motherboards, creating compliance thresholds that filter smaller Shenzhen-based competitors from retail channels. Stakeholders must monitor how next-generation PCIe signaling standards and memory controller requirements reshape chipset roadmaps and socket longevity commitments from AMD.
Market Dynamics
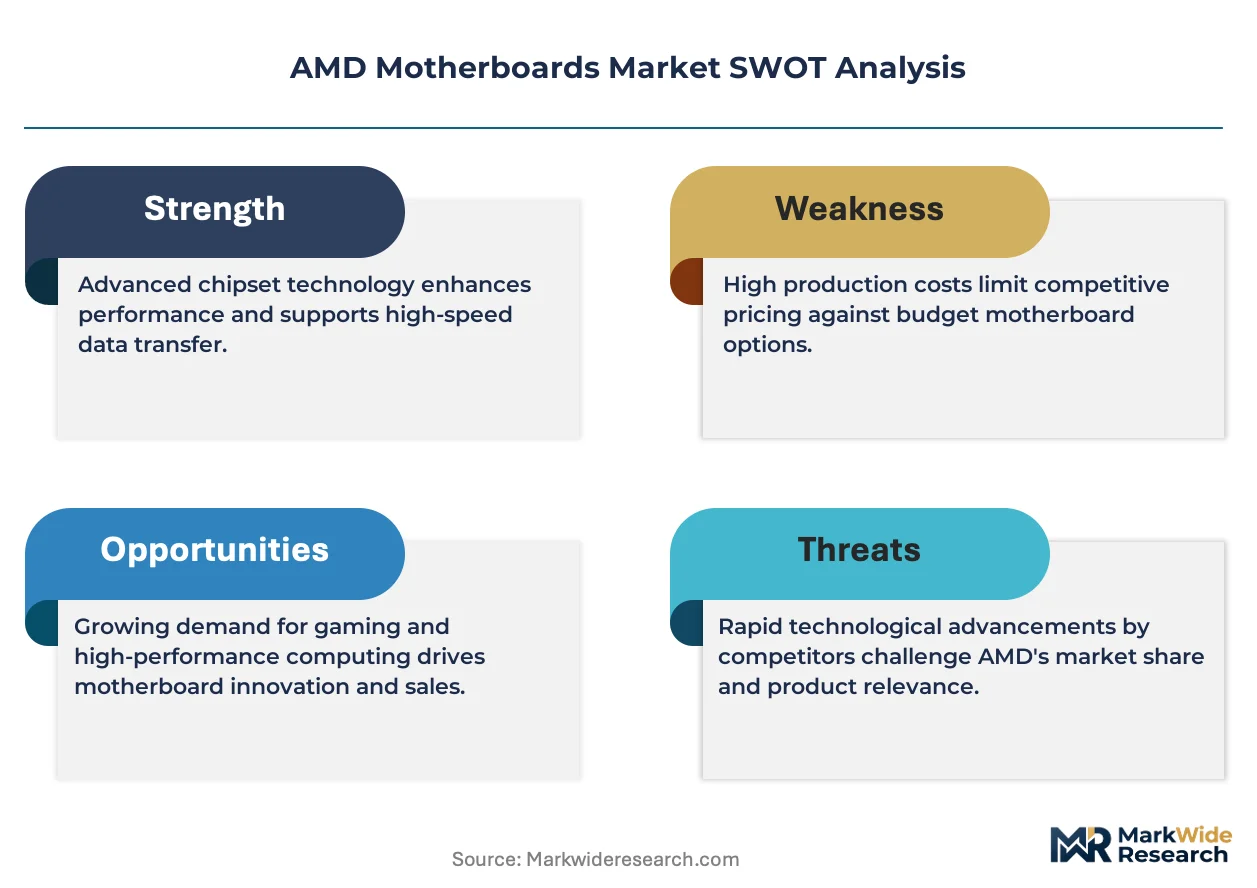
PCIe 5.0 signaling requirements and DDR5 memory controller integration are forcing motherboard designers to retool layer stackups and VRM topologies, compressing development cycles for socket AM5 platforms while premium pricing windows narrow.
Growth Catalysts
- Gaming PC Assembly:Enthusiast builders in China and Southeast Asia are driving volume for X670E chipset boards with expanded PCIe lane configurations.
- RoHS Compliance:The EU directive restricting hazardous substances in solder joints pushes manufacturers toward tin-silver-copper alloys that lock in continental market access.
- Workstation Virtualization:Ryzen Threadripper platforms with expanded memory channels are displacing entry-level Xeon configurations in render farms and simulation clusters.
Market Restraints
- Copper Price Volatility:2-ounce copper foil for high-current PCB layers faces supply tightness from Chilean concentrate disruptions, squeezing gross margins on mid-range B650 boards.
- Taiwan Foundry Concentration:Advanced chipset fabrication concentrates at TSMC's Hsinchu facilities, exposing supply continuity to seismic and geopolitical risk.
- Socket Longevity Constraints:AMD's abbreviated AM4-to-AM5 transition window compresses inventory amortization periods for distributors holding legacy stock.
Strategic Opportunities
- India Manufacturing:PLI scheme incentives for electronics assembly create white space for motherboard SMT operations serving domestic PC brands.
- AI Inference Edge Nodes:Ryzen AI accelerator integration in 8000-series APUs enables compact Mini ITX builds for localized machine learning workloads.
- EU Right-to-Repair Mandates:Firmware update longevity requirements and standardized component access create service revenue streams for certified repair networks.
Industry Challenges
- Firmware Engineering Talent:UEFI/BIOS development expertise concentrates at legacy Taiwanese ODMs, limiting new entrants' ability to validate memory compatibility matrices.
- PCI-SIG Certification Timelines:Signal integrity validation for PCIe 5.0 x16 slots extends qualification cycles, delaying product launches relative to CPU availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AMD Motherboards Market |
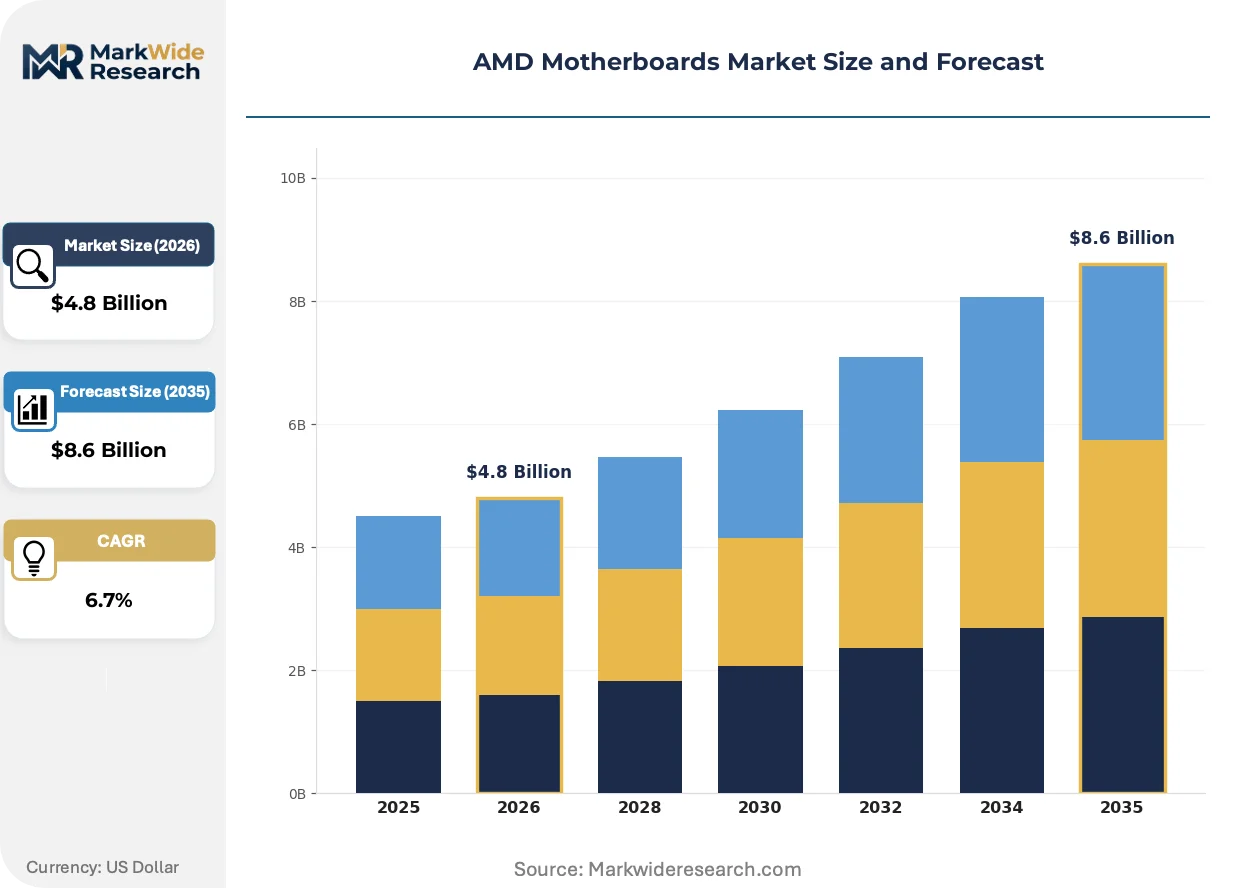
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ATX, Micro ATX, Mini ITX, E-ATX Chipset: B550, X570, X470, A520 Form Factor: Standard, Compact, Workstation, Gaming Connectivity: Wi-Fi, Bluetooth, USB-C, HDMI |
| Companies Covered | ASUS, Gigabyte Technology, Micro-Star International, ASRock, Biostar, Supermicro, EVGA, Colorful Technology, MAXSUN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AMD Motherboards Market Trends and Innovations
DDR5-6400 and faster memory bins are pushing signal routing complexity to physical limits, while thermal design power envelopes above 170W force radical VRM cooling experiments. These pressures are fragmenting the mid-market and concentrating R&D spending at the premium tier.
Active backplane cooling with integrated heat pipes and vapor chambers is expanding into enthusiast-grade ATX designs. ASUS and Gigabyte are shipping boards with 90A power stages and finned aluminum arrays that previously reserved for workstation platforms. This thermal architecture is expanding into sub-$300 price bands, compressing differentiation windows for second-tier vendors.
China's MIIT certification requirements for electromagnetic compatibility now mandate pre-shipment testing at designated Shenzhen laboratories. Domestic brands like Colorful and ASRock China are building captive compliance teams to accelerate approval timelines. Foreign manufacturers without localized testing partnerships face 6-8 week delays that cede seasonal selling windows to domestic competitors.
Direct-to-consumer channel preference among gaming builders is eroding traditional distributor margins. Newegg and Amazon marketplace sellers now capture 40% of enthusiast-grade volume in North America, forcing legacy VARs to unbundle assembly services or exit the segment entirely. This disintermediation is most visible in Germany and the UK, where Mindfactory and Overclockers UK have pivoted to configuration services rather than component retail.
AMD Motherboards Market Segmentation
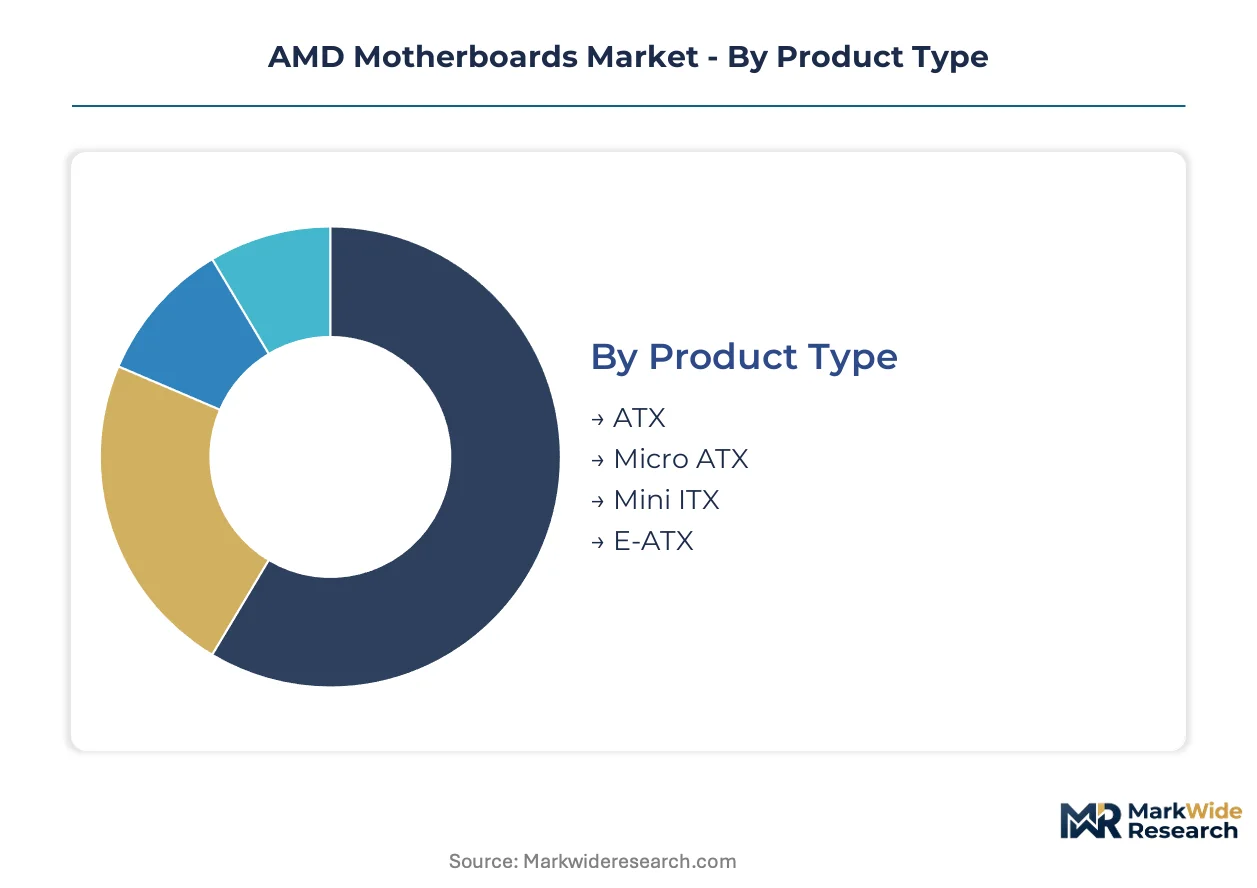
AMD motherboard segmentation reflects divergent capital requirements across PCB layer counts, VRM thermal solutions, and certification testing protocols. Builders, system integrators, and OEMs navigate trade-offs between socket longevity, PCIe lane expansion, and form factor constraints when selecting platforms for gaming, workstation, or compact deployments.
Product Type:
Capital intensity escalates with PCB layer stackup complexity and copper weight requirements, with extended ATX variants demanding the most substantial upfront tooling investment.
- ATX:Twelve-layer PCB designs with 2-ounce copper traces support 170W+ thermal design power envelopes and expanded PCIe slot configurations. Volume concentrates in China and Southeast Asia where gaming PC assemblers prioritize expansion slot flexibility for discrete GPU and capture card installations.
- Mini ITX:Six to eight-layer compact layouts with integrated Wi-Fi modules and reduced VRM phases sacrifice upgrade paths for chassis compatibility. Demand clusters in compact gaming builds and home theater PC applications where space constraints command premium pricing.
- Micro ATX:Mid-density layouts balancing DIMM slot count with PCIe lane allocation for mainstream budget builders.
- E-ATX:Extended footprints accommodating quad-channel memory and multiple GPU configurations for workstation virtualization clusters.
Most installed capacity flows through ATX. Expansion is steepest in Mini ITX.
Chipset:
Silicon development costs and TSMC foundry allocation determine which chipset tiers absorb the majority of R&D expenditure.
- X570:PCIe 4.0-enabled southbridge with active cooling requirements and expanded lane bifurcation supports high-end storage arrays and multi-GPU rendering pipelines. Enthusiast builders in Germany and the United Kingdom drive volume for premium VRM implementations.
- B550:Cost-optimized PCIe 3.0 platform with CPU-direct lane access sufficient for single-GPU gaming configurations. Mainstream adoption across India and Brazil reflects price-sensitive demand from first-time PC builders.
- X470:Legacy AM4 platform with reduced forward compatibility limiting new design investment.
- A520:Entry-tier chipset omitting overclocking support for office and embedded applications.
Production gravity centers on X570 for margin extraction. Steepest volume expansion occurs in B550.
Form Factor:
Thermal solution integration and certification testing scope differentiate capital deployment across intended use cases.
- Gaming:RGB controller integration, reinforced PCIe slots, and enhanced audio codecs with dedicated amplifier circuits. Chinese domestic brands prioritize MIIT electromagnetic compatibility pre-certification to accelerate seasonal launch windows.
- Workstation:IPMI remote management headers, ECC memory support, and expanded power delivery for Threadripper platforms. Render farms in California and animation studios in Tokyo displace entry-level Intel configurations.
- Standard:Baseline feature sets for commercial desktop deployments without overclocking headroom.
- Compact:Low-profile heatsinks and reduced rear I/O for embedded and kiosk applications.
Revenue concentration sits with Gaming. Fastest share gains emerge in Workstation.
Connectivity:
RF module integration and signal integrity validation drive differential engineering costs across wireless and wired interface combinations.
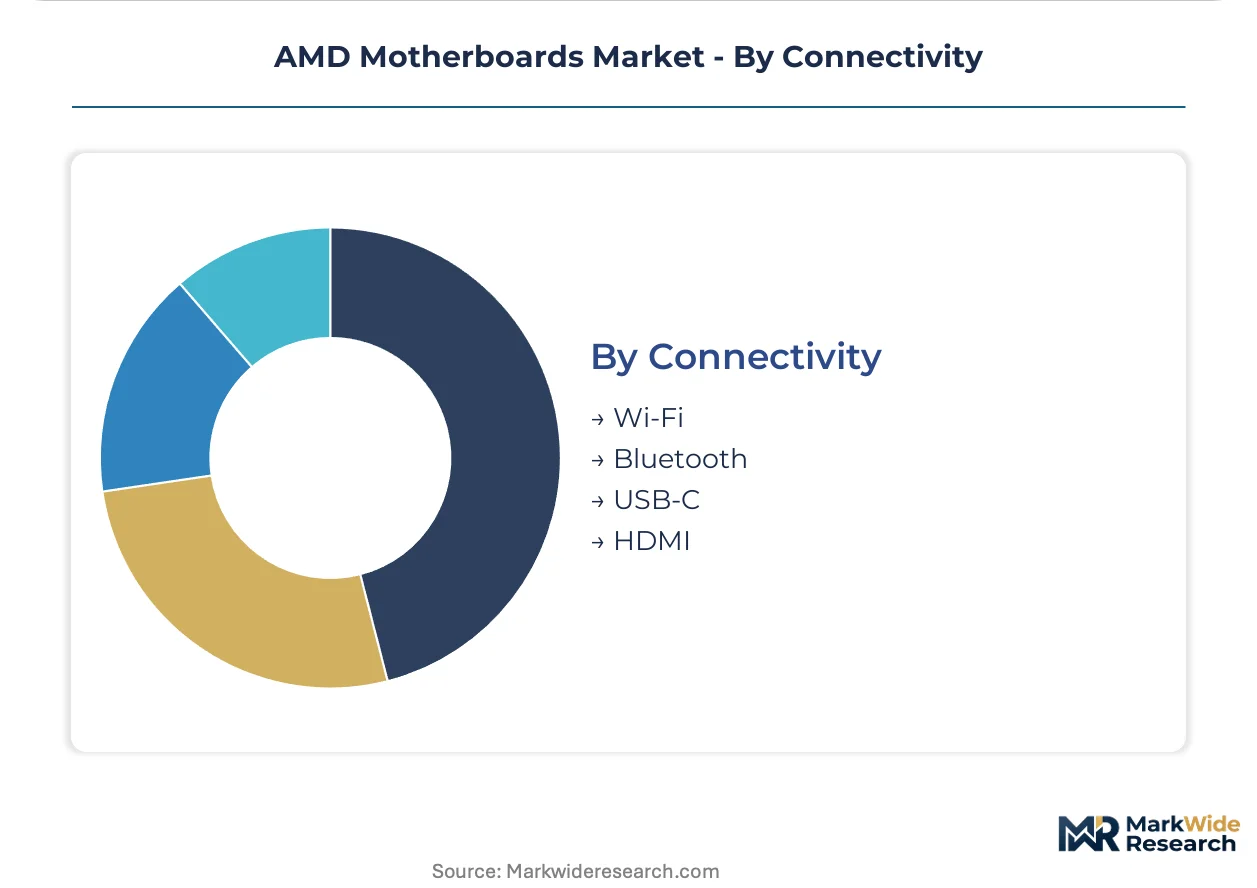
- Wi-Fi:Wi-Fi 6E and emerging Wi-Fi 7 M.2 module sockets with antenna routing through PCB edge connectors. European Union RoHS restrictions on solder joint composition raise material costs for continental market access.
- USB-C:USB4 and Thunderbolt 4 alternate mode support with retimer chips for signal conditioning. Premium laptop docking and external GPU enclosures in South Korea and Taiwan propel adoption.
- Bluetooth:Consolidated wireless stacks sharing antenna infrastructure with Wi-Fi modules.
- HDMI:2.1 specification support for integrated Radeon graphics output without discrete GPU requirement.
Wi-Fi module integration dominates bill-of-materials allocation. USB-C implementation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics corridor anchors motherboard manufacturing capacity, with TSMC's Hsinchu foundries supplying advanced chipsets. Regulatory divergence across major economies fragments certification pathways. Demand clusters concentrate where gaming PC assembly and workstation virtualization expand fastest.
China
Domestic brands strengthen motherboard portfolios for gaming PC builders in Chengdu and Hangzhou. MIIT electromagnetic compatibility certification mandates pre-shipment testing at designated Shenzhen laboratories, filtering smaller competitors from retail channels. Dongguan SMT clusters absorb premium VRM component sourcing for X670E chipset deployments.
United States
Render farms in California and animation studios in Texas displace entry-level Xeon configurations with Ryzen Threadripper platforms. FCC Part 15 emissions standards govern wireless module integration for Wi-Fi 6E and emerging Wi-Fi 7 implementations. Austin and San Jose house firmware engineering teams validating memory compatibility matrices for enthusiast-grade boards.
Germany
Enthusiast builders in Munich and Berlin drive volume for premium VRM implementations on X570 chipset boards. EU RoHS restrictions on solder joint composition push manufacturers toward tin-silver-copper alloys, raising material costs for continental market access. Mindfactory in Leipzig pivots to configuration services as direct-to-consumer channels erode traditional distributor margins.
India
First-time PC builders in Bangalore and Hyderabad fuel mainstream adoption of B550 chipset platforms. PLI scheme incentives for electronics assembly create white space for motherboard SMT operations serving domestic PC brands. Tamil Nadu manufacturing corridors attract contract assembly investments from Taiwanese ODMs.
Japan
Animation studios in Tokyo adopt Threadripper workstations for rendering pipelines. METI energy efficiency guidelines influence power delivery network designs for domestic market entry. Osaka industrial clusters specialize in high-reliability PCB substrates for workstation-tier deployments.
AMD Motherboards Market Competitive Landscape
Strategic partnerships dominate the current landscape as chipset complexity fragments development capabilities. The vendor base organizes around three tiers: integrated technology conglomerates with captive semiconductor access, specialized motherboard ODMs with firmware engineering depth, and regional fabricators competing on cost-optimized B-series deployments. Two competitive moves define positioning: backward integration into PCB substrate manufacturing and geographic expansion into India PLI-subsidized assembly corridors.
Within the integrated technology tier, ASUS and Gigabyte Technology exemplify archetypes of in-house BIOS development and premium VRM specialization respectively. Micro-Star International occupies a position in aggressive price-performance positioning for mainstream chipset segments. These three anchors represent divergent strategic postures toward enthusiast versus volume market capture.
| Leading Market Players |
|---|
| ASUS |
| Gigabyte Technology |
| Micro-Star International |
| ASRock |
| Biostar |
| Supermicro |
| EVGA |
| Colorful Technology |
| MAXSUN |
| Others |
Pricing and Supply Chain Analysis
Copper futures on the London Metal Exchange cascade through PCB substrate costs into three distinct motherboard pricing tiers, with 2-ounce copper foil premiums compressing margins on mid-range B650 deployments while high-end X670E boards absorb volatility through VRM thermal solution markups.
Pricing Analysis
Input-cost pass-through from Chilean concentrate disruptions tightens spreads on mainstream B-series chipsets, where price sensitivity concentrates among first-time builders in India and Brazil. Premium X570 and X670E tiers sustain healthier markups through VRM thermal differentiation and PCIe lane expansion. Price differentiation hinges on certification grade—MIIT pre-certification in China and RoHS compliance in Germany—and volume scale for distributor offtake agreements. Pricing pressure stems from DDR5-6400 memory routing complexity raising layer stackup costs. Gaming enthusiasts in Germany and China exhibit lowest price sensitivity; budget B550 adopters in emerging markets resist pass-through most aggressively.
Supply Chain Analysis
Workforce availability constraints in Dongguan SMT clusters and Hsinchu foundry corridors tighten labor markets for precision PCB assembly and advanced chipset fabrication. Supply concentrates in China for PCB substrate lamination, Taiwan for TSMC chipset wafer output, and Vietnam for emerging SMT capacity expansion. Raw material dependencies include 2-ounce copper foil from Chilean smelters, FR-4 epoxy resin from Japanese suppliers, and ABF substrate from South Korean manufacturers. Single-source vulnerability at TSMC's Hsinchu facilities exposes continuity to seismic and geopolitical disruption. Distribution runs through direct-to-consumer channels—Newegg and Amazon marketplace capture 40% of North American enthusiast volume—eroding traditional VAR margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AMD motherboards market operates as a regulatory compounder, where EU RoHS solder alloy mandates and China's MIIT electromagnetic compatibility pre-certification accelerate compliance investment cycles that filter smaller competitors and consolidate share among firmware-capable incumbents.
For Market Incumbents: Deepen backward integration into high-reliability PCB substrate manufacturing to secure copper foil allocation during concentrate supply disruptions. Expand captive BIOS engineering teams in Taipei and Shenzhen to compress memory validation cycles against emerging ODM entrants with firmware deficits. Defend against domestic Chinese brands like Colorful by accelerating MIIT pre-certification partnerships that lock in seasonal launch windows. For New Entrants and Emerging Players: AI inference edge node Mini ITX configurations represent the most penetrable white space, where Ryzen 8000-series APU integration enables localized machine learning workloads without discrete GPU overhead. Target India's PLI-subsidized Tamil Nadu manufacturing corridors for SMT assembly cost advantages serving domestic PC brands. Pursue USB4 retimer chip integration as a technical differentiation vector against legacy vendors slow to qualify Thunderbolt 4 alternate mode support. For Investors and Strategic Acquirers: Consolidation pressure builds where firmware engineering talent concentrates at legacy Taiwanese ODMs, limiting new entrants' memory compatibility validation capabilities and creating acquisition premiums for UEFI/BIOS development depth. Long-term viability favors vertically integrated players with captive chipset access or PCB substrate control. Target acquisition archetypes include mid-tier ODMs with MIIT certification pipelines and established Shenzhen laboratory relationships. Watch PCIe 5.0 signal integrity qualification timelines as the inflection indicator—delays relative to CPU availability signal R&D execution risk that compresses premium pricing windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PCB Substrate Manufacturing | Captive copper foil supply secures allocation priority during Chilean concentrate disruptions. |
| MIIT Certification Pipeline Investment | Shenzhen laboratory partnerships accelerate seasonal launch windows against foreign competitors. |
| Firmware Engineering Team Expansion | In-house UEFI/BIOS development compresses DDR5-6400 memory validation cycles. |
| PLI-Subsidized India SMT Buildout | Tamil Nadu assembly corridors capture cost advantages for domestic PC brand supply. |
| AI Edge Mini ITX Product Line Launch | Ryzen 8000-series APU integration targets localized machine learning inference workloads. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with motherboard ODM procurement directors, firmware engineering leads at Taiwanese design houses, gaming PC assembler sourcing managers in Chengdu and Hangzhou, and distributor category buyers at Newegg and Amazon marketplace operations. Secondary validation drew from TSMC foundry utilization disclosures, MIIT electromagnetic compatibility certification registries, London Metal Exchange copper futures data, and SEC 10-K filings from listed motherboard vendors. Bottom-up bill-of-materials costing and top-down channel shipment estimates were triangulated against chipset wafer allocation reports.
Segment-weighting across the projection horizon applied dimensional modeling by form factor (ATX, Mini ITX, Micro ATX, E-ATX), chipset tier (X570, B550, X470, A520), and intended use case (gaming, workstation, standard, compact). CAGRs were derived from installed base depreciation curves, socket transition velocity assumptions, and regional PC assembly growth differentials. Industry-specific forecast inputs included PCIe 5.0 signal integrity qualification timelines and DDR5 memory bin adoption rates by enthusiast builder segments.
The model holds under stable TSMC foundry allocation and copper concentrate supply continuity; deviation in seismic disruption at Hsinchu facilities or Chilean smelter output would shift volume and value trajectories. Forecasts embed assumptions regarding AMD socket longevity commitments and PCIe generational transition pacing. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
Mosfet Power Transistors Market
Semiconductor Devices
Global Power MOSFET Market
Semiconductor Devices
Single Electron Transistor Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
Gan Transistor Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Europe Microcontroller Market
Semiconductor Devices
India MLCC Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Pcie Switches Market
Semiconductor Devices
Japan Power Transistor Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market
Semiconductor Devices
Ram BOP Market
Semiconductor Devices
Semiconductor in Phones Market