
 Grain Roller Market | 2026-2036
Grain Roller Market Size, Share, and Industry Trends Forecast 2026-2036
Grain Roller Market Foresight
Skilled millwright and equipment technician availability is collapsing across grain processing hubs, forcing equipment buyers toward automated electric roller systems that reduce dependency on specialized maintenance labor. Bühler Holding AG leverages its Swiss engineering heritage to sustain premium positioning in high-capacity industrial installations. Satake Corporation anchors Asian supply chains through rice-specific roller expertise. AGCO Corporation competes in North American farm-gate sales with integrated grain handling portfolios.
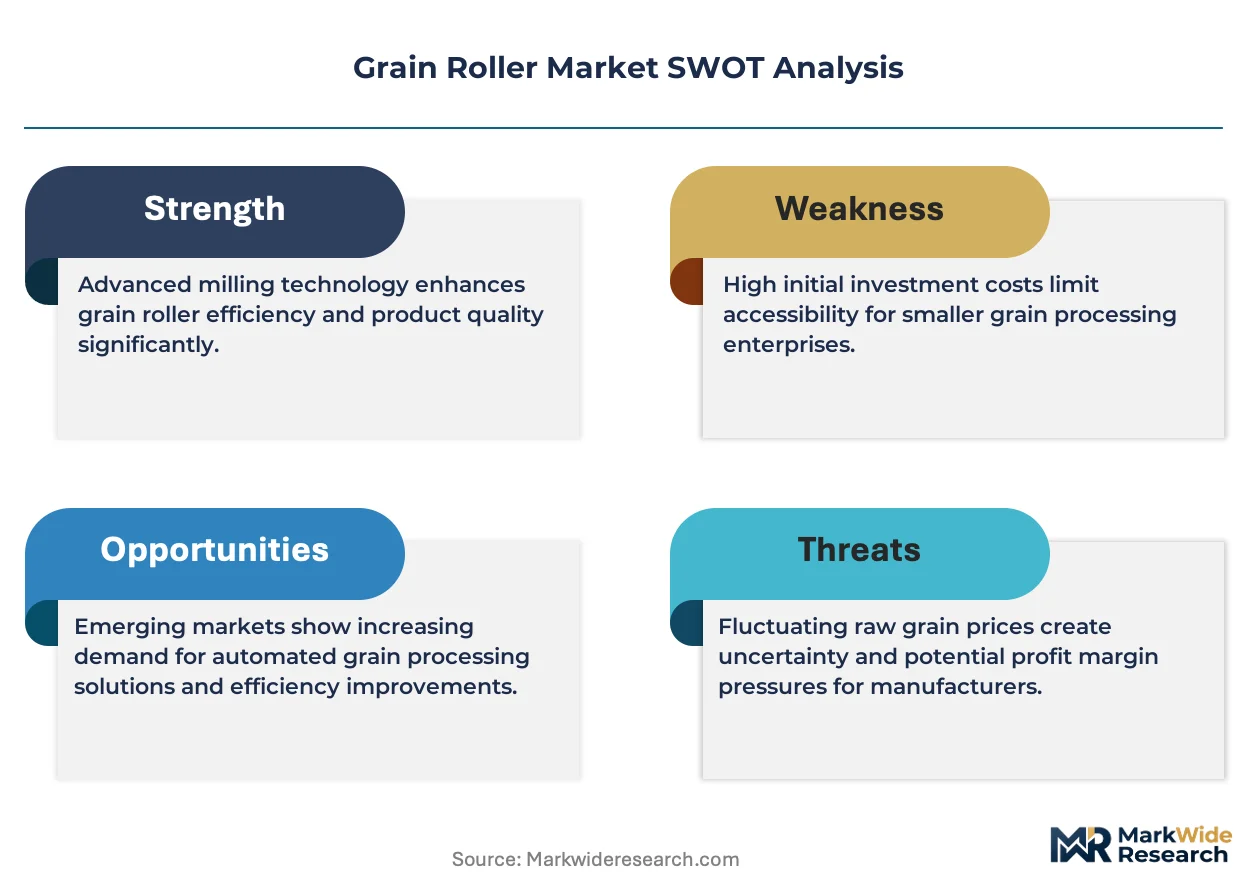
A grain roller is a cylindrical processing machine that crushes or flattens grain kernels between rotating drums, typically constructed from chilled cast iron or alloy steel with surface hardness ratings exceeding 500 BHN to withstand abrasive wear. The device reduces particle size to improve digestibility in animal feed or prepare malt for brewing. Electric rollers command the largest installed base due to throughput advantages in commercial feed mills, while portable units represent the fastest-growing form category as livestock producers adopt decentralized grain processing. Adjustable thickness features capture disproportionate margin pools because precise gap control correlates directly with feed conversion efficiency metrics that buyers track.
The EPA enforces dust emission limits under the Clean Air Act that compel grain roller manufacturers to integrate sealed bearing housings and dust collection interfaces. OSHA grain handling facility standards mandate explosion-proof electrical components in commercial installations, elevating compliance costs for equipment suppliers. The USDA's biofuel policy indirectly stimulates corn roller demand through ethanol production volume incentives. Stakeholders must monitor how evolving silica exposure thresholds and pending mechanical safeguarding rules reshape total cost of ownership calculations for end users.
Market Dynamics
Skilled millwright and equipment technician availability is collapsing across grain processing hubs, forcing equipment buyers toward automated electric roller systems that reduce dependency on specialized maintenance labor. This structural labor shortage is accelerating capital reallocation toward plug-and-play automation platforms.
Growth Catalysts
- US Midwest corn processing clusters:Commercial feed mills across Iowa, Illinois, and Nebraska are scaling grain processing capacity to meet livestock producer demand for optimized feed conversion ratios.
- EPA renewable fuel standards:Ethanol production volume incentives under the Clean Air Act indirectly stimulate corn roller demand through biofuel policy linkages.
- Adjustable gap control technology:Precision thickness mechanisms capture disproportionate margin pools because precise gap control correlates directly with feed conversion efficiency metrics that buyers track.
Market Restraints
- Chilled cast iron input volatility:Surface hardness ratings exceeding 500 BHN require specialized alloy compositions subject to foundry capacity constraints and raw material price swings.
- Swiss-German engineering concentration:Premium industrial installations depend on a narrow supplier base concentrated in Central European precision manufacturing corridors.
- OSHA explosion-proof mandates:Grain handling facility standards elevate compliance costs for electrical component sourcing in commercial installations.
Strategic Opportunities
- Portable unit decentralization:Livestock producers in pasture-heavy regions are adopting mobile grain processing to reduce transportation costs and improve feed freshness.
- Sealed bearing housing integration:Dust emission limits under the Clean Air Act create specification gaps for manufacturers who can engineer maintenance-free sealing systems.
- Rice-specific roller convergence:Asian supply chain expertise in specialty grain processing offers technology transfer potential for multi-crop processing platforms.
Industry Challenges
- Millwright apprenticeship pipeline collapse:Grain processing hubs face acute shortages of technicians capable of maintaining chilled cast iron roller surfaces and precision gap calibration.
- Legacy pneumatic system integration:Automated electric rollers must interface with existing grain elevator infrastructure originally designed for mechanical drive systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain Roller Market |
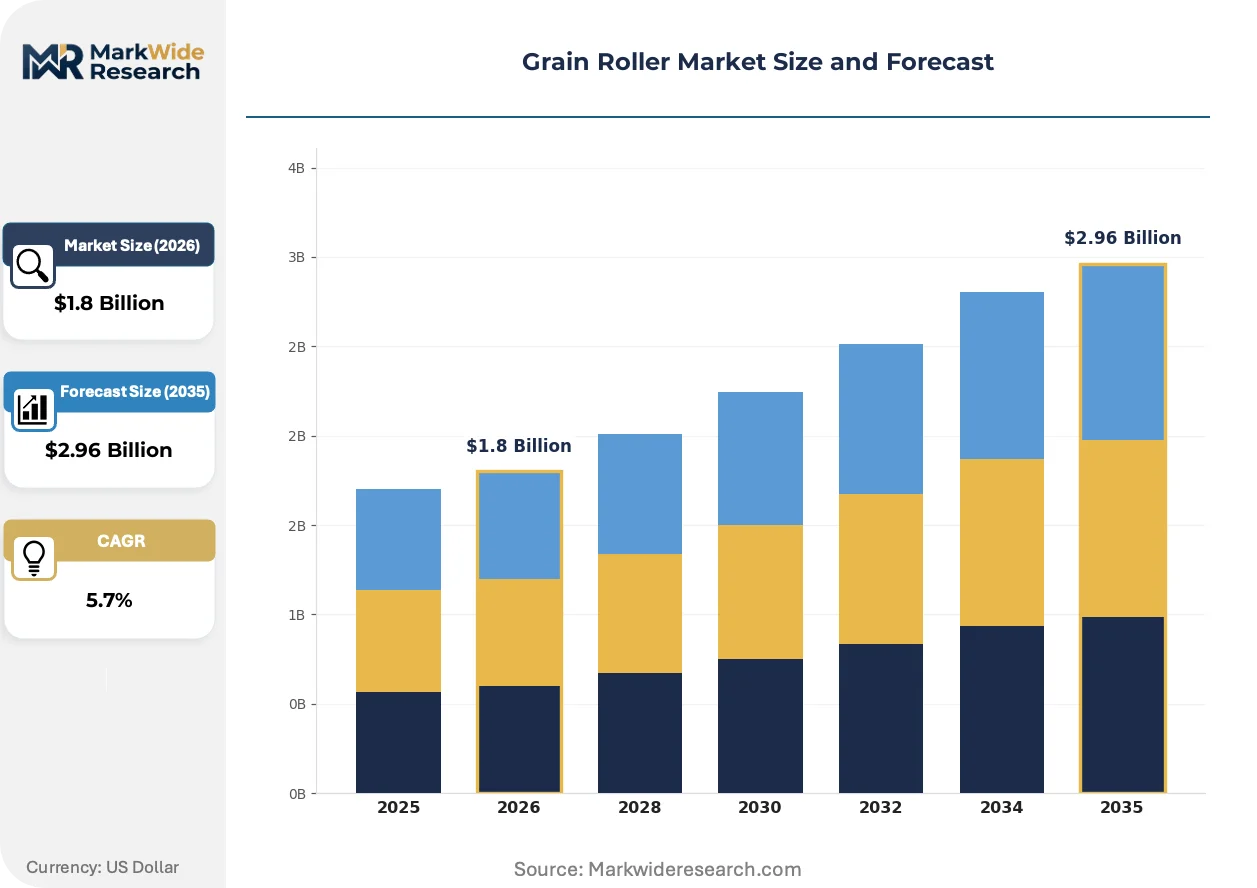
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Rollers, Electric Rollers, Commercial Rollers, Industrial Rollers End User: Farmers, Feed Mills, Grain Processors, Livestock Producers Form: Portable, Stationary, Mobile, Fixed Feature: Adjustable Thickness, High Capacity, Durability, User-Friendly |
| Companies Covered | Bühler Holding AG, Satake Corporation, Alapala Machine Industry & Trade Inc., Peterson Pacific Corporation, AGCO Corporation, Buhler Industries, Valmetal, Horning Manufacturing, Automatic Equipment Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain Roller Market Shifts & Advancements
Equipment specification is pivoting toward predictive maintenance architectures and multi-crop processing flexibility. Manufacturers are engineering modular platforms that accommodate shifting regulatory thresholds without full equipment replacement.
Sensor-embedded roller systems with real-time wear monitoring and automated gap adjustment are displacing manual calibration protocols in commercial feed mills. Large-scale operations in the US Corn Belt are adopting these platforms fastest, with mid-cap facilities following within eighteen-month lag cycles. The technology is displacing scheduled maintenance contracts and shifting vendor revenue toward per-ton processing fees.
EPA dust emission enforcement under the Clean Air Act is compelling sealed bearing housing redesigns across the installed base. Manufacturers must now engineer maintenance-free sealing systems that eliminate grease points while maintaining 500+ BHN surface integrity. Commercial installations in Nebraska and Iowa are retrofitting fastest, with equipment suppliers absorbing compliance engineering costs to defend account relationships.
Livestock producers are consolidating grain processing decisions at the enterprise level rather than delegating to individual facility managers. Large integrated protein companies are centralizing specification authority and negotiating master service agreements that bundle equipment, maintenance, and consumables. This concentration is most visible in the US Midwest, where Tyson Foods and JBS operating companies are standardizing roller specifications across feed mill networks.
Grain Roller Market Segmentation
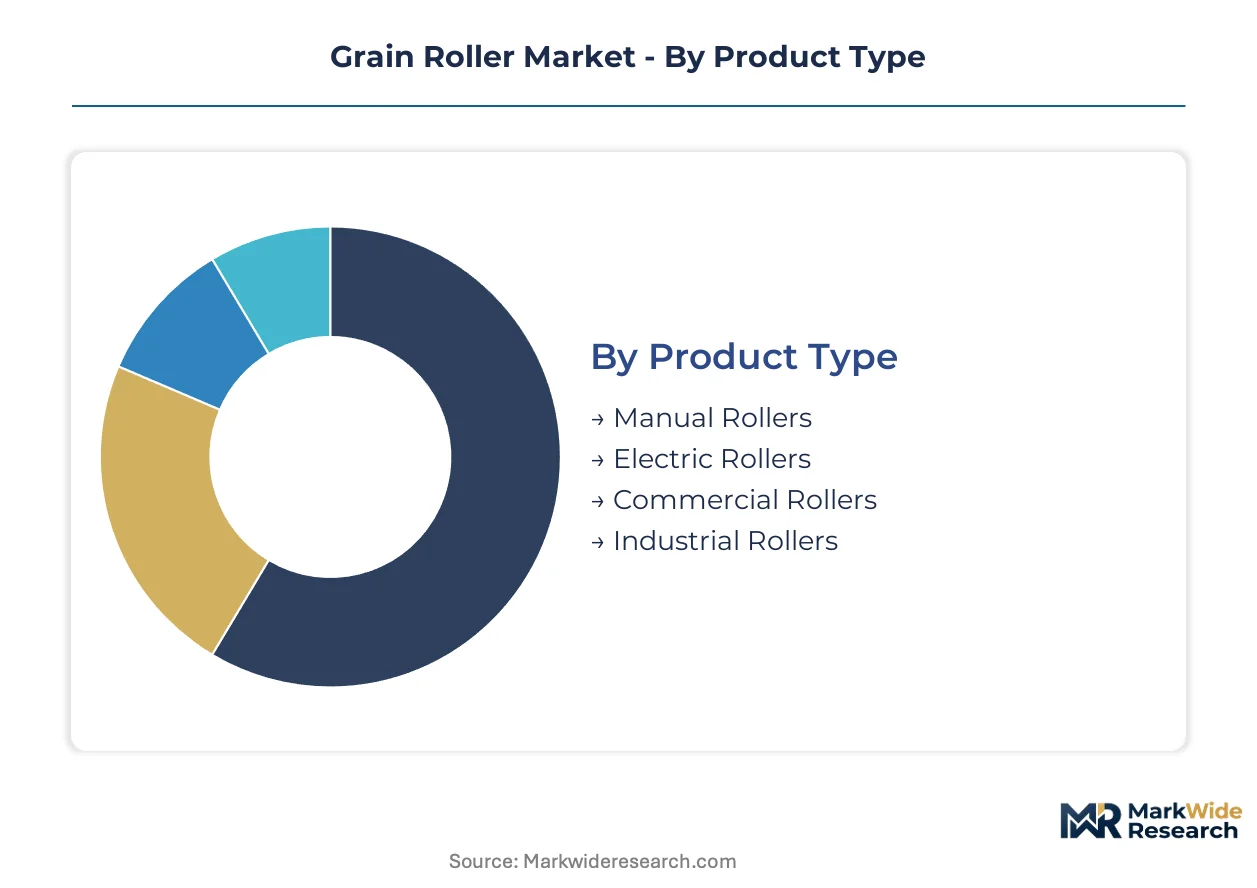
Grain roller segmentation reveals how equipment specifications align with distinct operational scales and regulatory environments. Buyers select across product type, end user, form, and feature dimensions based on throughput requirements, labor availability, and compliance obligations.
Product Type:
Margin pools concentrate in electric and industrial configurations where automation premiums and precision engineering command pricing power.
- Electric Rollers:These systems utilize variable-speed motors and programmable logic controllers to deliver consistent throughput with minimal operator intervention. Commercial feed mills across Iowa, Illinois, and Nebraska are standardizing on electric platforms to offset collapsing millwright availability. The dominant share belongs to Electric Rollers, while Industrial Rollers is closing the gap fastest.
- Industrial Rollers:High-capacity installations engineered for continuous operation with hardened alloy steel drums exceeding 500 BHN surface hardness. Large integrated protein companies in the US Midwest are consolidating procurement around industrial specifications to standardize maintenance protocols across feed mill networks.
- Manual Rollers:Hand-cranked or simple mechanical drive systems suited for low-volume farm-gate processing with minimal capital outlay.
- Commercial Rollers:Mid-tier electric systems balancing throughput and footprint for independent feed mills serving regional livestock markets.
Equipment buyers are migrating from manual toward electrified platforms as labor scarcity reshapes total cost of ownership calculations.
End User:
Procurement authority is shifting toward enterprise-level decision-making among the largest customer categories.
- Feed Mills:Centralized grain processing facilities purchasing high-capacity electric and industrial roller systems under master service agreements. Tyson Foods and JBS operating companies in the US Midwest are standardizing specifications across their networks to leverage volume purchasing and unified maintenance contracts. Feed Mills holds the dominant share, with Livestock Producers expanding most quickly.
- Livestock Producers:Pasture-based and confinement operations adopting portable electric rollers for decentralized grain processing to improve feed freshness and reduce transportation costs. Mobile units with adjustable gap control are gaining traction among cattle and swine operations in Nebraska and Kansas.
- Farmers:Small-scale grain producers utilizing manual or compact electric rollers for on-farm feed preparation and seed conditioning.
- Grain Processors:Specialty malt houses and oilseed processors requiring precision particle size control for brewing and extraction applications.
Enterprise consolidation among protein companies is compressing the farmer and independent processor share of equipment purchases.
Form:
Equipment mobility correlates directly with operational decentralization trends across livestock production systems.
- Portable:Self-contained electric roller units mounted on trailers or skids for relocation between feedlots and pasture operations. Livestock producers in the US Great Plains are adopting portable configurations to process grain at the point of consumption, reducing spoilage and trucking expenses. Portable captures the dominant share, with Mobile configurations gaining share fastest.
- Stationary:Permanent installations integrated into commercial feed mill infrastructure with pneumatic grain handling systems and dust collection interfaces.
- Mobile:Truck-mounted processing units serving custom grain rolling services for producers without capital investment in owned equipment.
- Fixed:Heavy industrial foundations for high-throughput continuous operation in large-scale corn and soybean processing clusters.
Decentralization of livestock production is elevating mobile and portable form factors relative to traditional fixed installations.
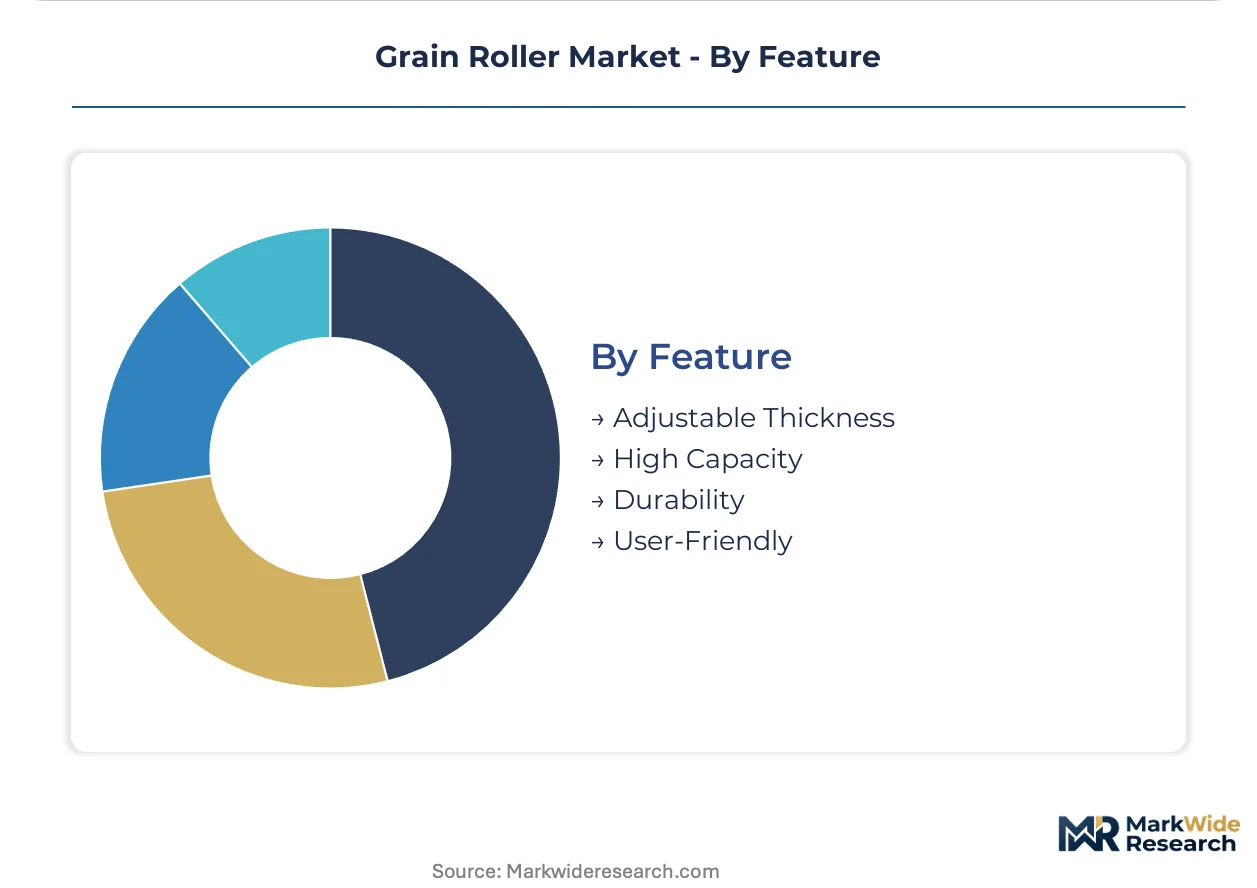
Feature:
Premium pricing attaches most strongly to precision control capabilities that translate directly into measurable production outcomes.
- Adjustable Thickness:Precision gap control mechanisms enabling real-time calibration of roller spacing to optimize feed conversion ratios. Commercial feed mills track particle size distribution as a direct input to livestock performance metrics, making adjustable thickness the most specified feature in new equipment procurement. Adjustable Thickness commands the dominant share, with High Capacity narrowing the gap fastest.
- High Capacity:Throughput-optimized drum geometries and drive systems for large-volume continuous processing operations.
- Durability:Hardened surface treatments and sealed bearing housings engineered for abrasive grain environments and extended maintenance intervals.
- User-Friendly:Simplified controls and automated calibration interfaces reducing dependency on specialized technician labor.
Precision control features are displacing raw throughput as the primary specification criterion in commercial purchasing decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA renewable fuel standards and OSHA grain handling mandates anchor the United States as the dominant geography, with regulatory spillover effects shaping equipment specifications across export markets. Commercial feed mills in the US Midwest are scaling capacity to meet livestock producer demand for optimized feed conversion ratios.
United States
Corn and soybean processing clusters in Iowa, Illinois, and Nebraska are driving electric roller procurement as livestock producers consolidate grain processing decisions at the enterprise level. EPA dust emission limits under the Clean Air Act compel manufacturers to integrate sealed bearing housings and dust collection interfaces. Tyson Foods and JBS operating companies in Nebraska are standardizing roller specifications across feed mill networks under master service agreements.
Germany
Precision engineering heritage from Central European manufacturing corridors sustains premium industrial installation demand among malt houses and specialty grain processors. REACH chemical safety regulations and CE marking requirements elevate compliance engineering costs for equipment suppliers serving the brewing sector. Bavarian malt processors are retrofitting existing facilities with automated gap control systems to meet traceability requirements under EU food safety frameworks.
Brazil
Soybean and corn processing expansion in Mato Grosso and Paraná is stimulating demand for high-capacity continuous operation rollers. ANVISA food safety regulations and the country's agricultural ministry equipment certification standards shape import specifications for foreign suppliers. São Paulo-based integrated protein companies are centralizing procurement authority and negotiating volume purchasing agreements for feed mill networks.
China
Domestic grain processing capacity expansion in Heilongjiang and Jilin provinces is driving demand for multi-crop processing platforms capable of handling corn, soybean, and rice varietals. GB standards for agricultural machinery safety and MIIT equipment efficiency mandates influence domestic manufacturer design priorities. Yangtze River Delta feed compounders are adopting sensor-embedded roller systems with real-time wear monitoring to reduce maintenance labor dependency.
Australia
Wheat and barley processing for export markets and domestic livestock feed is concentrating equipment demand in New South Wales and Victoria. The country's national agricultural equipment safety regulator and state-level workplace health frameworks mandate explosion-proof electrical components in commercial grain handling facilities. Grain processors in the Murray-Darling Basin are retrofitting portable electric roller units to reduce transportation costs between harvest sites and feedlots.
Grain Roller Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around automation-capable suppliers who can deliver predictive maintenance architectures. The competitive terrain fragments between premium Swiss-German engineering houses, Asian rice-specialist fabricators, and North American farm-gate equipment portfolios. Strategic archetypes include precision engineering specialists, multi-crop platform generalists, and regional integration champions. Dominant competitive moves center on technology licensing for sensor-embedded systems and backward integration into hardened alloy steel drum foundry capacity.
Within the precision engineering tier, Bühler Holding AG exemplifies the integrated leader archetype through its Swiss engineering heritage and high-capacity industrial installation focus. Satake Corporation occupies a position representing Asian rice-specific roller expertise and supply chain anchoring. AGCO Corporation sits within the North American farm-gate sales vector with integrated grain handling portfolios. These three companies represent distinct strategic positions rather than exhaustive market coverage, with additional competition emerging from regional specialists and emerging automation-focused entrants.
| Leading Market Players |
|---|
| Bühler Holding AG |
| Satake Corporation |
| Alapala Machine Industry & Trade Inc. |
| Peterson Pacific Corporation |
| AGCO Corporation |
| Buhler Industries |
| Valmetal |
| Horning Manufacturing |
| Automatic Equipment Manufacturing |
| Others |
Supply & Pricing Matrix
OSHA grain handling facility standards and EPA dust emission mandates under the Clean Air Act gate both supplier qualification and price differentiation simultaneously. Equipment buyers face tiered cost structures where explosion-proof electrical certification and sealed bearing housing compliance separate premium Swiss-German engineering from standard commercial offerings.
Pricing Analysis
Long-term offtake contracts dominate procurement between large integrated protein companies and precision engineering suppliers, while spot purchases persist among independent feed mills and livestock producers. Three-tier pricing structure across premium automation platforms, standard electric configurations, and economy manual units reflects certification grade and after-sales bundling intensity. Cost compression in mid-tier commercial rollers is intensifying because foundry capacity constraints for 500+ BHN alloy steel drums elevate input costs. Independent feed mills exhibit highest price sensitivity, whereas Tyson Foods and JBS operating companies prioritize total cost of ownership over unit price.
Supply Chain Analysis
Germany and Switzerland anchor precision manufacturing for high-capacity industrial rollers, while China and India feed foundry capacity for hardened alloy components. Chilled cast iron formulations, sealed bearing assemblies, and programmable logic controllers constitute critical input dependencies. Single-source vulnerability concentrates in Central European engineering corridors where Bühler Holding AG and specialist fabricators maintain captive process knowledge. Distribution runs through OEM-direct channels for large installations and agricultural equipment dealers for farm-gate sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-embedded predictive maintenance architectures are disrupting traditional scheduled service contracts across the grain processing sector. EPA enforcement patterns on dust emission limits will accelerate equipment replacement cycles beyond baseline demand.
For Market Incumbents: Shield installed base relationships by absorbing compliance engineering costs for sealed bearing retrofits in Nebraska and Iowa feed mill networks. Backward integration into hardened alloy steel drum foundry capacity secures margin control against chilled cast iron input volatility. Automation platform standardization across customer networks raises switching costs for large protein company accounts.
For New Entrants and Emerging Players: Lead with portable electric roller configurations targeting pasture-heavy livestock operations in Kansas and the Dakotas where transportation cost reduction drives purchasing decisions. Custom grain rolling services offer asset-light market entry before capital deployment into owned equipment manufacturing. Sensor-as-a-service revenue models bypass upfront capital barriers among mid-cap feed mills.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable and mobile equipment categories as modular platform designs reduce per-unit engineering overhead. Acquisition targets should display multi-crop processing flexibility and established relationships with USDA ethanol policy beneficiaries. Watch for EPA silica exposure threshold revisions as signal for accelerated replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Sealed Bearing Housing Integration | OSHA compliance mandates in Nebraska and Iowa retrofit programs defend account relationships. |
| Sensor-Embedded Platform Launch | Real-time wear monitoring displaces scheduled maintenance contracts with per-ton processing fees. |
| Multi-Crop Processing Flexibility | Rice-specific roller expertise from Asian supply chains enables corn-soybean-rice platform convergence. |
| Portable Unit Geographic Expansion | Mobile configurations reduce transportation costs for pasture-based livestock producers in the Great Plains. |
| Backward Integration into Foundry Capacity | Captive supply of 500+ BHN alloy steel drums insulates margin from raw material price swings. |
Research Methodology
A spread of perspectives from feed mill maintenance directors, grain elevator operations managers, agricultural equipment procurement leads, and aftermarket service heads converged on the working assumptions. Primary fieldwork combined with secondary validation from USDA biofuel policy documentation, EPA Clean Air Act enforcement records, OSHA grain handling facility standards, and SEC filings from listed agricultural equipment manufacturers. Bottom-up equipment unit economics and top-down addressable market sizing underwent cross-verification.
Segmentation dimensions modeled include product type automation level, end-user procurement authority tier, equipment mobility configuration, and precision control feature intensity across the projection horizon. CAGRs derived from historical replacement cycle analysis, regulatory compliance-driven acceleration factors, and livestock producer decentralization trends. Forecast inputs incorporate millwright labor availability indices and ethanol production volume policy linkages.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement intensity or abrupt chilled cast iron supply disruption would require recalibration. Forecasts reflect documented assumptions on technology adoption lag cycles and enterprise procurement consolidation patterns. Recalibration cycles align with material shifts in renewable fuel standards and grain handling safety mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
North America Rice Market
Grains
China Rice Market
Grains
00 Flour Market
Grains
Mexico Rice Market
Grains
United States Gluten-Free Oats Market
Grains
Europe Wheat Protein Market
Grains
Brown Rice Market
Grains
Global Flour Market
Grains
Mesquite Flour Market
Grains
Italy Rice Market
Grains
Heritage Grain Market
Grains
Argentina Maize Market
Grains
Cameroon Grains Market
Grains
GMO Corn Market
Grains
Black Gram Market
Grains
Corn Gluten Feed Market