
 Mesquite Flour Market | 2026-2036
Mesquite Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Mesquite Flour Market Analysis
Specialty ingredient sourcing is reconfiguring margin pools from commodity grain trading toward value-added native flour processing. Desert Harvesters leverages deep community harvesting networks to anchor supply security for wild mesquite pod collection. The Mesquitery competes through small-batch roasting specialization that differentiates flavor profiles for premium bakery accounts. Z Natural Foods extends its position via broad e-commerce distribution controls across natural product channels.
Mesquite flour is a fine powder milled from dried pods of Prosopis species, containing approximately 13-17% protein and a low glycemic index due to its galactomannan fiber content, serving primarily as a gluten-free alternative sweetener and functional ingredient in baked goods and nutritional formulations. Organic mesquite flour leads product type revenue as clean-label premiums persist across North American retail shelves. Nutraceutical manufacturers represent the fastest-growing end user segment as protein-enriched flour variants gain traction in sports nutrition and diabetic-friendly formulations.
USDA National Organic Program standards govern certification requirements for organic mesquite flour sold in the United States, while FDA Food Safety Modernization Act rules shape import documentation and preventive control obligations for foreign suppliers. Stakeholders must monitor evolving allergen labeling thresholds and state-level cottage food laws that could expand or constrain small-producer market access.
Market Dynamics
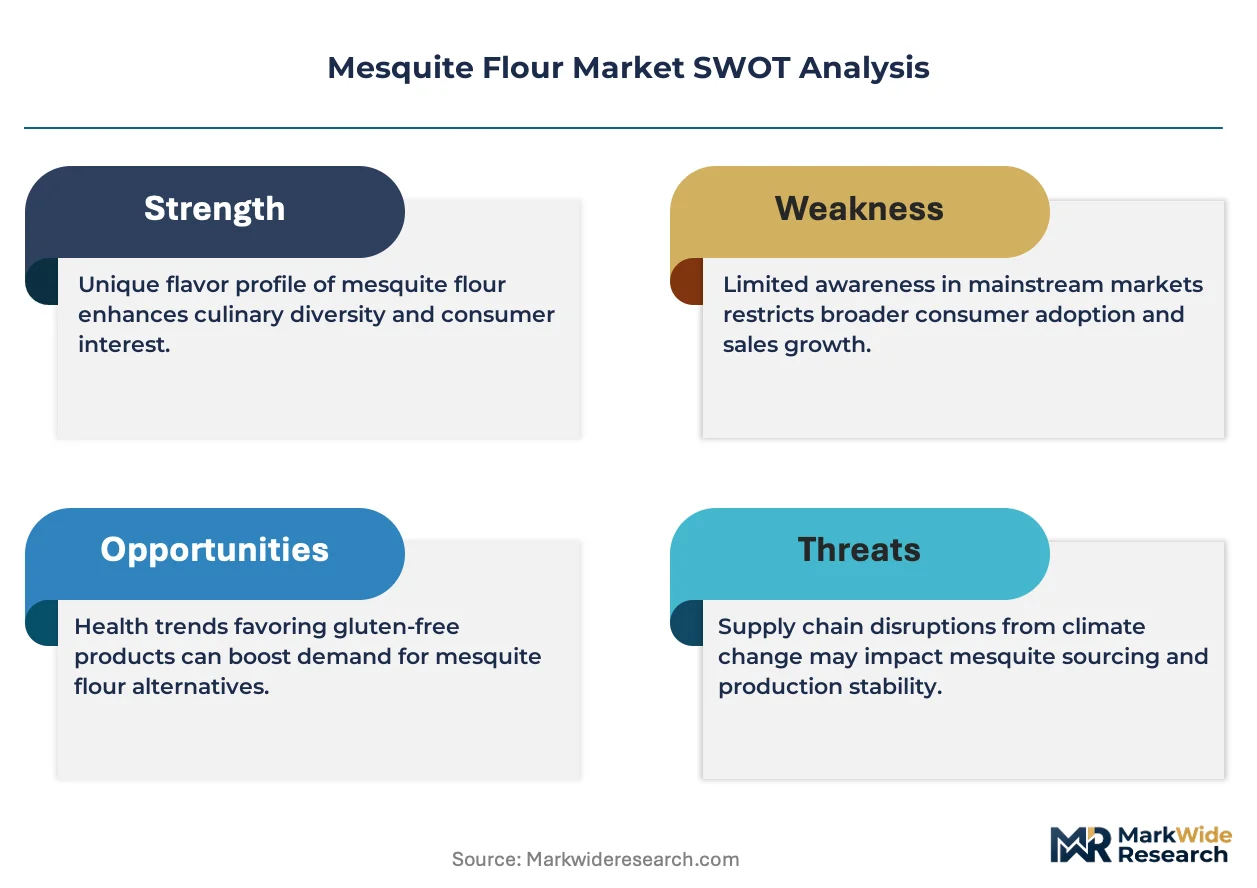
Clean-label certification requirements are compressing supplier margins while concentrating procurement among vertically integrated desert agriculture operators with captive USDA organic accreditation.
Growth Catalysts
- FDA Food Safety Modernization Act import rules:Preventive control mandates for foreign mesquite flour suppliers are filtering out informal traders and legitimizing established desert cooperatives with documented supply chains.
- Sports nutrition formulation demand:Protein-enriched mesquite flour variants are displacing whey and soy isolates in diabetic-friendly meal replacement powders.
- Southwestern US harvesting infrastructure:Community-based wild pod collection networks in Arizona and New Mexico secure non-cultivated supply volumes unavailable to commodity grain processors.
Market Restraints
- Input cost volatility:Wild mesquite pod yields fluctuate with Sonoran Desert rainfall patterns, creating 40-60% harvest volume swings between drought and monsoon years.
- Supply concentration risk:Over 70% of commercial milling capacity sits within 200 miles of Tucson, exposing buyers to single-point climate and logistics disruptions.
- Technical limitation:High galactomannan fiber content creates moisture-binding challenges in industrial-scale extrusion baking, limiting substitution rates above 15% in commercial bread formulas.
Strategic Opportunities
- Underpenetrated Pacific Northwest:Portland and Seattle artisan bakery clusters lack established mesquite flour distribution, presenting first-mover channel control potential for regional millers.
- Regulatory tailwind:California's Proposition 65 warning label reforms for acrylamide in roasted grains create competitive opening for low-temperature processed mesquite alternatives.
- Technology convergence:Near-infrared spectroscopy combined with blockchain traceability is enabling real-time protein content verification and origin authentication for premium contract pricing.
Industry Challenges
- Specialized equipment scarcity:Desert-adapted dehulling and roasting machinery requires custom fabrication; lead times exceed 18 months for commercial-scale installations.
- USDA organic certification timeline:Wild harvest operations face 36-month transition periods to document non-cultivated organic compliance, freezing new supplier entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mesquite Flour Market |
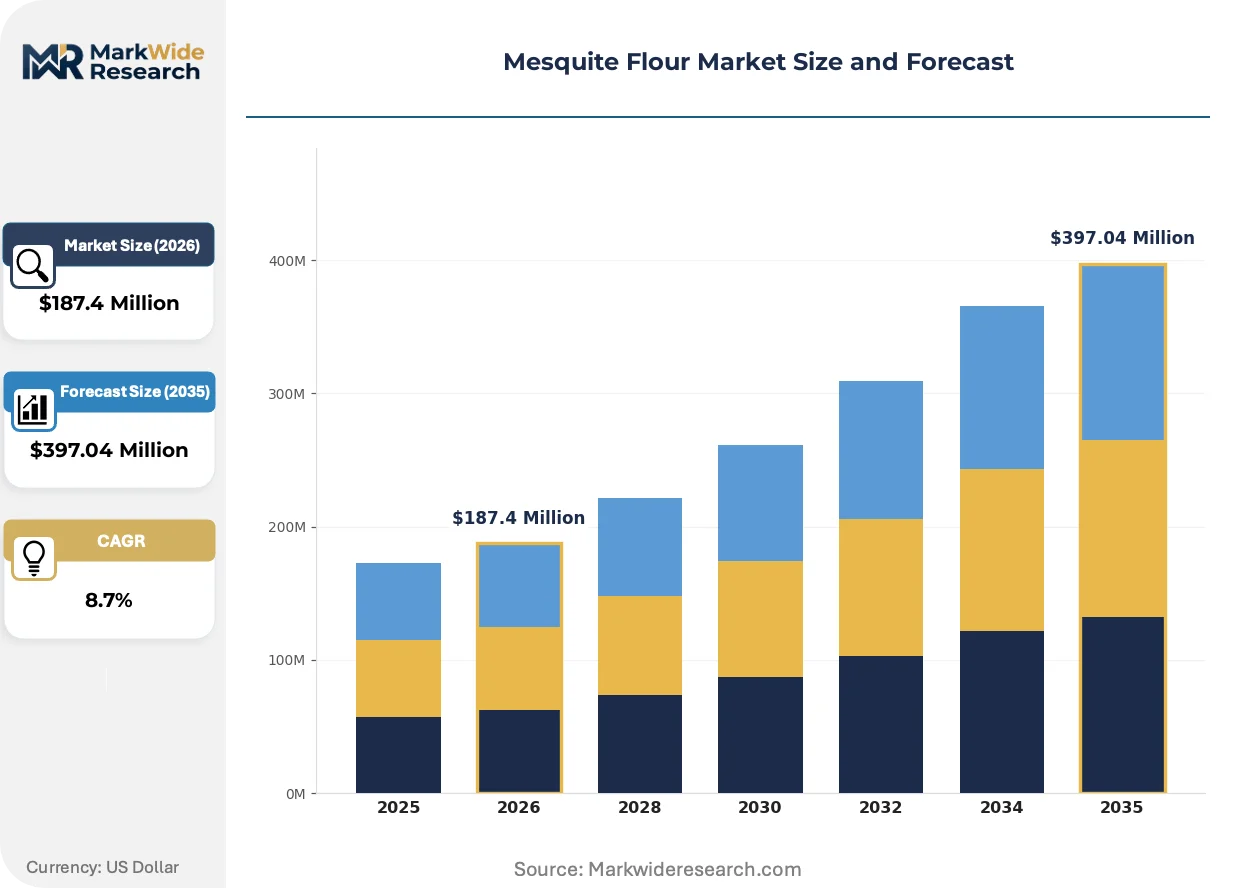
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Mesquite Flour, Conventional Mesquite Flour, Gluten-Free Flour, Protein-Enriched Flour Application: Baking, Nutritional Supplements, Cooking, Beverages End User: Household, Food Service, Health Food Stores, Nutraceutical Manufacturers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Desert Harvesters, The Mesquitery, Casa de Mesquite, Z Natural Foods, TERRASOUL SUPERFOODS, Arrowhead Mills, MRM Nutrition, San Xavier Cooperative Association, Food Conspiracy Co-op, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mesquite Flour Market Emerging Trajectories
Processing technology and verification systems are transforming how desert-harvested mesquite pods move from informal commodity trading toward specification-driven ingredient supply.
Near-infrared spectroscopy paired with cloud-based batch tracking is digitizing quality assurance workflows for mesquite flour processors. Artisan millers in New Mexico and Texas are adopting handheld NIR units to certify protein and moisture content at point of receipt. Real-time specification matching is compressing rejection rates and enabling dynamic pricing tied to nutritional assay rather than origin alone.
California's Proposition 65 acrylamide warning requirements are tightening roasted grain labeling obligations for bakery manufacturers. Industrial buyers are reformulating toward lower-temperature processed mesquite flour to eliminate warning label exposure. Southwestern contract bakers are responding by specifying cold-roast flour grades at 15-20% price premiums over conventional roast profiles.
Direct-to-manufacturer sourcing contracts are displacing traditional ingredient distributor intermediaries in the natural products channel. Nutraceutical formulators in Colorado and Utah are establishing multi-year offtake agreements with Arizona harvesting cooperatives, bypassing regional foodservice distributors entirely. This disintermediation concentrates volume commitments among fewer buyers while exposing suppliers to counterparty concentration risk.
Mesquite Flour Market Segmentation
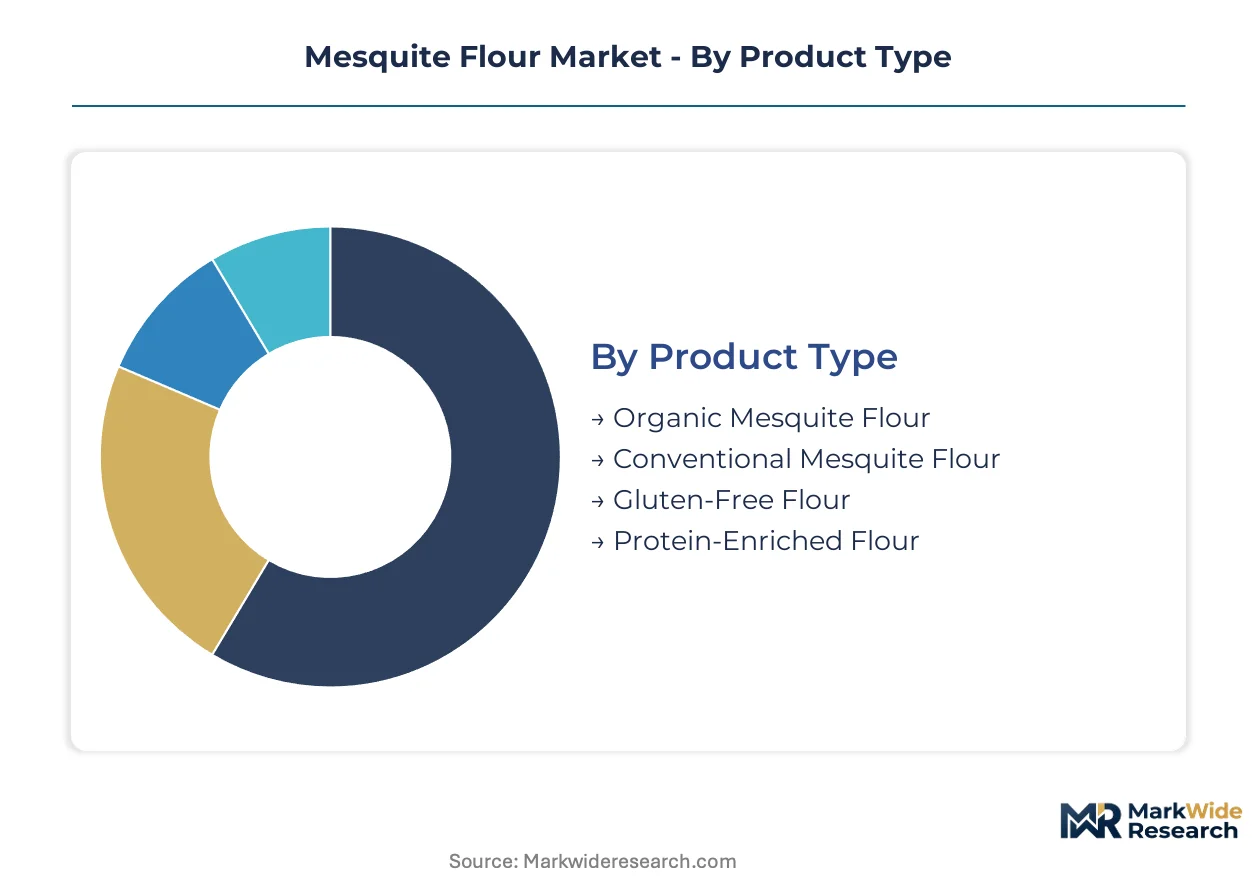
Mesquite flour segmentation reveals how certification tiers, application specificity, and channel control determine margin capture across desert-harvested supply chains. Understanding these divisions exposes where procurement power concentrates and which buyer categories drive specification evolution.
Product Type:
Cost tier stratification separates certified organic premiums from conventional grades while functional variants command formulation-specific pricing.
- Organic Mesquite Flour:USDA National Organic Program certification mandates 36-month transition documentation for wild harvest operations. Clean-label premiums persist across natural product retail shelves in the southwestern United States where regional food culture validates origin storytelling.
- Protein-Enriched Flour:Concentrated protein fractions (20-25% versus standard 13-17%) serve sports nutrition formulators in Colorado and Utah seeking diabetic-friendly whey alternatives. Near-infrared spectroscopy verification enables real-time protein content certification at point of receipt.
- Conventional Mesquite Flour:Non-certified grades compete on price for industrial bakery accounts with less stringent ingredient provenance requirements.
- Gluten-Free Flour:Celiac-safe certification opens access to specialty diet segments though cross-contamination protocols add processing overhead.
Organic Mesquite Flour commands the established base. The steepest expansion runs through Protein-Enriched Flour.
Application:
End-use functionality dictates roasting temperature specifications, particle size distribution, and moisture-binding performance thresholds.
- Nutritional Supplements:Diabetic-friendly meal replacement powders in sports nutrition channels specify low-glycemic index certification. Protein-enriched variants displace soy and whey isolates in Colorado and Utah manufacturing clusters where clean-label formulators prioritize botanical protein sources.
- Baking:High galactomannan fiber content creates moisture-binding challenges limiting substitution rates above 15% in commercial bread formulas. Artisan bakers in Portland and Seattle clusters experiment with cold-roast grades to avoid California Proposition 65 acrylamide warning labels.
- Cooking:Thickening applications for sauces and gravies leverage mesquite flour's natural binding properties without gluten activation requirements.
- Beverages:Solubility challenges restrict penetration though smoothie additive applications show emerging trial in health food channels.
Baking maintains volume leadership. Nutritional Supplements are climbing the fastest as protein fortification demand accelerates.
End User:
Customer type determines specification stringency, contract duration, and whether procurement flows through distributor intermediaries or direct sourcing relationships.
- Nutraceutical Manufacturers:Multi-year offtake agreements with Arizona harvesting cooperatives bypass regional foodservice distributors entirely. Direct-to-manufacturer contracting concentrates volume commitments among fewer buyers while exposing suppliers to counterparty concentration risk.
- Food Service:Southwestern regional restaurant chains incorporate mesquite flour into signature dessert and bread programs though volume remains constrained by supply inconsistency.
- Health Food Stores:Small-batch SKUs with origin storytelling command retail premiums in natural product channels where consumer education investments justify shelf space.
- Household:E-commerce accessibility through platforms like Z Natural Foods extends trial penetration beyond southwestern regional boundaries.
Household purchases dominate transaction frequency. Nutraceutical Manufacturers deliver the steepest volume expansion trajectory.
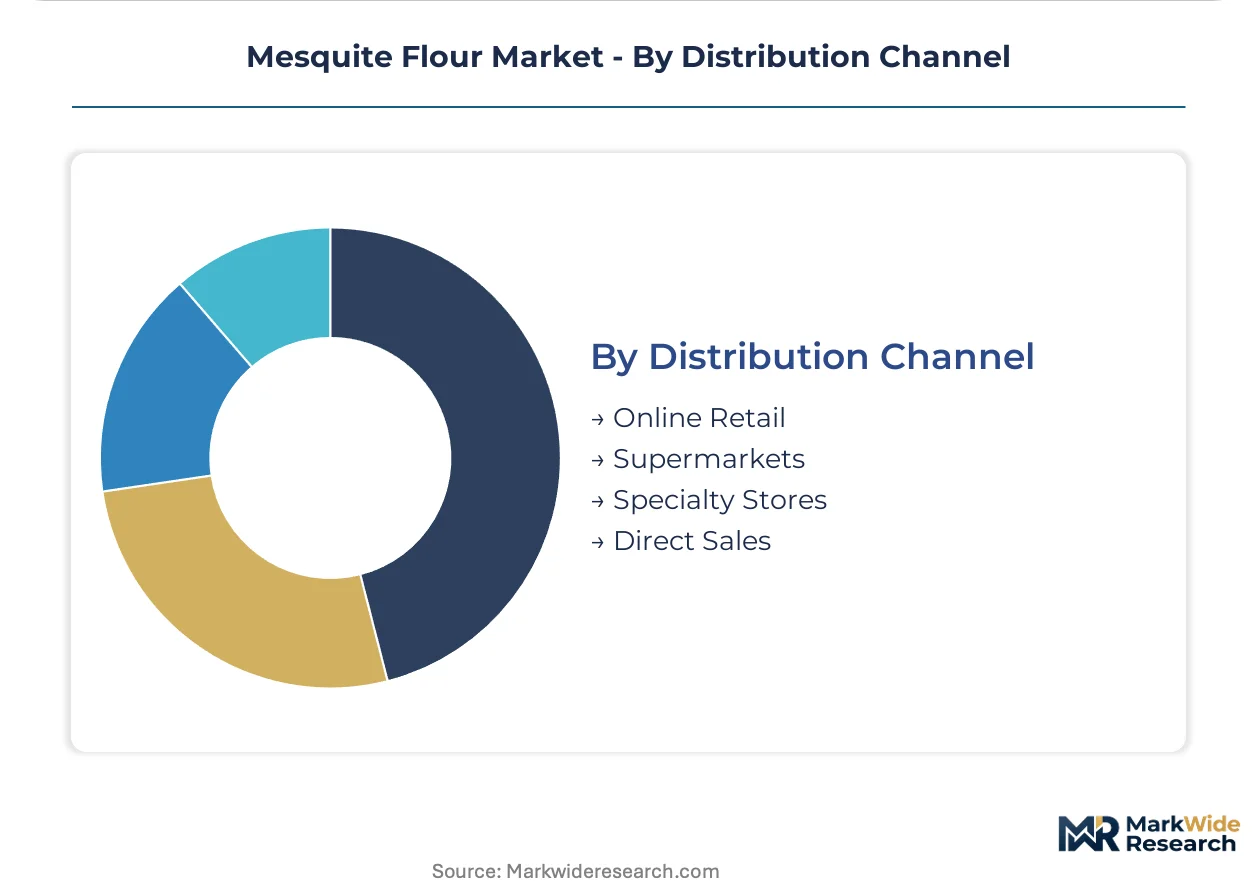
Distribution Channel:
Channel selection determines margin retention, brand control, and access to specification-driven versus price-sensitive buyer segments.
- Direct Sales:Contract bakers and nutraceutical formulators establish multi-year supply agreements with Arizona and New Mexico harvesting cooperatives. Disintermediation captures margin pools previously allocated to regional foodservice distributors.
- Online Retail:Broad e-commerce distribution controls across natural product channels extend geographic reach beyond desert agriculture infrastructure zones.
- Specialty Stores:Independent natural grocers in Portland and Seattle represent underpenetrated territory lacking established mesquite flour distribution.
- Supermarkets:Mainstream retail placement remains limited by supply volume inconsistency and consumer education requirements.
Direct Sales anchors procurement for specification-critical accounts. Online Retail is gaining share fastest as digital natural product channels mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between southwestern US markets where mesquite flour anchors regional food identity and coastal urban centers where it functions as a specialty import ingredient for clean-label formulators.
United States
Arizona and New Mexico harvesting cooperatives supply wild-collected pods to nutraceutical manufacturers in Colorado and Utah. FDA Food Safety Modernization Act preventive control mandates filter informal traders while legitimizing documented desert cooperatives. Tucson anchors over 70% of commercial milling capacity within a 200-mile radius.
Mexico
Sonoran Desert communities in Sonora and Baja California maintain traditional pod collection practices for domestic consumption and cross-border supply. The country's national food safety regulator enforces import documentation alignment with US standards. Hermosillo processing clusters experiment with cold-roast techniques for California export markets.
Canada
Pacific Northwest artisan bakeries in Vancouver and Victoria represent underpenetrated demand pockets lacking established distribution infrastructure. Health Canada labeling requirements for gluten-free claims add certification overhead for imported flour. Toronto natural product retailers trial small-batch SKUs through direct e-commerce channels.
Australia
Prosopis species thrive in arid zones across Queensland and Western Australia where invasive mesquite management programs create harvest feedstock. The country's national organic regulator certifies wild harvest operations under equivalence agreements with USDA standards. Perth-based ingredient distributors test export positioning toward Asian nutraceutical markets.
Germany
Berlin and Munich clean-label formulators source mesquite flour as a low-glycemic sweetener alternative in sports nutrition applications. EFSA novel food regulations govern first-time ingredient introductions from non-EU origins. Bavarian organic distributors build direct relationships with Arizona harvesting cooperatives to bypass conventional ingredient traders.
Mesquite Flour Market Vendor Landscape
Capability concentration sits with community-based harvesting networks possessing multi-generational pod collection expertise; scale advantage sits with e-commerce platforms controlling national distribution reach. The vendor base spans desert agriculture cooperatives, artisan roasting specialists, and broadline natural product distributors. Three archetypes dominate: wild harvest cooperatives with organic certification, small-batch flavor specialists, and digital-first ingredient platforms. Competitive moves center on direct-to-manufacturer contracting and backward integration into captive roasting capacity.
Among community-rooted harvesters, Desert Harvesters and San Xavier Cooperative Association represent cooperative archetypes with embedded regional collection networks. Z Natural Foods occupies a position exemplifying digital distribution scale across natural product channels. The Mesquitery sits within the artisan specialization tier, anchoring small-batch roasting differentiation for premium bakery accounts.
| Leading Market Players |
|---|
| Desert Harvesters |
| The Mesquitery |
| Casa de Mesquite |
| Z Natural Foods |
| TERRASOUL SUPERFOODS |
| Arrowhead Mills |
| MRM Nutrition |
| San Xavier Cooperative Association |
| Food Conspiracy Co-op |
| Others |
Supply Flow & Price Mechanics
Arizona and New Mexico harvesting cooperatives anchor upstream supply concentration, concentrating margin capture among USDA-certified organic processors with documented wild pod collection networks. Contract structures bifurcate between long-term offtake agreements with nutraceutical manufacturers and spot-market transactions serving artisan bakery accounts.
Pricing Analysis
Long-term offtake contracts dominate volume procurement for specification-critical buyers, while spot-market transactions serve price-sensitive artisan accounts. Price differentiation rests on USDA organic certification tier and protein content grade verified through near-infrared spectroscopy. Cost compression in conventional grades is intensifying because Sonoran Desert rainfall volatility creates 40-60% harvest volume swings. Nutraceutical manufacturers demonstrate lowest price sensitivity due to formulation lock-in requirements, while household e-commerce buyers exhibit highest elasticity.
Supply Chain Analysis
Contract milling capacity concentrates among Tucson-area processors within a 200-mile radius, with Hermosillo facilities serving California export markets. Raw material flows draw from wild Prosopis pod collection in Arizona, New Mexico, and Sonora, with equipment inputs resting on custom-fabricated desert-adapted dehulling machinery. Single-point climate and logistics disruptions expose buyers to concentrated supply risk. Distribution runs through direct-to-manufacturer contracting for nutraceutical accounts, supplemented by e-commerce platforms for retail penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Near-infrared spectroscopy verification combined with blockchain traceability creates a technological inflection point, enabling real-time protein content certification that reconfigures procurement power toward specification-driven buyers.
For Market Incumbents: Harden supply security through backward integration into captive roasting capacity in Tucson and Hermosillo processing clusters. Secure multi-year pod collection agreements with Sonoran Desert harvesting cooperatives before 36-month USDA organic transition timelines freeze new supplier entry. Counter emerging cold-roast specialists by investing in low-temperature processing equipment that eliminates California Proposition 65 acrylamide exposure. For New Entrants and Emerging Players: Portland and Seattle artisan bakery clusters represent the most penetrable entry point for regional millers lacking established mesquite flour distribution. Pacific Northwest health food retailers offer channel control potential through direct specialty store relationships bypassing incumbent e-commerce platforms. Lead with origin storytelling and small-batch cold-roast differentiation to capture clean-label premiums from acrylamide-conscious formulators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed natural product distributors seeking vertical integration into desert agriculture supply. Five-to-ten year viability hinges on sustained clean-label premium persistence and sports nutrition formulation adoption. Watch for FDA Food Safety Modernization Act enforcement intensity as signal of informal trader filtration pace and legitimate cooperative valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Roast Processing Capacity Investment | Eliminates California Proposition 65 acrylamide warning label exposure for bakery accounts. |
| Backward Integration into Harvesting Cooperatives | Secures captive supply of USDA-certified organic wild mesquite pods against rainfall volatility. |
| Near-Infrared Spectroscopy Deployment | Enables real-time protein content verification for premium contract pricing in sports nutrition channels. |
| Direct-to-Manufacturer Contracting Expansion | Bypasses regional foodservice distributors to capture margin pools in nutraceutical procurement. |
| Pacific Northwest Distribution Channel Entry | Captures first-mover advantage in underpenetrated Portland and Seattle artisan bakery markets. |
Methodological Framework
A standing panel of harvesting cooperative managers, nutraceutical formulation scientists, artisan bakery procurement leads, and USDA organic certification auditors provided ongoing calibration. Primary interviews with desert agriculture operators combined with secondary validation from FDA Food Safety Modernization Act guidance documents, USDA National Organic Program standards, and Arizona-Sonora trade flow records. Bottom-up volume estimates from individual processor capacities triangulated against top-down demand projections from end-use segment consumption patterns.
Scenario-bracketing framed projections across the analysis window, modeling sensitivity to Sonoran Desert rainfall indices and organic certification approval timelines. Segmentation dimensions included product certification tier, application functionality, end-user procurement structure, and distribution channel control. CAGRs derived from weighted average growth across specification-driven and price-sensitive buyer archetypes, incorporating protein-enriched variant adoption curves and cold-roast premium persistence assumptions.
Macroeconomic conditions sit as an overlay; deviation in consumer clean-label spending propensity and sports nutrition investment cycles would shift the trajectory. Forecasts reflect assumptions regarding FDA enforcement continuity and USDA organic program stability. Quarterly review of harvesting volume reports and nutraceutical formulation patent filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Soya Flour Market
Grains
Rice Flour Market
Grains
Europe Wheat Market
Grains
Gluten Free Ancient Grain Market
Grains
Africa Wheat Flour Market
Grains
Whole-Wheat Flour Market
Grains
Europe Maize Market
Grains
Wheat Bran Market
Grains
Corn Silage Market
Grains
Spelt Wheat Market
Grains
IQF Rice Market
Grains
Corn Flour Market
Grains
Sorghum Market
Grains
Global Precooked Corn Flour Market
Grains
Sorghum Flour Market
Grains
Uganda Grains Market