
 GMO Corn Market | 2026-2036
GMO Corn Market Size, Share, and Industry Trends Forecast 2026-2036
GMO Corn Market Analytics
The capital-intensity divergence between integrated seed-chemistry conglomerates and regional breeding specialists is reorganizing competitive tiers in GMO corn. Bayer CropScience leverages its combined germplasm and crop protection pipeline to sustain pricing power across North American and Latin American markets. Corteva Agriscience anchors its position through proprietary CRISPR-edited trait stacks that differentiate its portfolio from first-generation transgenic offerings. Syngenta competes by controlling distribution networks in emerging production zones where farmer education on stacked-trait hybrids remains incomplete.
Genetically modified corn comprises maize varieties engineered with inserted recombinant DNA sequences to express herbicide tolerance, insect resistance, or modified oil and starch profiles, with commercial cultivars typically containing one to eight stacked transgenic events regulated by event-specific molecular markers. The primary commercial purpose centers on reducing yield losses to lepidopteran pests and broadleaf weeds while enabling conservation tillage practices that lower fuel and labor inputs. Seeds dominate value capture within product type segmentation due to recurring annual purchases and intellectual property premiums embedded in hybrid genetics, while biofuel application channels represent the fastest-expanding demand segment as renewable fuel mandates in multiple jurisdictions expand corn ethanol blending requirements. Agricultural production remains the mature anchor application, though margin pools are shifting toward specialized high-lysine and high-oil varieties destined for food processing and animal nutrition.
The EPA regulates insect-resistant corn through mandatory refuge requirements that preserve susceptible pest populations, while the USDA oversees deregulation of novel transgenic events through its Animal and Plant Health Inspection Service. Brazil's national biosafety commission, CTNBio, and Argentina's agriculture ministry enforce parallel approval frameworks that determine market access for stacked-trait varieties in South America's expanding production belt. Stakeholders must monitor how divergent national gene-editing classifications between the United States and European trading partners reshape seed development priorities and grain export certification requirements.
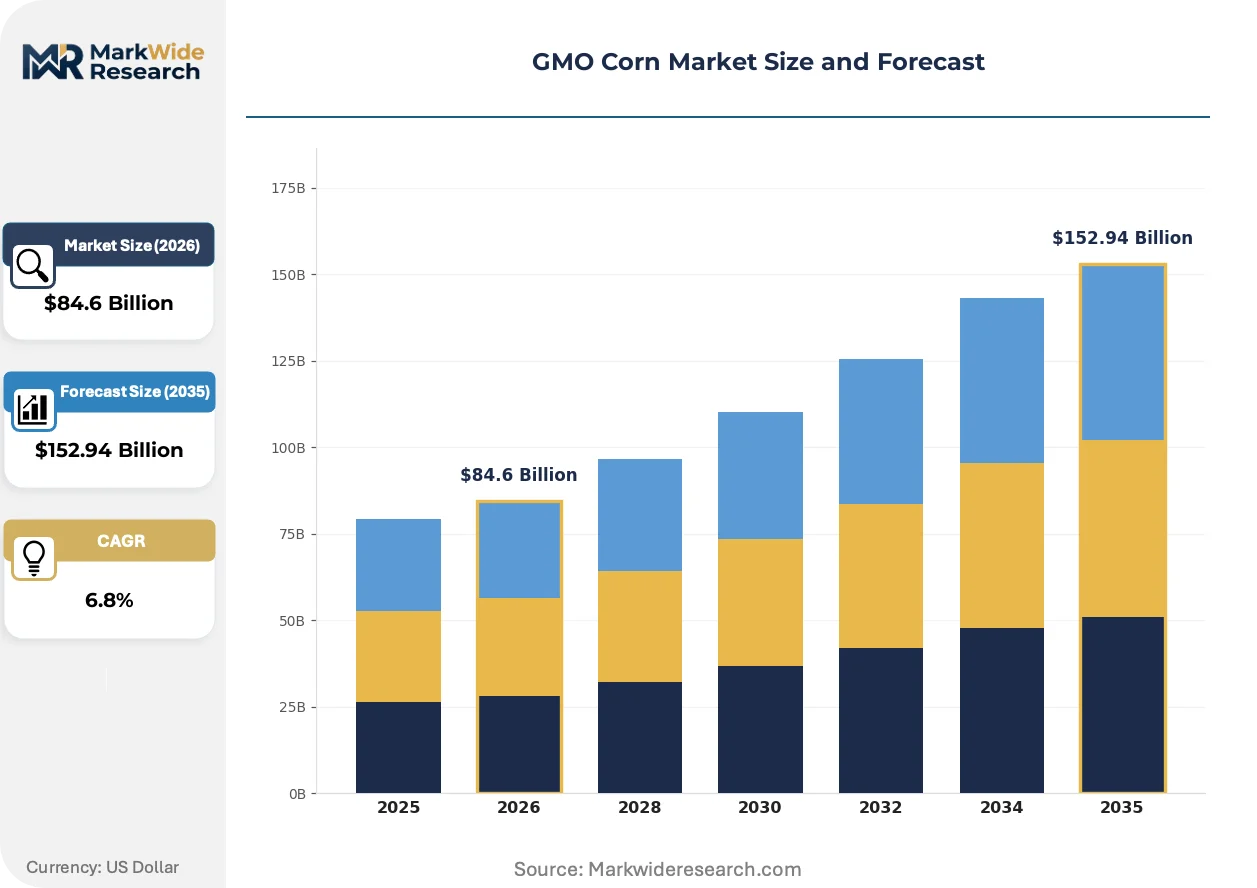
Market Dynamics
Stacked-trait seed technology is compressing breeding cycles and concentrating purchasing power among large-scale row-crop operations across the United States Corn Belt and Brazil's expanding livestock feed zones.
Growth Catalysts
- Renewable Fuel Mandates:Corn ethanol blending requirements in multiple jurisdictions are redirecting acreage toward high-starch varieties optimized for biofuel processing channels.
- CTNBio Approvals:Brazil's national biosafety commission is accelerating stacked-trait variety registrations, enabling faster commercialization of herbicide-tolerant hybrids for expanding cattle feed operations.
- Conservation Tillage Expansion:Glyphosate-tolerant cultivars are enabling zero-tillage adoption across Argentina's Pampas, reducing fuel and labor inputs for commercial producers.
Market Restraints
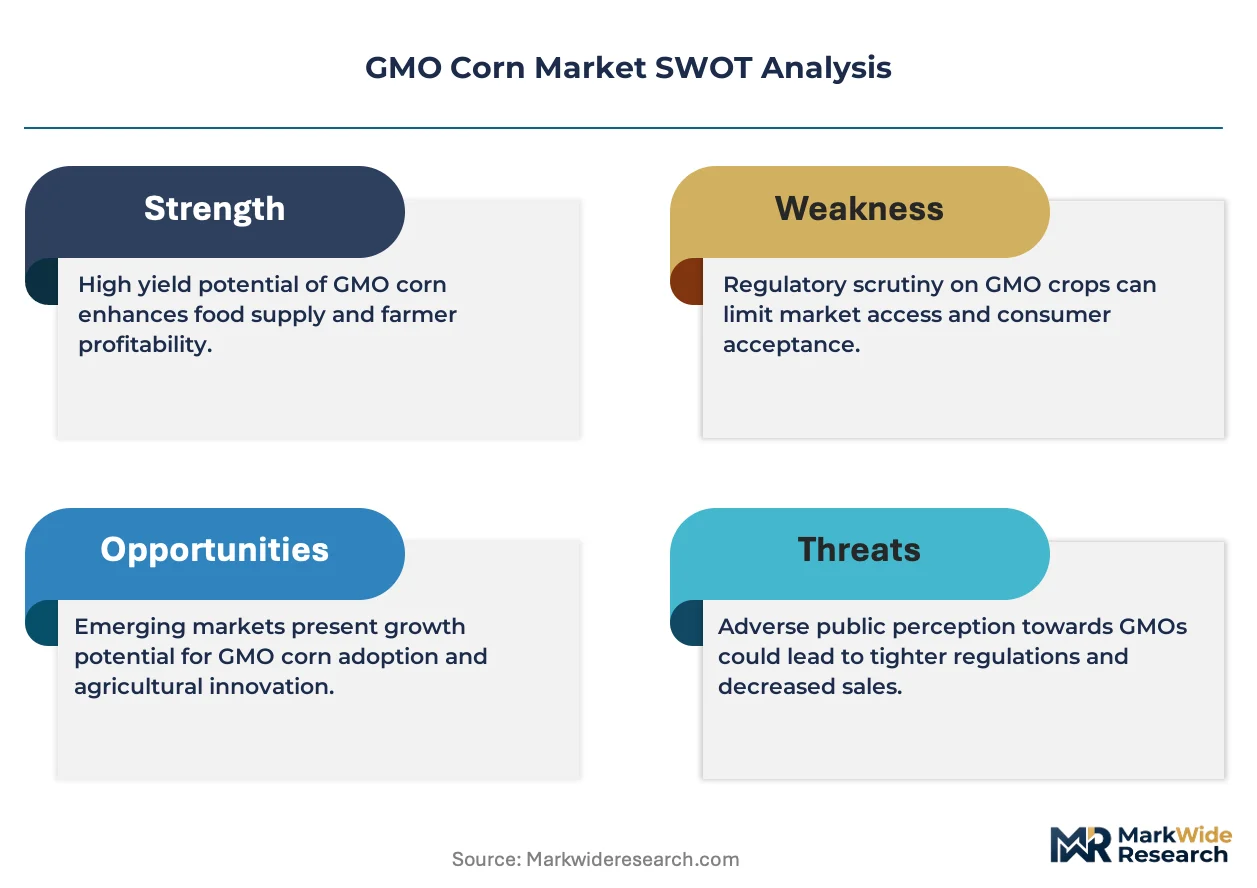
- Refuge Requirement Compliance:EPA mandates for insect-resistant corn preserve susceptible pest populations, forcing farmers to plant non-GMO buffer zones that reduce effective acreage yields.
- European Import Classification:EFSA gene-editing distinctions are creating certification bottlenecks for grain exporters, with evolving definitions between transgenic and edited varieties generating customs delays.
- Seed Cost Concentration:Intellectual property premiums embedded in hybrid genetics are concentrating input cost burdens among smaller producers in Paraguay and Uruguay.
Strategic Opportunities
- High-Lysine Food Processing:Specialized varieties for animal nutrition command margin premiums in integrated poultry and swine operations across the United States Midwest.
- CRISPR Convergence:Gene-editing platforms are enabling multi-trait stacking without transgenic markers, potentially bypassing EFSA regulatory thresholds for certain export classifications.
- Farmer Education Networks:Distribution partnerships in Mato Grosso and Goiás are addressing incomplete knowledge of stacked-trait hybrid performance, unlocking adoption in Brazil's frontier production zones.
Industry Challenges
- Event-Specific Marker Tracking:Regulatory compliance requires molecular verification of one to eight stacked transgenic events per cultivar, complicating seed certification and grain traceability systems.
- Trait Licensing Complexity:Cross-licensing agreements between germplasm holders and trait developers are creating royalty stacking that inflates seed pricing and fragments breeding pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GMO Corn Market |
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $152.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seeds, Grains, Flour, Feed Application: Agricultural Production, Livestock Feed, Food Processing, Biofuel End Use Industry: Agriculture, Food & Beverage, Bioenergy, Animal Husbandry Distribution Channel: Wholesale, Retail, Direct Sales, E-commerce |
| Companies Covered | Bayer CropScience, Corteva Agriscience, Syngenta, BASF, Groupe Limagrain, KWS Saat, Mahyco, Sakata Seed Corporation, DLF Seeds & Science, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GMO Corn Market Evolving Landscape
Gene-editing platforms are displacing first-generation transgenic insertion methods, while regulatory divergence between major trading blocs is forcing seed developers to maintain parallel certification pathways.
CRISPR-Cas9 editing systems are enabling precise trait insertion without foreign DNA sequences, preserving herbicide tolerance and insect resistance functions. Large-scale commercial row-crop producers in Iowa and Illinois are adopting these varieties at accelerating rates. The technology is miniaturizing regulatory approval timelines in jurisdictions that distinguish edited from transgenic organisms.
USDA-APHIS deregulation frameworks are streamlining novel trait evaluations for varieties lacking plant pest risk characteristics. Seed developers are redirecting R&D portfolios toward gene-edited stacks that circumvent EPA refuge requirements. North American export certification is experiencing the most significant documentation adjustments as trading partners adopt divergent edited-crop classifications.
Vertical coordination between ethanol processors and corn producers is compressing procurement cycles from annual spot purchasing to multi-year varietal contracts. Integrated biofuel facilities in Nebraska and Indiana are specifying starch content and moisture parameters directly with seed suppliers. This channel consolidation is most visible across the United States Corn Belt, where processor-owned agronomy services are displacing independent input retailers.
GMO Corn Market Segmentation
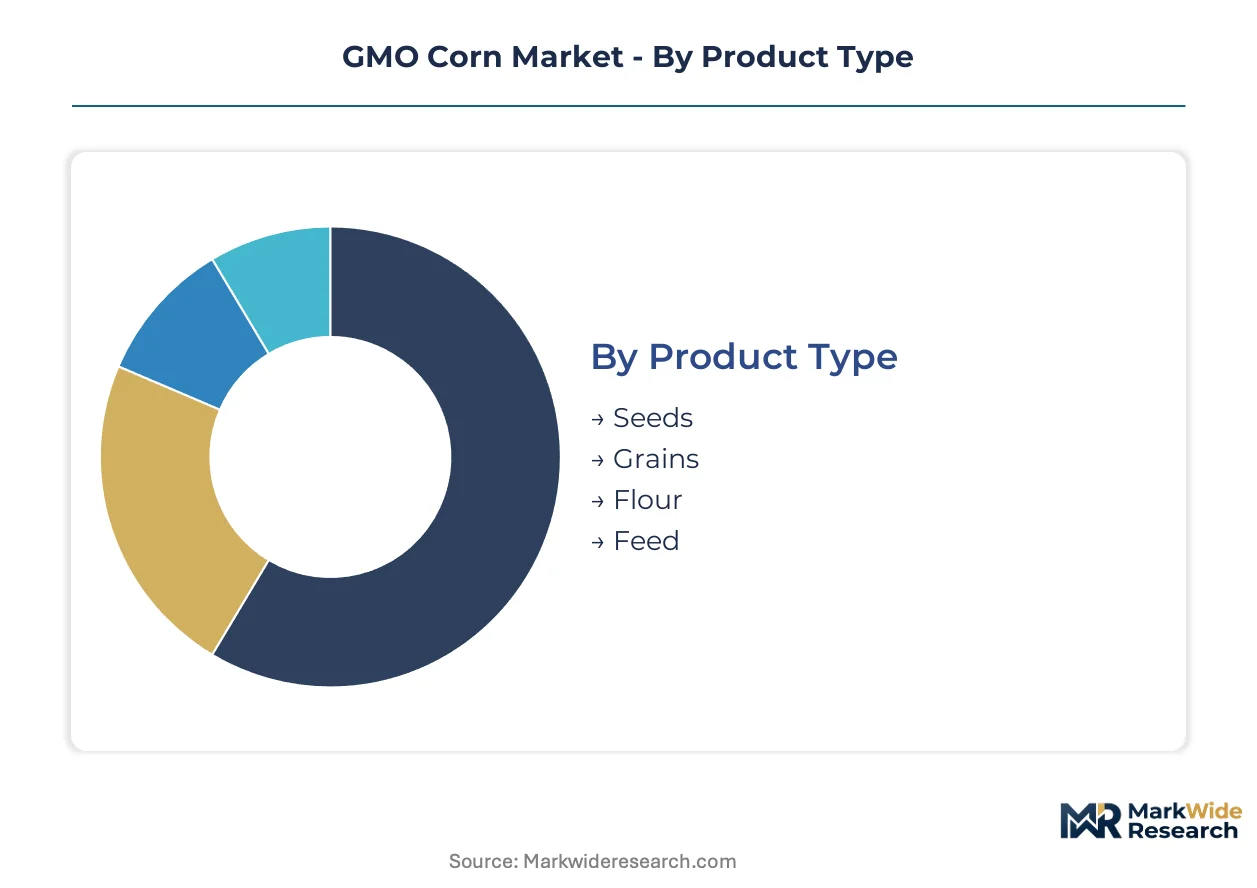
Segmentation in the GMO corn market reveals divergent value capture mechanisms across the seed-to-grain value chain. Intellectual property premiums concentrate in upstream genetics, while downstream channels fragment across commodity and specialized nutrition applications.
Product Type:
Domestic consumption patterns dominate seeds and feed, while grains and flour flow through export certification pipelines shaped by divergent national gene-editing classifications.
- Seeds:Hybrid genetics containing one to eight stacked transgenic events command recurring annual purchases with embedded trait licensing fees. Demand concentrates across Iowa and Illinois row-crop operations where large-scale producers optimize for herbicide tolerance and lepidopteran resistance traits.
- Grains:Commercial cultivars destined for ethanol processing and animal nutrition channels require molecular marker verification for stacked-event compliance. Brazil's CTNBio and Argentina's agriculture ministry enforce parallel approval frameworks that determine market access for export-bound shipments.
- Flour:Milled derivatives for food processing undergo specialized high-lysine and high-oil variety specifications.
- Feed:Livestock nutrition applications in Mato Grosso and Goiás drive herbicide-tolerant variety adoption for expanding cattle operations.
Seeds commands the established base. The steepest expansion runs through grains.
Application:
Cost tier differentiation separates mature anchor applications from emerging margin pools in renewable fuel channels.
- Agricultural Production:Conservation tillage systems leverage glyphosate-tolerant cultivars across Argentina's Pampas to reduce fuel and labor inputs for commercial producers.
- Livestock Feed:Specialized high-lysine varieties command nutrition premiums in integrated poultry and swine operations across the United States Midwest.
- Food Processing:Modified oil and starch profiles serve ingredient manufacturers with specific functional requirements.
- Biofuel:High-starch varieties optimized for ethanol processing experience accelerating procurement as renewable fuel mandates expand corn ethanol blending requirements in multiple jurisdictions.
Agricultural production anchors volume. Biofuel procurement is climbing the fastest.
End Use Industry:
Customer type fragmentation splits between commodity-scale operators and specialized nutrition formulators seeking differentiated trait stacks.
- Agriculture:Commercial row-crop producers in the United States Corn Belt sustain highest seed technology adoption rates through integrated agronomy services.
- Food & Beverage:Ingredient processors specify modified starch and oil profiles for functional food applications.
- Bioenergy:Ethanol facilities in Nebraska and Indiana compress procurement cycles through multi-year varietal contracts specifying starch content and moisture parameters.
- Animal Husbandry:Integrated operations across Brazil's expanding livestock zones purchase herbicide-tolerant hybrids for feed ration optimization.
Agriculture holds the volume foundation. Bioenergy shows the steepest trajectory.
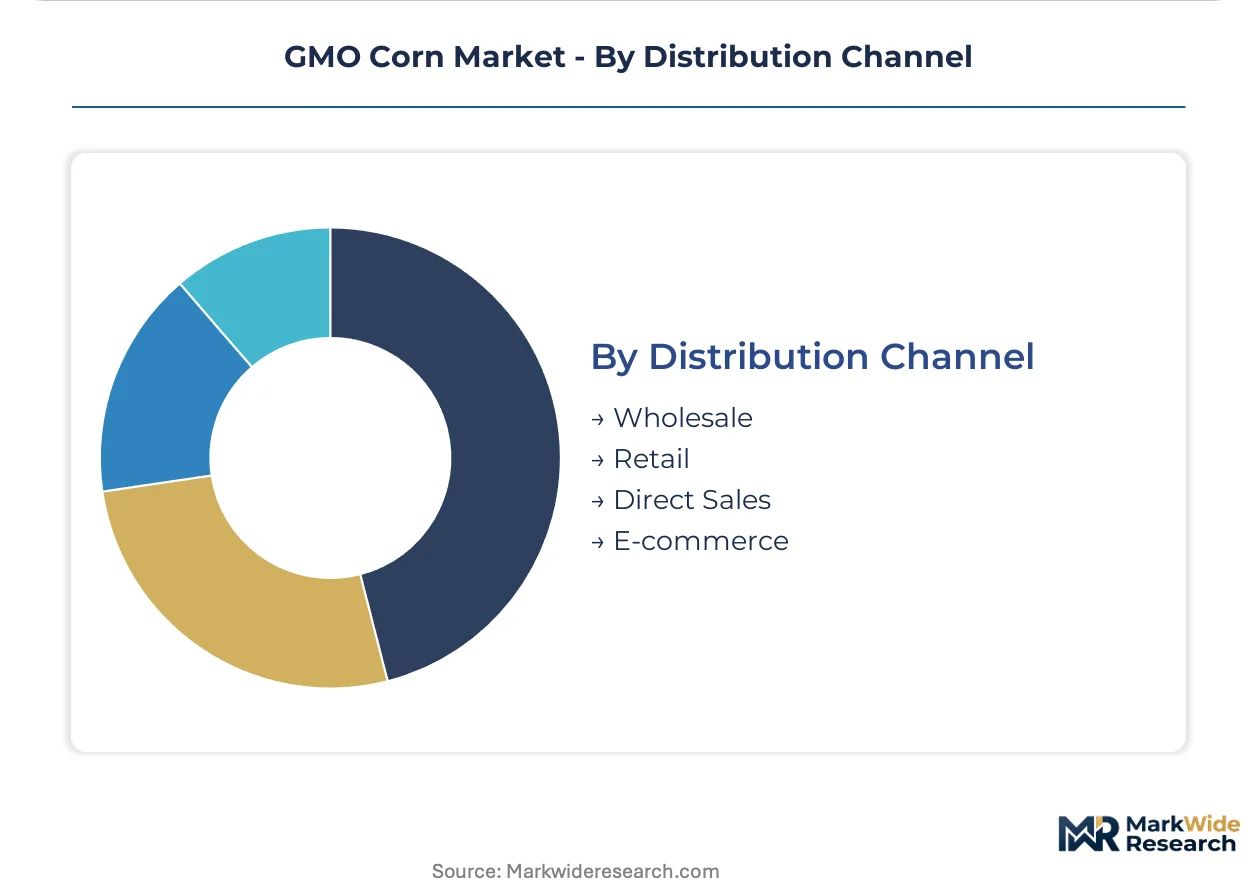
Distribution Channel:
Supply concentration dynamics favor direct relationships between seed developers and large-scale producers, while fragmented retail channels serve smaller operations.
- Wholesale:Volume aggregation for grain export channels requires traceability systems compliant with event-specific marker tracking regulations.
- Retail:Independent input retailers face displacement as processor-owned agronomy services consolidate across the United States Corn Belt.
- Direct Sales:Corteva Agriscience and Bayer CropScience leverage proprietary germplasm pipelines for large-scale row-crop contracting.
- E-commerce:Digital platforms penetrate frontier production zones where farmer education on stacked-trait hybrid performance remains incomplete.
Direct sales controls premium relationships. E-commerce is gaining share fastest in underserved regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States channels GMO corn predominantly into biofuel processing and livestock feed, while Brazil and Argentina prioritize export grain shipments and cattle ranching inputs. European demand concentrates in specialized high-lysine varieties for food processing. China maintains separate approval pathways for import versus domestic cultivation.
United States
Iowa and Illinois row-crop operations sustain the highest stacked-trait seed adoption rates for herbicide tolerance and lepidopteran resistance. The EPA enforces mandatory refuge requirements for insect-resistant cultivars, preserving susceptible pest populations through buffer zone mandates. Nebraska and Indiana ethanol facilities compress procurement cycles through multi-year varietal contracts specifying starch content parameters.
Brazil
Mato Grosso and Goiás livestock feed operations drive accelerating purchases of herbicide-tolerant hybrids for expanding cattle operations. CTNBio accelerates stacked-trait variety registrations, enabling faster commercialization timelines for frontier production zones. Distribution partnerships in Brazil's central-west region address incomplete farmer education on hybrid performance characteristics.
Argentina
The Pampas region leverages glyphosate-tolerant cultivars for zero-tillage adoption, reducing fuel and labor inputs for commercial producers. The agriculture ministry enforces parallel approval frameworks determining market access for export-bound grain shipments. Conservation tillage systems concentrate across Buenos Aires and Córdoba provinces where large-scale operations dominate.
China
Domestic cultivation approvals remain restricted while import demand for processing and feed channels expands. The Ministry of Agriculture and Rural Affairs maintains separate regulatory pathways for transgenic versus gene-edited varieties. Processing clusters in Shandong and Guangdong provinces drive demand for high-starch varieties optimized for industrial applications.
Germany
Specialized high-lysine and high-oil varieties command margin premiums in integrated poultry and swine operations across Lower Saxony and Bavaria. EFSA gene-editing distinctions create certification bottlenecks for grain exporters, with evolving definitions between transgenic and edited varieties generating customs complexities. Food processing clusters in North Rhine-Westphalia specify modified starch profiles for functional ingredient applications.
GMO Corn Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence reorganizing competitive tiers across germplasm and crop protection pipelines. The upstream segment concentrates around conglomerates combining seed genetics with chemistry portfolios, while regional breeding specialists compete through localized adaptation programs. Two strategic archetypes dominate: integrated seed-chemistry conglomerates leveraging combined R&D pipelines, and regional specialists optimizing for specific agroclimatic zones. Competitive moves center on trait licensing agreements and distribution network consolidation in frontier production zones.
Within the integrated tier, Bayer CropScience and Corteva Agriscience occupy positions representing combined germplasm and trait stack capabilities. Syngenta exemplifies the distribution-focused archetype, anchoring competitive positioning through network control in emerging production zones. BASF represents the chemistry-originated entrant, while KWS Saat and Groupe Limagrain sit within the European specialist tier emphasizing regional breeding programs.
| Leading Market Players |
|---|
| Bayer CropScience |
| Corteva Agriscience |
| Syngenta |
| BASF |
| Groupe Limagrain |
| KWS Saat |
| Mahyco |
| Sakata Seed Corporation |
| DLF Seeds & Science |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Bayer CropScience's North American germplasm facilities and Corteva's CRISPR editing platforms shapes both supply concentration and price floors across stacked-trait seed markets. Input cost burdens from trait licensing fees and molecular marker verification systems concentrate pricing power among integrated seed-chemistry conglomerates while squeezing regional breeding specialists.
Pricing Analysis
After-sales revenue from annual trait licensing renewals and refuge compliance advisory services drives lifetime value capture for seed developers. Three-tier pricing structure across premium CRISPR-edited stacks, standard transgenic hybrids, and economy conventional varieties segments buyers by scale and technology sophistication. Price differentiation hinges on stacked-event complexity and CTNBio or USDA-APHIS certification tier, with Brazil's frontier producers showing highest sensitivity and Iowa's large-scale operations least responsive. Cost compression in economy-tier conventional seeds is intensifying because of royalty stacking from cross-licensing agreements.
Supply Chain Analysis
Inventory lead times for stacked-trait hybrid seeds compress during Brazil's planting windows as CTNBio accelerates variety registrations. Germplasm development concentrates in the United States, Brazil, and Argentina where regulatory pathways for novel events are most established. Trait development draws from CRISPR-Cas9 editing systems, recombinant DNA insertion platforms, and molecular marker verification infrastructure. Single-source vulnerability sits with proprietary germplasm pipelines controlled by integrated conglomerates. Distribution runs through processor-owned agronomy services displacing independent retailers across the United States Corn Belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in refuge compliance advisory and multi-year varietal contracting expand faster than hardware seed sales as biofuel processors compress procurement cycles. Recurring revenue from trait licensing renewals and farmer education networks outpaces one-time germplasm transactions.
For Market Incumbents: Secure backward integration into CRISPR editing platforms to bypass EPA refuge requirements and reduce regulatory approval timelines. Defend against gene-edited specialty entrants by controlling distribution networks in Mato Grosso and Goiás where farmer education gaps persist. Capacity addition in Brazil's central-west region anchors market share against regional breeding specialists.
For New Entrants and Emerging Players: Anchor in high-lysine food processing varieties for integrated poultry and swine operations across the United States Midwest where margin premiums exceed commodity channels. Target Paraguay and Uruguay where intellectual property cost concentration has displaced smaller producers from stacked-trait adoption. Digital e-commerce platforms penetrating frontier zones with incomplete hybrid knowledge offer the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated seed-chemistry conglomerates with combined germplasm and crop protection pipelines. Long-term viability across the analysis window favors developers maintaining parallel certification pathways for transgenic and gene-edited classifications. Acquisition targets should demonstrate CTNBio or USDA-APHIS regulatory track records with stacked-trait portfolios. Divergence between United States and European gene-editing classifications serves as the critical inflection signal for export certification complexity.
| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Trait Stack Development | USDA-APHIS deregulation frameworks accelerate approval timelines for varieties lacking plant pest risk characteristics. |
| Brazil Distribution Partnership | Farmer education networks in Mato Grosso address incomplete knowledge of stacked-trait hybrid performance characteristics. |
| Refuge Compliance Service | EPA mandatory buffer zone mandates create recurring advisory revenue attached to insect-resistant seed sales. |
| Biofuel Processor Contracting | Nebraska and Indiana ethanol facilities specify starch content parameters through multi-year varietal agreements. |
| European Regulatory Pathway | EFSA gene-editing distinctions determine certification requirements for grain export classifications to specialized processors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with seed development executives, regulatory affairs leads at CTNBio and USDA-APHIS, agronomy service directors, and grain procurement managers at ethanol processing facilities. Secondary validation drew from EPA refuge requirement filings, CTNBio variety registration databases, USDA-APHIS deregulation petitions, and SEC 10-K disclosures from integrated seed-chemistry conglomerates. Bottom-up acreage adoption modeling and top-down revenue aggregation triangulate market sizing across the value chain.
Across the projection horizon, the analytical framework segments by product type, application channel, end-use industry, and distribution method. Modeled dimensions include stacked-event complexity, regulatory approval pathway, and regional production cluster. CAGRs derive from acreage penetration curves and input cost elasticity estimates. Forecast inputs incorporate renewable fuel mandate expansion trajectories and CTNBio registration velocity assumptions.
Material uncertainties — regulatory reclassification of gene-edited varieties, CTNBio approval delays, and European import certification bottlenecks — sit outside the modeled envelope. Forecasts reflect assumptions about farmer education completion rates and trait licensing fee structures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Grain Storage Silos Market
Grains
Basmati Rice Market
Grains
India Rice Market
Grains
Barley Grass Market
Grains
Colombia Grains Market
Grains
North America Wheat Protein Market
Grains
Wheat Bran Market
Grains
Guar Complex Market
Grains
Brazil Maize Market
Grains
Europe Wheat Market
Grains
Grain Augers Market
Grains
Cornmeal Market
Grains
Grain-Based Flours Market
Grains
Global Maize Market
Grains
Africa Maize Market
Grains
North America Rice Market