
 Europe Wheat Protein Market | 2026-2036
Europe Wheat Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wheat Protein Market Foresight
Subscription-based formulation support is expanding how wheat protein suppliers monetize technical partnerships beyond commodity sales. Cargill leverages its European R&D network to anchor customized protein blends for meat alternative developers. Kerry Group competes through flavor-masked hydrolyzed proteins that reduce bitter off-notes in high-concentration applications.
Wheat protein comprises glutenin and gliadin fractions extracted from wheat flour through wet-processing or dry-milling, yielding viscoelastic hydrates that provide structure, water binding, and emulsification in food matrices. Concentrates currently dominate European volume due to their cost position in bakery and snack applications, while isolates command premium positioning in nutritional supplements where protein purity thresholds exceed 90%. Hydrolyzed variants represent the fastest-expanding category as enzymatic treatment improves digestibility scores for sports nutrition and clinical nutrition formulations.
EFSA novel food assessments, EU Green Deal agricultural transition targets, and REACH chemical safety protocols collectively shape ingredient approval timelines, sustainable sourcing requirements, and processing aid classifications across the value chain. Germany's Federal Office of Consumer Protection and Food Safety enforces strict gluten threshold labeling that differentiates allergen-managed product lines from standard offerings. Stakeholders must monitor how the EU Deforestation Regulation extends due diligence obligations into wheat supply chains beyond current farm-gate traceability systems.
Market Dynamics
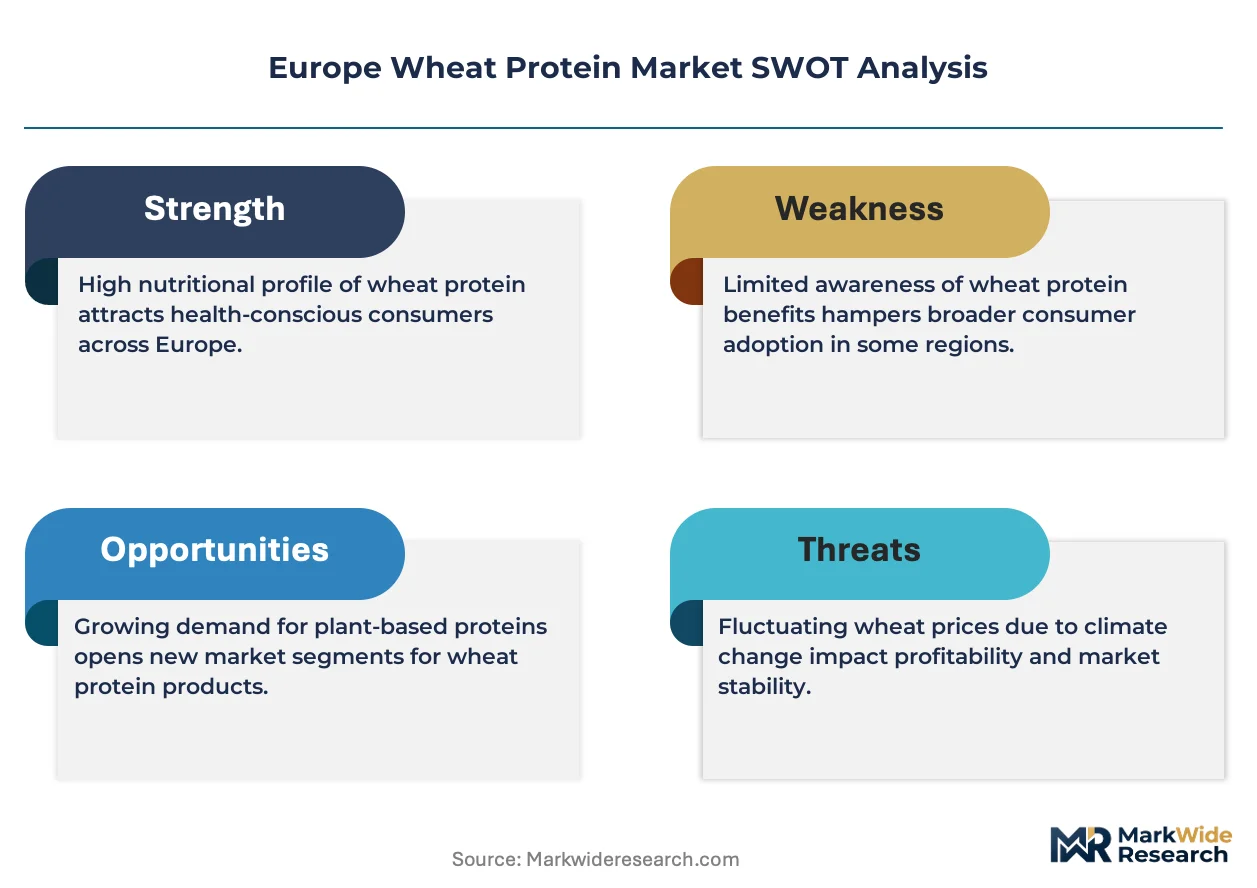
EFSA novel food assessments and EU Green Deal agricultural transition targets are compressing approval timelines while simultaneously mandating sustainable sourcing verification across wheat protein supply chains. These dual pressures are forcing ingredient suppliers to restructure technical documentation and farm-gate traceability systems simultaneously.
Growth Catalysts
- Plant-based meat alternatives:Food manufacturers in Germany and the Netherlands are substituting soy and pea proteins with wheat-derived isolates to achieve superior texture profiles in extruded products.
- REACH chemical safety protocols:Standardized processing aid classifications reduce regulatory friction for hydrolyzed protein variants entering sports nutrition formulations.
- EFSA novel food pathway streamlining:Accelerated safety evaluations for enzymatically treated proteins shorten time-to-market for clinical nutrition applications.
Market Restraints
- Input cost volatility:Wheat futures price swings tied to Black Sea supply disruptions compress margin predictability for concentrate producers.
- Supply concentration risk:Wet-processing capacity clusters in northern France, creating single-point vulnerability for isolate-grade output.
- Substitution threat:Fava bean and mung bean proteins from Asian suppliers displace wheat variants in allergen-sensitive bakery segments.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania exhibit sub-15% adoption rates for hydrolyzed proteins in sports nutrition, presenting first-mover expansion potential.
- EU Deforestation Regulation tailwind:Due diligence mandates favor European-sourced wheat over imported oilseed alternatives in sustainability-scored procurement.
- Precision fermentation convergence:Hybrid formulations combining wheat glutenin with microbial proteins unlock texture engineering previously unattainable with single-source ingredients.
Industry Challenges
- Enzymatic process engineering talent scarcity:Hydrolyzed protein production requires specialized biochemists conversant with EFSA dossier preparation, a skill set concentrated in Dutch and Belgian technical universities.
- Certification timeline compression:Dual-track approvals for novel food status and organic certification create 18-24 month commercialization delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wheat Protein Market |
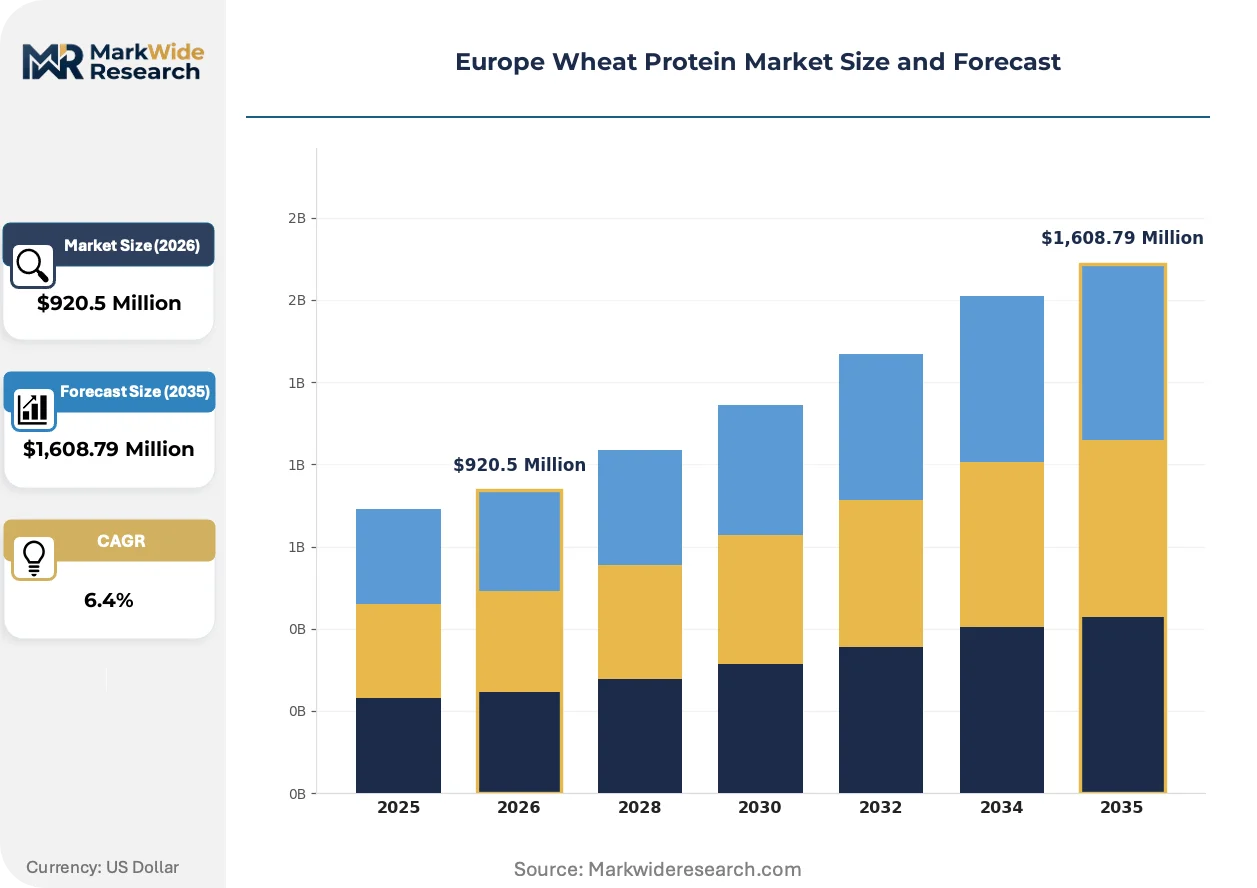
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,608.79 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Protein, Hydrolyzed Protein, Isolates, Concentrates Application: Bakery, Meat Alternatives, Snacks, Nutritional Supplements End Use Industry: Food & Beverage, Animal Feed, Pharmaceuticals, Cosmetics Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Archer Daniels Midland, Cargill, Bunge, ABF Ingredients, Rohm GmbH, Meelunie, Kerry Group, Tereos, Südzucker, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wheat Protein Market Shifts & Advancements
Processing technology advances and regulatory harmonization efforts are restructuring how wheat protein suppliers configure production assets and commercial partnerships. These shifts favor operators with integrated R&D-to-manufacturing capabilities.
Membrane filtration systems for protein fractionation are modularizing production economics for mid-scale European processors. Bakery ingredient manufacturers in France and Germany are adopting these units to produce custom glutenin-to-gliadin ratios for regional bread traditions. This equipment configuration is modularizing what previously required centralized industrial-scale wet-milling facilities into deployable 2,000-tonne annual modules.
EU Green Deal agricultural transition targets are mandating farm-level carbon accounting for wheat destined for food ingredients. German Federal Office of Consumer Protection and Food Safety enforcement of gluten threshold labeling now extends to imported raw materials. Dutch suppliers are responding by deploying blockchain-anchored farm-gate verification to preempt audit failures.
Ingredient buyers in meat alternative development are consolidating formulation partnerships around subscription-based technical service models rather than transactional commodity procurement. This restructuring compresses supplier rosters to three-to-five preferred partners per major food manufacturer. The Netherlands and southern Germany exhibit the most concentrated buyer consolidation, with developers locking multi-year protein supply agreements that bundle R&D collaboration.
Europe Wheat Protein Market Segmentation
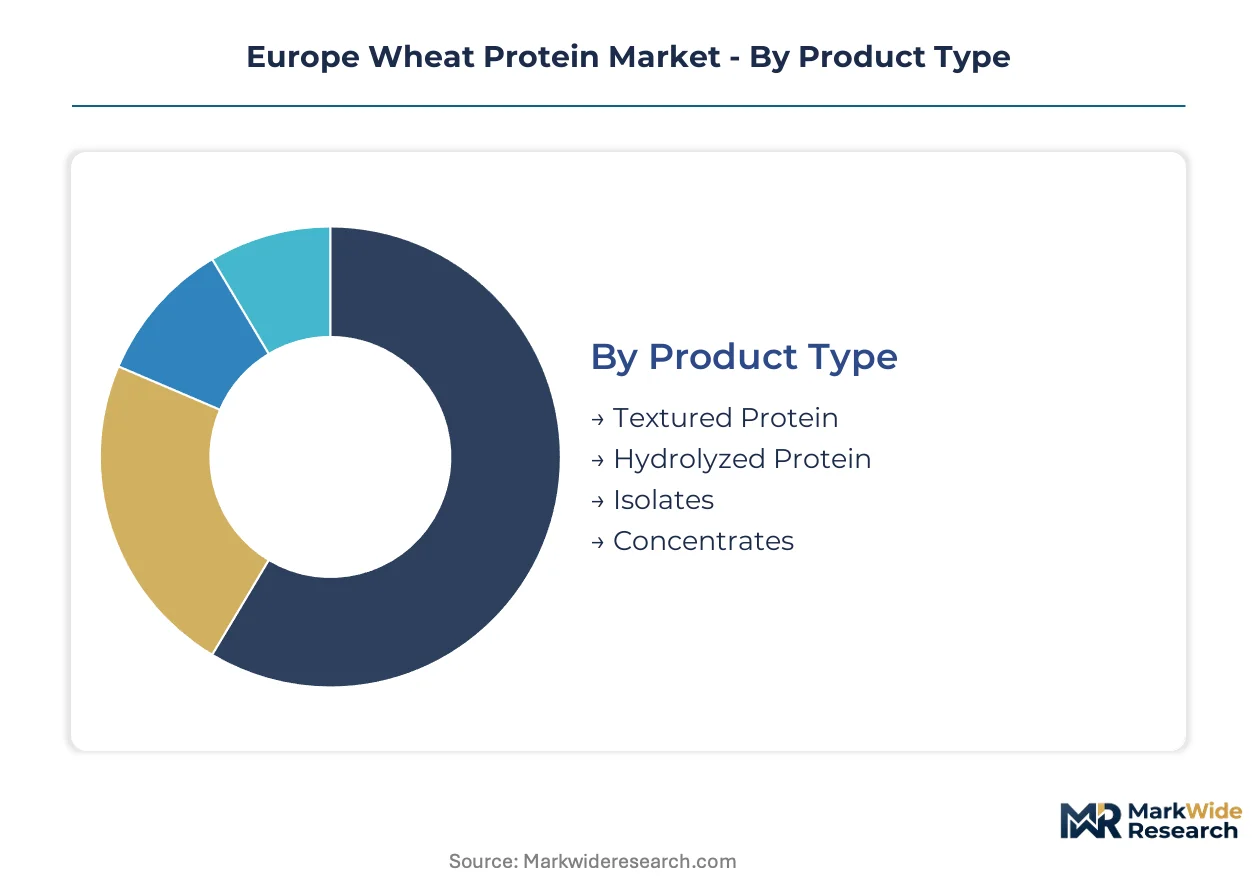
Segmentation in the Europe Wheat Protein Market reveals how protein fractionation technologies and end-use specifications create divergent margin structures across supplier portfolios. Product type distinctions drive capital allocation decisions, while application-based demand patterns determine regional facility investments.
Product Type:
Protein extraction intensity and enzymatic modification depth define the technical specification axis across this category.
- Concentrates:These 60-80% protein fractions retain native glutenin-gliadin ratios through wet-milling or dry-processing, delivering cost-efficient viscoelasticity for high-volume bakery applications. German and French industrial bakers dominate procurement volumes, though margin pressure from wheat futures volatility compresses supplier returns.
- Hydrolyzed Protein:Enzymatic cleavage reduces molecular weight to improve digestibility scores and solubility in liquid formulations. Sports nutrition developers in the Netherlands and clinical nutrition specialists in Belgium are expanding offtake fastest as EFSA novel food pathways streamline for enzymatically treated variants.
- Isolates:90%+ purity fractions command premium positioning through membrane filtration refinement. Nutritional supplement manufacturers source these for protein fortification where label claims require minimum impurity thresholds.
- Textured Protein:Extruded and spun fiber structures replicate meat mouthfeel through controlled hydration and heat-setting. Meat alternative developers in Germany substitute these for soy isolates to achieve superior bite resistance in refrigerated analogues.
Concentrates lead on scale; hydrolyzed protein leads on momentum.
Application:
Formulation complexity and regulatory exposure differentiate demand patterns across end-use categories.
- Meat Alternatives:Extruded wheat proteins provide structural integrity in plant-based sausages and cutlets where chew resistance and water retention determine consumer acceptance. Dutch and German food manufacturers are locking multi-year supply agreements with technical service bundling.
- Bakery:Native and modified gluten fractions control dough rheology, gas retention, and crumb structure across artisan and industrial bread production. French regional bread traditions drive custom glutenin-to-gliadin ratio specifications from local ingredient suppliers.
- Nutritional Supplements:High-purity isolates and hydrolyzed variants serve protein powder and ready-to-drink formulations where amino acid completeness and allergen labeling precision are non-negotiable.
- Snacks:Textured inclusions and binding proteins fortify extruded cereals and savory crisps, with cost positioning favoring concentrate grades over isolate alternatives.
Bakery commands absolute volume; meat alternatives are climbing the fastest.
End Use Industry:
Regulatory stringency and certification requirements segment value capture potential across downstream sectors.
- Food & Beverage:Dominant consumption channel spanning bakery, meat alternatives, and functional beverages. EFSA enforcement of gluten threshold labeling and EU Green Deal farm-gate traceability mandates shape procurement specifications.
- Pharmaceuticals:Hydrolyzed proteins enter clinical nutrition and specialized medical foods where digestibility and hypoallergenic positioning support therapeutic claims.
- Animal Feed:Wheat gluten meal provides protein fortification in pet food and aquaculture formulations, competing with soy and pea alternatives on amino acid profile and price.
- Cosmetics:Hydrolyzed wheat proteins function as film-forming agents and conditioning ingredients in hair and skin care, representing a niche but margin-accretive outlet.
Food & Beverage leads on scale; pharmaceuticals leads on margin expansion.
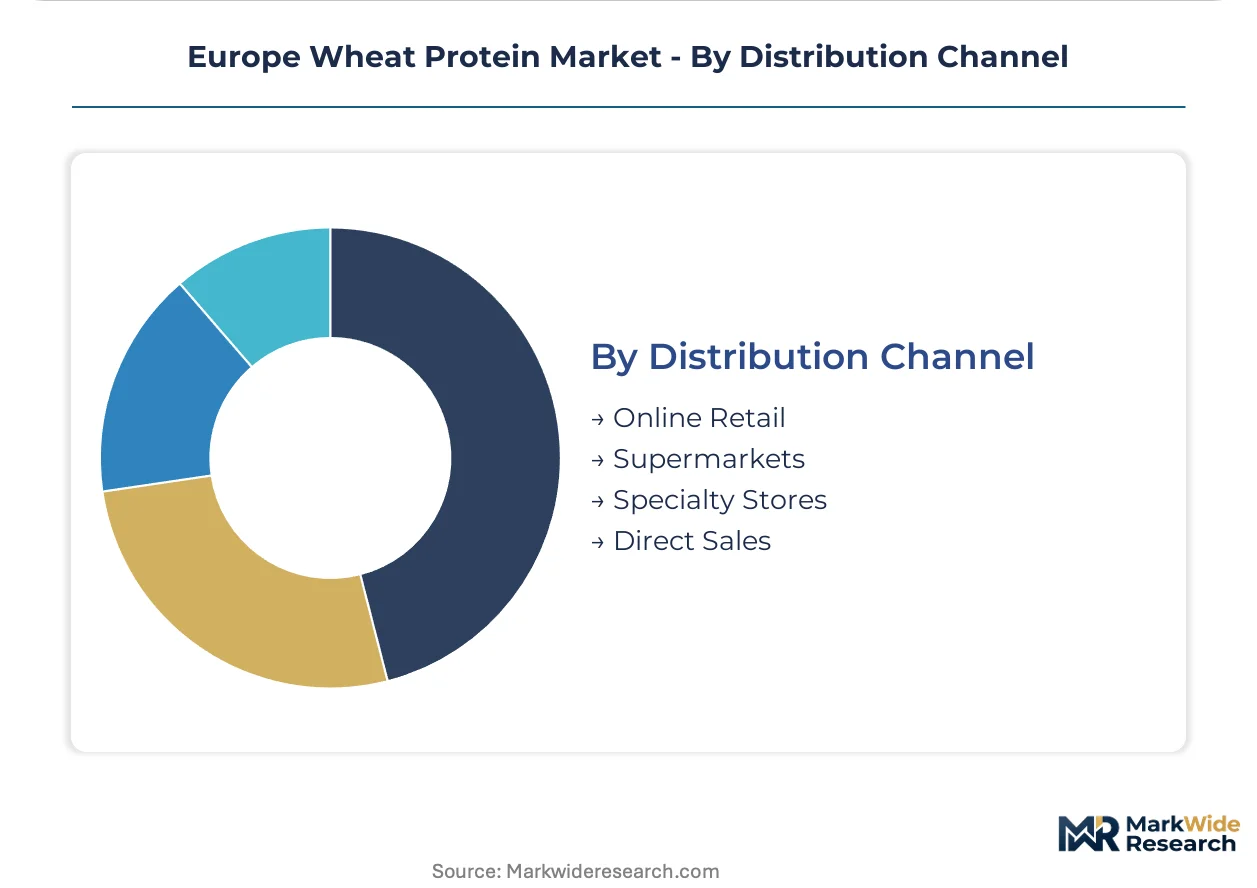
Distribution Channel:
Customer scale and technical service requirements determine channel economics and supplier relationship structures.
- Direct Sales:Large food manufacturers and meat alternative developers procure through technical partnership agreements with embedded formulation support. Subscription-based service models are consolidating supplier rosters to three-to-five preferred partners per major buyer.
- Specialty Stores:Independent bakeries and artisan food producers source customized gluten fractions and technical guidance through regional ingredient distributors.
- Supermarkets:Packaged wheat protein ingredients for home baking and small-scale food manufacturing reach consumers through retail grocery placement.
- Online Retail:E-commerce platforms serve sports nutrition enthusiasts and small supplement manufacturers with direct-to-consumer and small-batch procurement options.
Direct sales leads on revenue concentration; specialty stores retain growth in artisan segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's meat alternative sector absorbs wheat protein volumes at roughly triple the per-capita rate of Spain, reflecting divergent plant-based adoption curves across the continent. France maintains dominance in bakery-grade concentrate consumption through artisan and industrial channels alike. The Netherlands anchors hydrolyzed protein innovation for sports nutrition applications.
Germany
Meat alternative developers in Berlin and Cologne drive isolate-grade procurement for extruded analogues, while industrial bakers in Munich maintain steady concentrate offtake for traditional bread production. The Federal Office of Consumer Protection and Food Safety enforces strict gluten threshold labeling that segments allergen-managed product lines. Wet-processing capacity clusters along the Rhine corridor, with Mannheim and Ludwigshafen hosting fractionation facilities serving pan-European supplement manufacturers.
France
Artisan bakers in Paris and Lyon demand custom glutenin-to-gliadin ratios for regional bread traditions, sustaining specialty concentrate production. EU Green Deal agricultural transition targets mandate farm-level carbon accounting for wheat entering food ingredient channels. Northern France, particularly the Hauts-de-France region, concentrates wet-milling infrastructure that supplies isolate-grade output to pharmaceutical and nutritional customers.
Netherlands
Sports nutrition formulators in Amsterdam and Utrecht expand hydrolyzed protein incorporation for digestibility-optimized powders and ready-to-drink beverages. EFSA novel food assessments for enzymatically treated proteins streamline faster in Dutch regulatory submissions than comparable southern European filings. The Wageningen food innovation cluster anchors precision fermentation research into hybrid wheat-microbial protein formulations.
Belgium
Clinical nutrition specialists in Brussels and Antwerp source hydrolyzed variants for medical food applications requiring hypoallergenic positioning. REACH chemical safety protocols standardize processing aid classifications that reduce regulatory friction for hydrolyzed entrants. The Port of Antwerp handles import flows of wheat gluten meal competing with domestic fractionation output.
Poland
Sports nutrition adoption rates for hydrolyzed proteins remain below fifteen percent, presenting first-mover expansion potential for suppliers establishing local technical partnerships. EU Deforestation Regulation due diligence obligations favor European-sourced wheat over imported oilseed alternatives in sustainability-scored procurement. Warsaw and Łódź industrial zones attract mid-scale membrane filtration investments to serve emerging Central European demand.
Europe Wheat Protein Market Competitive Landscape
Top-tier vendors anchor premium isolate and hydrolyzed protein supply, while mid-scale regional processors compete on bakery-grade concentrate customization. The vendor base stratifies across three tiers: multinational agribusiness conglomerates with integrated R&D networks, specialized European ingredient houses with formulation service bundling, and regional millers with commodity-grade output. Strategic archetypes include subscription-based technical partnership providers, precision fermentation collaborators, and carbon-accounted sourcing specialists. Competitive moves concentrate on multi-year supply agreements with embedded R&D collaboration and membrane filtration capacity modularization.
Within the multinational agribusiness tier, Cargill and Archer Daniels Midland occupy positions defined by global sourcing scale and European R&D network deployment. Kerry Group exemplifies the specialized ingredient house archetype through flavor-masked hydrolyzed protein offerings. Meelunie represents Dutch-origin trading and processing expertise with historical strength in gluten and starch fractionation. These three entities anchor the competitive structure through distinct capability configurations rather than overlapping strategic positioning.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Cargill |
| Bunge |
| ABF Ingredients |
| Rohm GmbH |
| Meelunie |
| Kerry Group |
| Tereos |
| Südzucker |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap millers in northern France anchor wet-processing capacity for isolate-grade output, their consolidated ownership patterns enabling patient capital allocation that sustains pricing discipline despite wheat futures volatility. This supply-side concentration reinforces premium capture for hydrolyzed variants while compressing margins in commoditized concentrate tiers.
Pricing Analysis
Capacity additions in Poland and Romania are reshaping price floors for mid-grade concentrates as membrane filtration modularization reduces entry barriers. Pricing stratifies across isolate premiums for pharmaceutical buyers, contract-indexed concentrates for industrial bakers, and spot-traded hydrolyzed variants for sports nutrition formulators. Cost compression in concentrate tiers is intensifying because Black Sea supply disruptions feed raw material volatility. Industrial bakers in Germany exhibit highest price sensitivity; clinical nutrition specialists in Belgium show lowest elasticity due to certification-locked supplier relationships.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Antwerp, and Hamburg orchestrate hub-and-spoke patterns that consolidate wheat protein flows before final-mile dispersion to meat alternative developers and supplement manufacturers. Wet-milling infrastructure draws from wheat cultivation clusters in France, Germany, and Poland, with enzymatic processing inputs resting on biocatalyst supply chains anchored in Dutch and Belgian technical centers. Single-source vulnerability concentrates in Hauts-de-France isolate production. Distribution runs through direct technical partnerships for large formulators and specialty ingredient distributors for artisan bakery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on enzymatic process efficiency gains that reduce unit costs for hydrolyzed variants while EFSA pathway streamlining accelerates premium-tier adoption.
For Market Incumbents: Deepen backward integration into wheat cultivation partnerships that secure farm-gate traceability for EU Deforestation Regulation compliance, while expanding membrane filtration capacity in Poland to preempt emerging competitor entry. Fava bean protein substitution in allergen-sensitive segments demands flavor-masked hydrolyzed innovation investments. Certification-locked supplier relationships with Dutch sports nutrition formulators provide defensive moats against price erosion. For New Entrants and Emerging Players: Launch via direct technical service partnerships targeting Polish and Romanian sports nutrition developers where hydrolyzed protein adoption remains below fifteen percent. Eastern European underpenetration offers white-space expansion before incumbent capacity localization. Subscription-based formulation support bundling differentiates entrants from transactional commodity suppliers. For Investors and Strategic Acquirers: Specialized ingredient houses with enzymatic process capabilities and EFSA dossier expertise are the most active acquirer targets in this space, as multinational agribusiness conglomerates seek technical service bundling competencies. Long-term viability hinges on precision fermentation hybrid formulation pipelines. The signal to watch is Dutch regulatory submission velocity for novel food approvals, which indicates pipeline maturity and partnership traction.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Modularization | Polish facility investments reduce capital barriers for mid-scale isolate production serving Central European pharmaceutical customers. |
| EFSA Dossier Capability Acquisition | Biochemical talent concentration in Wageningen and Ghent accelerates novel food approval timelines for enzymatic variants. |
| Blockchain-Anchored Farm Verification | German Federal Office enforcement of gluten threshold labeling extends to imported raw materials, demanding traceability infrastructure. |
| Precision Fermentation Collaboration | Hybrid wheat-microbial protein formulations unlock texture engineering previously unattainable with single-source ingredients. |
| Subscription Technical Service Model | Multi-year supply agreements with embedded R&D collaboration consolidate supplier rosters to three-to-five preferred partners per major buyer. |
Research Methodology
Multiple input streams — primary interviews with plant protein procurement managers, regulatory affairs specialists at EFSA, and sports nutrition formulators; secondary validation through EU novel food approval databases, REACH chemical safety filings, and customs trade records — were reconciled through bottom-up facility capacity modeling and top-down demand segmentation triangulation.
Data-stream reconciliation anchored volume projections across product type, application, and end-use industry dimensions, with CAGRs derived from elasticity-adjusted price-quantity relationships and capacity utilization trajectories. Wheat futures correlation modeling and enzymatic process yield assumptions shaped the analytical framework throughout the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Black Sea supply disruption scenarios and EFSA approval timeline delays. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and agricultural transition compliance costs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
North America Wheat Protein Market
Grains
Brown Rice Market
Grains
Grain Augers Market
Grains
North America Pulses Market
Grains
North America Wheat Market
Grains
United States Rice Market
Grains
Asia Pacific Maize Market
Grains
Whole-Wheat Flour Market
Grains
Pulses Market
Grains
North America Wheat Flour Market
Grains
Argentina Maize Market
Grains
Corn Gluten Feed Market
Grains
Ancient Grain Market
Grains
Europe Maize Market
Grains
Global Grain Mill Products Market
Grains
South America Wheat Market