
 Cameroon Grains Market | 2026-2036
Cameroon Grains Market Size, Share, and Industry Trends Forecast 2026-2036
Cameroon Grains Market Insights
Food manufacturing is realigning grain procurement toward standardized, traceable supply chains as packaged food processors scale operations in Douala and Yaoundé. Sodecoton leverages its upstream control over cottonseed and rotational grain production in northern growing belts. Crésus Agro sustains contract farming networks that anchor smallholder maize and sorghum into formal wholesale channels. T Choithram and Sons' Mahima SARL competes through integrated milling and retail distribution across coastal urban corridors.
Cameroon grains comprise cereal crops—principally maize, rice, millet, and sorghum—cultivated across agro-ecological zones from the Sudano-Sahelian north to the humid forest south, with moisture content and mycotoxin thresholds determining commercial eligibility for industrial buyers. Maize dominates volume throughput as the primary feedstock for flour millers and brewing operations, while rice imports face structural displacement from domestic parboiling investments. Distribution channels fragment structurally: wholesale assemblies at Bamenda and Garoua retain price-setting power for rural surplus, but retail and export channels capture widening margin pools as urban consumption formalizes.
Cameroon's Ministry of Trade and the National Agency for Food Safety (ANASA) enforce phytosanitary standards and packaging rules that determine market access for domestic and cross-border grain flows. The Central African Economic and Monetary Community (CEMAC) customs union shapes regional export eligibility through harmonized tariff structures and origin certification requirements. Stakeholders must monitor evolving mycotoxin limits and traceability mandates that will determine which processing investments secure preferential offtake from formal sector buyers.
Market Dynamics
Cameroon's Ministry of Agriculture and Rural Development is tightening quality certification rules for domestic grain circulation, forcing food manufacturers to realign procurement toward standardized, traceable supply chains as urban milling clusters scale operations.
Growth Catalysts
- Urban milling cluster expansion:Industrial flour millers and brewing operations in Douala and Yaoundé are consolidating offtake from formal wholesale channels, pulling smallholder production into certified supply chains.
- ANASA phytosanitary enforcement:The National Agency for Food Safety's packaging and mycotoxin standards are disqualifying informal traders from industrial buyer networks, privileging compliant processors.
- Domestic parboiling investment:Rice import displacement through local processing capacity is redirecting demand toward domestic grain varieties cultivated in humid forest agro-ecological zones.
Market Restraints
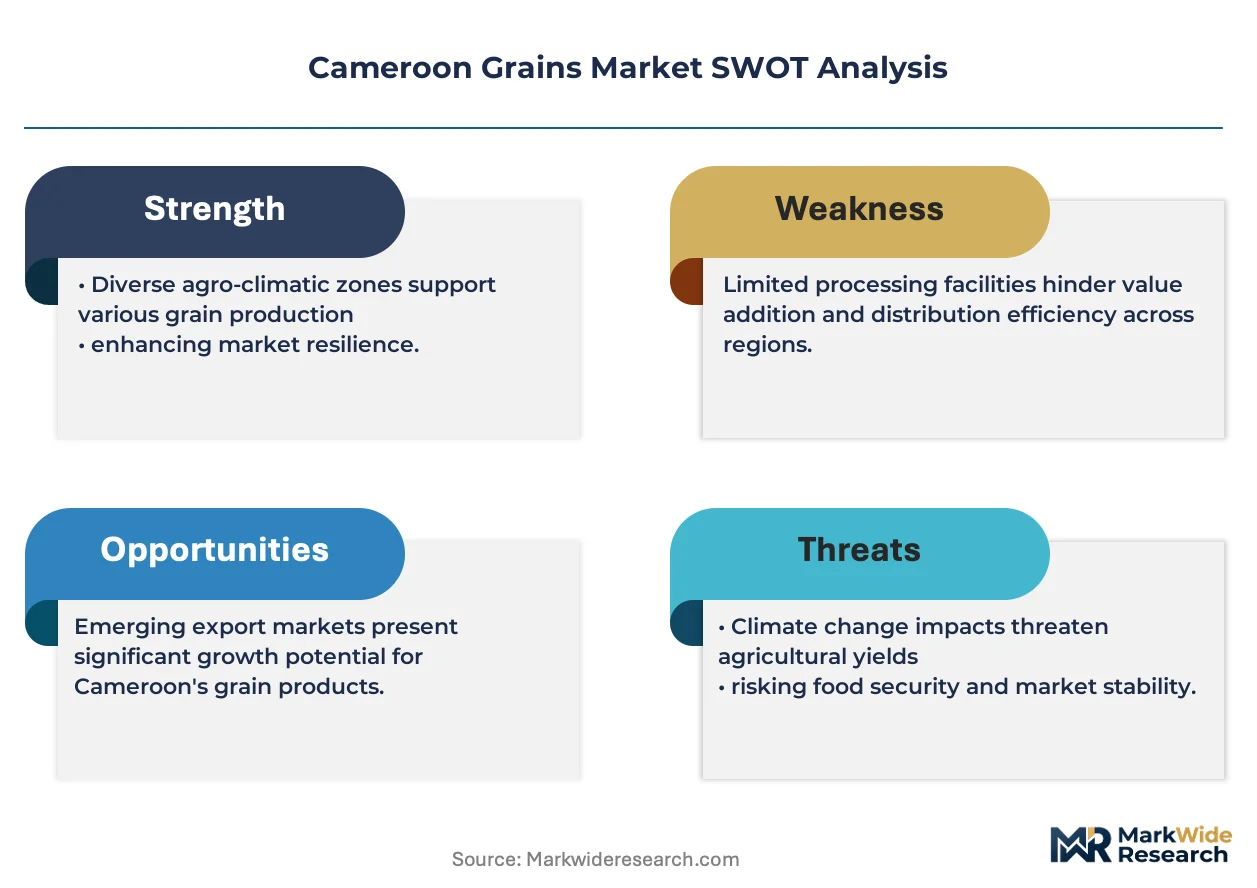
- Input cost volatility:Fertilizer and fuel price fluctuations in northern Sudano-Sahelian growing belts compress margins for rotational grain producers dependent on cottonseed byproduct cycles.
- Supply concentration risk:Wholesale assemblies at Bamenda and Garoua retain price-setting power over rural surplus, limiting processor bargaining leverage during harvest compression periods.
- Technical limitation:Moisture content thresholds for commercial eligibility exclude substantial smallholder harvest volumes from formal sector channels, perpetuating informal trade dominance.
Strategic Opportunities
- CEMAC regional export eligibility:Harmonized tariff structures and origin certification requirements within the Central African Economic and Monetary Community customs union open cross-border grain flows to Gabon, Equatorial Guinea, and Chad.
- Traceability mandate compliance:Evolving mycotoxin limits create preferential offtake windows for processing investments integrating blockchain or digital farm-gate verification systems.
- Port logistics integration:Coastal urban corridors around Douala offer underexploited export channel potential for premium-grade certified grains meeting international phytosanitary standards.
Industry Challenges
- Certification timeline compression:ANASA's accelerating inspection cycles strain smallholder cooperatives lacking laboratory access or documentation infrastructure for rapid compliance demonstration.
- Supply chain reconfiguration friction:Transitioning from wholesale assembly dependence to direct contract farming networks requires working capital restructuring that informal traders cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cameroon Grains Market |
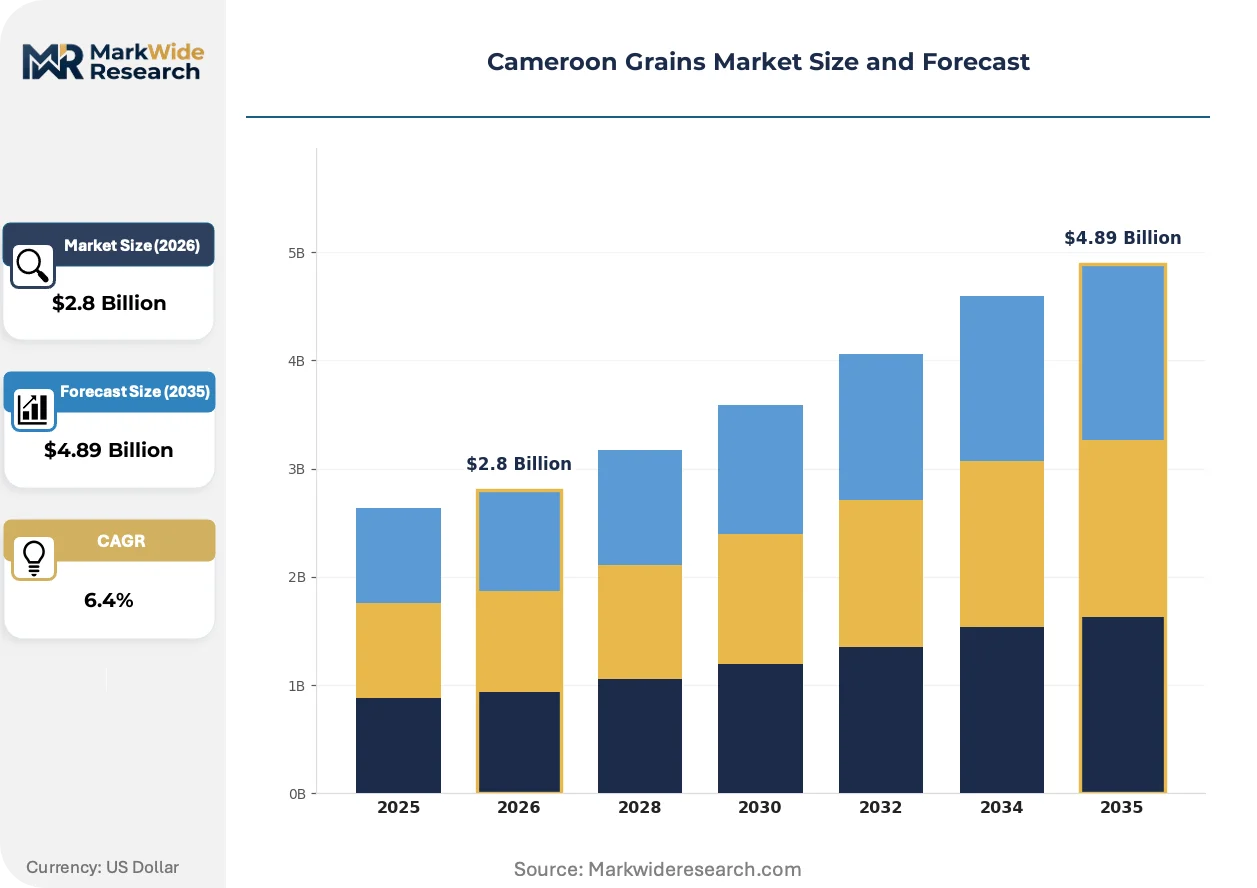
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Maize, Rice, Millet, Sorghum Distribution Channel: Wholesale, Retail, Online, Export End User: Food Manufacturers, Restaurants, Households, Exporters Processing Method: Drying, Milling, Parboiling, Packaging |
| Companies Covered | Cameroon Development Corporation, Sodecoton, Farms Solution, Crésus Agro, AIT Group, YFarmer, Ethos SARL, JMAO Business, T Choithram and Sons’ Mahima SARL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cameroon Grains Market Trends and Innovations
Digital traceability systems and mechanized post-harvest handling are compressing the gap between farm-gate production and industrial buyer specifications, while regulatory tightening accelerates formalization of previously informal trade channels.
Blockchain-enabled grain provenance tracking is consolidating quality verification workflows into unified digital platforms that capture moisture content, pesticide application records, and storage conditions from harvest through milling. Large flour processors in Yaoundé are piloting these systems to preempt ANASA rejection penalties. The technology is consolidating previously fragmented documentation steps into single-source compliance records that reduce inspection delays.
ANASA's phased implementation of mycotoxin threshold reductions is forcing processors to invest in on-site testing laboratories or third-party certification partnerships. Industrial buyers are responding by tightening supplier prequalification criteria and rejecting spot-market purchases lacking chain-of-custody documentation. Parboiling operations in the Littoral Region face the steepest compliance ramps due to rice's susceptibility to aflatoxin contamination during humid storage.
Contract farming arrangements are displacing spot-market procurement as the dominant sourcing mechanism for formal sector millers. Smallholder networks in the Centre Region are aggregating through cooperatives to meet volume and consistency thresholds that individual farms cannot satisfy. This shift is most visible among maize suppliers to brewing operations, where multi-year purchase agreements now specify varietal purity and delivery scheduling.
Cameroon Grains Market Segmentation
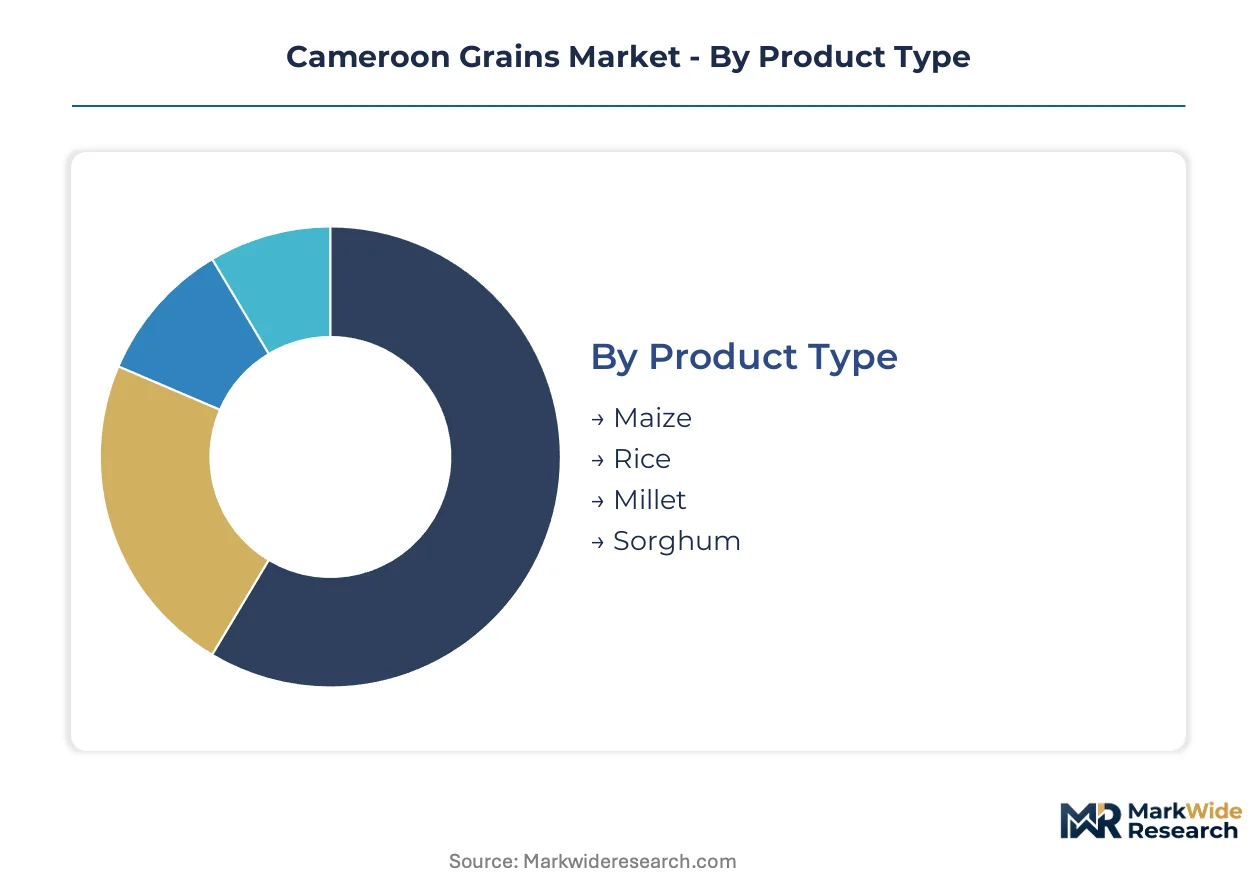
Grain procurement decisions in Cameroon diverge sharply across buyer categories, with industrial processors imposing certification requirements that informal channels cannot satisfy. Understanding these fault lines reveals where value capture concentrates and which supply chain investments yield preferential market access.
Product Type:
Buyers differentiate grain types by moisture tolerance, mycotoxin susceptibility, and suitability for mechanized processing—factors that determine eligibility for formal sector offtake.
- Maize:High-starch varieties with 13-14% moisture thresholds dominate industrial flour milling and brewing feedstocks. Yaoundé millers consolidate procurement through contract networks that specify varietal purity and delivery windows, squeezing spot-market traders from formal channels.
- Rice:Humid forest zone cultivation yields parboiling-grade paddy with strict aflatoxin vulnerability during storage. Domestic processing investments in the Littoral Region are displacing imports, redirecting demand toward local supply chains that meet ANASA packaging mandates.
- Millet:Drought-tolerant small grains from Sudano-Sahelian belts serve niche brewing and traditional food applications with limited formal sector penetration.
- Sorghum:Rotational cropping with cottonseed byproduct cycles in northern growing zones supplies regional brewing and animal feed channels.
Volume sits with maize; growth tilts toward rice.
Distribution Channel:
Margin capture varies dramatically by channel, with formalization pressures rewarding investments in traceability infrastructure and punishing informal assembly points.
- Wholesale:Bamenda and Garoua assemblies retain price-setting power over rural surplus but face disqualification from industrial buyer networks lacking chain-of-custody documentation. Cooperatives with laboratory access are consolidating previously fragmented supplier bases.
- Retail:Urban milling clusters in Douala and Yaoundé capture widening margin pools as packaged food processors scale operations and tighten prequalification criteria.
- Online:Digital platforms aggregate smallholder volumes for direct-to-processor sales, bypassing traditional wholesale markups where blockchain verification systems are deployed.
- Export:CEMEC origin certification requirements filter eligible flows toward Gabon, Equatorial Guinea, and Chad, privileging processors with integrated port logistics in coastal corridors.
Wholesale channels dominate current throughput; retail and export routes are expanding most quickly.
End User:
Specification stringency separates industrial buyers from price-sensitive consumers, creating tiered supply chains that rarely intersect.
- Food Manufacturers:Flour millers and brewing operations impose varietal purity, moisture content, and mycotoxin thresholds that exclude substantial smallholder harvest volumes. Multi-year purchase agreements now specify delivery scheduling and digital traceability compliance.
- Restaurants:Urban food service operators source through intermediate wholesalers with inconsistent quality documentation, limiting access to premium-grade certified stocks.
- Households:Traditional consumption channels absorb informal trade volumes disqualified from industrial specifications, perpetuating parallel market structures.
- Exporters:Cross-border flows to CEMEC partners require harmonized phytosanitary documentation that only integrated processors with captive laboratory capacity can satisfy.
Food manufacturers command the largest volume commitments; exporters are gaining share fastest.
Processing Method:
Capital intensity and regulatory exposure determine which processing stages attract investment and which remain fragmented.
- Drying:Mechanized post-harvest handling with moisture monitoring systems determines commercial eligibility for formal sector channels. Smallholder cooperatives lacking controlled drying infrastructure lose volume to integrated processors.
- Milling:Industrial flour operations in Douala and Yaoundé consolidate offtake through backward integration into contract farming networks, displacing independent millers.
- Parboiling:Rice-specific processing in humid forest zones faces steepest ANASA compliance ramps due to aflatoxin susceptibility, favoring investments with on-site testing laboratories.
- Packaging:National Agency for Food Safety labeling mandates disqualify informal repackagers from industrial buyer networks, concentrating this function among certified facilities.
Milling commands installed capacity; parboiling shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cameroon's Free Trade Zone incentives around Douala and Yaoundé concentrate grain processing investments where port logistics and urban milling clusters converge. The Ministry of Agriculture and Rural Development deploys differential quality certification rules across agro-ecological zones, creating compliance gradients that favor coastal processors over inland assemblers.
Centre Region
Yaoundé's brewing operations and flour millers anchor formal sector demand for certified maize with varietal purity specifications. ANASA's phytosanitary enforcement tightest around urban processing clusters, disqualifying informal traders lacking chain-of-custody documentation. Contract farming networks in the humid forest belt aggregate smallholder volumes through cooperatives that meet multi-year purchase agreement thresholds.
Littoral Region
Douala's port logistics infrastructure positions coastal corridors for export channel expansion into CEMEC partner markets. Domestic parboiling investments displace rice imports, redirecting demand toward local supply chains that satisfy packaging mandates. Industrial buyers here impose the steepest mycotoxin compliance ramps due to rice's aflatoxin susceptibility during humid storage.
North Region
Sudano-Sahelian growing belts supply rotational grain production tied to cottonseed byproduct cycles around Garoua. Wholesale assemblies retain price-setting power over rural surplus, limiting processor bargaining leverage during harvest compression. Sodecoton leverages upstream control over cottonseed to anchor smallholder sorghum into formal wholesale channels.
Northwest Region
Bamenda's wholesale markets historically dominated regional price discovery for maize and millet destined for traditional food applications. Moisture content thresholds for commercial eligibility exclude substantial smallholder harvest volumes from formal sector channels. Cooperatives with laboratory access are consolidating previously fragmented supplier bases to bypass traditional assembly markups.
Far North Region
Drought-tolerant millet cultivation serves niche brewing and animal feed channels with limited formal sector penetration. Input cost volatility from fertilizer and fuel price fluctuations compress margins for rotational grain producers. The Ministry of Trade's harmonized tariff structures within CEMEC open cross-border flows to Chad, privileging processors with integrated logistics.
Cameroon Grains Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated processors capturing formal sector volume and informal traders retaining household channel dominance. The vendor base organizes around three strategic archetypes: state-linked agricultural corporations with upstream land control, private contract farming aggregators with cooperative networks, and integrated miller-distributors with captive retail distribution. Competitive moves concentrate on backward integration into contract farming and port logistics capacity expansion.
Among Cameroon-based operators, Sodecoton exemplifies the state-linked agricultural corporation archetype through its cottonseed-derived grain rotations in northern belts. Crésus Agro occupies a position within the contract farming aggregator tier, anchoring smallholder networks into formal wholesale channels. T Choithram and Sons' Mahima SARL sits within the integrated miller-distributor category, competing through combined milling and retail distribution across coastal urban corridors.
| Leading Market Players |
|---|
| Cameroon Development Corporation |
| Sodecoton |
| Farms Solution |
| Crésus Agro |
| AIT Group |
| YFarmer |
| Ethos SARL |
| JMAO Business |
| T Choithram and Sons' Mahima SARL |
| Others |
Pricing and Supply Chain Analysis
ANASA's tightening mycotoxin thresholds gate both qualified supply and premium-tier pricing access, as processors lacking laboratory verification face disqualification from industrial buyer networks while compliant operators capture widening margin pools through certified offtake premiums.
Pricing Analysis
Short lead-time premiums reward processors with integrated drying and testing infrastructure that can deliver certified grain within compressed ANASA inspection cycles, while spot-market inventory trades at discounts due to chain-of-custody documentation gaps. Contract-based long-term offtake dominates formal sector procurement, with price differentiation hinging on certification grade and volume scale rather than brand premium. Pricing pressure stems from input cost volatility in northern growing belts, where fertilizer and fuel fluctuations compress rotational producer margins. Smallholder cooperatives exhibit highest price sensitivity due to working capital constraints, while integrated millers with captive supply chains demonstrate lowest sensitivity through backward-integrated sourcing.
Supply Chain Analysis
Freight cost differentials between coastal corridors and inland assemblies reshape procurement economics, favoring processors with port-adjacent infrastructure that minimizes transshipment markups. Geographic supply concentrates in Cameroon, Chad, and Central African Republic through CEMEC customs union flows, with raw material dependencies on cottonseed byproduct cycles, fertilizer imports, and fuel for mechanized post-harvest handling. Single-source vulnerability runs through Bamenda and Garoua wholesale assemblies that retain price-setting power over rural surplus. Distribution runs through contract farming networks displacing spot-market procurement as urban milling clusters tighten prequalification criteria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cameroon's grains sector is consolidating around compliance-capable processors as ANASA's accelerating inspection cycles force informal traders and undercapitalized cooperatives from formal buyer networks.
For Market Incumbents: Deepen backward integration into contract farming networks in the Centre Region to secure varietal purity and delivery scheduling specifications that brewing operations now mandate. Invest in on-site mycotoxin testing laboratories to preempt ANASA rejection penalties and capture premium-tier pricing access that disqualifies spot-market competitors. The threat of digital traceability mandates from industrial buyers demands blockchain-enabled provenance systems as a defensive necessity. For New Entrants and Emerging Players: Blockchain-enabled farm-gate verification systems offer a technology-first wedge into the parboiling segment, where rice's aflatoxin susceptibility creates steepest compliance ramps and incumbent capacity constraints. Target the Littoral Region's domestic rice processing investments, where import displacement redirects demand toward local supply chains lacking sufficient certified throughput. A go-to-market angle anchored in cooperative aggregation platforms with embedded laboratory access bypasses traditional wholesale markups. For Investors and Strategic Acquirers: ANASA's publication of revised mycotoxin thresholds is the leading indicator that processing investments with captive certification infrastructure will secure preferential offtake from formal sector buyers. The five-to-ten-year viability window favors acquisition targets with integrated port logistics in Douala corridors and existing cooperative networks that can scale to multi-year purchase agreement thresholds. Watch for CEMEC harmonized tariff implementation announcements as the signal for cross-border export channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | Secures varietal purity and delivery scheduling that Yaoundé millers now mandate. |
| On-Site Mycotoxin Testing Laboratory Investment | Preempts ANASA rejection penalties and qualifies processors for premium-tier pricing. |
| Blockchain-Enabled Provenance Tracking | Consolidates chain-of-custody documentation into unified compliance records. |
| Port Logistics Capacity Expansion | Positions coastal processors for CEMEC export eligibility to Gabon and Chad. |
| Cooperative Aggregation Platform Development | Bypasses Bamenda and Garoua wholesale markups through direct processor linkages. |
Research Methodology
Trade statistics from the Ministry of Trade, ANASA regulatory filings, and CEMEC customs documentation formed the secondary backbone, supplemented by primary interviews with flour milling procurement directors, cooperative aggregation managers, agricultural input distributors, and National Agency for Food Safety inspection officers. Bottom-up and top-down triangulation validated volume estimates across agro-ecological zones and distribution channels.
Bottom-up modeling anchored projections in segmented throughput across maize, rice, millet, and sorghum varieties, while top-down verification cross-checked against macroeconomic consumption trends and urbanization patterns. Segmentation dimensions included product type, distribution channel, end-user category, and processing method. CAGRs were derived from trend extrapolation of formalization rates and regulatory compliance adoption curves, with specific inputs from parboiling capacity expansion timelines and contract farming penetration trajectories.
Several conditions sit outside the modeled scope, including political instability in cross-border supply corridors, currency volatility within the CEMEC zone, and climate-induced yield variations in Sudano-Sahelian belts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Asia-Pacific Guar Market
Grains
Spain Rice Market
Grains
Millets Market
Grains
South Africa Maize Market
Grains
Paraguay Grains Market
Grains
Quinoa Flour Market
Grains
South America Wheat Market
Grains
Barley Market
Grains
United States Maize Market
Grains
Global Flour Market
Grains
Canada Pulses Market
Grains
Mesquite Flour Market
Grains
Grain-Based Flours Market
Grains
Chickpeas Market
Grains
Corn Silage Market
Grains
Gluten Free Ancient Grain Market