
 North America Rice Market | 2026-2036
North America Rice Market Size, Share, and Industry Trends Forecast 2026-2036
North America Rice Market Analytics
The North America rice market is realigning around a widening split between premium aromatic varieties and bulk commodity grades. Riceland Foods leverages its farmer-owned cooperative structure to dominate volume flows across the Mississippi Delta. Lotus Foods differentiates through organic and heirloom sourcing, while California Family Foods anchors premium medium-grain production in the Sacramento Valley.
Rice is a semi-aquatic cereal grain (Oryza sativa) processed to retain moisture content between 12% and 14% for stable storage and milling yield. Its primary commercial purpose centers on caloric staple supply for direct consumption, brewing, and processed food manufacturing. Long grain varieties lead volume throughput in retail and export channels, while jasmine and specialty aromatics command margin concentration in supermarkets and online platforms. Food service distribution sustains the fastest throughput expansion as restaurant chains standardize bowl-based menu formats.
The USDA Agricultural Marketing Service enforces official rice standards for grade, kernel size, and milling quality that govern interstate commerce and export eligibility. California's State Water Resources Control Board imposes agricultural water allocation limits that directly constrain planted acreage in the Central Valley. Stakeholders must monitor evolving state-level groundwater sustainability mandates and federal Farm Bill conservation provisions that will reshape planting economics and variety selection across the region.
Market Dynamics
California's State Water Resources Control Board allocation limits are compressing Sacramento Valley acreage while Gulf Coast growers expand long-grain output, creating a continental production split that favors water-secure regions.
Growth Catalysts
- USDA Grade Standards:Uniform interstate commerce rules enable seamless bulk transfers from Arkansas mills to Mexican importers and Caribbean food service distributors.
- Food Service Bowl Formats:Restaurant chains standardizing rice-based menu architectures pull volume through broadline distributors at contract scale.
- Ethnic Cuisine Penetration:Southeast Asian and Latin American cooking techniques spread through metropolitan culinary education channels, expanding aromatic variety demand.
Market Restraints
- Groundwater Sustainability Mandates:California's SGMA implementation layers pumping restrictions atop surface water cuts, raising per-acre cultivation costs in the Central Valley.
- Input Concentration Risk:Fertilizer and diesel supply chains anchor to Gulf Coast petrochemical corridors, exposing growers to energy price volatility.
- Substitution Pressure:Cauliflower rice and other vegetable-based alternatives capture calorie-conscious retail shelf space in premium urban markets.
Strategic Opportunities
- Underpenetrated Canadian Prairies:Saskatchewan's irrigation infrastructure expansion creates new temperate-zone production capacity for medium-grain varieties.
- Organic Certification Premiums:USDA Organic and California Certified Organic Farmers standards command 40-60% price lifts in direct-to-consumer channels.
- Direct E-Commerce Integration:Heirloom and single-origin varieties bypass traditional elevator systems through vertically integrated farm-to-door platforms.
Industry Challenges
- Specialized Milling Talent Scarcity:Kernel quality assessment and parboiling process control require apprenticeship pipelines that rural labor markets no longer supply.
- Multi-Jurisdictional Compliance Burden:California Proposition 65 warning requirements, FDA food facility registration, and Mexico's NOM standards create overlapping audit obligations for cross-border shippers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Rice Market |
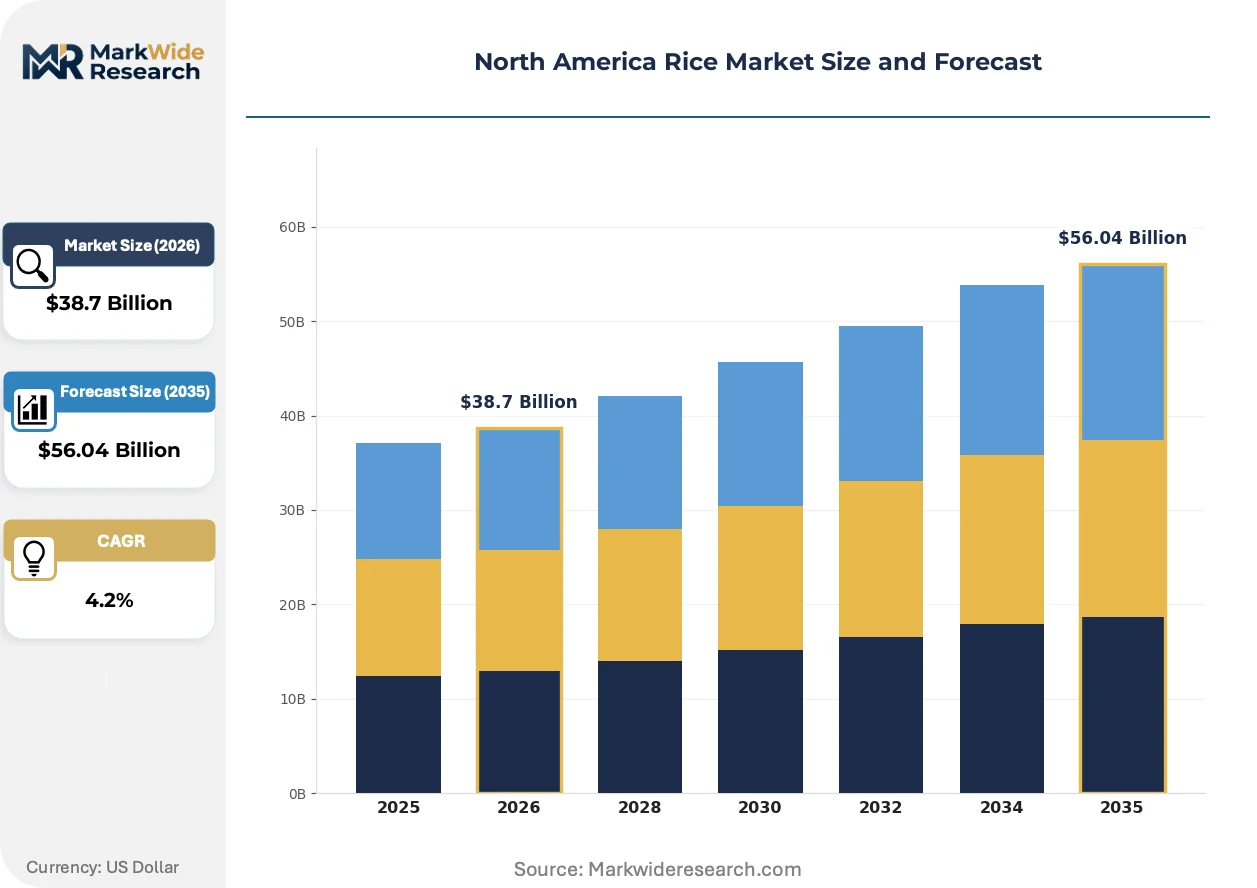
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Long Grain, Medium Grain, Short Grain, Jasmine End User: Food Service, Retail, Industrial, Export Distribution Channel: Online, Supermarkets, Wholesalers, Specialty Stores Packaging Type: Bulk, Retail Packs, Eco-Friendly, Bags |
| Companies Covered | Riceland Foods, Farmers' Rice Cooperative, California Family Foods, Riviana Foods Inc., Producers Rice Mill, SunFoods LLC, Lotus Foods, Gulf Pacific Rice Co., Inc., Blue Ribbon Rice, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Rice Market Evolving Landscape
Precision agriculture and varietal breeding programs are compressing the gap between commodity yields and specialty grade premiums, while water stress accelerates geographic production shifts.
Variable-rate irrigation systems paired with drone-mounted multispectral sensors are electrifying water-use efficiency in Texas and Louisiana rice operations. Large-scale cooperatives deploy these platforms to maintain yield consistency despite aquifer drawdown limits. The technology is electrifying margin preservation for growers facing tightening environmental constraints.
The USDA's updated grade standards for milled rice kernel integrity take effect across interstate commerce channels, forcing millers to upgrade optical sorting equipment. Arkansas and Mississippi processing facilities face six-figure capital outlays to maintain export eligibility. Medium-grain processors in California's Sacramento Valley accelerate compliance timelines to capture premium Japanese import contract windows.
Restaurant procurement teams now specify origin-verified aromatic varieties through broadline distributor portals rather than accepting commodity-grade substitutions. This specification discipline compresses spot-market participation by chain accounts. Texas and Florida food service markets exhibit the strongest contract commitment to single-source jasmine and basmati supply chains.
North America Rice Market Segmentation
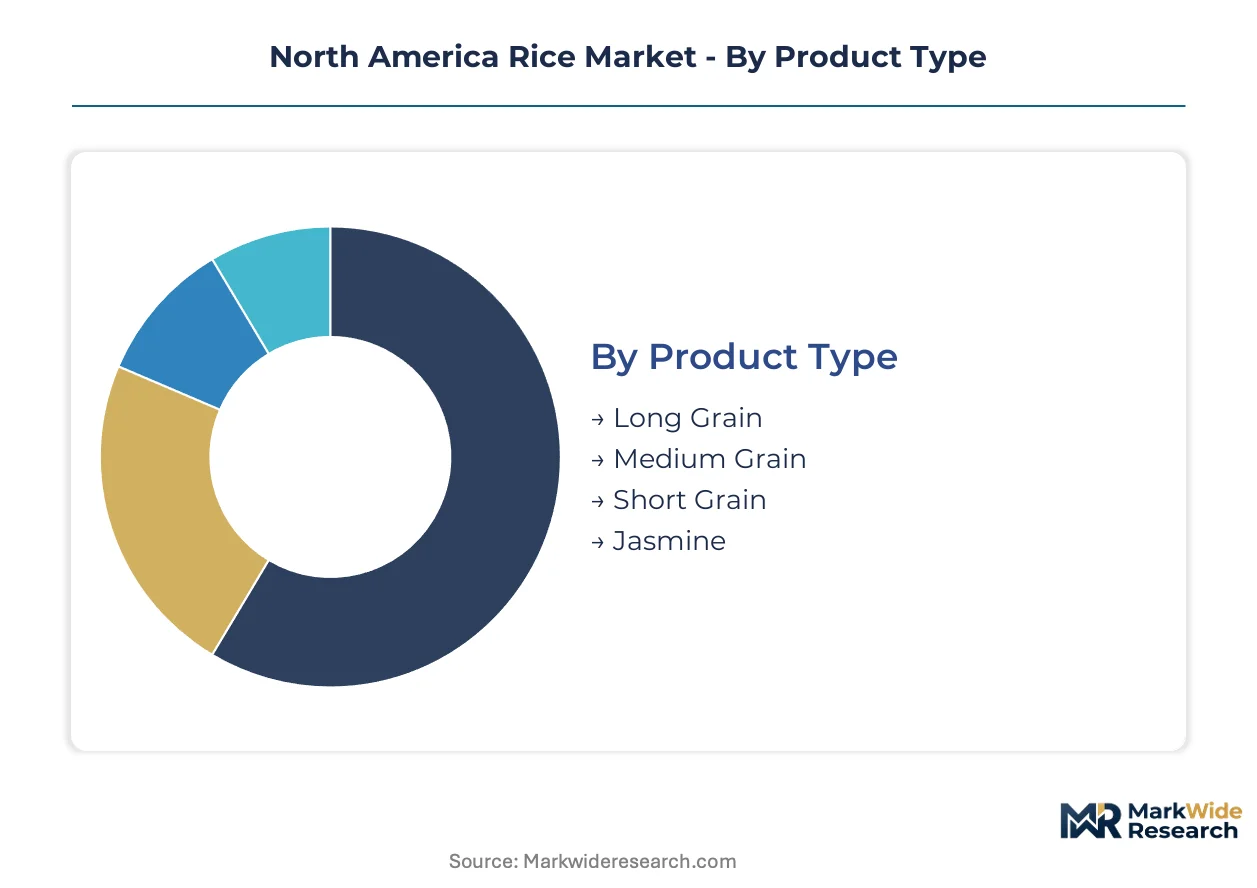
Rice segmentation in North America reflects divergent capital requirements across milling infrastructure, varietal breeding programs, and channel-specific packaging lines. Each dimension carries distinct investment thresholds that reshape competitive entry barriers and margin capture potential.
Product Type:
Capital intensity peaks with aromatic specialty varieties requiring dedicated breeding facilities and segregated milling streams, while commodity grades leverage shared infrastructure.
- Long Grain:High-amylose starch structure delivers fluffy, separate kernels after cooking. Gulf Coast food service distributors and Mexican export corridors pull the majority of volume, with Arkansas and Louisiana mills running dedicated parboiling lines to serve contract scale. Long grain absorbs the bulk of installed capacity; jasmine is expanding most quickly.
- Medium Grain:Higher moisture retention and stickier texture profile suit sushi applications and Spanish-style preparations. California's Sacramento Valley dominates production, where medium-grain varieties face water allocation constraints from the State Water Resources Control Board that limit acreage expansion despite Japanese import demand.
- Short Grain:Waxy, low-amylose composition creates dense, clingy texture prized for Korean and Japanese cuisine. California and limited Texas acreage supply niche demand through specialty distributors.
- Jasmine:Aromatic compound 2-acetyl-1-pyrroline delivers distinctive floral notes; Thai and US-sourced varieties compete in premium retail and food service channels.
Long grain commands the heaviest milling infrastructure investment; jasmine carries the steepest expansion trajectory.
End User:
Customer-type segmentation reveals divergent procurement patterns, with food service requiring volume consistency and retail demanding SKU proliferation.
- Food Service:Broadline distributors contract for grade-standardized bulk supply to power bowl-format menu architectures at restaurant chains. Procurement teams specify origin-verified aromatic varieties through distributor portals rather than accepting commodity substitutions.
- Retail:Supermarket and online channels demand packaging variety, organic certification options, and heritage storytelling that strain supply chain flexibility.
- Industrial:Brewers, cereal manufacturers, and processed food producers purchase milled rice and rice flour under tight specification tolerances for ingredient integration.
- Export:Caribbean and Central American buyers source US Gulf Coast supply under USDA grade standards; Mexican importers drive cross-border volume through NOM-compliant channels.
Food service channels concentrate procurement volume; retail is gaining share fastest through e-commerce expansion.
Distribution Channel:
Channel segmentation tracks the shift from traditional elevator systems toward direct consumer access and specialty curation.
- Online:Farm-to-door platforms and Amazon-scale marketplaces enable heirloom and single-origin varieties to bypass conventional grain handling infrastructure.
- Supermarkets:Mass retail chains demand national distribution, promotional support, and private label manufacturing capacity that favors large cooperative structures.
- Wholesalers:Broadline food service distributors consolidate volume from multiple mills to serve restaurant chain accounts under annual contracts.
- Specialty Stores:Asian grocers and organic retailers stock aromatic imports and heritage varieties with higher margin profiles but fragmented demand.
Supermarkets and wholesalers together move the majority of volume; online channels are climbing the fastest.
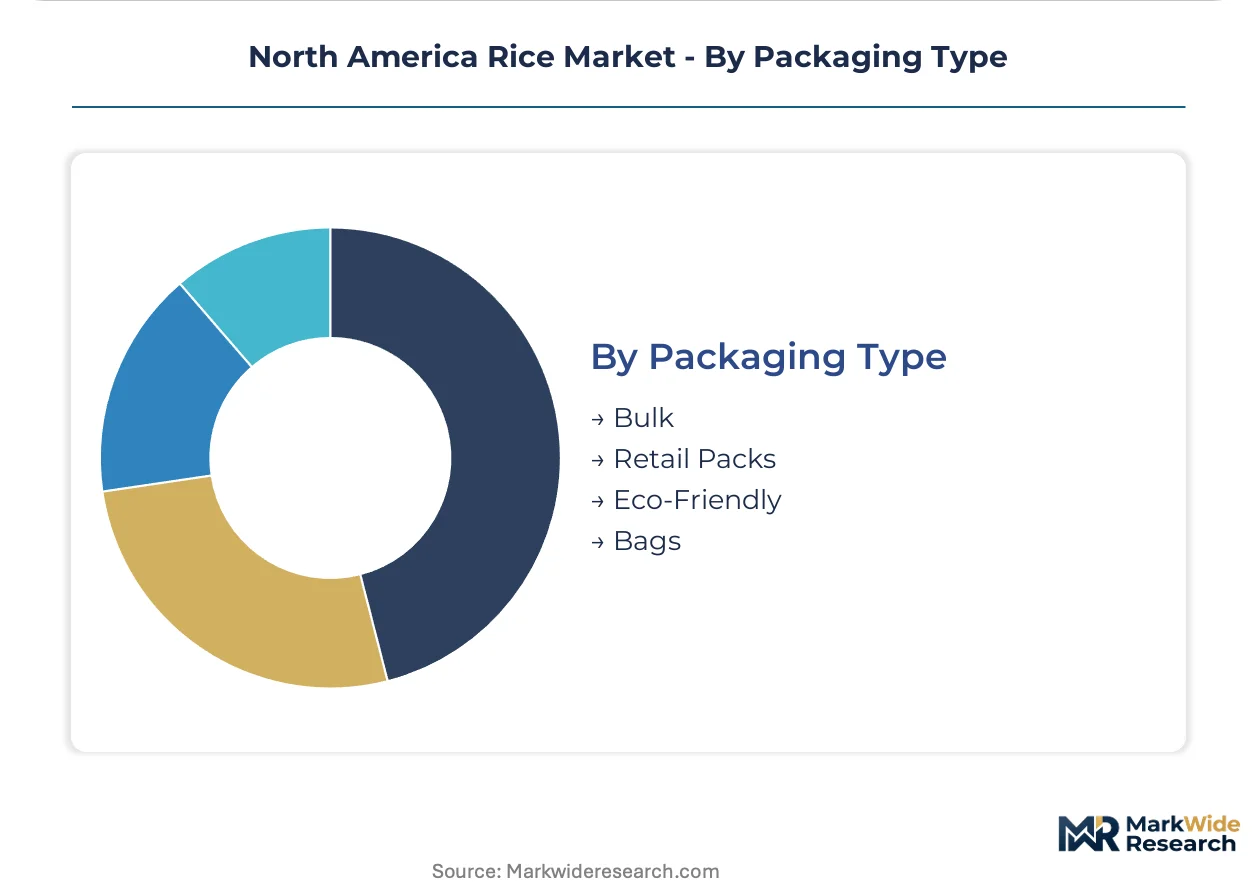
Packaging Type:
Packaging segmentation reflects diverging sustainability mandates and automation investment requirements across channel customers.
- Bulk:Railcar and truckload shipments to mills, brewers, and industrial processors minimize per-unit handling costs but require dedicated logistics contracts.
- Retail Packs:Two-pound to ten-pound bags, boxes, and pouches demand form-fill-seal automation and graphic design capabilities for shelf differentiation.
- Eco-Friendly:Compostable films, paper-based structures, and reduced-plastic formats respond to California Proposition 65 pressures and retailer sustainability scorecards.
- Bags:Traditional woven polypropylene and paper bags persist in ethnic retail and food service bulk purchasing.
Bulk and retail packs dominate current infrastructure; eco-friendly formats are gaining share fastest amid regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi Delta corridor spanning Arkansas and Louisiana anchors North American rice production volume, with Gulf Coast mills processing long-grain supply for domestic food service and Mexican export channels.
United States
Arkansas and Louisiana long-grain mills supply broadline distributors powering restaurant chain bowl-format menus. The USDA Agricultural Marketing Service enforces grade standards governing interstate commerce and export eligibility. The Mississippi Delta rice belt concentrates milling infrastructure where parboiling lines serve contract-scale procurement.
California
Japanese and Korean cuisine expansion drives medium-grain and short-grain demand through specialty distributors. The State Water Resources Control Board imposes agricultural water allocation limits that constrain Sacramento Valley planted acreage. Sacramento Valley processors accelerate optical sorting upgrades to capture premium Japanese import contract windows.
Canada
Saskatchewan's irrigation infrastructure expansion creates temperate-zone production capacity for medium-grain varieties targeting Asian cuisine segments. Health Canada and the Canadian Food Inspection Agency administer grain quality and safety standards. Prairie province growers test commercial viability of rice cultivation outside traditional North American belts.
Mexico
Cross-border importers source US Gulf Coast supply under NOM standards for domestic tortilla and brewing applications. The Secretariat of Economy oversees compliance with Mexico's Official Mexican Standards for grain imports. Northern border states concentrate rice handling infrastructure for redistribution to Central Mexican population centers.
Texas and Florida
Metropolitan food service markets in Houston and Miami exhibit strong contract commitment to single-source jasmine and basmati supply chains. State agriculture departments coordinate with the USDA on phytosanitary certification for interstate movement. Gulf Coast port facilities support Caribbean re-export activity from regional warehousing.
North America Rice Market Competitive Landscape
Premium-margin players sit above commodity-margin players across varietal specialization and channel access dimensions. The competitive structure organizes around farmer-owned cooperatives, integrated processors, and specialty importers. Three archetypes dominate: cooperative volume aggregators, premium heritage curators, and broadline distribution specialists. Capacity consolidation and direct e-commerce integration represent the dominant competitive moves reshaping participant positioning.
Within the cooperative archetype, Riceland Foods anchors farmer-owned aggregation across the Mississippi Delta. California Family Foods exemplifies premium medium-grain specialization tied to Sacramento Valley water-constrained acreage. Lotus Foods occupies a position within heritage and organic curation, sourcing aromatic varieties outside conventional elevator systems.
| Leading Market Players |
|---|
| Riceland Foods |
| Farmers' Rice Cooperative |
| California Family Foods |
| Riviana Foods Inc. |
| Producers Rice Mill |
| SunFoods LLC |
| Lotus Foods |
| Gulf Pacific Rice Co., Inc. |
| Blue Ribbon Rice |
| Others |
Value Network & Pricing Analysis
Backward integration into captive milling infrastructure anchors pricing power for cooperative processors across the Mississippi Delta. California's water-constrained Sacramento Valley operations command premium positioning through segregated medium-grain handling that commodity handlers cannot replicate.
Pricing Analysis
Yield-locked contract pricing governs long-grain procurement between Arkansas mills and broadline distributors serving restaurant chains. Price differentiation rests on USDA grade certification and organic accreditation tiers that separate commodity spot markets from Japanese import contract windows. Cost compression in standard-grade channels is intensifying because Gulf Coast petrochemical corridors expose growers to diesel and fertilizer volatility. Food service buyers exhibit the highest price sensitivity due to volume scale procurement, while direct-to-consumer organic channels show inelastic demand.
Supply Chain Analysis
USDA grade certification and NOM compliance requirements gate cross-border shipment eligibility for Mexican importers. Geographic concentration centers on Arkansas, Louisiana, and California, with Mississippi Delta mills drawing from water-secure aquifer regions. Raw material dependencies include diesel fuel, nitrogen fertilizers, and proprietary seed varieties. Single-source vulnerability runs through Gulf Coast petrochemical corridors. Distribution runs through farmer-owned cooperatives, broadline food service distributors, and direct e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California's State Water Resources Control Board allocations have created a supply-constrained environment where Sacramento Valley acreage limits prop medium-grain pricing premiums.
For Market Incumbents: Lock in water-secure acreage through long-term lease structures in Arkansas and Louisiana before groundwater sustainability mandates expand eastward. Defend against cauliflower rice substitution by accelerating organic certification pipelines that command 40-60% retail premiums. Prioritize optical sorting capital deployment to maintain Japanese export eligibility under updated USDA kernel integrity standards. For New Entrants and Emerging Players: Drone-mounted multispectral sensing platforms offer a technology-first wedge into precision agriculture services for water-stressed Texas and Louisiana operations. Target Saskatchewan's underdeveloped irrigation infrastructure for medium-grain production expansion. Pursue direct farm-to-door e-commerce integration for heirloom aromatic varieties bypassing traditional elevator systems. For Investors and Strategic Acquirers: Exit pathways concentrate in cooperative-to-integrated-processor rollup transactions across the Gulf Coast rice belt. Five-to-ten year viability favors operators with dual certification capacity for USDA Organic and California Certified Organic Farmers standards. Monitor State Water Resources Control Board allocation announcements as the critical inflection signal for Sacramento Valley production capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorting Equipment Upgrade | USDA kernel integrity standards force Arkansas and Mississippi mills into six-figure capital outlays for export eligibility. |
| Organic Certification Pipeline Expansion | California Certified Organic Farmers and USDA Organic tiers command substantial price lifts in direct-to-consumer channels. |
| Variable-Rate Irrigation Deployment | Drone-mounted multispectral sensors preserve margins for growers facing State Water Resources Control Board pumping limits. |
| Direct E-Commerce Platform Integration | Farm-to-door channels enable heirloom and single-origin varieties to bypass conventional grain handling infrastructure. |
| Saskatchewan Irrigation Infrastructure Development | Prairie province expansion creates temperate-zone production capacity for medium-grain varieties targeting Asian cuisine segments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cooperative procurement managers, food service distributor category heads, California agricultural water regulators, and Sacramento Valley mill operators combined with USDA Agricultural Marketing Service grade standard documentation, state water board allocation records, and cross-border customs flows. Bottom-up acreage and yield estimates triangulated against top-down consumption and trade data.
Reconciliation of production surveys, milling capacity registers, and channel shipment data shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include grain type, end-user category, distribution channel, and packaging format alongside water-stress regional classification. CAGRs derived from historical volume trajectories adjusted for regulatory constraint scenarios and varietal substitution patterns. Forecast inputs incorporated State Water Resources Control Board allocation trajectories and restaurant chain bowl-format menu expansion rates.
Several conditions sit outside the modeled scope, including extreme drought declarations, trade agreement renegotiations, and breakthrough alternative protein adoption curves. Forecasts reflect documented assumptions about water allocation stability and food service demand continuity. A model refresh is warranted upon material change in California groundwater sustainability mandate implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Africa Wheat Protein Market
Grains
Grain Silos and Storage System Market
Grains
Guar Complex Market
Grains
United States Maize Market
Grains
North America Oats Market
Grains
Europe Maize Market
Grains
Fortified Rice Market
Grains
Whole-Wheat Flour Market
Grains
Barley Market
Grains
North America Wheat Market
Grains
Bangladesh Rice Market
Grains
Global Quinoa Market
Grains
North America Wheat Protein Market
Grains
Pea Grits Market
Grains
Low Fat Rice Market
Grains
Oat Flour Market