
 Grain Handling Equipment Market | 2026-2036
Grain Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Grain Handling Equipment Market Insights
North American grain handling equipment manufacturers is rebalancing capacity toward automated control systems after years of supply chain strain on mechanical components. AGCO Corporation leverages its dealer network density across the US Midwest to sustain aftermarket parts revenue. Bühler Group anchors its position through backward integration into precision manufacturing of bucket elevator components. Sukup Manufacturing Co. specializes in galvanized grain dryers and occupies a dominant share of on-farm storage bin installations across Iowa and Illinois.
Grain handling equipment encompasses mechanical and pneumatic systems engineered to move, clean, dry, and store cereal crops at throughput rates ranging from 1,000 to 100,000 bushels per hour, with structural designs rated for wind loads up to 90 mph and seismic zones. These systems preserve germination rates, prevent mycotoxin accumulation, and enable just-in-time delivery to food processing and export terminals. Conveyors and bucket elevators generate the largest installed base revenue, while IoT-enabled wireless monitoring commands premium pricing due to predictive maintenance capabilities and remote diagnostics that reduce unplanned downtime. Grain dryers retain strong replacement demand in humid climates where moisture removal determines storage eligibility.
The US Department of Agriculture sets moisture content and sanitation standards that directly influence dryer specification and aeration system design, while OSHA regulates grain bin entry and dust explosion prevention through confined space protocols. The EPA governs particulate emissions from grain handling operations, pushing facilities toward pneumatic conveying upgrades and dust collection retrofits. Stakeholders must weigh capital allocation between expanding storage footprint and retrofitting existing elevators with sensor integration that satisfies both safety mandates and operational efficiency targets.
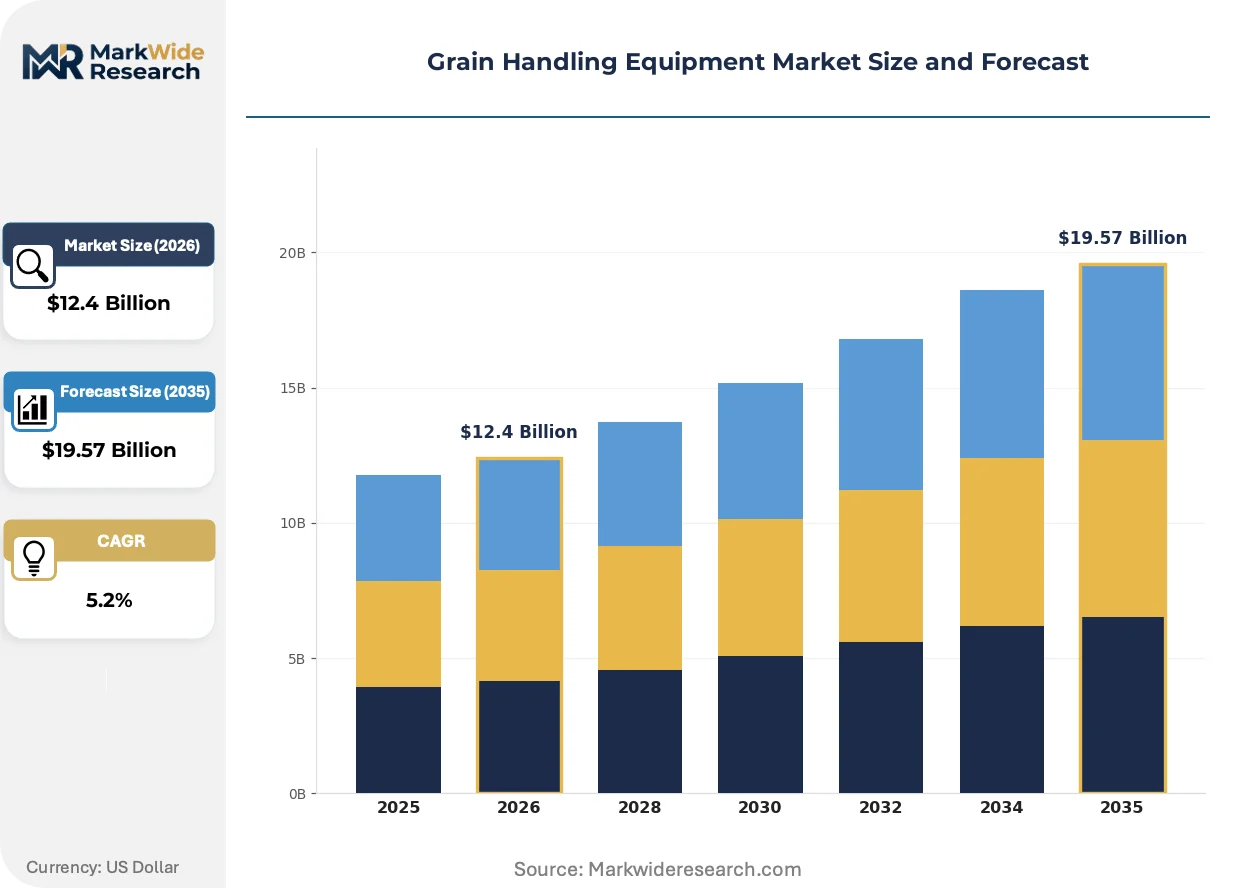
Market Dynamics
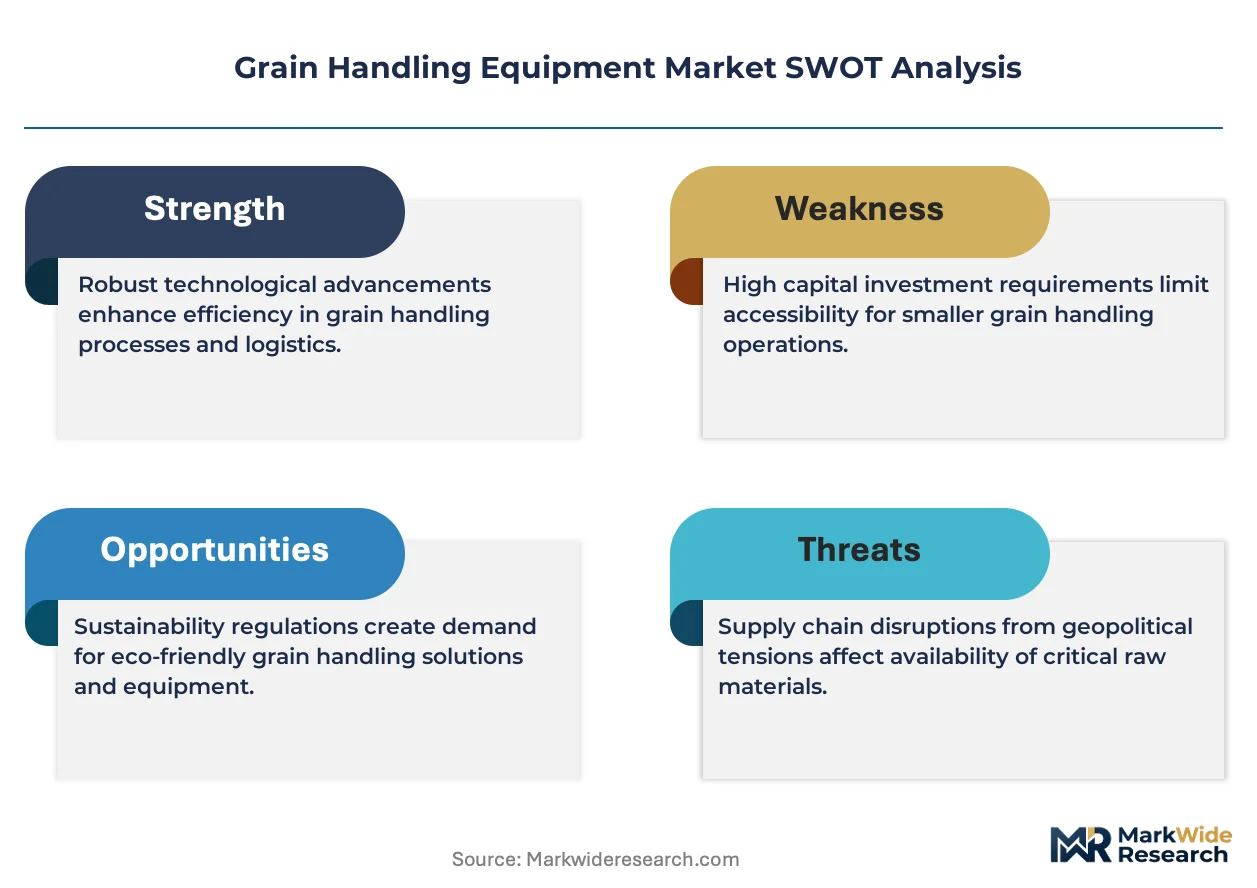
Elevator consolidation across the US Corn Belt is compressing replacement cycles for mechanical conveying systems while cooperatives prioritize IoT-enabled monitoring platforms that reduce unplanned downtime. This structural pressure favors vendors with captive manufacturing capacity over assembly-dependent competitors.
Growth Catalysts
- OSHA confined space protocols:Grain bin entry regulations mandate automated monitoring systems that eliminate human exposure, accelerating sensor deployment across commercial elevators in humid climate zones.
- On-farm storage expansion:Agricultural cooperatives in Iowa and Illinois are doubling bin capacity to capture basis spreads, driving demand for galvanized aeration systems and portable dryers.
- IoT predictive maintenance:Wireless vibration monitoring and remote diagnostics command premium pricing by reducing mechanical failure rates in bucket elevator drive trains.
Market Restraints
- Steel price volatility:Galvanized structural components represent 35-45% of equipment COGS, exposing manufacturers to scrap metal and zinc input cost swings.
- EPA particulate mandates:Dust collection retrofit requirements impose six-figure capital burdens on aging pneumatic conveying systems without production volume offsets.
- Technical limitation:Current wireless sensor networks face signal degradation in steel-reinforced concrete silos, limiting real-time monitoring effectiveness in large-diameter storage.
Strategic Opportunities
- Brazilian commercial elevator upgrades:Port terminal expansions in Paraná and Mato Grosso create demand for high-throughput bucket elevators rated for 100,000 bushels per hour.
- USDA moisture compliance automation:Integrated dryer-control systems that auto-adjust burners based on real-time grain moisture readings reduce labor oversight requirements.
- Sensor-to-ERP integration:Convergence of wireless IoT networks with farm management software platforms enables predictive inventory positioning and forward-contract optimization.
Industry Challenges
- Electro-mechanical technician scarcity:Rural elevator operators struggle to recruit personnel capable of servicing variable-frequency drive systems and PLC-based control architectures.
- Legacy pneumatic integration:Retrofitting dust-collection systems onto 1970s-era conveying lines requires custom fabrication that extends project timelines and inflates installation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain Handling Equipment Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $19.57 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyors, Bucket Elevators, Air Legs, Grain Cleaners, Grain Dryers, Mechanical Conveyors Technology: Automated Control Systems, Sensor Integration, Pneumatic Conveying, Mechanical Conveying, Wireless Monitoring, IoT Enabled Application: Post-Harvest Processing, Storage Facilities, Processing Plants, Feed Manufacturing, Seed Treatment, Bulk Material Handling End User: Agricultural Cooperatives, Grain Elevators, Feed Mills, Research Institutions, Commodity Traders, Agricultural Dealers |
| Companies Covered | AGCO Corporation, Bühler Group, Sukup Manufacturing Co., AGI, Cimbria A/S, GSI, BROCK Grain Systems, PETKUS Technologie GmbH, Symaga, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain Handling Equipment Market Trends and Innovations
Automation is penetrating deeper into grain handling workflows, compressing the gap between mechanical reliability and data-driven operational control. Equipment specifications now prioritize interoperability with farm enterprise software over standalone durability metrics.
Wireless sensor networks are absorbing maintenance responsibilities previously assigned to scheduled mechanical inspections. Large commercial elevators in Nebraska and Kansas are deploying vibration-monitoring arrays on bucket elevator head sections within eighteen-month replacement windows. This technology is absorbing capital that elevator operators previously allocated to redundant mechanical spares.
EPA dust emission thresholds are forcing pneumatic system upgrades across older US facilities. Facilities must install baghouse collectors or transition to enclosed belt conveyors to maintain operating permits. The regulatory pressure falls heaviest on 1980s-vintage elevators in Illinois and Indiana, where replacement economics favor full system overhaul over incremental retrofit.
Cooperative procurement committees now require five-year total cost of ownership models that factor energy consumption and predicted maintenance labor. Traditional capital-expenditure approval processes are giving way to lifecycle-based vendor selection frameworks. This behavioral shift is most visible among multi-facility cooperatives in Minnesota and the Dakotas, where central engineering staffs standardize equipment specifications across dozen-site networks.
Grain Handling Equipment Market Segmentation
Grain handling equipment segmentation reflects divergent procurement logics across mechanical reliability, digital integration, and operational scale. Equipment buyers prioritize throughput specifications, moisture control precision, and interoperability with farm management platforms when allocating capital across these categories.
Product Type:
Mechanical specifications determine equipment selection based on throughput requirements, crop fragility, and facility layout constraints.
- Conveyors:Belt and drag-chain configurations handle 10,000 to 50,000 bushels per hour across horizontal and inclined transport paths. Demand concentrates in Nebraska and Kansas elevator retrofits where enclosed belt designs replace legacy open-air systems to satisfy EPA dust emission thresholds.
- Bucket Elevators:Vertical lifting systems with urethane or steel buckets achieve heights exceeding 150 feet at throughputs up to 100,000 bushels per hour. Brazilian port terminals in Paraná and Mato Grosso drive specification upgrades for high-capacity leg systems serving export corridors.
- Air Legs:Pneumatic vertical conveyors utilize high-velocity air streams to lift grain through enclosed tubes, reducing mechanical wear on fragile seed stocks.
- Grain Cleaners:Screening and aspiration systems remove foreign material and dockage prior to storage or sale, with oscillating sieve designs dominating US Corn Belt installations.
- Grain Dryers:Continuous-flow and batch drying systems reduce moisture content from 25% to 15% for safe storage, with automated burner controls commanding premium pricing in humid climates.
- Mechanical Conveyors:Screw and drag conveyors handle intermediate distances at lower capital cost, serving on-farm storage expansions across Iowa and Illinois.
Bucket elevators lead on scale; grain dryers lead on momentum.
Technology:
Cost tiers separate basic mechanical systems from digitally integrated platforms with predictive capabilities.
- Automated Control Systems:PLC-based architectures coordinate dryer burners, conveyor sequencing, and aeration fans through centralized HMI interfaces. Agricultural cooperatives in Minnesota and the Dakotas mandate five-year TCO models that factor energy optimization and labor reduction.
- Sensor Integration:Hardwired temperature, moisture, and CO2 probes enable real-time grain condition monitoring. Signal degradation in steel-reinforced concrete silos limits effectiveness in large-diameter US facilities exceeding 100-foot diameters.
- Pneumatic Conveying:Vacuum and pressure systems transport grain through enclosed pipelines, eliminating dust emissions but consuming 40% more energy than mechanical alternatives.
- Mechanical Conveying:Traditional belt, chain, and screw mechanisms dominate installed base revenue due to lower operating cost and simpler maintenance protocols.
- Wireless Monitoring:Battery-powered vibration and temperature sensors transmit data via LoRaWAN or cellular networks, reducing unplanned downtime in bucket elevator drive trains.
- IoT Enabled:Cloud-connected platforms integrate sensor networks with ERP and farm management software, enabling predictive inventory positioning across multi-site cooperative networks.
Mechanical conveying dominates installed value; IoT-enabled platforms are expanding most quickly.
Application:
Volume concentration varies across facility types with divergent throughput requirements and regulatory exposure.
- Post-Harvest Processing:Field-to-elevator receiving, cleaning, and initial drying operations handle seasonal harvest surges. USDA moisture compliance mandates drive automation investment at commercial elevators.
- Storage Facilities:Aerated bin systems and flat storage structures preserve grain quality over 6-18 month cycles. On-farm expansion across Iowa and Illinois doubles bin capacity to capture basis spreads.
- Processing Plants:Food and ethanol facilities require sanitary design standards and continuous feed reliability.
- Feed Manufacturing:Batch mixing operations demand precise ingredient metering and contamination prevention protocols.
- Seed Treatment:Coating and conditioning equipment handles high-value germplasm with fragility-sensitive handling systems.
- Bulk Material Handling:Port and rail terminal operations prioritize throughput maximization over conditioning precision.
Storage facilities lead on scale; post-harvest processing leads on automation intensity.
End User:
Customer type determines procurement sophistication, with cooperatives and commercial elevators driving technology adoption.
- Agricultural Cooperatives:Multi-facility networks in the US Corn Belt standardize specifications across dozen-site footprints. Central engineering staffs require sensor-to-ERP integration and lifecycle-based vendor selection frameworks.
- Grain Elevators:Commercial facilities face OSHA confined space mandates and EPA dust regulations. Automated monitoring systems eliminate human bin entry while maintaining operating permits.
- Feed Mills:Continuous production schedules prioritize equipment reliability and rapid parts availability.
- Research Institutions:University and government breeding programs require small-batch handling with traceability documentation.
- Commodity Traders:Merchandising firms prioritize throughput velocity and inventory visibility for forward-contract optimization.
- Agricultural Dealers:Equipment retailers influence on-farm purchasing decisions through financing packages and installation services.
Grain elevators lead on capital deployment; agricultural cooperatives lead on standardization pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturers are arbitraging regulatory compliance costs by shifting fabrication capacity toward jurisdictions with lower environmental enforcement intensity while maintaining sales presence in high-standard markets. This geographic stratification shapes regional competitive dynamics.
United States
Elevator consolidation across Iowa and Illinois drives replacement demand for bucket elevators and enclosed belt conveyors. OSHA confined space protocols mandate automated bin monitoring systems that eliminate human entry. The Corn Belt corridor from Omaha to Des Moines concentrates retrofit activity at cooperative facilities upgrading 1980s-vintage pneumatic systems.
Brazil
Port terminal expansions in Paraná and Mato Grosso create demand for high-throughput handling systems serving soybean export corridors. ANVISA sanitation standards influence equipment specification for food-grade grain flows. The Matopiba region anchors new elevator construction as agricultural frontier expansion accelerates.
Germany
Engineering-intensive component fabrication concentrates in Baden-Württemberg and Bavaria, serving EMEA aftermarket demand for precision-manufactured elevator buckets and drive assemblies. REACH chemical regulations constrain coating and surface treatment options for galvanized structural steel. Stuttgart-based fabricators supply retrofit kits for aging EU storage facilities.
Canada
Prairie province grain handlers face Canadian Grain Commission moisture compliance mandates that drive dryer automation investment. The Red River Valley from Winnipeg to Fargo anchors cross-border equipment procurement patterns. Manitoba and Saskatchewan cooperatives prioritize aeration system upgrades to extend storage cycles through variable harvest conditions.
Australia
Wheat belt storage operators from New South Wales to Western Australia confront extreme weather volatility that accelerates replacement cycles for outdoor handling equipment. Biosecurity protocols under the Department of Agriculture mandate cleaning system specifications that prevent weed seed contamination. Port terminals in Queensland handle growing export volumes to Southeast Asian feed markets.
Grain Handling Equipment Market Competitive Landscape
North American producers anchor the high-volume tier; European specialists hold the precision-component segment. The vendor base separates into three strata: integrated conglomerates with captive distribution networks, regional fabricators serving cooperative procurement committees, and component specialists supplying OEM aftermarket channels. Consolidation pressure favors manufacturers with backward integration into steel fabrication over assembly-dependent competitors. Two dominant competitive moves are emerging: captive manufacturing capacity expansion to offset steel price volatility, and technology licensing partnerships to embed IoT capabilities without internal R&D burden.
Within the integrated conglomerate tier, AGCO Corporation and Bühler Group occupy positions defined by geographic footprint density and manufacturing control depth. AGCO exemplifies the dealer-network-dependent archetype, leveraging aftermarket parts availability to sustain revenue across replacement cycles. Bühler represents the precision-manufacturing specialist, with backward integration into bucket elevator component fabrication. Sukup Manufacturing Co. anchors the regional-fabricator category, occupying a dominant position in on-farm storage installations across the US Corn Belt. These three patterns—network scale, manufacturing depth, and regional specialization—structure competitive positioning across procurement segments.
| Leading Market Players |
|---|
| AGCO Corporation |
| Bühler Group |
| Sukup Manufacturing Co. |
| AGI |
| Cimbria A/S |
| GSI |
| BROCK Grain Systems |
| PETKUS Technologie GmbH |
| Symaga |
| Others |
Pricing and Supply Chain Analysis
Agricultural cooperatives in Minnesota and the Dakotas anchor pricing power through lifecycle-based procurement frameworks that favor vendors offering five-year total cost of ownership models over upfront equipment discounts. This buyer concentration compresses margins for assembly-dependent manufacturers while rewarding backward-integrated suppliers capable of absorbing steel price volatility through captive fabrication capacity.
Pricing Analysis
Distributor margins on replacement parts sustain aftermarket revenue streams that offset cyclical equipment sales. Pricing stratifies across premium IoT-enabled platforms with predictive maintenance capabilities, standard automated control systems, and economy-tier mechanical conveyors without sensor integration. Cost compression in the standard tier is intensifying as Brazilian port terminal operators demand high-throughput specifications at Midwest price benchmarks. Cooperative procurement committees exhibit lowest price sensitivity for wireless monitoring systems that reduce unplanned downtime, while on-farm storage buyers prioritize capital efficiency in aeration system selection.
Supply Chain Analysis
Refurbishment flows for bucket elevator components create secondary supply channels that compete with OEM aftermarket pricing. Manufacturing concentration centers on the US Midwest, Germany, and Brazil, with Baden-Württemberg fabricators supplying precision-machined drive assemblies to EMEA retrofit markets. Galvanized structural steel and zinc coating inputs draw from scrap metal markets and primary zinc smelters, exposing fabricators to commodity price swings. Single-source vulnerability concentrates in urethane bucket molding capacity controlled by a limited supplier base. Distribution runs through dealer networks anchored by AGCO's Midwest density and direct sales channels serving Brazilian port authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment manufacturers can arbitrage regulatory compliance costs between EPA-mandated US facilities and ANVISA-regulated Brazilian operations, exploiting divergent dust emission enforcement intensity to optimize fabrication location against end-market pricing power.
For Market Incumbents: Lock in captive supply of galvanized structural components to neutralize steel price volatility that erodes assembly-dependent competitors. Expand precision manufacturing capacity in Baden-Württemberg to serve EMEA aftermarket demand for elevator bucket retrofits. Defend against IoT-enabled entrants by embedding wireless monitoring into base equipment configurations rather than premium tiers. For New Entrants and Emerging Players: E-commerce parts platforms offer direct channel access to rural elevator operators frustrated by dealer network delays. Target the Matopiba agricultural frontier in Brazil where new elevator construction outpaces established vendor relationships. Lead with portable dryer systems for on-farm storage expansion in Iowa and Illinois, bypassing cooperative procurement committees that favor incumbent brands. For Investors and Strategic Acquirers: Agricultural conglomerates with grain merchandising operations are the most active acquirer in this space, seeking vertical integration into handling infrastructure. Mid-cap fabricators with backward integration into steel fabrication represent the most defensible acquisition profile over a multi-year holding period. Monitor OSHA enforcement intensity around confined space protocols as the signal for accelerated sensor deployment capital expenditure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Fabrication | Captive supply of galvanized components insulates margin from zinc price volatility. |
| IoT Platform Licensing Partnership | Cloud connectivity integration satisfies cooperative ERP requirements without internal R&D burden. |
| Brazilian Port Terminal Expansion | High-throughput bucket elevator installations capture soybean export corridor growth. |
| Aftermarket Parts Distribution Network | Dealer density across the Corn Belt sustains revenue between equipment replacement cycles. |
| Automated Dryer Control Development | USDA moisture compliance automation reduces labor oversight at commercial elevators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with grain elevator operations managers, cooperative procurement directors, OEM aftermarket service heads, and agricultural equipment dealers with secondary validation against USDA harvest statistics, EPA enforcement databases, Brazilian ANVISA sanitation filings, and customs trade data for steel and zinc inputs. Bottom-up equipment shipment tracking and top-down agricultural production modeling provided triangulation across the analysis window.
Segment-weighting approaches distributed volume and value across product type, technology tier, application intensity, and end-user procurement sophistication dimensions. CAGRs derived from regression analysis against harvest volume projections, replacement cycle compression rates, and regulatory mandate implementation timelines. Forecast inputs incorporated cooperative capital expenditure survey data and Brazilian port authority infrastructure disclosure patterns.
Steel price volatility, OSHA enforcement intensity shifts, and wireless sensor network reliability breakthroughs are the dominant revision risks that could alter equipment demand trajectories. Practitioners should monitor galvanized steel futures pricing, confined space fatality incident rates, and LoRaWAN signal penetration trials in large-diameter silos for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Pulp Wash Equipment Market
Agricultural Processing Equipment
Vegetable Dicing Machines Market
Agricultural Processing Equipment
Solar Herbs Dryer Market
Agricultural Processing Equipment
Harvesting Machinery Market
Agricultural Processing Equipment
India Rice Milling Market
Agricultural Processing Equipment
Rice Milling Machines Market
Agricultural Processing Equipment
Solar Powered Agricultural Dryer Market
Agricultural Processing Equipment
Global Egg Processing Market
Agricultural Processing Equipment
Harvesting Equipment Market
Agricultural Processing Equipment
Asia-Pacific Meat Processing Equipment Market
Agricultural Processing Equipment
Egg Processing Machine Market
Agricultural Processing Equipment
Rotary Drum Dryers Market
Agricultural Processing Equipment
Meat Processing Equipment Market
Agricultural Processing Equipment
Rice Polishing Machines Market
Agricultural Processing Equipment
Global Dry Milling Market
Agricultural Processing Equipment
Cashew Processing Machine Market