
 North America Grain Oriented Electrical Steel Market | 2026-2036
North America Grain Oriented Electrical Steel Market Size, Share, and Industry Trends Forecast 2026-2036
North America Grain Oriented Electrical Steel Market Analytics
Core loss optimization services is reshaping how value migrates from commodity sheet sales to technical partnerships in the North America Grain Oriented Electrical Steel Market. Nippon Steel Corporation leverages its ultra-low-loss Hi-B technology to command premium positioning among North American transformer OEMs. Cleveland-Cliffs Inc. anchors regional supply security through its integrated US steelmaking footprint and electrical steel finishing investments. ArcelorMittal dominates import channels with European-sourced grain-oriented grades calibrated to IEEE and CSA specifications.
Grain-oriented electrical steel is a silicon-alloyed ferromagnetic material, typically containing 3-3.5% silicon, manufactured through precise hot rolling and secondary recrystallization to achieve a Goss texture with magnetic flux density above 1.88 T. This microstructural alignment minimizes hysteresis and eddy current losses, making it indispensable for laminated transformer cores and large generator applications where energy efficiency determines operational economics. The grain-oriented steel segment leads absolute volume due to irreplaceable performance in power transformers above 10 MVA, while laminated steel configurations capture expanding share in modular renewable energy step-up stations. Epoxy-coated variants concentrate margin pools where utilities specify 30-year service life in coastal or humid environments.
The US Department of Energy enforces minimum efficiency standards under 10 CFR 431 that effectively mandate high-permeability grain-oriented grades for new distribution transformers. Canada's Natural Resources Canada administers parallel MEPS regulations through its Energy Efficiency Regulations, while NEMA and IEEE 1106 define core loss testing protocols that differentiate market access tiers. CSA C802.2 in Canada adds harmonization complexity for cross-border equipment procurement. Stakeholders must monitor how amendments to transformer efficiency rules in Washington and Ottawa redirect procurement specifications toward next-generation domain-refined grades.
Market Dynamics
The US Department of Energy's 10 CFR 431 efficiency mandates are compressing transformer design cycles and forcing OEMs toward domain-refined grain-oriented grades that slash core losses below legacy Hi-B thresholds.
Growth Catalysts
- 10 CFR 431 Efficiency Standards:DOE mandates for distribution transformers eliminate conventional grain-oriented grades from new procurement specifications, creating immediate pull for ultra-low-loss material across US utilities.
- Grid Modernization Investment:Transmission operators in Texas, California, and the Great Lakes corridor are replacing aging transformer fleets with high-efficiency units that specify premium core steel.
- Renewable Integration:Wind and solar step-up substations require compact, high-flux-density cores that only advanced grain-oriented grades can deliver at 10 MVA+ ratings.
Market Restraints
- Silicon Metal Price Volatility:Ferrosilicon input costs swing with Chinese export quotas and energy prices, compressing mill margins on fixed-price utility contracts.
- Single-Source Supply Risk:North American finishing capacity concentrates in Indiana and Ohio, creating geographic vulnerability to weather or logistics disruptions.
- Amorphous Metal Substitution:Distribution transformers below 5 MVA face competitive pressure from amorphous ribbon cores that achieve lower no-load losses in specific duty cycles.
Strategic Opportunities
- Canadian Hydroelectric Expansion:Quebec and British Columbia utility procurements for remote transmission tie-ins specify 30-year service life cores that favor epoxy-coated grain-oriented grades.
- Infrastructure Resilience Programs:FEMA and state-level hardening grants for coastal substations prioritize corrosion-resistant laminated configurations with extended warranties.
- Digital Core Design Services:Finite-element modeling partnerships between steel suppliers and transformer OEMs are creating recurring revenue streams beyond commodity sheet sales.
Industry Challenges
- Domain-Refined Process Expertise:Secondary recrystallization furnace control requires metallurgists with 15+ years of Goss texture optimization experience, a shrinking talent pool.
- IEEE 1106 Certification Timelines:Third-party core loss verification for new grade introductions extends 18-24 months, delaying revenue recognition on R&D investments.
- Legacy Transformer Integration:Utilities operating mixed fleets of 1970s-1990s vintage units face spare parts mismatches when upgrading to metric-dimensioned modern cores.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Grain Oriented Electrical Steel Market |
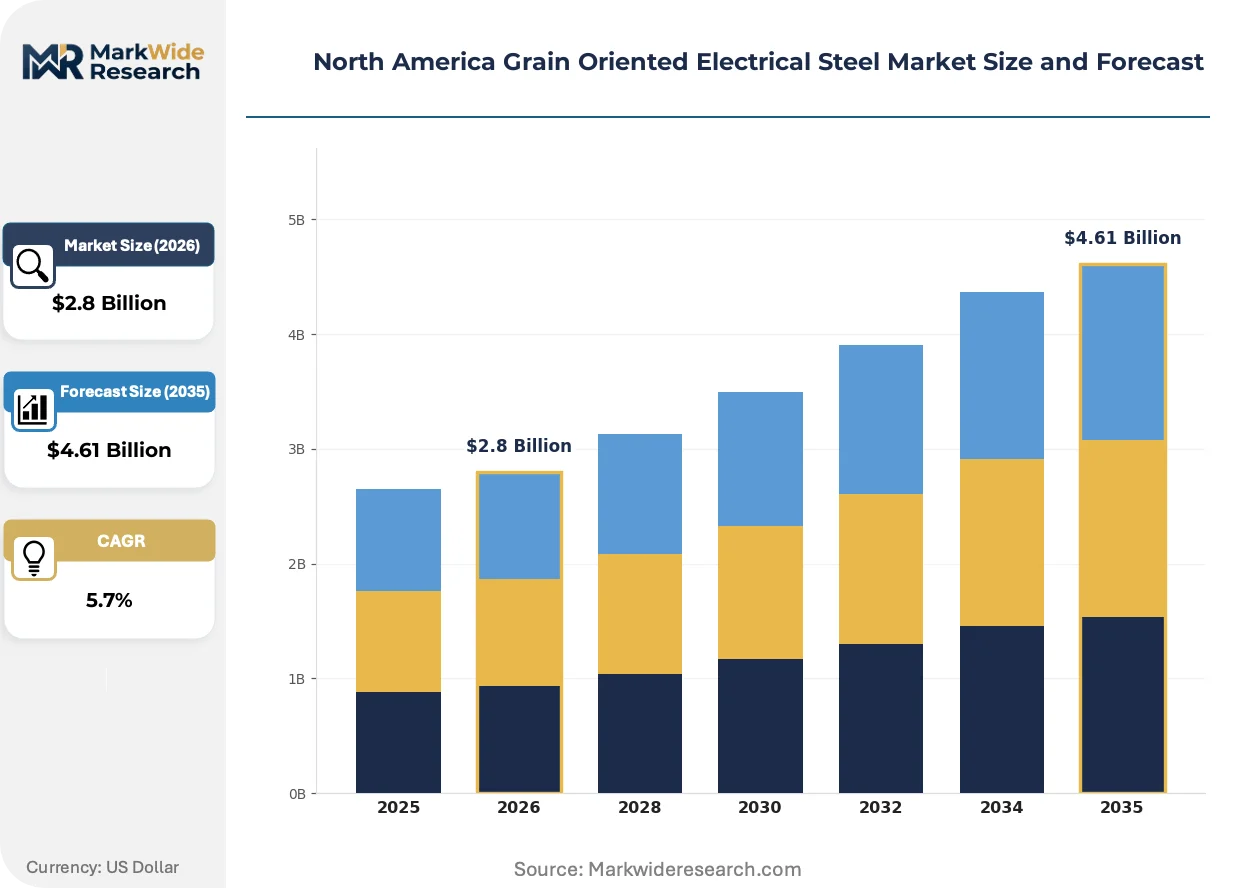
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Oriented Steel, Grain-Oriented Steel, Laminated Steel, Coated Steel End User: Power Transformers, Motors, Generators, Inductors Coating Type: Silicon Coated, Epoxy Coated, Zinc Coated, Others Application: Electrical Equipment, Renewable Energy, Industrial Machinery, Home Appliances |
| Companies Covered | ArcelorMittal, Nippon Steel Corporation, Cleveland-Cliffs Inc., Aperam SA, POSCO International Corporation, United States Steel Corporation, Thyssenkrupp AG, Tempel Steel, AK Steel Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Grain Oriented Electrical Steel Market Evolving Landscape
Technical differentiation is migrating from material specifications to integrated core design partnerships that lock in multi-year supply agreements through performance guarantees rather than spot pricing.
Laser-scribed domain-refined grain-oriented steel is collapsing the performance gap between conventional Hi-B grades and experimental amorphous alternatives in distribution transformers above 2.5 MVA. Midwestern utilities including Ameren and DTE Energy are specifying laser-etched cores for new substation installations. The technology is collapsing price premiums for entry-level ultra-low-loss grades as process yields improve at integrated US mills.
Canada's Natural Resources Canada is tightening MEPS alignment with US DOE standards through amendments to Energy Efficiency Regulations that remove grandfathering provisions for imported distribution equipment. Cross-border transformer OEMs must now dual-certify core grades to CSA C802.2 and IEEE 1106 protocols simultaneously. Ontario-based manufacturers are responding by consolidating testing partnerships with accredited labs in Toronto and Chicago to compress approval timelines.
Utility procurement departments are unbundling core steel sourcing from finished transformer contracts, creating direct mill-OEM-utility tri-party agreements that specify loss guarantees over 30-year service lives. This pattern displaces traditional tier-one transformer OEMs as sole procurement gatekeepers. The shift is most visible in California IOU solicitations where Pacific Gas & Electric and Southern California Edison now require steel supplier disclosure in bid documentation.
North America Grain Oriented Electrical Steel Market Segmentation
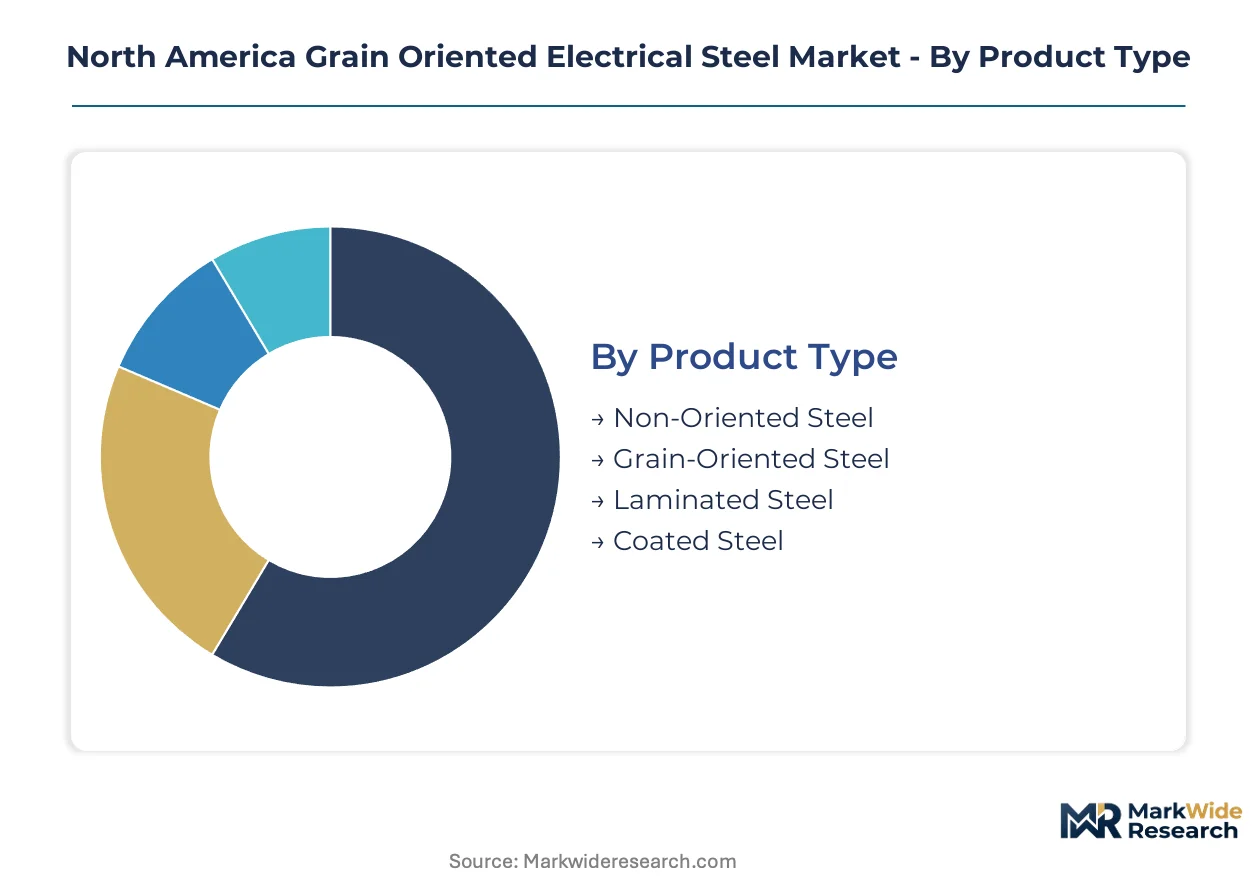
Grain-oriented electrical steel markets fragment across technical specifications, end-use requirements, and protective coating systems. Each segmentation dimension carries distinct procurement protocols, certification standards, and margin structures that reshape supplier-OEM relationships across the United States and Canada.
Product Type:
Transformer OEMs specify steel grades along a performance-cost spectrum that spans legacy commodity grades through domain-refined ultra-low-loss material.
- Grain-Oriented Steel:Silicon-alloyed ferromagnetic material with 3-3.5% silicon content, manufactured through secondary recrystallization to achieve Goss texture alignment above 1.88 T magnetic flux density. US Great Lakes transformer OEMs concentrate procurement for power applications above 10 MVA where core loss minimization determines operational economics.
- Laminated Steel:Thin-gauge sheets stacked and bonded into core assemblies that reduce eddy current losses through insulation between layers. Texas and California renewable step-up substations specify laminated configurations for compact high-flux-density designs in wind and solar integration projects.
- Non-Oriented Steel:Isotropic magnetic properties suit rotating machinery applications where flux direction varies continuously during operation.
- Coated Steel:Surface-treated variants provide enhanced corrosion resistance for coastal and humid environment installations.
The dominant share belongs to Grain-Oriented Steel, while Laminated Steel is closing the gap fastest.
End User:
Customer segments align with equipment scale, duty cycle intensity, and regulatory efficiency mandates that differentiate procurement specifications.
- Power Transformers:Transmission and distribution infrastructure above 10 MVA rating constitutes the primary demand sink. US Department of Energy 10 CFR 431 efficiency standards mandate domain-refined grades for new distribution transformer procurement, eliminating conventional Hi-B material from utility specifications.
- Generators:Large rotating electrical machines for utility-scale power generation require high-permeability core steel with precise magnetic anisotropy. Canadian hydroelectric expansion in Quebec and British Columbia specifies 30-year service life cores that favor premium grain-oriented grades with extended warranties.
- Motors:Industrial drive systems and commercial equipment utilize non-oriented and grain-oriented grades depending on efficiency tier and size class.
- Inductors:Power conditioning and filtering equipment in grid modernization projects specify specialized core geometries with controlled magnetic properties.
Power Transformers command the largest volume position, though Generators is expanding most quickly on hydroelectric and grid resilience investment.
Coating Type:
Surface protection systems segment by environmental exposure severity, service life requirements, and total cost of ownership calculations.
- Epoxy Coated:Thermoset polymer barrier delivers superior moisture and chemical resistance for 30-year service life specifications. FEMA and state-level infrastructure hardening grants for coastal US substations prioritize epoxy-coated laminated configurations with corrosion-resistant warranties.
- Silicon Coated:Inorganic surface treatment provides electrical insulation between laminations with thermal stability exceeding organic alternatives. Standard specification for interior transformer applications in controlled environments across Midwestern manufacturing corridors.
- Zinc Coated:Sacrificial corrosion protection for outdoor or partially exposed core assemblies in harsh climate zones.
- Others:Specialized ceramic and hybrid coating systems for extreme duty cycles and custom OEM specifications.
Epoxy Coated holds the premium positioning, while Silicon Coated maintains the broadest adoption base.
Application:
Downstream demand clusters around equipment replacement cycles, renewable integration timelines, and industrial electrification trajectories.
- Electrical Equipment:Distribution transformers, switchgear, and grid infrastructure replacement dominates current procurement. Ameren and DTE Energy Midwestern utilities specify laser-scribed domain-refined cores for new substation installations under grid modernization programs.
- Renewable Energy:Wind and solar step-up substations require compact high-flux-density cores at 10 MVA+ ratings that advanced grain-oriented grades deliver. California IOU solicitations from Pacific Gas & Electric and Southern California Edison now require steel supplier disclosure in bid documentation.
- Industrial Machinery:Manufacturing equipment and process automation drives demand for motor and inductor-grade material.
- Home Appliances:High-efficiency residential transformers and power supplies utilize thinner-gauge non-oriented and grain-oriented grades.
Electrical Equipment anchors absolute volume, with Renewable Energy gaining share fastest on interconnection queue backlogs and IRA-driven project finance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated steelmaking capacity clusters around the Great Lakes manufacturing corridor, with finishing operations concentrating in Indiana and Ohio. This geographic configuration creates supply security advantages for transformer OEMs while exposing the market to localized logistics disruptions.
United States
US utilities are replacing aging transformer fleets under grid modernization programs spanning Texas, California, and the Great Lakes corridor. The Department of Energy's 10 CFR 431 efficiency mandates eliminate conventional grain-oriented grades from new distribution transformer procurement. Cleveland and Pittsburgh anchor electrical steel finishing investments that supply regional OEM clusters.
Canada
Quebec and British Columbia hydroelectric expansion drives procurement for remote transmission tie-ins requiring 30-year service life cores. Natural Resources Canada is tightening MEPS alignment with US DOE standards through amendments to Energy Efficiency Regulations. Toronto-based manufacturers are consolidating testing partnerships with accredited labs to compress dual-certification timelines.
Mexico
Cross-border manufacturing integration positions northern border states as emerging assembly locations for export-oriented transformer production. Mexican energy reform implementation is accelerating utility procurement of high-efficiency distribution equipment. Monterrey and Tijuana industrial corridors are attracting coil winding and core assembly investments serving North American demand.
North America Grain Oriented Electrical Steel Market Competitive Landscape
Integrated steel producers and specialized electrical steel finishers split the market between captive supply security and import flexibility. The vendor base concentrates around three strategic archetypes: domestic integrated mills with finishing capacity, Asian exporters with ultra-low-loss technology, and European traders with specification-calibrated import channels. Competitive dynamics center on capacity expansion in the US Midwest and strategic partnerships between steel suppliers and transformer OEMs.
Within the integrated mill tier, Cleveland-Cliffs Inc. and United States Steel Corporation anchor regional supply security through captive US steelmaking footprints. Nippon Steel Corporation represents the technology-licensing archetype with advanced domain-refined process expertise. ArcelorMittal occupies the import-channel position with European-sourced grades calibrated to IEEE and CSA specifications.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nippon Steel Corporation |
| Cleveland-Cliffs Inc. |
| Aperam SA |
| POSCO International Corporation |
| United States Steel Corporation |
| Thyssenkrupp AG |
| Tempel Steel |
| AK Steel Holdings Corporation |
| Others |
Value Network & Pricing Analysis
Indiana and Ohio finishing corridors concentrate North American electrical steel capacity, granting integrated mills leverage over transformer OEMs locked into long-term offtake agreements. This geographic concentration amplifies pricing power during periods of ferrosilicon cost volatility or logistics disruption.
Pricing Analysis
Service and technical partnership revenue now drives lifetime value beyond commodity sheet transactions. Three-tier pricing structure across domain-refined, Hi-B, and conventional grades stratifies by core loss performance and IEEE 1106 certification tier. Cost compression in entry-level ultra-low-loss segments is intensifying because laser-scribing process yields are improving at US mills. Municipal utilities exhibit highest price sensitivity due to fixed capital budgets, while coastal IOUs prioritize performance guarantees over unit cost.
Supply Chain Analysis
Extended payment terms from integrated mills to ferrosilicon suppliers are tightening working capital cycles across the value chain. Primary production draws from the United States, Japan, and South Korea, with finishing operations concentrated in the Great Lakes corridor. The supply chain rests on ferrosilicon, high-purity iron ore, and specialized refractory materials. Single-source vulnerability at Indiana and Ohio finishing facilities exposes the market to weather-related disruption. Distribution runs through direct mill-OEM contracts with emerging tri-party utility involvement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DOE efficiency mandates are compressing transformer design cycles and forcing material substitution toward ultra-low-loss grades, creating a high-growth disruption window for suppliers with domain-refined capability.
For Market Incumbents: Insulate core margins by securing captive ferrosilicon supply through backward integration into silicon metal processing. Add finishing capacity in the Great Lakes corridor to reduce geographic concentration risk. Amorphous metal substitution in sub-5 MVA distribution transformers threatens volume in legacy grade tiers.
For New Entrants and Emerging Players: Build out digital core design services partnerships with regional transformer OEMs to capture recurring revenue beyond commodity sales. White-space exists in epoxy-coated grades for FEMA-funded coastal hardening projects. Target Canadian hydroelectric expansion in Quebec and British Columbia where 30-year service life specifications favor premium material.
For Investors and Strategic Acquirers: Long-term, this sits as a regulated infrastructure play because grid modernization investment and efficiency mandate tightening create durable demand tailwinds. Acquisition candidates include specialized electrical steel finishers with IEEE 1106 certification capabilities and established utility relationships. Watch for amendments to 10 CFR 431 or Canadian MEPS regulations as signals of accelerated grade migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrosilicon Supply | Cleveland-Cliffs and US Steel are securing captive silicon metal to insulate margins from Chinese export quota volatility. |
| Domain-Refined Capacity Expansion | Midwest mills are adding secondary recrystallization furnace capacity to meet DOE 10 CFR 431 ultra-low-loss grade demand. |
| Dual-Certification Testing Partnerships | Toronto manufacturers are consolidating CSA C802.2 and IEEE 1106 lab relationships to compress cross-border approval timelines. |
| Digital Core Design Service Launch | Nippon Steel is deploying finite-element modeling partnerships that lock in multi-year supply agreements through performance guarantees. |
| Epoxy-Coated Grade Production Scale-Up | Integrated mills are expanding surface treatment capacity to capture FEMA infrastructure hardening grant demand in coastal states. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement and secondary source validation. Primary interviews covered transformer OEM procurement directors, utility planning engineers, electrical steel mill metallurgists, and FERC regulatory specialists. Secondary sources included EIA electricity distribution data, DOE 10 CFR 431 rulemaking dockets, NEMA shipment statistics, IEEE standards documentation, and SEC filings from integrated steel producers. Bottom-up volume modeling triangulated against top-down grid investment forecasts.
Forecast inputs incorporated product type segmentation across grain-oriented, laminated, and coated grades; end-user categories spanning power transformers, generators, and renewable step-up stations; and coating systems differentiated by environmental exposure severity. CAGRs were derived from regression analysis of historical utility capital expenditure patterns and projected efficiency mandate compliance timelines across the analysis window. Ferrosilicon price elasticity and transformer OEM inventory cycle assumptions shaped year-to-year trajectory modeling.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Asian exporters or breakthrough amorphous metal cost reductions would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Europe Metal Service Centers Market
Metals
Cold Drawn Wire Market
Metals
Electrodeposited Copper Foil Market
Metals
Precious Metals Wire Market
Metals
Ultrafine Tungsten Wire for Medical Applications Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
Galvanized Steel Market
Metals
Global Hot Rolled Coil Steel Market
Metals
Aluminum Hot Rolling Mill Market
Metals
TMCP Steel Market
Metals
High Purity Pig Iron Market
Metals
Nickel Powder Plating Market
Metals
Global Ultra Fine Copper Powder Market
Metals
Global Flat Carbon Steel Market
Metals
US and Mexico Stainless Steel Market
Metals
Molybdenum Market