
 Rhodium Market | 2026-2036
Rhodium Market Size, Share, and Industry Trends Forecast 2026-2036
Rhodium Market Analysis
Automotive OEM procurement is expanding across both legacy manufacturers and emerging EV hybrid platforms, fragmenting historically concentrated buyer pools. Anglo American PLC leverages integrated Bushveld mining assets to sustain upstream rhodium supply control. Johnson Matthey Plc anchors global autocatalyst fabrication capacity through proprietary washcoat technologies. Umicore differentiates via closed-loop recycling infrastructure that recovers platinum-group metals from spent automotive catalysts.
Rhodium is a silvery-white platinum-group metal with atomic number 45, melting point 1,964°C, and exceptional catalytic activity for nitrogen oxide reduction in exhaust streams. Its primary commercial purpose centers on automotive emission control, where even trace loadings dramatically enhance NOx conversion efficiency. Metallic rhodium commands premium pricing in autocatalyst formulations, while rhodium compounds supply electronics manufacturers depositing thin-film resistors and electrical contacts. Rhodium alloys occupy specialized niches in high-temperature thermocouples and glass-fiber production equipment where oxidation resistance proves critical.
EPA Tier 3 and Euro 7 regulations tighten permissible NOx and particulate thresholds, directly amplifying rhodium intensity per gasoline and hybrid powertrain. South Africa's Department of Mineral Resources and Energy oversees licensing in the Bushveld Complex, while the EU's Critical Raw Materials Act classifies rhodium as strategically important, accelerating stockpiling mandates and recycling investment. Stakeholders must monitor how hybrid vehicle production volumes and hydrogen fuel-cell catalyst formulations redistribute rhodium demand across propulsion technologies.
Market Dynamics
Automotive emission control dominates rhodium consumption, with regulatory loadings per vehicle rising faster than powertrain diversification can offset, concentrating demand volatility in a single end-use vertical.
Growth Catalysts
- EPA Tier 3 mandates:United States gasoline vehicle producers must achieve lower NOx thresholds, expanding rhodium washcoat intensity per catalytic converter.
- Hybrid powertrain proliferation:Toyota and Hyundai hybrid platforms retain internal combustion architectures, preserving autocatalyst demand even as battery-electric volumes rise.
- Bushveld Complex geology:South Africa's Merensky and UG2 reef formations host the world's richest rhodium-bearing platinum-group metal ore bodies.
Market Restraints
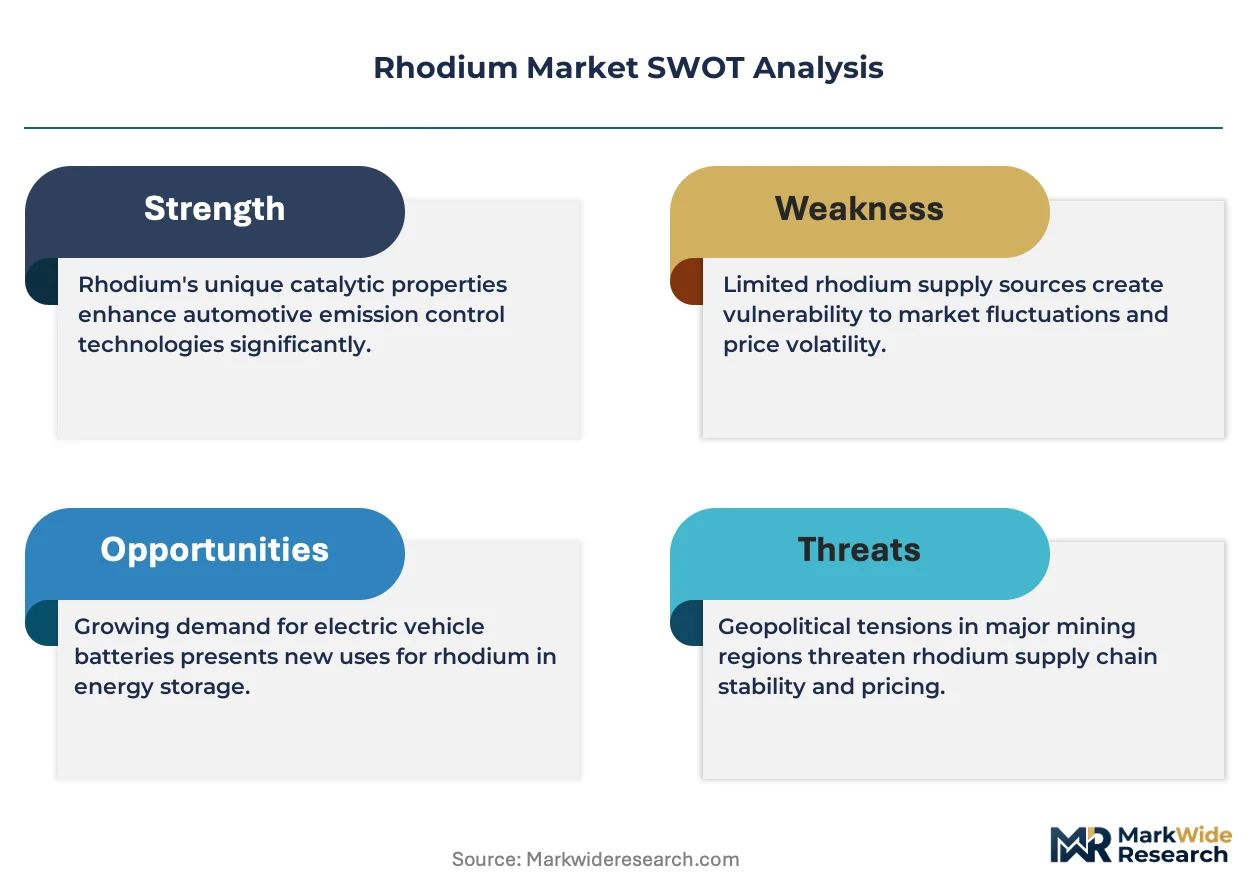
- Supply concentration risk:South Africa's Department of Mineral Resources and Energy controls licensing for over eighty percent of primary rhodium extraction capacity.
- Substitution pressure:Palladium-gold alloys and base-metal zeolite formulations threaten rhodium's NOx reduction monopoly in cost-sensitive vehicle segments.
- Input cost volatility:Mining depth below two kilometers in the Bushveld Complex amplifies energy and labor cost exposure for rhodium producers.
Strategic Opportunities
- EU Critical Raw Materials Act stockpiling:Brussels mandates strategic platinum-group metal reserves, creating guaranteed offtake for certified producers.
- Hydrogen fuel-cell catalysts:Proton-exchange membrane electrolyzers require platinum-rhodium coatings for durability in high-current-density operation.
- Closed-loop recycling infrastructure:Umicore and Johnson Matthey are expanding pyrometallurgical recovery from spent automotive catalysts in Belgium and the United Kingdom.
Industry Challenges
- Deep-level mining expertise scarcity:Bushveld operators face retirements among blast-hole stoping engineers with thirty-plus years of narrow-reef extraction experience.
- Washcoat formulation IP complexity:Proprietary ceria-zirconia-rhodium dispersion patents held by catalyst fabricators create licensing friction for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rhodium Market |
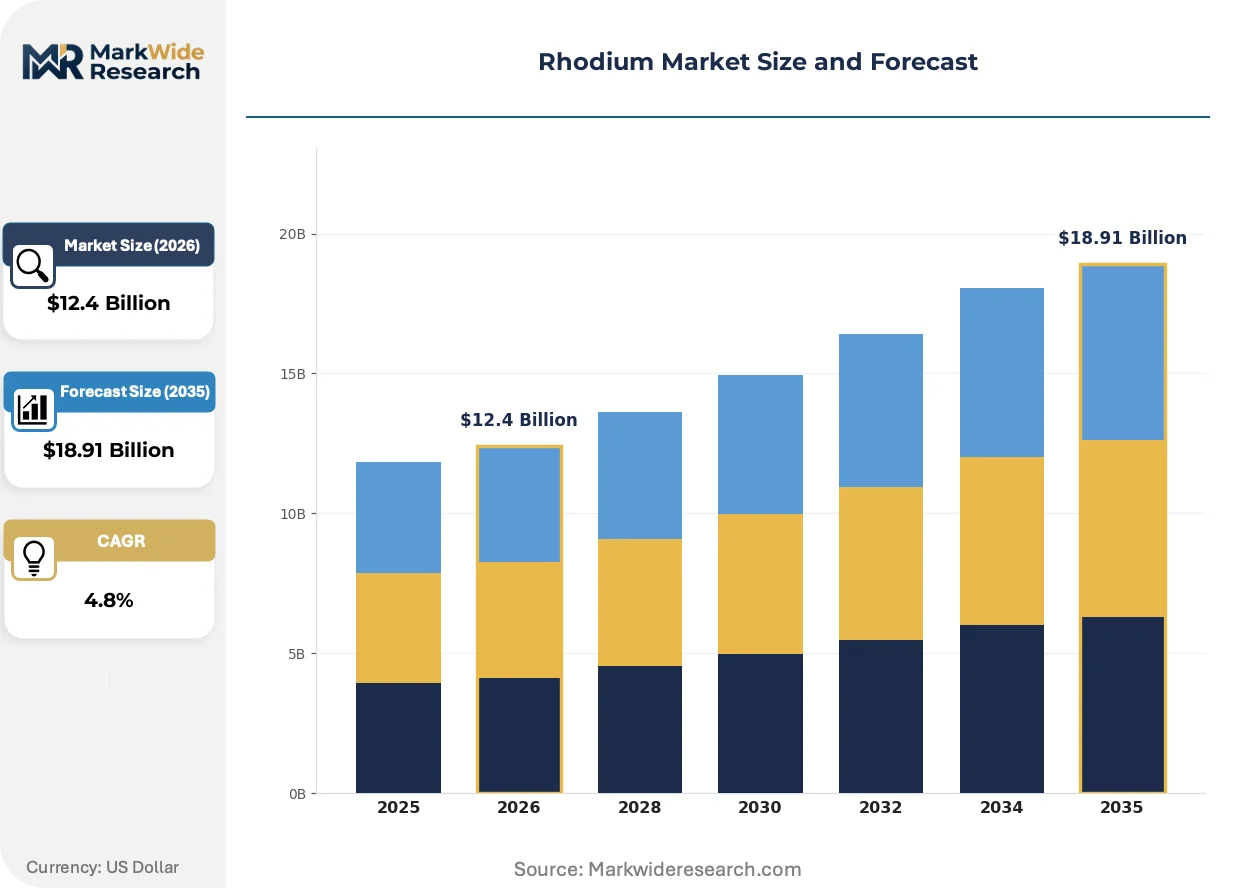
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.91 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic Rhodium, Rhodium Alloys, Rhodium Compounds, Rhodium Coating Application: Catalytic Converters, Electronics, Jewelry, Electroplating Form: Granules, Powder, Sheets, Bars End User: Automotive Industry, Electronics Manufacturers, Jewelry Makers, Chemical Sector |
| Companies Covered | Johnson Matthey Plc, Umicore, Anglo American PLC, African Rainbow Minerals Limited, Norilsk Nickel, Impala Platinum Holdings Limited, Heraeus Holding GmbH, Northam Platinum Holdings Limited, Sibanye Stillwater Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rhodium Market Emerging Trajectories
Tri-metal catalyst architectures are compressing the traditional platinum-palladium-rhodium hierarchy, while regulatory loadings and recycling economics reshape upstream investment priorities.
Advanced tri-metal formulations is unifying platinum, palladium, and rhodium in single-layer washcoats that optimize precious metal efficiency across temperature ranges. Ford and Stellantis have adopted these architectures for Euro 7-compliant gasoline engines. The technology is unifying previously separate catalyst bricks into compact modular units, reducing converter volume and rhodium gram-per-vehicle variance.
REACH authorization requirements for nickel compounds are tightening precursor chemical sourcing for rhodium electroplating used in electronics thin-film deposition. ECHA's 2024 sunset date for certain nickel salts forces resistor manufacturers toward alternative electrolyte formulations. German and Austrian plating houses are accelerating rhodium sulfate bath conversions to maintain CE-marked component supply.
Long-term offtake contracting is displacing spot-market purchasing among European automotive OEMs seeking supply security for Euro 7 ramp-up. Tier-1 catalyst suppliers like Umicore now structure five-year fixed-volume agreements with Bushveld miners, transferring price risk downstream. This pattern is most visible in Germany, where Volkswagen Group and Mercedes-Benz have locked rhodium supply through 2029.
Rhodium Market Segmentation
Rhodium procurement decisions pivot on purity specifications, form factor logistics, and end-use catalytic performance requirements. Automotive OEMs dominate volume flows, yet electronics and chemical applications command premium pricing for specialized compounds and coatings.
Product Type:
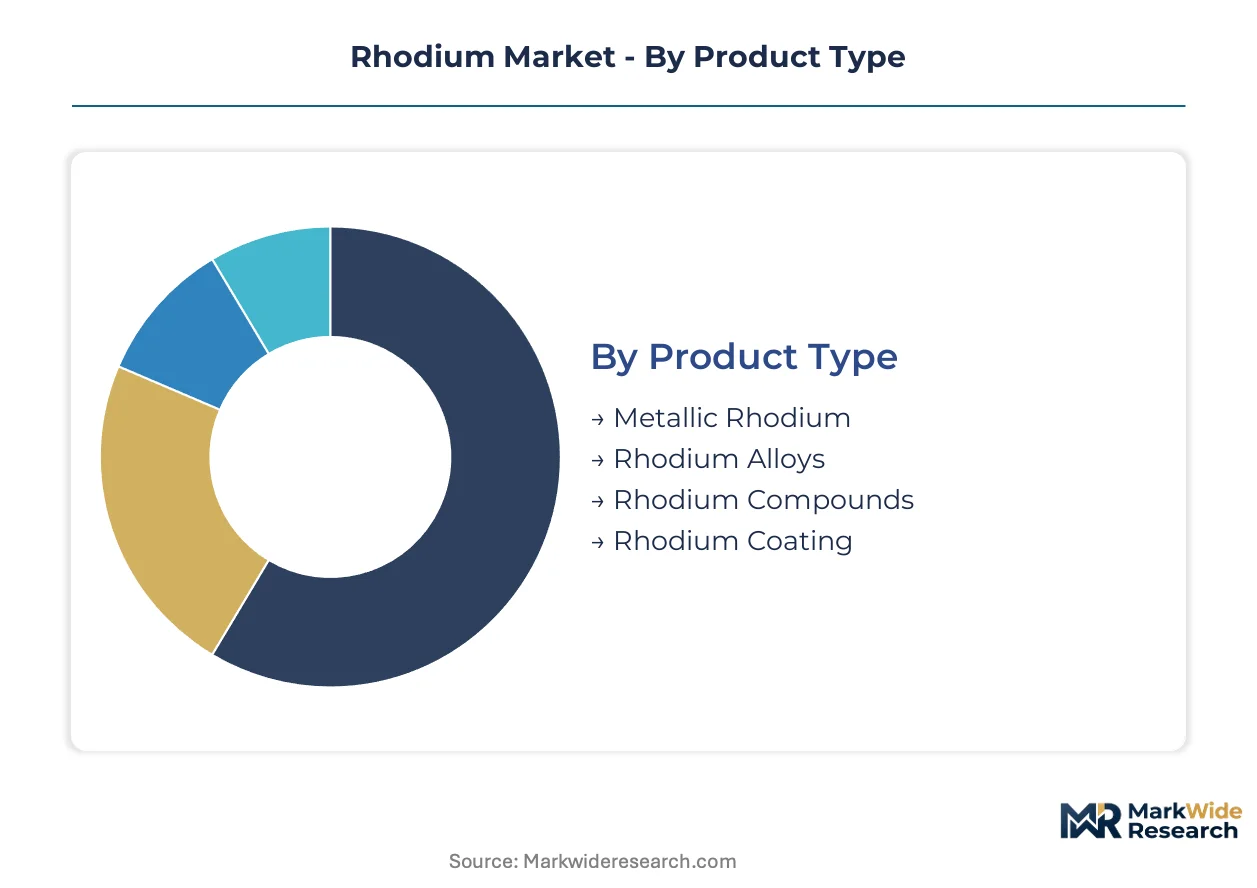
Buyers select rhodium product types based on downstream processing requirements and purity thresholds, with metallic forms commanding premium positioning for autocatalyst fabrication.
- Metallic Rhodium:High-purity ingots and sponge serve as feedstock for autocatalyst washcoat deposition and investment holdings. Automotive catalyst fabricators in Germany and Japan source metallic rhodium for direct dissolution into nitric acid solutions. EPA Tier 3 compliance timelines are accelerating metallic rhodium offtake from South African refiners.
- Rhodium Alloys:Binary and ternary formulations with platinum or palladium enhance high-temperature stability in thermocouple applications and glass-fiber bushings. Glass manufacturing clusters in the Czech Republic and Italy specify rhodium-platinum alloys for molten glass handling equipment. Alloy demand concentrates where oxidation resistance exceeds pure metal performance limits.
- Rhodium Compounds:Chloride, nitrate, and sulfate salts enable electroplating baths and chemical synthesis precursors. Electronics manufacturers in South Korea deposit rhodium thin films from sulfate electrolytes for resistor applications.
- Rhodium Coating:Electrodeposited and chemical vapor deposition layers provide wear-resistant surfaces for electrical contacts and optical reflectors. Plating houses in Austria convert nickel-salt processes to rhodium sulfate systems under REACH authorization pressures.
Volume sits with Metallic Rhodium; growth tilts toward Rhodium Compounds for electronics deposition.
Application:
Application selection tracks regulatory stringency and manufacturing process requirements, with emission control mandates creating divergent intensity profiles across vehicle powertrain categories.
- Catalytic Converters:Washcoat formulations incorporate rhodium at 0.2-2.0 gram loadings per gasoline vehicle to achieve NOx reduction efficiency above 90%. Euro 7 and EPA Tier 3 standards are expanding rhodium intensity per converter even as hybrid architectures preserve internal combustion demand.
- Electronics:Thin-film resistors, electrical contacts, and connector platings exploit rhodium's low electrical resistance and tarnish resistance. German and Japanese electronics manufacturers specify rhodium coatings for high-reliability automotive sensor applications.
- Jewelry:Electroplated rhodium provides reflective white finishes over white gold and silver substrates. Italian and Indian jewelry fabrication centers utilize rhodium flashing for premium positioning.
- Electroplating:Functional coatings for scientific instruments and semiconductor processing equipment require precise thickness control. Belgian plating specialists serve aerospace and medical device specifications.
Catalytic Converters absorb the dominant volume share; Electronics plating applications are climbing the fastest as sensor miniaturization intensifies.
Form:
Form factor procurement aligns with melting equipment capabilities and batch processing economics, with granule and powder formats dominating industrial-scale consumption.
- Granules:Standardized 1-5mm spheroidal particles optimize induction furnace feeding for alloy production and investment casting. Bushveld refiners package granules for European autocatalyst fabricators seeking consistent dissolution rates.
- Powder:Sub-micron and micron-sized particulates enable sintering, powder metallurgy, and chemical synthesis pathways. Additive manufacturing research programs in the United States evaluate rhodium powder for high-temperature component fabrication.
- Sheets:Rolled foil and strip stock supply thermocouple junction fabrication and specialized electrical contacts. Japanese precision metalworkers specify rhodium sheet for thin-gauge thermocouple elements.
- Bars:Cast and wrought ingots serve investment holdings and large-scale alloy melting operations. Swiss precious metals vaults store rhodium bars for institutional allocation.
Granules dominate fabrication throughput; Powder formats are gaining share fastest in emerging additive manufacturing qualification programs.
End User:
End-user segmentation reflects divergent procurement scale, with automotive sector volume contracting against electronics and chemical sector spot purchasing.
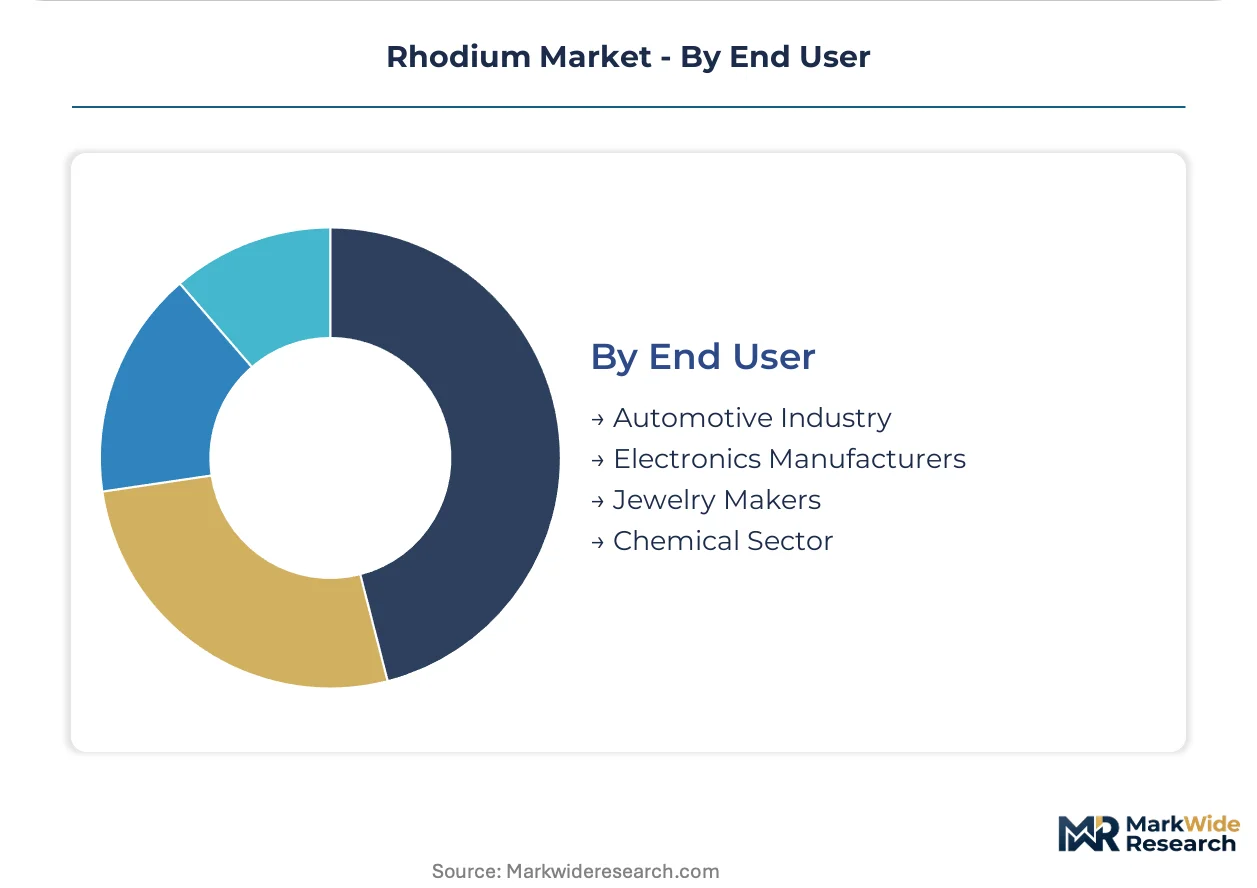
- Automotive Industry:OEMs and Tier-1 catalyst suppliers structure long-term offtake agreements for washcoat fabrication. Volkswagen Group and Toyota have locked multi-year supply contracts through 2029.
- Electronics Manufacturers:Resistor, connector, and sensor producers purchase rhodium compounds and coatings in kilogram-scale batches. South Korean and Japanese electronics clusters drive specification development.
- Jewelry Makers:Artisan and industrial plating operations consume rhodium salts for decorative finishing. Italian jewelry districts in Vicenza and Arezzo concentrate fabrication demand.
- Chemical Sector:Specialty chemical and pharmaceutical producers utilize rhodium catalysts for hydroformylation and hydrogenation reactions. German fine chemical manufacturers specify rhodium phosphine complexes for pharmaceutical intermediate synthesis.
Automotive Industry commands installed volume; Electronics Manufacturers are expanding procurement fastest as sensor electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhodium procurement concentrates where automotive manufacturing and emission regulation stringency intersect. South Africa dominates upstream extraction, while Germany, the United States, Japan, and China concentrate downstream fabrication and vehicle production.
South Africa
The Bushveld Complex hosts the world's richest rhodium-bearing ore bodies through the Merensky and UG2 reef formations. The Department of Mineral Resources and Energy controls licensing for over eighty percent of primary global extraction capacity. Johannesburg and Rustenburg anchor refining operations that supply metallic rhodium to European and Asian autocatalyst fabricators.
Germany
Volkswagen Group and Mercedes-Benz have locked multi-year rhodium supply contracts through 2029 to secure Euro 7 compliance timelines. The KBA enforces type-approval standards that mandate NOx reduction efficiency above ninety percent. Stuttgart and Ingolstadt concentrate catalyst integration facilities where Johnson Matthey and Umicore operate washcoat deposition plants.
United States
EPA Tier 3 mandates compel Detroit automakers to expand rhodium loadings per gasoline vehicle catalytic converter. Ford and Stellantis have adopted tri-metal architectures to achieve lower NOx thresholds. Michigan and Ohio host Tier-1 supplier clusters that structure long-term offtake agreements with South African refiners.
Japan
Toyota's hybrid platform proliferation preserves internal combustion architectures and associated autocatalyst demand even as battery-electric volumes rise. METI oversees critical mineral stockpiling programs that classify platinum-group metals as strategically important. Nagoya and Toyota City anchor catalyst formulation R&D where washcoat optimization for hybrid powertrains advances.
China
Domestic automotive production scale drives rhodium compound imports for local catalyst fabrication, though indigenous mine supply remains negligible. MEE enforces China VI emission standards that approach Euro 6b stringency. Shanghai and Guangzhou concentrate precious metal trading and catalyst manufacturing for both domestic OEMs and export markets.
Rhodium Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue recycling infrastructure and hydrogen fuel-cell catalyst formulations. The market exhibits dual upstream-downstream consolidation, with mining majors controlling primary supply and specialized fabricators dominating autocatalyst technology. Three archetypes prevail: integrated mining-refining conglomerates, dedicated catalyst fabricators with proprietary washcoat IP, and closed-loop recycling specialists recovering platinum-group metals from spent automotive units. Capacity expansion and strategic partnerships represent the dominant competitive vectors, as miners seek offtake security and fabricators secure feedstock pipelines.
Among integrated mining conglomerates, Anglo American PLC and Sibanye Stillwater Limited exemplify upstream supply control through Bushveld Complex asset ownership. Johnson Matthey Plc anchors the catalyst fabrication tier, representing the specialized technology archetype where proprietary dispersion patents create licensing friction for new entrants. Umicore occupies the recycling infrastructure position, demonstrating how closed-loop pyrometallurgical recovery from spent automotive units can offset primary supply concentration risk.
| Leading Market Players |
|---|
| Johnson Matthey Plc |
| Umicore |
| Anglo American PLC |
| African Rainbow Minerals Limited |
| Norilsk Nickel |
| Impala Platinum Holdings Limited |
| Heraeus Holding GmbH |
| Northam Platinum Holdings Limited |
| Sibanye Stillwater Limited |
| Others |
Supply Flow & Price Mechanics
Deep-level mining labor costs in South Africa's Bushveld Complex cascade through rhodium pricing tiers, with energy-intensive extraction below two kilometers amplifying refinery gate prices before metallic sponge reaches German and Japanese autocatalyst fabricators. Long-term offtake contracts now displace spot purchasing as Volkswagen Group and Toyota lock supply through 2029, transferring price volatility downstream to Tier-1 suppliers.
Pricing Analysis
Volume concentrates in contract-based long-term offtake agreements while margins accrue to South African refiners commanding premium positioning. Price differentiation hinges on purity grade and volume scale, with automotive OEMs securing fixed-volume terms against spot-market exposure for smaller electronics manufacturers. Pricing pressure stems from palladium-gold substitution threats in cost-sensitive vehicle segments. Electronics plating houses exhibit highest price sensitivity due to REACH-driven nickel-salt conversion costs, whereas automotive OEMs absorb premiums for Euro 7 compliance security.
Supply Chain Analysis
Workforce-availability constraints in South Africa's Rustenburg and Johannesburg refining corridors amplify supply chain fragility as experienced blast-hole stoping engineers retire. Geographic supply concentrates in South Africa, Russia, and Zimbabwe, with Bushveld Complex ore bodies feeding ninety percent of primary extraction. Raw material dependencies center on Merensky and UG2 reef concentrates, sulfuric acid for hydrometallurgical refining, and natural gas for smelter energy. Single-source vulnerability pervades the upstream tier. Distribution runs through Swiss precious metals vaults and Belgian pyrometallurgical recovery facilities to German and Japanese catalyst fabrication plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rhodium markets operate under severe supply constraint with Bushveld Complex geological concentration propping structural pricing power regardless of demand fluctuations. Deep-level mining expertise scarcity functions as the binding capacity bottleneck sustaining refinery margin capture.
For Market Incumbents: Deepen backward integration into spent catalyst collection networks to secure secondary feedstock pipelines against South African supply disruption. Expand pyrometallurgical recovery capacity in Belgium and the United Kingdom to offset primary concentration risk. Fortify proprietary ceria-zirconia-rhodium dispersion patents against emerging washcoat formulation challengers.
For New Entrants and Emerging Players: Electronics manufacturers seeking REACH-compliant nickel-free plating alternatives represent an underserved buyer archetype with urgent specification needs. Target South Korean and German resistor producers converting sulfate electrolyte systems. Pursue hydrogen fuel-cell catalyst coating qualifications for proton-exchange membrane electrolyzers as a technical wedge. Structure toll-refining partnerships with Bushveld miners lacking downstream fabrication assets.
For Investors and Strategic Acquirers: EU Critical Raw Materials Act stockpiling mandate activation is the leading indicator that strategic reserve procurement will absorb available spot supply regardless of automotive demand cycles. Five-to-ten year viability favors closed-loop recycling specialists with pyrometallurgical capabilities over pure-play miners exposed to South African regulatory and labor dynamics. Monitor Brussels strategic reserve tender announcements as the definitive demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Volkswagen Group and Toyota lock Bushveld offtake through 2029, securing Euro 7 compliance timelines. |
| Backward Integration | Umicore and Johnson Matthey expand pyrometallurgical recovery from spent automotive catalysts in Belgium. |
| Capacity Expansion | Anglo American PLC sustains Bushveld Complex extraction depth below two kilometers despite energy cost pressures. |
| Joint Venture | Platinum-rhodium coating partnerships for hydrogen fuel-cell electrolyzers target durability in high-current-density operation. |
| Green Manufacturing Transition | German plating houses accelerate rhodium sulfate bath conversions to maintain CE-marked component supply under REACH. |
Methodological Framework
Document review covered SEC 10-K filings from platinum-group metal miners, EU Critical Raw Materials Act implementation guidance, and EPA Tier 3 compliance documentation, complemented by interviews with autocatalyst procurement directors at German automotive OEMs, washcoat formulation engineers at Tier-1 suppliers, and pyrometallurgical operations managers at Belgian recycling facilities. Secondary validation drew from South African Department of Mineral Resources and Energy licensing records, ECHA REACH authorization databases, and Japanese METI critical mineral stockpiling reports. Bottom-up and top-down triangulation reconciled mine production data with vehicle production forecasts and catalyst loading specifications.
Historical production volumes were cross-referenced against expert panel assessments of Euro 7 and EPA Tier 3 implementation pacing across the projection horizon. Segmentation dimensions modeled include product type purity tier, application end-use intensity, form factor processing economics, and regional regulatory cluster stringency. CAGRs were derived from regression analysis of historical price-volume relationships adjusted for hybrid powertrain penetration scenarios and hydrogen fuel-cell catalyst adoption curves. Industry-specific inputs incorporated Bushveld Complex ore grade degradation trajectories and blast-hole stoping labor force retirement schedules.
Revisions become necessary when South African mining license moratoria, EU strategic reserve procurement acceleration, or palladium-rhodium substitution breakthroughs in base-metal zeolite formulations materialize outside baseline assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Rubidium Market
Metals
High Carbon Bearing Steel Market
Metals
Transition Metals Market
Metals
High Purity Base Metals Market
Metals
Metal Forging Parts Market
Metals
Copper Clad Aluminum Wire Market
Metals
Wear Steel Plate Market
Metals
Anodized Titanium Market
Metals
China Neodymium Iron Boron Magnet Market
Metals
Aluminum Welding Market
Metals
Tantalum and Niobium Material Market
Metals
India Steel Market
Metals
Metallic Rope Cords Market
Metals
North America Grain Oriented Electrical Steel Market
Metals
North America Metal Casting Market
Metals
Niobium Market