
 Grain Alcohol Market | 2026-2036
Grain Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Grain Alcohol Market Outlook
Brazil is tilting toward expanded grain alcohol distillation capacity as sugarcane processing facilities diversify into corn-based feedstocks. ADM leverages its integrated grain handling and fermentation infrastructure across North American corn belts to sustain supply continuity for fuel and beverage customers. Cargill Inc. anchors its position through deep origination networks that control feedstock costs and quality specifications. Greenfield Global Inc. specializes in high-purity neutral grain spirits for pharmaceutical and beverage applications, competing on consistency and regulatory compliance.
Grain alcohol denotes ethanol produced through fermentation and distillation of cereal grains such as corn, wheat, rye, or barley, typically achieving purity levels between 95% and 96% alcohol by volume before final processing. Its primary commercial purpose spans beverage formulation, pharmaceutical solvent applications, industrial cleaning compounds, and biofuel blending. Neutral grain spirits command the largest volume share within product type segmentation due to their versatility across end-use formulations. Food grade classifications attract premium pricing relative to industrial grade material, reflecting stricter impurity thresholds and certification requirements. The beverage industry end-user segment generates the most concentrated margin pool, though pharmaceutical grade specifications carry the highest per-liter value.
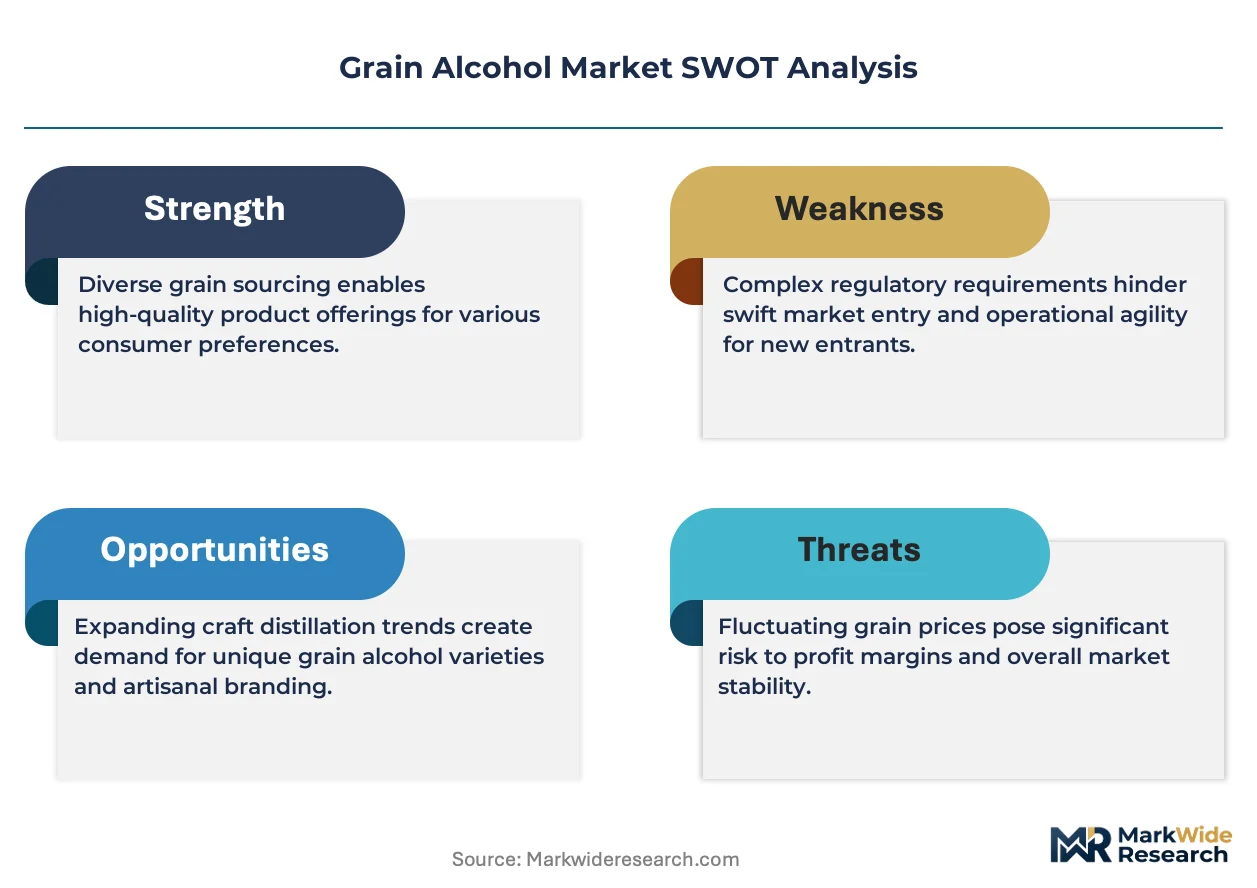
The EPA enforces Renewable Fuel Standard blending obligations that redirect substantial U.S. corn ethanol output toward transportation fuel markets, tightening beverage-grade supply during peak harvest intervals. FDA and TTB oversight of alcohol purity, labeling, and tax classification shapes product standards for potable and pharmaceutical applications, creating compliance barriers for new market entrants. Brazil's ANP biofuel policies and India's BIS quality standards for ethanol blending add further regulatory complexity for multinational suppliers. Stakeholders must monitor feedstock cost volatility, blending mandate revisions, and grade-specific certification timelines to align capacity investments with shifting demand composition.
Market Dynamics
EPA's Renewable Fuel Standard redirects substantial U.S. corn ethanol capacity toward fuel blending obligations, tightening beverage-grade supply availability and compressing margins for potable alcohol producers during peak harvest periods.
Growth Catalysts
- Beverage Industry Procurement Expansion:Premium spirits and ready-to-drink formulations drive concentrated demand for high-purity neutral grain spirits. Buyers prioritize consistent quality specifications and regulatory compliance.
- Biofuel Blending Mandates:Brazil's ANP policies sustain large-scale grain alcohol production infrastructure. Sugarcane and corn ethanol facilities diversify feedstock sources to capture industrial and potable revenue streams.
- Pharmaceutical Solvent Applications:High-purity grades attract premium pricing for vaccine production and active pharmaceutical ingredient extraction. FDA oversight enforces stringent impurity thresholds that favor specialized producers.
Market Restraints
- Feedstock Cost Volatility:Corn and wheat prices fluctuate with weather patterns and commodity speculation. Input cost swings compress margins for undifferentiated industrial-grade producers.
- Supply Concentration Risk:Brazilian sugarcane-to-corn processing infrastructure dominates large-scale distillation capacity. Geopolitical or climate disruptions in this region cascade through global supply chains.
- Regulatory Friction:TTB classification requirements and state-level distribution permits create compliance barriers. New entrants face extended timelines for beverage-grade certification.
Strategic Opportunities
- Underpenetrated Indian Market:BIS quality standards for ethanol blending create infrastructure investment incentives. Domestic producers can expand capacity to serve both fuel and pharmaceutical demand.
- Cellulosic Feedstock Technology:Agricultural residue fermentation processes reduce competition with food-grade grain supplies. Technology convergence with biogas recovery systems improves process economics.
- Direct-to-Brewery Distribution:Craft distilleries and regional beverage manufacturers seek bypass of traditional distributor networks. Channel innovation enables margin capture and customized specification negotiation.
Industry Challenges
- Distillation Engineering Talent Scarcity:High-purity neutral spirit production requires specialized fermentation science and column design expertise. Workforce gaps constrain capacity expansion timelines.
- Multi-Jurisdiction Certification Complexity:Food-grade, pharmaceutical-grade, and fuel-grade specifications demand separate testing protocols. Compliance timeline extensions delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain Alcohol Market |
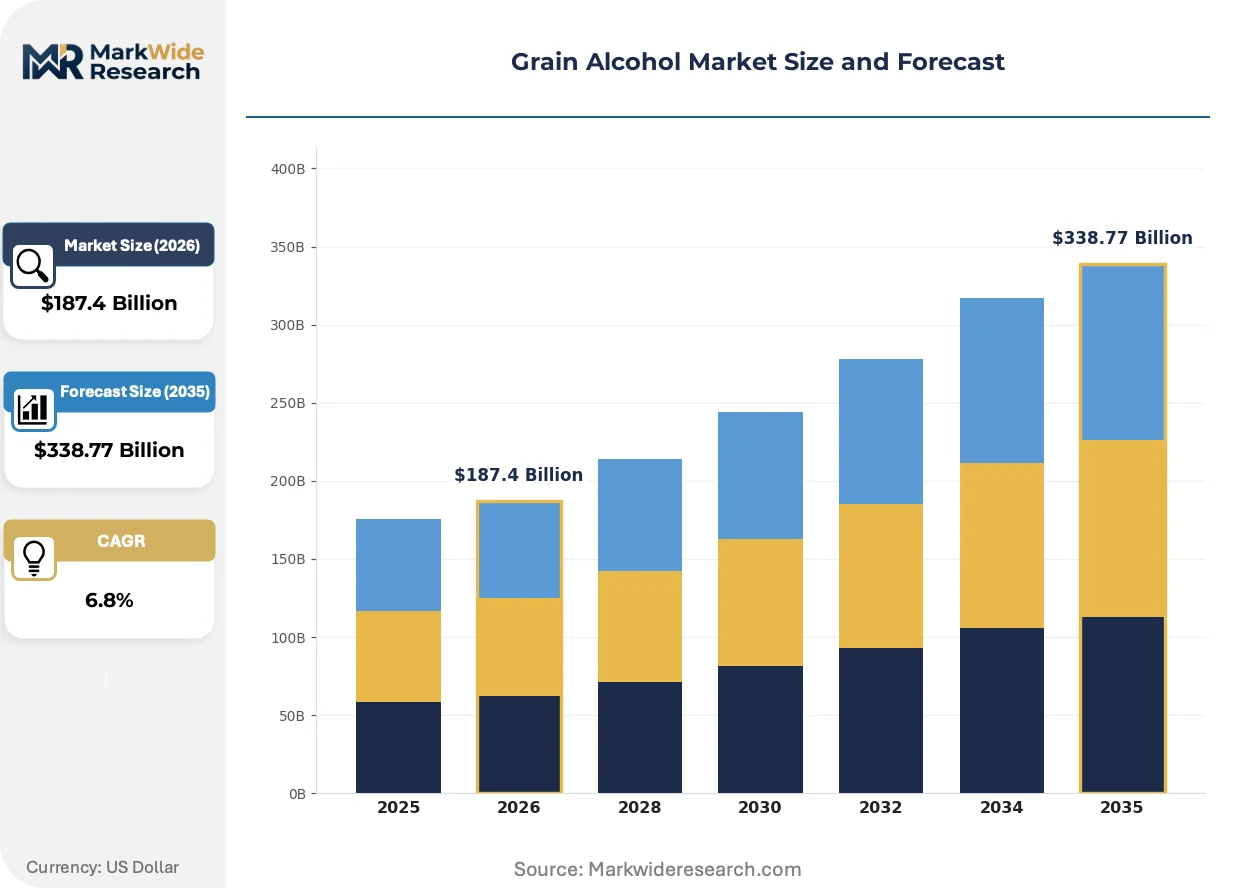
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neutral Grain Spirits, Flavored Grain Alcohol, Organic Grain Alcohol, Conventional Grain Alcohol End User: Beverage Industry, Pharmaceutical Industry, Food Industry, Cleaning Industry Packaging Type: Bottles, Tetra Packs, Cans, Bulk Containers Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Laboratory Grade |
| Companies Covered | ADM, Cargill Inc., Grain Processing Corporation, Greenfield Global Inc., Cristalco SAS, MGP Ingredients Inc., Wilmar International Limited, Manildra Group, Glacial Grain Spirits LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain Alcohol Market Strategic Shifts
Digital process control systems and advanced fermentation monitoring are compressing batch-to-batch variation in grain alcohol production. These technologies enable real-time quality assurance that reduces waste and accelerates certification timelines.
Continuous fermentation monitoring using spectroscopic analysis is virtualizing traditional laboratory-based quality control workflows. Beverage and pharmaceutical manufacturers adopt these systems to reduce release cycle times from days to hours. The technology is virtualizing quality assurance labor pools and enabling distributed production models previously constrained by centralized testing infrastructure.
REACH registration requirements for industrial ethanol used in cleaning compounds and solvents are tightening impurity disclosure obligations. European chemical manufacturers face reformulation pressures to eliminate residual aldehydes and fusel oils. Pharmaceutical-grade specifications are most affected, with producers investing in additional distillation stages to meet evolving ECHA thresholds.
Buyers in the premium spirits segment now demand chain-of-custody documentation from grain field to finished spirit. This certification-driven preference shift displaces anonymous bulk purchasing through commodity brokers. Craft distilleries in the United States and Western Europe lead this behavioral change, using provenance transparency as a competitive differentiator against mass-market alternatives.
Grain Alcohol Market Segmentation
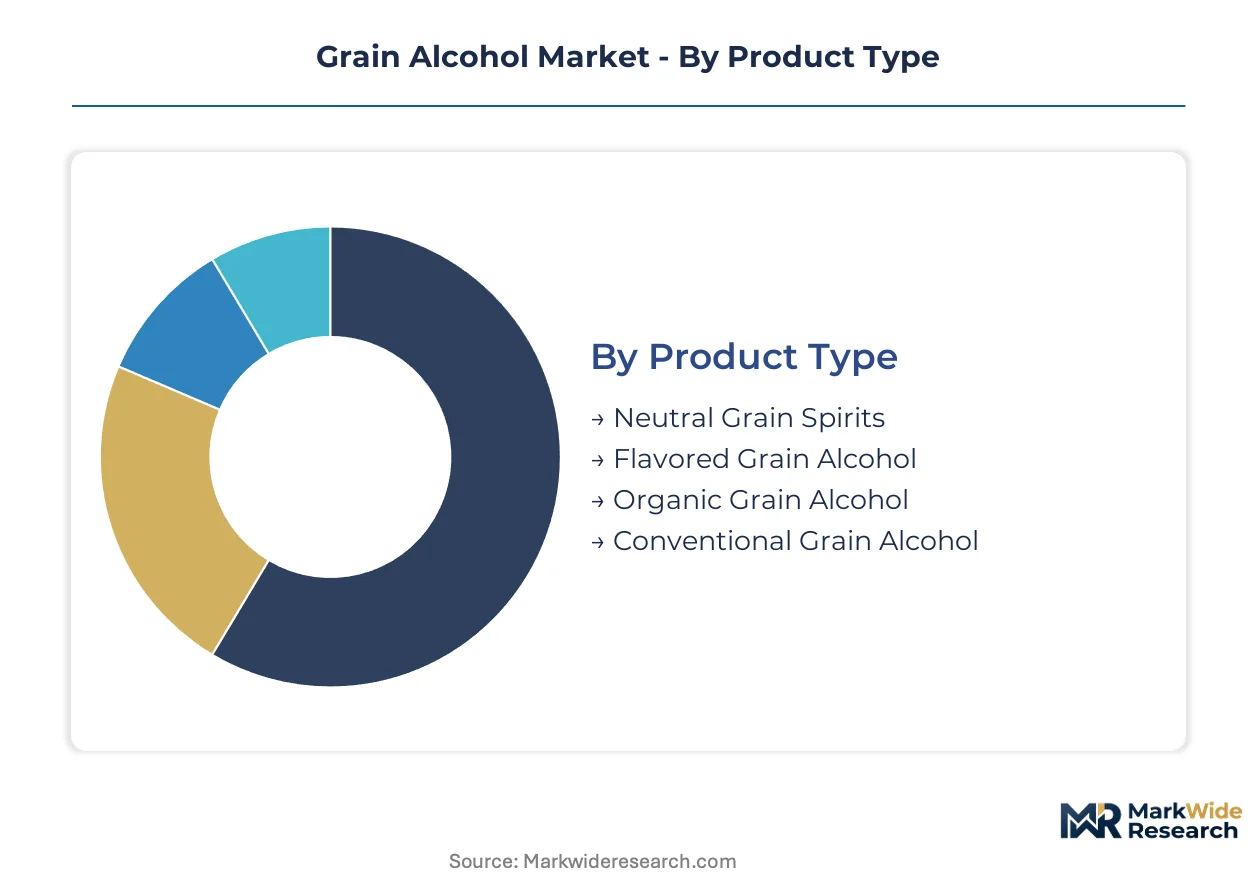
Grain alcohol buyers demand specification precision that varies dramatically across end-use applications. Product purity, packaging format, and regulatory certification requirements create distinct commercial segments with divergent margin profiles and procurement behaviors.
Product Type:
After-sales technical support intensity tracks inversely with product standardization — neutral spirits require minimal ongoing service while organic and specialty variants demand sustained certification documentation.
- Neutral Grain Spirits:Achieves 95-96% alcohol by volume through multi-column distillation of corn, wheat, or rye. Beverage manufacturers in Brazil and the United States concentrate procurement for vodka, gin, and ready-to-drink formulations where consistency and regulatory compliance outweigh provenance claims.
- Flavored Grain Alcohol:Infused with botanical extracts, fruit essences, or spice compounds during or post-distillation. Craft distilleries in Western Europe and North American metropolitan clusters drive demand for small-batch flavored bases that bypass traditional distributor markups.
- Organic Grain Alcohol:Fermented from certified organic cereal grains with USDA or EU organic verification. Premium spirits producers and clean-label beverage formulators absorb price premiums for supply chain transparency.
- Conventional Grain Alcohol:Standard fermentation output without organic or specialty certifications. Industrial solvent and fuel blending applications in the United States and Brazil absorb volume at compressed margins.
Neutral Grain Spirits holds the largest share; momentum sits with Organic Grain Alcohol.
End User:
Application-driven purity requirements stratify the customer base across four distinct compliance regimes.
- Beverage Industry:Demands TTB-certified neutral spirits for spirits production and flavored alcohol bases. FDA and TTB oversight enforces strict impurity thresholds that disqualify industrial-grade material.
- Pharmaceutical Industry:Requires USP-grade or equivalent specifications for vaccine production, API extraction, and medicinal tinctures. FDA validation protocols extend certification timelines and concentrate procurement among specialized high-purity producers.
- Food Industry:Utilizes food-grade ethanol for flavor extraction, food coloring, and preservative applications. FSSAI in India and FDA in the United States enforce separate additive safety standards.
- Cleaning Industry:Absorbs industrial-grade ethanol for surface disinfectants and solvent formulations. REACH registration in Europe and EPA oversight in the United States govern residual aldehyde limits.
Beverage Industry commands dominant volume; Pharmaceutical Industry posts the steepest expansion trajectory.
Packaging Type:
Volume concentration and handling economics determine format selection across customer scale tiers.
- Bottles:Glass or PET containers for retail spirits, pharmaceutical tinctures, and premium food-grade products. Craft distilleries and specialty chemical distributors favor bottle formats for brand differentiation and regulatory traceability.
- Tetra Packs:Aseptic cartons for bulk beverage bases and industrial food applications. Limited adoption in grain alcohol due to compatibility constraints with high-proof ethanol.
- Cans:Aluminum containers for ready-to-drink cocktails and portable disinfectant products. Beverage manufacturers in Brazil and the United States test can formats for outdoor consumption occasions.
- Bulk Containers:Stainless steel totes, tanker trucks, and flexitanks for industrial-scale procurement. Fuel blenders, large distilleries, and pharmaceutical manufacturers capture economies through bulk logistics.
Bulk Containers dominates industrial procurement; Bottles retains premium positioning in branded spirits.
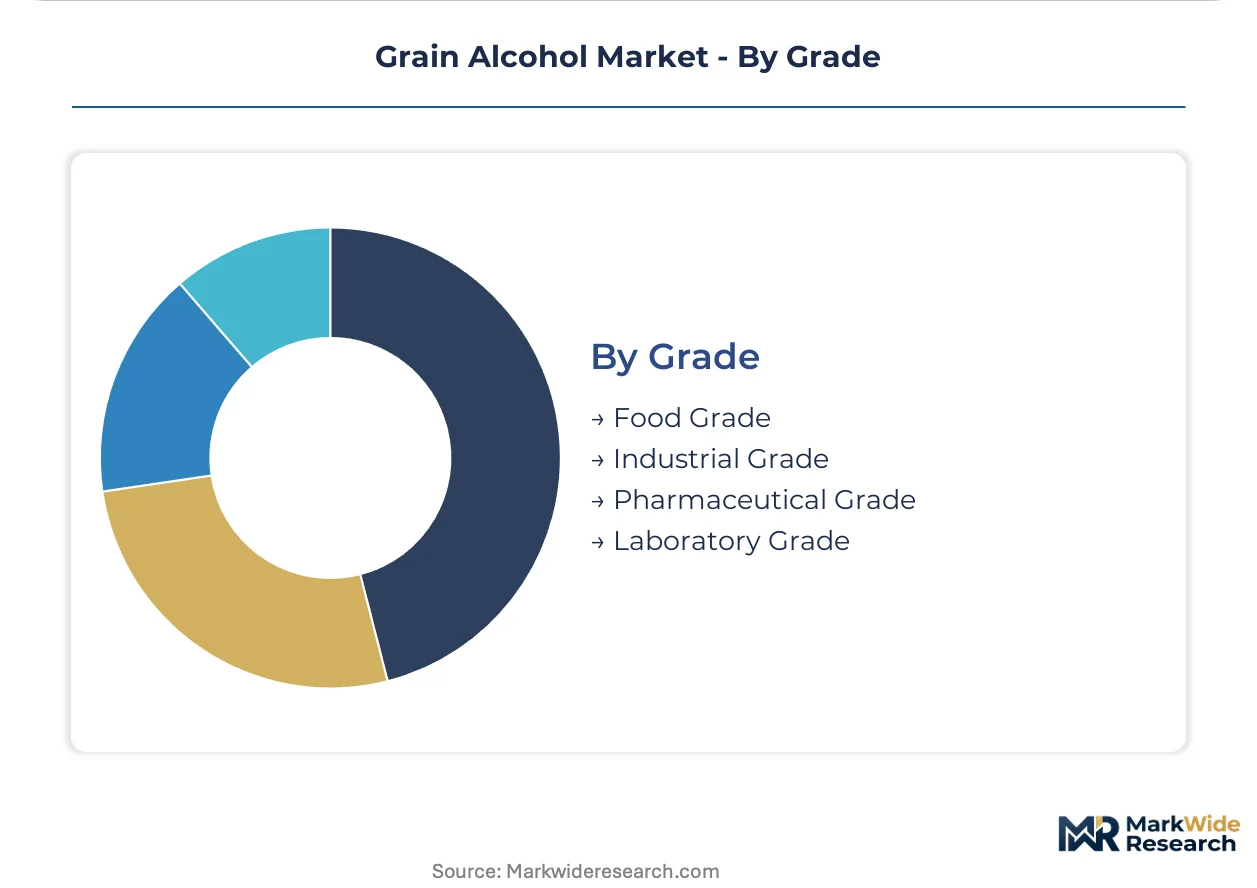
Grade:
Certification tier directly determines permissible applications and achievable pricing.
- Food Grade:Meets FDA and FSSAI purity standards for direct consumption or food contact. Beverage and food manufacturers absorb volume at mid-tier pricing with documented chain-of-custody requirements.
- Industrial Grade:Satisfies fuel blending and non-contact solvent specifications under EPA Renewable Fuel Standard and REACH industrial ethanol categories. Lower impurity thresholds compress margins relative to food-grade material.
- Pharmaceutical Grade:Complies with USP, EP, or JP monographs for medicinal applications. FDA and EMA validation requirements restrict supply to specialized distillers with dedicated pharmaceutical production lines.
- Laboratory Grade:Achieves ACS or equivalent specifications for analytical and research applications. Universities, contract research organizations, and quality control laboratories procure at premium per-liter pricing for assured reagent consistency.
Food Grade captures the broadest demand base; Pharmaceutical Grade achieves the highest unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River barge network and Gulf Coast export terminals underwrite North American grain alcohol logistics, connecting Midwest corn belts to coastal fuel blenders and beverage manufacturers.
United States
EPA Renewable Fuel Standard obligations redirect substantial corn ethanol capacity toward transportation fuel markets, tightening beverage-grade supply availability during peak harvest intervals. FDA and TTB oversight enforces strict impurity thresholds for potable applications. Iowa and Illinois processing clusters concentrate distillation infrastructure along rail corridors serving Chicago-area beverage manufacturers.
Brazil
Sugarcane and corn ethanol facilities diversify feedstock sources to capture industrial and potable revenue streams simultaneously. ANP biofuel policies sustain large-scale production infrastructure with mandated blending requirements. São Paulo state hosts the densest concentration of flexible distilleries capable of switching between sugarcane and corn inputs seasonally.
Germany
REACH registration requirements for industrial ethanol tighten impurity disclosure obligations for cleaning compound and solvent manufacturers. ECHA thresholds drive investment in additional distillation stages for pharmaceutical-grade material. North Rhine-Westphalia chemical clusters absorb bulk industrial volumes while Bavarian specialty distillers serve premium spirits producers.
India
BIS quality standards for ethanol blending create infrastructure investment incentives for domestic producers expanding capacity. FSSAI enforces separate additive safety standards for food-grade applications. Maharashtra and Karnataka processing hubs leverage sugarcane belt proximity to serve both fuel blending and pharmaceutical solvent demand.
China
Dual carbon goals and GB standards for fuel ethanol accelerate corn-based capacity expansion in northeastern grain-producing provinces. NMPA oversight governs pharmaceutical-grade specifications for vaccine production and API extraction. Shandong Peninsula distillation clusters integrate with regional chemical manufacturing complexes for industrial solvent supply.
Grain Alcohol Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The grain alcohol market exhibits moderate concentration with integrated agribusiness conglomerates controlling feedstock origination and fermentation infrastructure alongside specialized high-purity distillers serving pharmaceutical and premium beverage segments. Three archetypes dominate: diversified grain processors with captive ethanol streams, dedicated neutral spirit specialists with multi-column purification systems, and regional cooperatives serving local fuel blending markets. Capacity expansion and backward integration into grain origination networks constitute the primary competitive vectors as margin pressure intensifies on undifferentiated industrial grades.
Within the integrated processor tier, ADM and Cargill Inc. anchor North American supply continuity through control of Midwest grain handling and fermentation infrastructure. Greenfield Global Inc. occupies a specialized position emphasizing high-purity neutral grain spirits for pharmaceutical and beverage applications where regulatory compliance and batch consistency command premium positioning.
| Leading Market Players |
|---|
| ADM |
| Cargill Inc. |
| Grain Processing Corporation |
| Greenfield Global Inc. |
| Cristalco SAS |
| MGP Ingredients Inc. |
| Wilmar International Limited |
| Manildra Group |
| Glacial Grain Spirits LLC |
| Others |
Value Chain & Pricing Dynamics
Feedstock cost volatility in corn and wheat markets determines both the spread between pharmaceutical-grade and industrial-grade pricing tiers and the geographic configuration of distillation capacity. Brazilian sugarcane-to-corn processing flexibility and U.S. Midwest corn belt concentration create divergent supply chain architectures that respond asymmetrically to commodity price shocks.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade neutral spirits from food-grade beverage material and industrial-grade fuel ethanol. Certification-grade differentiation and TTB compliance timelines command premium positioning for vaccine production and premium spirits applications. Cost compression in industrial-grade material intensifies as EPA Renewable Fuel Standard obligations redirect corn ethanol capacity toward fuel blending. Fuel blenders exhibit highest price sensitivity while pharmaceutical manufacturers absorb premiums for batch consistency and regulatory documentation.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities anchor procurement relationships between Brazilian flexible distilleries and North American beverage manufacturers. Corn feedstock draws from the United States, Brazil, and China while distillation engineering talent concentrates in São Paulo state and Iowa-Illinois processing clusters. Single-source vulnerability runs through Brazilian sugarcane-to-corn infrastructure exposed to climate disruption. Distribution runs through Mississippi River barge networks and Gulf Coast export terminals connecting Midwest origination to coastal demand centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellulosic feedstock fermentation technology and EPA mandate revisions are reshaping competitive positioning in grain alcohol production. Regulatory inflection toward biofuel blending creates divergent capacity investment incentives across pharmaceutical and fuel-grade segments.
For Market Incumbents: Harden pharmaceutical-grade certification barriers through USP-grade dedicated production lines and FDA validation protocol investments. Backward integration into grain origination networks in Iowa and Illinois secures feedstock cost control against commodity volatility. Capacity addition in Maharashtra and Karnataka processing hubs captures Indian ethanol blending infrastructure incentives. For New Entrants and Emerging Players: Indian pharmaceutical solvent demand represents the most penetrable white-space target given BIS quality standard implementation and domestic capacity gaps. Direct-to-brewery distribution models bypass traditional distributor markups for craft distilleries in Western Europe and North American metropolitan clusters. Cellulosic feedstock technology licensing offers entry without competing for food-grade grain supplies. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized high-purity distillers with pharmaceutical-grade compliance capabilities. Long-term viability rests on regulatory certification moats and multi-jurisdiction testing protocol expertise. Watch EPA Renewable Fuel Standard revision timing as inflection indicator for beverage-grade supply availability and margin compression direction.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Brazilian flexible distilleries add corn processing lines to capture ANP biofuel mandates and beverage demand simultaneously. |
| Backward Integration | ADM and Cargill leverage captive grain handling infrastructure to control feedstock quality specifications and cost volatility. |
| Pharmaceutical Certification Investment | Greenfield Global Inc. specializes in USP-grade production lines that command premium pricing for vaccine solvent applications. |
| Long-term Supply Agreement | Fuel blenders lock in industrial-grade offtake through EPA Renewable Fuel Standard compliance obligations. |
| Geographic Expansion | Domestic Indian producers expand Maharashtra and Karnataka capacity to serve BIS ethanol blending and FSSAI food-grade demand. |
Study Parameters
Initial hypotheses were tested against primary input from distillery operations managers, beverage procurement directors, pharmaceutical quality assurance leads, and biofuel regulatory affairs specialists and refined through secondary validation. Distillery operations managers provided fermentation yield and purification cost data. Beverage procurement directors detailed specification requirements and supplier qualification timelines. Pharmaceutical quality assurance leads described USP-grade testing protocols and FDA validation pathways. Biofuel regulatory affairs specialists explained EPA Renewable Fuel Standard compliance mechanics and ANP policy implementation. Secondary sources included EPA regulatory filings, ANP biofuel policy documents, FDA pharmaceutical grade monographs, BIS ethanol quality standards, and SEC 10-K disclosures from integrated grain processors. Bottom-up capacity modeling and top-down demand segmentation were triangulated for consistency.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled included product grade tier, end-use industry application, packaging format, and regional production hub concentration. CAGRs were derived from feedstock cost trajectory assumptions and regulatory mandate implementation schedules. Industry-specific forecast inputs incorporated EPA blending obligation revisions, ANP policy updates, and cellulosic fermentation technology commercialization timelines.
Practitioners should monitor EPA mandate revisions, Brazilian climate patterns affecting sugarcane yields, and cellulosic technology cost curves for early signals of forecast deviation. Forecasts reflect assumptions about regulatory stability, commodity price bands, and certification timeline continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Global Food-Grade Alcohol Market
Alcoholic Beverages
Digital Shaker Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market
Alcoholic Beverages
Balsam Bottle Market
Alcoholic Beverages
Rhum Agricole Market
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
Bright Beer Tank Market
Alcoholic Beverages
Moscato Wine Market
Alcoholic Beverages
Global Malted Barley Market
Alcoholic Beverages
Bayberry Wine Market
Alcoholic Beverages
Canned Cocktails Market
Alcoholic Beverages
Pub Cellar Equipment Market
Alcoholic Beverages
Australia and New Zealand Tequila Market
Alcoholic Beverages
Hogshead Barrel Market
Alcoholic Beverages
Beer Line Cooling System Market