
 Pub Cellar Equipment Market | 2026-2036
Pub Cellar Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pub Cellar Equipment Market Analytics
Multi-source procurement for compressor and tap hardware is restructuring supply relationships across the pub cellar equipment value chain. Micro Matic leverages its draught technology heritage to dominate European tap system supply. Perlick Corporation anchors North American premium bar infrastructure through stainless steel fabrication scale. Cornelius competes on beverage carbonation integration with cooling unit OEMs.
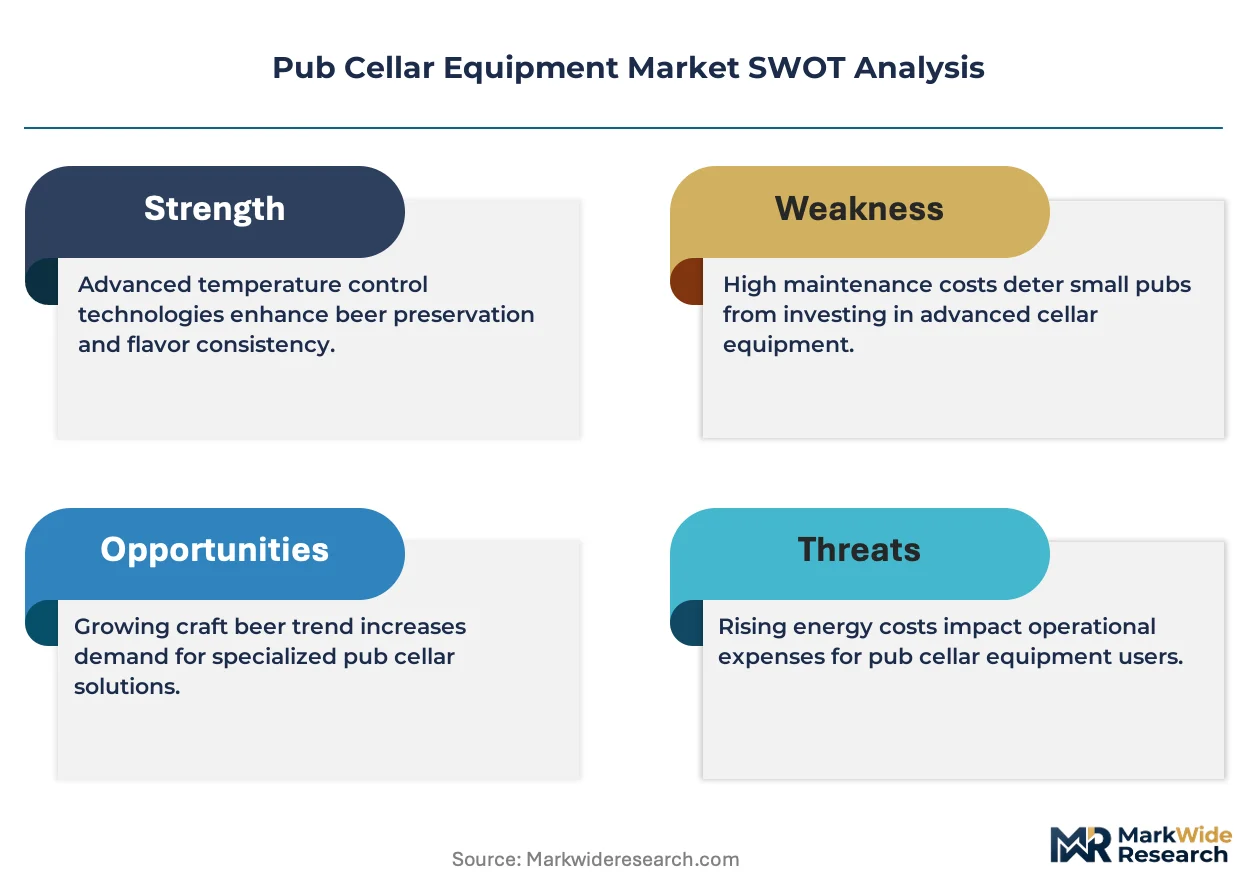
Pub cellar equipment encompasses temperature-controlled storage, draught dispense, and keg handling systems engineered to maintain beer at 2-4°C while preserving carbonation integrity through insulated python lines or glycol-cooled trunking. Draught systems lead product type revenue due to recurring tap handle and line replacement cycles, while glycol cooling technology captures margin from energy-conscious operators seeking F-Gas compliance pathways. Prefabricated installation formats are displacing on-site builds in chain rollouts where speed-to-open dictates capital deployment.
The EU F-Gas Regulation and EPA SNAP program in the United States are restricting hydrofluorocarbon refrigerants in cellar cooling units, forcing OEM redesigns toward CO2 or hydrocarbon alternatives. CE marking under the EU Machinery Directive governs electrical safety in pump and control assemblies exported to European markets. Stakeholders must monitor refrigerant phase-down schedules and energy labeling evolution to align R&D pipelines with compliance timelines.
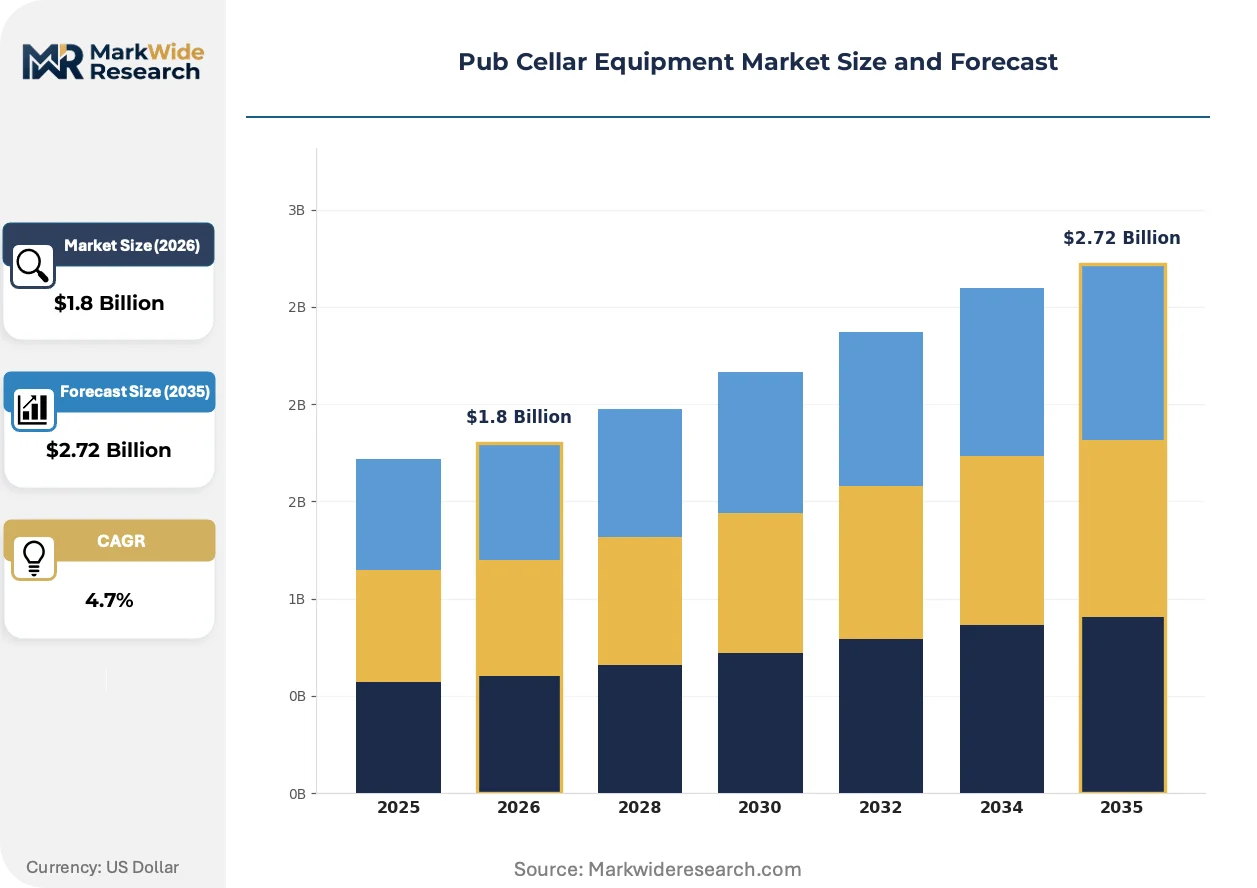
Market Dynamics
Energy efficiency mandates under the EU F-Gas Regulation are forcing a wholesale refrigerant transition across cellar cooling systems, compressing OEM redesign cycles while accelerating glycol retrofit demand from pub operators seeking compliance pathways.
Growth Catalysts
- EU F-Gas Regulation phase-down:The hydrofluorocarbon refrigerant restrictions are compelling pub chains across Germany and the United Kingdom to accelerate equipment replacement schedules.
- Craft brewery expansion:Independent craft breweries in Australia and the United Kingdom are driving multi-tap draught installations in urban clusters.
- Glycol cooling retrofits:Energy-conscious operators are adopting CO2 and hydrocarbon alternatives to meet evolving energy labeling standards.
Market Restraints
- Copper and aluminum input volatility:Stainless steel fabrication costs for premium tap systems fluctuate with base metal commodity markets.
- European supply concentration:Compressor and cooling unit manufacturing clusters in Germany and Italy create geographic dependency risk.
- Refrigerant technology lock-in:Legacy hydrofluorocarbon infrastructure in older pub estates delays full system replacement economics.
Strategic Opportunities
- Prefabricated cellar formats:Chain rollouts in the United Kingdom are adopting factory-built cooling and dispense modules to compress speed-to-open timelines.
- Smart monitoring convergence:Integration of IoT temperature sensors with predictive maintenance platforms is creating new service revenue streams.
- Australian gastropub segment:Underpenetrated urban venues in Sydney and Melbourne present whitespace for premium draught infrastructure.
Industry Challenges
- Refrigerant handling certification:Technician licensing requirements for CO2 and hydrocarbon systems are tightening labor availability across European markets.
- Legacy python line integration:New glycol-cooled trunking must interface with existing insulated line infrastructure without disrupting carbonation integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pub Cellar Equipment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Draught Systems, Keg Racks, Cooling Units, Beer Pumps Technology: Direct Draw, Glycol Cooling, Counter Pressure, Foam Control End User: Pubs, Bars, Restaurants, Nightclubs Installation: On-site, Modular, Prefabricated, Custom-built |
| Companies Covered | Micro Matic, Perlick Corporation, Cornelius, Foster Refrigerator, True Food Service Equipment, Beverage-Air, AB InBev, Heineken, Diageo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pub Cellar Equipment Market Evolving Landscape
Cellar equipment architecture is fragmenting into interchangeable subsystems as regulatory pressure and speed-to-market demands reshape how cooling and dispense infrastructure is specified, procured, and deployed.
Prefabricated cooling skids with plug-and-play glycol distribution manifolds are modularizing traditional on-site cellar builds. Large pub chains in the United Kingdom are specifying these formats to compress venue fit-out timelines from weeks to days. This shift is enabling centralized procurement contracts that bypass regional installation contractors.
The EPA SNAP program in the United States is restricting hydrofluorocarbon refrigerants in commercial cooling equipment, mirroring the EU F-Gas trajectory. American cellar cooling OEMs are redesigning compressor architectures around CO2 transcritical cycles. The North American premium bar segment is absorbing these redesign costs faster than mid-market pub operators.
After-sales service contracts are unbundling from equipment purchase agreements as buyers seek specialized third-party maintenance providers. Independent craft breweries in Australia are driving this preference shift toward outcome-based uptime guarantees. This pattern is most visible in Melbourne and Sydney where multi-tap venues concentrate.
Pub Cellar Equipment Market Segmentation
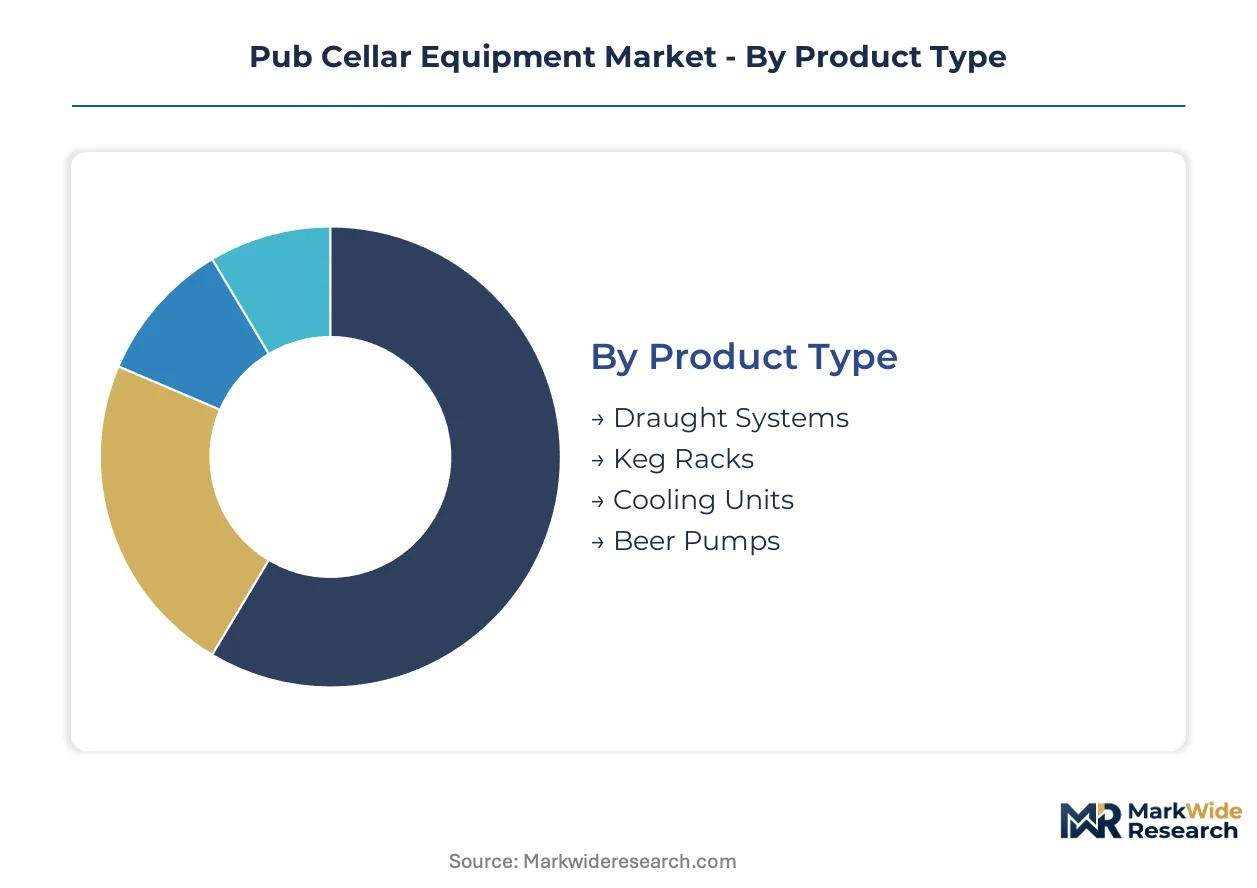
Segmentation in pub cellar equipment reveals how regulatory pressure, venue scale, and speed-to-market priorities split demand across incompatible technical specifications. Operators select configurations based on refrigerant compliance pathways, throughput requirements, and capital deployment timelines.
Product Type:
Technical specification and replacement cycle frequency differentiate revenue concentration across hardware categories.
- Draught Systems:Tap towers, python lines, and dispense valves engineered for 2-4°C temperature maintenance with carbonation integrity. Urban pub clusters in London and Manchester drive recurring replacement cycles for tap handles and beer lines. Revenue concentrates here due to consumable component turnover.
- Cooling Units:Compressor-driven refrigeration systems with glycol or direct-expansion architectures. German and United Kingdom pub chains are accelerating replacement schedules to meet EU F-Gas Regulation phase-down mandates. These units capture margin from energy-conscious operators seeking compliance pathways.
- Keg Racks:Stainless steel storage frameworks for cellar organization and keg rotation.
- Beer Pumps:Electric and pneumatic dispensing mechanisms for remote or high-lift installations.
Draught systems lead on scale; cooling units lead on momentum.
Technology:
Refrigerant chemistry and thermal transfer architecture determine compliance eligibility and operating economics.
- Glycol Cooling:Secondary-loop systems using propylene glycol mixtures to maintain temperature across extended trunking runs. Australian gastropub chains in Sydney and Melbourne specify these for multi-tap venues where python length exceeds direct-draw practical limits. The technology enables F-Gas compliance without hydrocarbon refrigerant handling certification.
- Direct Draw:Short-run dispense from kegs stored directly beneath the tap. Compact urban pubs in Birmingham favor this for space-constrained installations where cellar footprint is minimal.
- Counter Pressure:Carbonation-balanced filling systems for growler and crowler retail.
- Foam Control:Sensor-regulated flow restriction to minimize waste in high-throughput service.
Glycol cooling dominates new specification; direct draw retains installed base density.
End User:
Venue format dictates throughput requirements, service model, and equipment redundancy needs.
- Pubs:Traditional licensed premises with cellar-based storage and cask-conditioned ale infrastructure. United Kingdom free houses and tied estates represent the core installed base with legacy python systems requiring glycol retrofit compatibility.
- Bars:Beverage-forward venues with premium draught emphasis and rapid line cleaning protocols. German urban bar operators are driving demand for modular cooling skids with plug-and-play glycol distribution.
- Restaurants:Food-primary venues with limited cellar space and lower throughput requirements.
- Nightclubs:High-volume weekend-peaked operations requiring redundant cooling capacity and rapid pour speed.
Pubs anchor volume commitment; bars command specification premium.
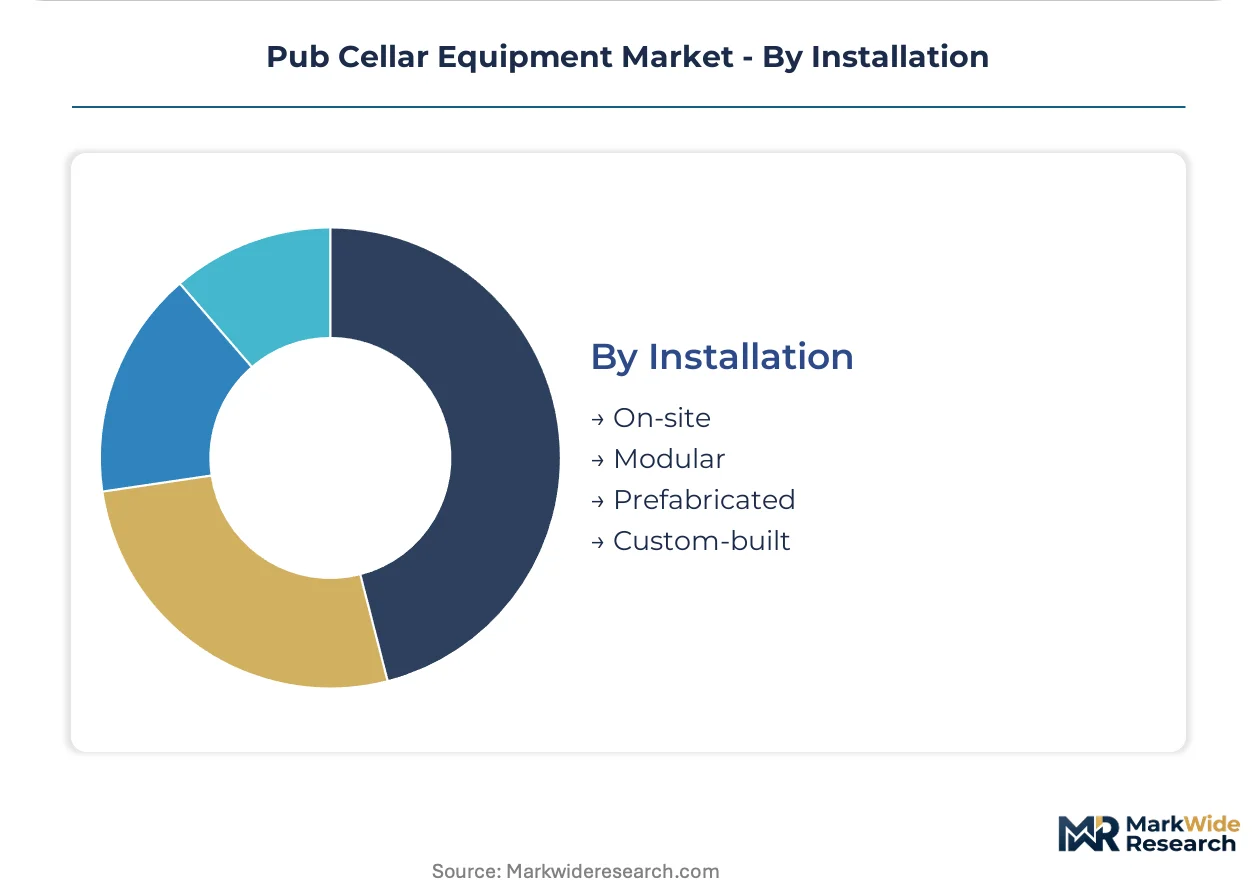
Installation:
Deployment methodology determines speed-to-open, capital structure, and lifecycle flexibility.
- Prefabricated:Factory-assembled cooling and dispense modules delivered as complete skids. Large United Kingdom pub chains specify these formats to compress venue fit-out from weeks to days, enabling centralized procurement bypassing regional contractors.
- Modular:Interchangeable subsystem components allowing field reconfiguration. Independent craft breweries in Australia prefer this for venue adaptation as tap rotation strategies evolve.
- On-site:Traditional build-to-suit construction with site-fabricated cellar infrastructure.
- Custom-built:Architect-specified installations for heritage or premium venue concepts.
Prefabricated formats gain share fastest; on-site retains legacy estate coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United Kingdom pub clusters anchor demand concentration for draught infrastructure and cellar cooling retrofits. Independent craft breweries and gastropub chains in London, Manchester, and Birmingham drive multi-tap installation cycles. Regulatory pressure from Brussels reshapes equipment specification across the continent.
United Kingdom
Free houses and tied estates in London and Manchester accelerate glycol cooling retrofits to meet EU F-Gas Regulation phase-down timelines. The Environment Agency enforces refrigerant handling certification requirements for CO2 system technicians. Birmingham's urban pub clusters dominate prefabricated cellar module procurement for chain rollouts.
Germany
Urban bar operators in Berlin and Munich specify modular cooling skids with plug-and-play glycol distribution manifolds. The KBA and federal environmental regulators align compressor redesign cycles with hydrocarbon refrigerant compliance pathways. Bavaria's brewing heritage regions concentrate draught system OEM manufacturing capacity.
Australia
Gastropub chains in Sydney and Melbourne drive whitespace penetration for premium draught infrastructure. The TGA and state environmental protection agencies monitor hydrocarbon refrigerant deployment in commercial cooling equipment. Victoria's craft brewery clusters concentrate multi-tap venue development in inner-urban corridors.
United States
Premium bar segments in Chicago and New York absorb EPA SNAP-driven compressor redesign costs faster than mid-market pub operators. The EPA restricts hydrofluorocarbon refrigerants through phased SNAP rules. California and Pacific Northwest craft brewery clusters drive counter-pressure and foam control technology adoption.
Italy
Compressor and cooling unit manufacturing in northern industrial zones supplies European retrofit demand. The Ministry of Environment implements EU F-Gas Regulation phase-down schedules through national enforcement protocols. Lombardy and Veneto host fabrication clusters serving German and United Kingdom export markets.
Pub Cellar Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart monitoring convergence and outcome-based service contracts. The vendor base stratifies across draught technology heritage, stainless steel fabrication scale, and beverage carbonation integration capabilities. Three archetypes dominate: European tap system specialists, North American premium bar fabricators, and cooling-carbonation integrators. Consolidation pressure favors centralized procurement contracts and prefabricated format standardization.
Among draught technology heritage players, Micro Matic anchors European tap system supply relationships. Perlick Corporation exemplifies North American premium bar infrastructure positioning through stainless steel fabrication. Cornelius occupies the beverage carbonation integration tier, linking cooling unit OEMs with dispense system architectures. These three represent distinct competitive vectors: heritage specification authority, fabrication scale, and subsystem integration.
| Leading Market Players |
|---|
| Micro Matic |
| Perlick Corporation |
| Cornelius |
| Foster Refrigerator |
| True Food Service Equipment |
| Beverage-Air |
| AB InBev |
| Heineken |
| Diageo |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation compliance deadlines are compressing procurement cycles for United Kingdom and German pub chains, forcing cooling unit OEMs to absorb refrigerant redesign costs while passing stainless steel input volatility through to tap system pricing. This demand-side regulatory pressure concentrates buyer power among large chain operators who leverage centralized contracts to extract prefabricated format discounts.
Pricing Analysis
Input-cost pass-through from copper and aluminum commodity markets dominates pricing dynamics for compressor and cooling unit tiers. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified glycol systems from direct-draw configurations and legacy hydrofluorocarbon retrofits. Pricing pressure stems from base metal volatility and refrigerant handling certification requirements that inflate technician labor costs. Mid-market pub operators exhibit highest price sensitivity, while premium bar segments absorb specification premiums for stainless steel fabrication and smart monitoring integration.
Supply Chain Analysis
Freight cost escalation from Italian and German manufacturing clusters to United Kingdom and Australian installation sites is reshaping procurement geography for compressor and cooling unit assemblies. Supply concentrates in Bavarian compressor fabrication zones, Lombardy metalworking districts, and Veneto refrigeration component centers. Raw material dependencies span stainless steel sheet, aluminum extrusion, and propylene glycol coolant stocks. Single-source vulnerability concentrates in German compressor OEM capacity. Distribution runs through regional installation contractors who are being disintermediated by chain-direct prefabricated module procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pub cellar equipment functions as a stable compounder anchored by mandatory regulatory replacement cycles that ensure predictable demand visibility across refrigerant transition timelines.
For Market Incumbents: Anticipate margin compression from refrigerant technology lock-in disputes as legacy hydrofluorocarbon estates delay full system replacements. Defensive consolidation should prioritize backward integration into stainless steel fabrication capacity and captive glycol coolant supply chains. Certification investment in CO2 transcritical handling protocols creates switching costs against emerging service competitors.
For New Entrants and Emerging Players: Begin with outcome-based maintenance contracts targeting independent craft breweries in Melbourne and Sydney where third-party service unbundling accelerates. White-space penetration should concentrate on smart monitoring convergence for multi-tap venues and prefabricated module specification for Australian gastropub rollouts. Direct channel relationships with state-level environmental regulators build compliance credibility faster than distributor networks.
For Investors and Strategic Acquirers: Asymmetric upside sits with cooling-carbonation integrators possessing EPA SNAP and EU F-Gas dual-certification pathways. Long-term viability frames around refrigerant transition completion and service contract recurring revenue density. Acquisition targets should display installed base density in United Kingdom urban clusters and technician certification depth for hydrocarbon handling. Monitor United Kingdom Environment Agency enforcement intensity as inflection signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Compliance Certification | Dual EPA SNAP and EU F-Gas pathways unlock United States and European chain procurement simultaneously. |
| Prefabricated Module Manufacturing | Factory assembly compresses United Kingdom chain speed-to-open timelines from weeks to days. |
| Smart Monitoring Platform Integration | IoT temperature sensors create recurring service revenue from Australian craft brewery clusters. |
| Backward Integration into Stainless Fabrication | In-house production of tap towers insulates Perlick-scale competitors from base metal volatility. |
| Technician Training Network Expansion | CO2 and hydrocarbon certification programs address labor scarcity tightening across European markets. |
Research Methodology
Coverage spans United Kingdom, Germany, Australia, United States, and Italy, with primary inputs from each market through structured interviews with pub chain procurement directors, cooling unit OEM technical leads, draught system installation contractors, and environmental regulator enforcement officers. Secondary validation drew from EU F-Gas Regulation implementation reports, EPA SNAP program filings, TGA commercial cooling equipment registrations, and stainless steel trade flow data. Bottom-up venue installation counts triangulate against top-down equipment manufacturer shipment aggregates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, refrigerant technology architecture, end-user venue format, and installation methodology. CAGRs derive from regression analysis against regulatory phase-down schedules and craft brewery formation rates. Industry-specific forecast inputs incorporate EU F-Gas quota allocation trajectories and Australian gastropub development pipeline tracking.
Several conditions sit outside the modeled scope, including abrupt refrigerant patent litigation outcomes, trade policy disruptions affecting Italian-German component flows, and pandemic-scale venue closure events. Forecasts reflect assumptions about regulatory enforcement consistency and commodity price band stability. Stakeholders should weight assumptions against their own operating context and regional compliance timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
India Tequila Market
Alcoholic Beverages
Non-Fuel Grade Alcohol Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
Hard Kombucha Market
Alcoholic Beverages
Hookah Charcoal Market
Alcoholic Beverages
Alcoholic Drinks Market
Alcoholic Beverages
United States Tequila Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Automated Brewing System Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
China Tequila Market
Alcoholic Beverages
India Alcohol Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Hard Tea Market