
 High Pressure Processing (HPP) for Rice and Grain Market | 2026-2036
High Pressure Processing (HPP) for Rice and Grain Market Size, Share, and Industry Trends Forecast 2026-2036
High Pressure Processing (HPP) for Rice and Grain Market Foresight
Non-thermal pasteurization at pressures exceeding 400 MPa is rewriting how rice and grain processors achieve microbial reduction without gelatinization or nutrient loss. Hiperbaric leverages its installed base of large-capacity vessels to dominate North American tolling services for grain applications. Avure Technologies competes through equipment modularity that lets mid-size mills retrofit existing lines. Thyssenkrupp anchors European supply with press systems engineered for continuous throughput of bulk grain streams.
High Pressure Processing for rice and grain subjects starchy seeds to isostatic pressures between 100 and 600 MPa, typically at ambient or chilled temperatures, to inactivate pathogens and spoilage organisms while preserving native starch crystallinity and vitamin retention. The technology serves commercial food manufacturers seeking extended refrigerated shelf life without the texture degradation or acrylamide formation associated with thermal treatment. White rice and brown rice together occupy the largest product volume share, though quinoa commands premium positioning among health-focused brands. Shelf-Life Extension and Nutritional Enhancement represent the fastest-growing application categories, as processors market HPP-treated grains to retailers demanding cleaner ingredient panels.
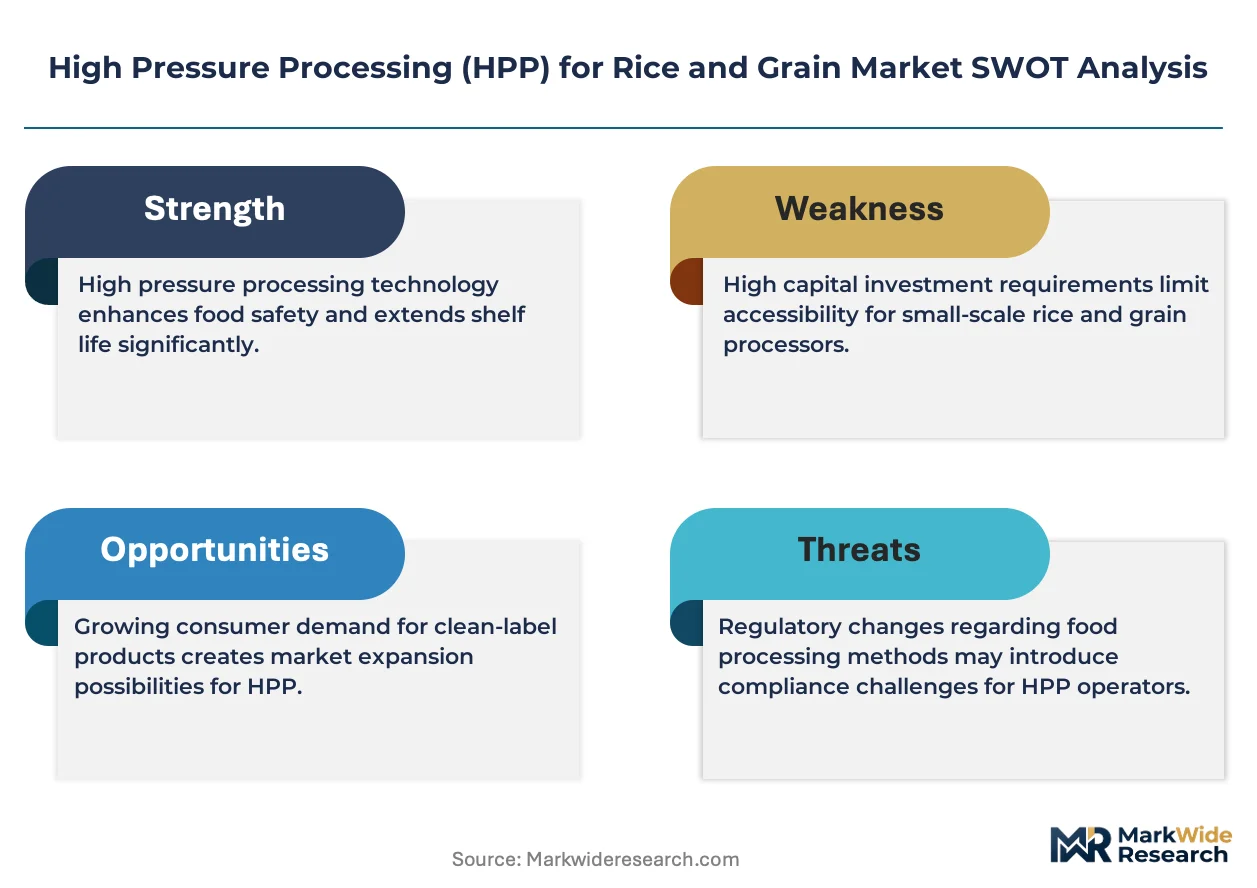
The FDA's Food Safety Modernization Act and USDA's pathogen reduction standards shape equipment validation requirements and facility inspection protocols for HPP grain operations in the United States. EFSA's novel food assessments and EU Green Deal sustainability metrics influence how European processors justify energy-intensive press systems against conventional thermal alternatives. Stakeholders must monitor evolving national equivalency agreements for HPP validation, as divergent regulatory recognition of non-thermal kill-step credentials threatens cross-border grain product approvals.
Market Dynamics
The FDA's Food Safety Modernization Act enforcement is forcing rice and grain processors to abandon thermal pasteurization for non-thermal alternatives that preserve starch crystallinity and vitamin retention without triggering gelatinization.
Growth Catalysts
- FSMA Compliance Pressure:The FDA's updated enforcement protocols mandate validated kill steps for ready-to-eat grain products, accelerating HPP adoption among meal manufacturers seeking clean-label positioning.
- Clean-Label Retail Demands:Supermarket chains now require extended refrigerated shelf life without chemical preservatives, pulling processors toward pressure-based microbial reduction.
- Quinoa Premium Positioning:Health-focused brands command price premiums for HPP-treated ancient grains, creating volume pull through specialty retail channels.
Market Restraints
- Capital Equipment Intensity:Large-capacity HPP vessels require substantial upfront investment, limiting adoption among small and mid-size mill operators.
- Energy Cost Volatility:Electricity-intensive press cycles expose processors to regional utility rate fluctuations, compressing margins in high-cost power markets.
- Thermal Pasteurization Incumbency:Existing steam and dry-heat infrastructure creates switching friction, particularly among commodity rice processors with thin margins.
Strategic Opportunities
- India Regulatory Window:FSSAI's evolving standards for non-thermal processing create first-mover advantage for equipment vendors establishing tolling networks.
- Functional Food Convergence:HPP-treated sprouted grains paired with probiotic fortification open positioning in digestive health segments.
- Direct-to-Retail Channel Expansion:E-commerce fulfillment centers for meal-kit services bypass traditional distributor markups for pressure-treated grain components.
Industry Challenges
- Specialized Technician Scarcity:HPP vessel operation and maintenance require certified pressure-system technicians, creating recruitment bottlenecks in food-processing labor markets.
- Validation Timeline Compression:FDA and USDA pathogen-reduction credentialing for novel grain matrices extends product launch cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Pressure Processing (HPP) for Rice and Grain Market |
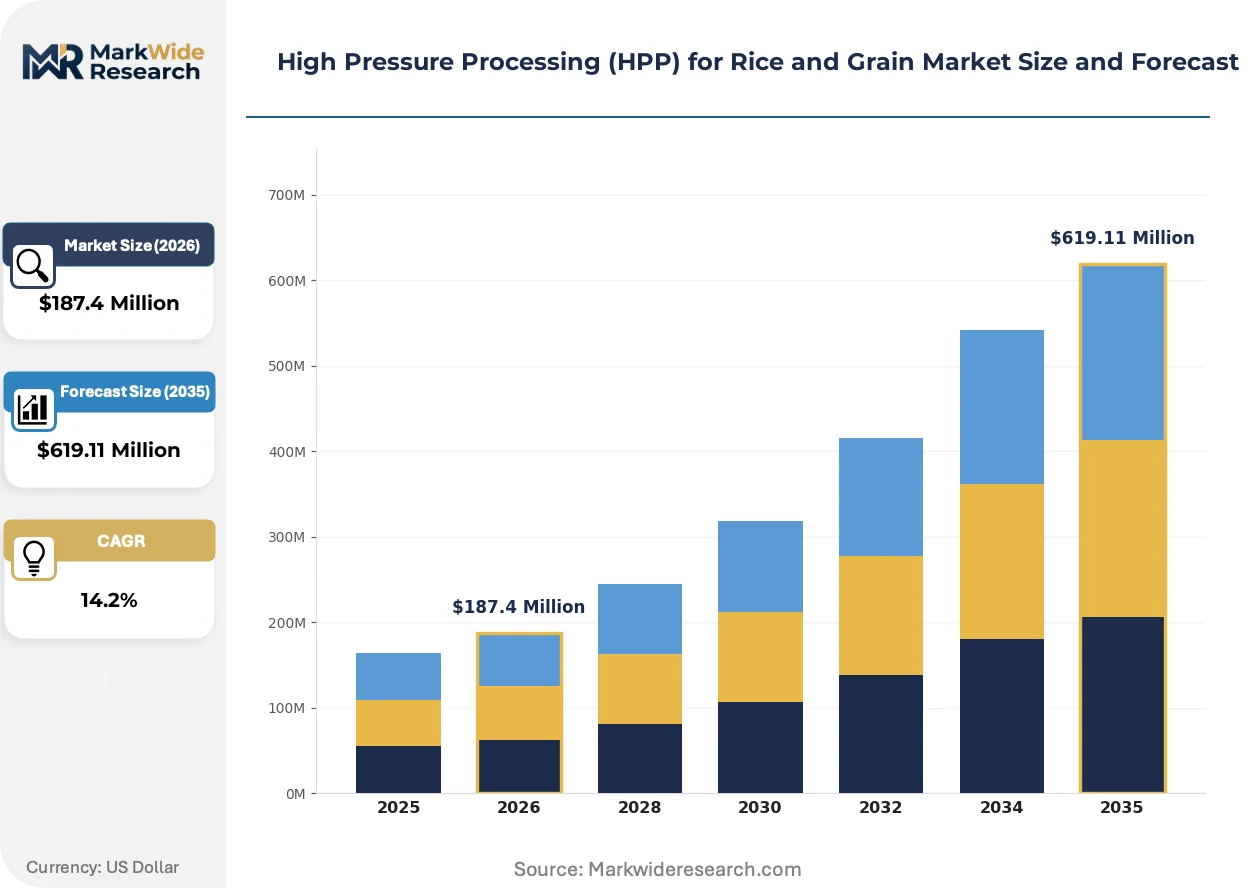
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Rice, Brown Rice, Quinoa, Barley Application: Food Preservation, Nutritional Enhancement, Texture Improvement, Shelf-Life Extension End User: Food Manufacturers, Retailers, Restaurants, Food Service Technology: Batch Processing, Continuous Processing, Home Use Equipment, Industrial Equipment |
| Companies Covered | American Pasteurization Company, Hiperbaric, Avure Technologies, Thyssenkrupp, Bao Tou Kefa High Pressure Technology, Multivac Sepp Haggenmüller, Hormel Foods, Cargill, FresherTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Pressure Processing (HPP) for Rice and Grain Market Shifts & Advancements
Equipment modularity and process automation are collapsing the traditional barriers between artisan-scale grain processing and industrial throughput requirements.
Ultra-high-pressure systems operating above 600 MPa are collapsing the distinction between microbial inactivation and enzymatic preservation in whole-grain applications. Specialty flour mills and sprouted-grain bakeries adopt these intensified cycles to achieve log-reduction targets without sacrificing amylase activity. The technology is collapsing equipment utilization rates as batch-cycle times compress below 180 seconds.
REACH authorization requirements for food-contact materials in pressurized environments are reshaping European equipment specifications. Manufacturers must now validate polymer seal integrity under cyclic loading conditions exceeding 100,000 pressurization events. German and Spanish tolling facilities face the steepest compliance curves as they retrofit legacy vessels for grain-stream continuous feeding.
Ingredient procurement from HPP-certified tollers is replacing in-house pasteurization among mid-size ready-meal manufacturers. This externalization transfers capital burden to specialized service providers while granting buyers flexible volume commitments. The pattern concentrates most visibly in California and Texas, where dense clusters of tolling facilities serve grain processors within 200-mile radii.
High Pressure Processing (HPP) for Rice and Grain Market Segmentation
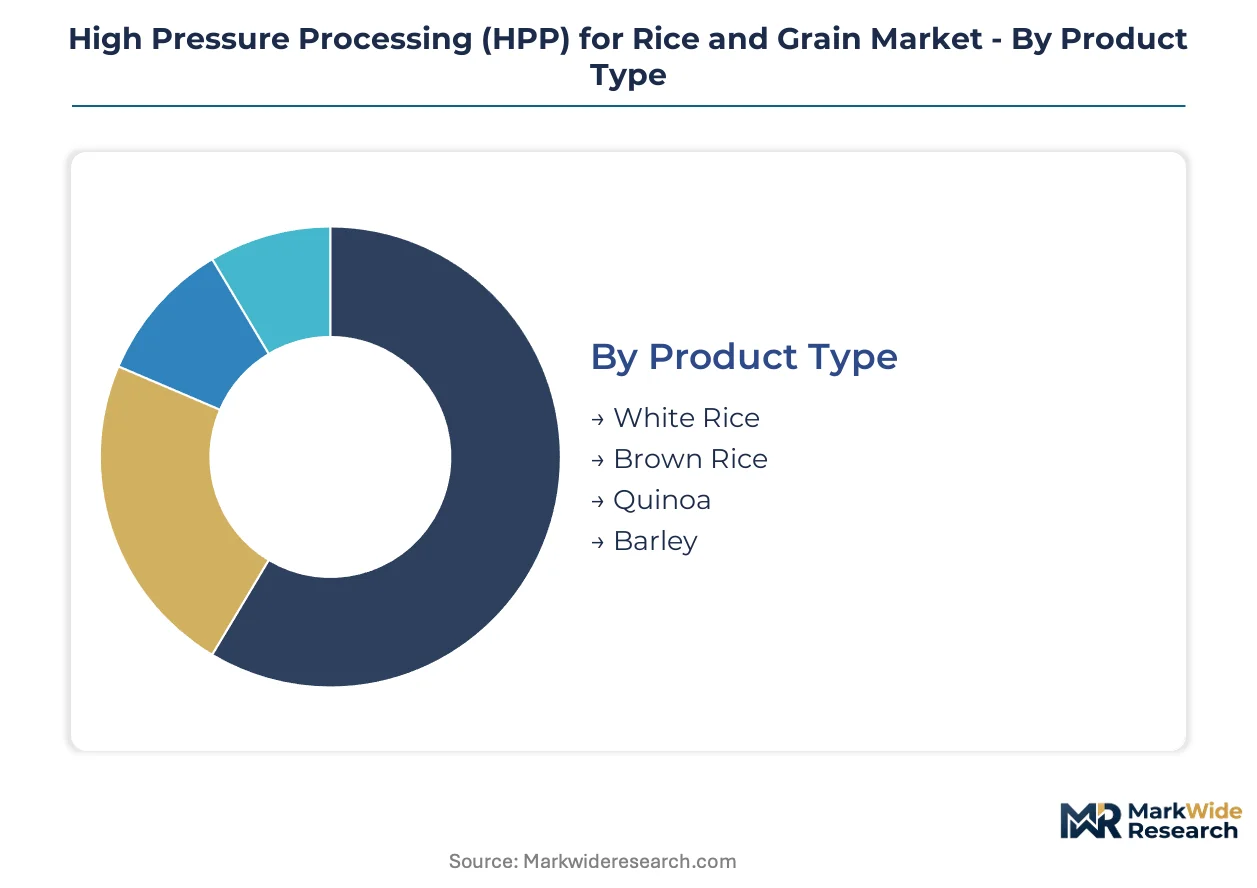
HPP-treated rice and grain markets fragment across four structural dimensions. Each dimension reflects distinct technical requirements, buyer economics, and regulatory exposure that shape equipment specifications and service pricing.
Product Type:
The use-case spectrum spans commodity staples commanding volume throughput to specialty ancient grains justifying premium tolling rates.
- White Rice:Polished endosperm structures respond uniformly to isostatic pressure between 400-600 MPa, enabling predictable microbial log reductions without gelatinization. Demand concentrates among California and Texas ready-to-eat meal manufacturers seeking FSMA-compliant kill steps for refrigerated rice bowls.
- Quinoa:Saponin-coated pericarp requires modified pressure cycles to achieve pathogen reduction while preserving bitter compound removal. Health-focused brands in specialty retail channels command price premiums for HPP-treated ancient grains, creating volume pull through meal-kit services.
- Brown Rice:Intact bran layers with lipase activity demand precise pressure-temperature profiles to prevent rancidity onset during extended shelf life.
- Barley:Beta-glucan-rich endosperm structures suit functional food applications targeting digestive health claims in European markets.
Established volume favors white rice; emerging adoption favors quinoa.
Application:
Cost tier differentiation separates basic microbial safety validation from value-added functional positioning.
- Food Preservation:Pathogen inactivation for Listeria monocytogenes and Salmonella spp. at pressures exceeding 400 MPa satisfies FDA kill-step requirements without thermal degradation. Mid-size grain processors in the United States adopt this application to replace steam pasteurization and access clean-label retail placement.
- Shelf-Life Extension:Spoilage organism suppression enables 30-45 day refrigerated distribution windows, collapsing traditional frozen-channel economics. Meal-kit fulfillment centers leverage this capability to reduce inventory write-offs and expand delivery radius.
- Nutritional Enhancement:Pressure-induced cell permeabilization improves bioaccessibility of B-vitamins and phenolic compounds in sprouted grain applications.
- Texture Improvement:Controlled starch retrogradation creates firmer mouthfeel in sushi rice and parboiled preparations for food service.
Margin compression favors food preservation; steepest expansion trajectory favors shelf-life extension.
End User:
Customer type determines equipment scale, with industrial buyers driving vessel utilization and service providers capturing capital efficiency.
- Food Manufacturers:Ready-to-eat meal producers and grain millers operate captive HPP lines or contract tolling services based on volume predictability. California clusters of tolling facilities serve this segment within 200-mile radii, minimizing logistics costs for pressure-treated components.
- Retailers:Private-label grain brands source HPP-treated inputs to meet clean-label commitments without in-house pasteurization infrastructure.
- Restaurants:Fast-casual chains adopt pre-treated grain components to reduce back-of-house labor and cross-contamination risk.
- Food Service:Institutional caterers and airline meal providers specify HPP-treated grains for extended holding safety in distributed preparation models.
Contracting concentration favors food manufacturers; direct procurement growth favors retailers.
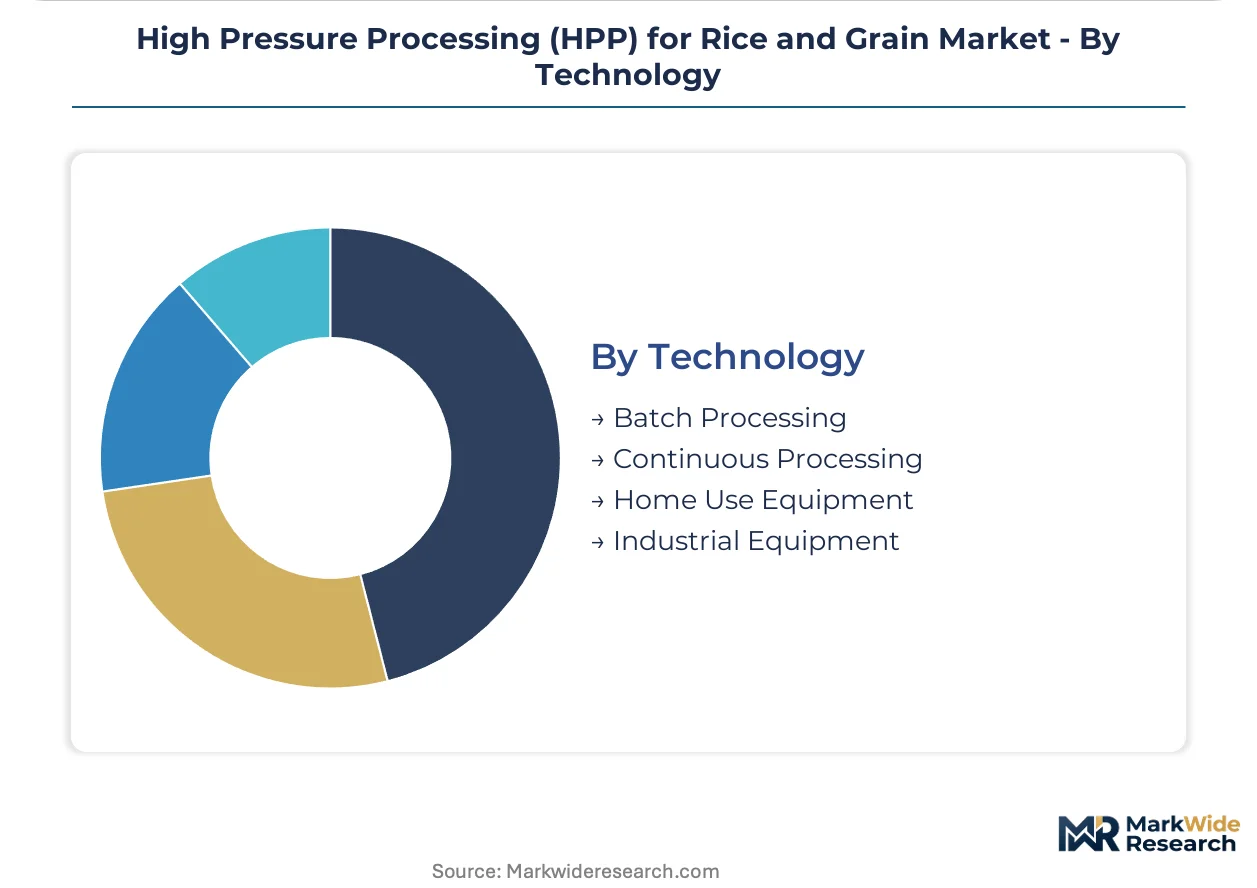
Technology:
Volume throughput separates batch-cycle economics from continuous-feed capital intensity.
- Batch Processing:Vessel-based isostatic presses accommodate variable grain matrices and package formats, dominating North American tolling infrastructure. Hiperbaric's large-capacity installations serve this segment with cycle times compressing below 180 seconds for high-throughput operations.
- Continuous Processing:Pump-based high-pressure homogenization enables uninterrupted grain stream treatment, requiring substantial upfront investment justified by commodity-scale rice processors. Thyssenkrupp anchors European supply with press systems engineered for bulk throughput.
- Industrial Equipment:300-600 liter vessel configurations dominate commercial installations, with modular retrofit options allowing mid-size mills to phase capital deployment.
- Home Use Equipment:Benchtop pressure chambers below 100 MPa serve research applications and artisan-scale product development, not commercial production.
Installed base favors batch processing; capacity expansion favors continuous processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain exports HPP-treated rice components to ready-to-eat meal manufacturers across Northern Europe, establishing a trans-Mediterranean trade corridor that channels Iberian tolling capacity into German and French retail supply chains.
United States
California and Texas host the densest clusters of HPP tolling facilities serving grain processors within 200-mile radii. FDA enforcement of Food Safety Modernization Act protocols pressures processors to abandon thermal pasteurization. Ready-to-eat meal manufacturers in the Central Valley source pressure-treated rice bowls for clean-label retail placement.
Germany
Bavaria-based equipment fabricators engineer press systems for continuous bulk grain throughput. REACH authorization requirements for food-contact materials reshape European equipment specifications as manufacturers validate polymer seal integrity under cyclic loading. Munich-area tolling facilities retrofit legacy vessels for grain-stream continuous feeding.
Spain
Valencia and Barcelona concentrate HPP tolling infrastructure serving Mediterranean rice varieties. EFSA novel food assessments and EU Green Deal sustainability metrics influence how processors justify energy-intensive press systems. Catalan facilities export pressure-treated arborio and bomba rice to Northern European meal-kit services.
China
Yangtze River Delta processors deploy high-pressure systems for white rice microbial reduction targeting export markets. SAMR food safety standards and GB standards for non-thermal processing create regulatory scaffolding for equipment validation. Shanghai-area tolling networks serve domestic ready-meal manufacturers and Japanese import buyers.
India
Maharashtra and Gujarat emerge as HPP equipment adoption frontiers for basmati and non-basmati rice processing. FSSAI evolving standards for non-thermal processing create first-mover advantage for vendors establishing tolling networks. Mumbai-Pune corridor facilities trial pressure-treated grains for domestic meal-kit startups and Middle East export channels.
High Pressure Processing (HPP) for Rice and Grain Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates around large-capacity vessel operators and modular equipment fabricators. The competitive terrain splits between tolling service providers capturing utilization economics and equipment manufacturers selling retrofit solutions to mid-size mills. Strategic archetypes include scale-driven tolling networks, technology-licensing specialists, and regional equipment integrators. Dominant competitive moves encompass geographic expansion of tolling footprints and strategic partnerships between equipment vendors and grain processors.
Among Spanish and German equipment fabricators, Hiperbaric and Thyssenkrupp occupy positions representing the scale-driven and continuous-processing archetypes respectively. Hiperbaric exemplifies the large-capacity tolling network model with its installed base of industrial vessels. Thyssenkrupp anchors European supply with press systems engineered for bulk throughput. Avure Technologies sits within the modular retrofit specialist tier, serving mid-size mills seeking phased capital deployment.
| Leading Market Players |
|---|
| American Pasteurization Company |
| Hiperbaric |
| Avure Technologies |
| Thyssenkrupp |
| Bao Tou Kefa High Pressure Technology |
| Multivac Sepp Haggenmüller |
| Hormel Foods |
| Cargill |
| FresherTech |
| Others |
Supply & Pricing Matrix
The California-Texas freight corridor channels grain processors toward tolling facilities within 200-mile radii, compressing logistics costs while amplifying price differentiation between captive HPP operations and third-party tolling services. This geographic concentration lets large-capacity vessel operators command premium rates for FSMA-validated kill steps, while mid-size mills negotiate modular retrofit pricing phased across equipment generations.
Pricing Analysis
Current-generation 600 MPa continuous systems command substantial premiums over prior-generation 400 MPa batch vessels, while next-generation ultra-high-pressure prototypes remain pre-commercial. Three-tier pricing structure across premium, standard, and economy levels stratifies by vessel capacity and validation tier — FDA-credited facilities extract 30-40% markups over uncertified competitors. Cost compression in standard-tier tolling is intensifying because electricity-intensive press cycles expose operators to regional utility volatility. Commodity rice processors exhibit highest price sensitivity; ready-to-eal meal manufacturers seeking clean-label positioning show lowest.
Supply Chain Analysis
Extended payment terms from 90 to 120 days have become standard among Spanish and German equipment fabricators supplying grain-processing tollers, with supply-chain finance facilities bridging working capital gaps for mid-size mill retrofits. Manufacturing concentrates in Spain, Germany, and China, with component sourcing drawing from Japanese high-pressure pump specialists and Italian polymer seal providers. Single-source vulnerability around ultra-high-pressure intensifier pumps creates procurement bottlenecks. Distribution runs through regional tolling hubs that aggregate grain streams from multiple processors before press treatment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HPP tolling services represent a service-attach opportunity where validation consulting and maintenance contracts expand faster than vessel hardware sales. Recurring revenue from FSMA compliance audits and seal replacement programs now exceeds 25% of total equipment vendor income in mature markets.
For Market Incumbents: Entrench position through backward integration into polymer seal manufacturing, eliminating dependency on Italian component suppliers. Add redundant vessel capacity in the Mumbai-Pune corridor before FSSAI standards crystallize, locking in first-mover relationships with domestic meal-kit startups. Thermal pasteurization incumbents with thin margins threaten price wars; counter through bundled validation services that commodity processors cannot replicate. For New Entrants and Emerging Players: Mid-market brown rice processors in the Yangtze River Delta represent the most penetrable entry point, as SAMR standards create compliance urgency without established tolling density. India's FSSAI regulatory window offers parallel white-space before equipment vendors consolidate tolling networks. Pursue equipment-leasing models with revenue-sharing structures that transfer capital burden while capturing utilization upside. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underutilized HPP assets stranded within legacy thermal processing divisions. Five-to-ten-year viability hinges on regulatory permanence of non-thermal kill-step recognition across FDA, EFSA, and FSSAI jurisdictions. Monitor FSSAI equivalency agreements with FDA as the critical inflection signal for cross-border grain product approvals.| Strategic Initiative | Industry Significance |
|---|---|
| Tolling Network Expansion | Geographic clustering in California, Texas, and Maharashtra captures grain processor density within 200-mile service radii. |
| Regulatory Validation Investment | FDA kill-step credentialing and FSSAI pre-certification create switching costs that lock in multi-year tolling contracts. |
| Equipment Modularity Development | Retrofit solutions for mid-size mills phase capital deployment and accelerate payback periods against thermal incumbency. |
| Backward Integration into Seals | In-house polymer seal production mitigates REACH compliance costs and 100,000-cycle validation bottlenecks. |
| Functional Food Partnerships | Probiotic fortification alliances with sprouted-grain brands open digestive health positioning beyond basic preservation. |
Research Methodology
The analysis maps batch processing systems, continuous throughput equipment, tolling service networks, and regulatory validation tiers, each validated through equipment procurement directors, tolling facility operators, grain mill technical managers, and FSMA compliance officers. Primary interviews with HPP vessel technicians and aftermarket service heads combined with secondary validation from FDA warning letter databases, FSSAI draft standard notifications, and EU Green Deal implementation trackers. Bottom-up equipment installation counts triangulate against top-down grain processing capacity estimates.
Assumptions held fixed include current FDA enforcement intensity, existing electricity tariff structures in California and Texas, and REACH authorization timelines for food-contact materials. Variables tested across the analysis window include FSSAI equivalency recognition speed, ultra-high-pressure system commercialization trajectories, and thermal pasteurization incumbent response timing. Segmentation dimensions modeled encompass product type, application tier, end-user scale, and technology generation. CAGRs derived from equipment shipment forecasts weighted by average vessel utilization rates and regional tolling price points.
Macroeconomic conditions sit as an overlay; deviation in electricity cost trajectories, grain commodity price volatility, or capital availability for mid-size mill retrofits would shift the trajectory. Forecasts reflect documented assumptions about regulatory permanence and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Low Fat Vegetable Soups Market
Processed Foods
Fat Free Soup Market
Processed Foods
United States Processed Meat Market
Processed Foods
Low Fat Soups Market
Processed Foods
Global Malted Milk Market
Processed Foods
Low Moisture Food Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
Processed Beef Market
Processed Foods
Apple Butter Market
Processed Foods
Processed Fruit Bases Market
Processed Foods
South America Processed Meat Market
Processed Foods
Global Potato Flake Market
Processed Foods
Ready to Cook Market
Processed Foods
Instant Curry Market
Processed Foods
Block Margarine Market
Processed Foods
Sugar-Free Ice Cream Market