
 Rhum Agricole Market | 2026-2036
Rhum Agricole Market Size, Share, and Industry Trends Forecast 2026-2036
Rhum Agricole Market Outlook
Specialty cocktail bars and high-end restaurants is expanding their agricole rum selections, creating concentrated buyer power among on-trade channels. Rhum J.M leverages its estate-grown cane program to sustain vertical integration from field to bottle. Trois Rivières anchors its market position through controlled fermentation protocols that emphasize terroir specificity. La Martiniquaise competes across multiple price tiers with broad portfolio depth.
Rhum Agricole denotes a cane juice rum produced through direct fermentation of fresh-pressed sugarcane rather than molasses, with Martinique AOC standards mandating minimum aging periods and geographic origin requirements. The spirit serves primarily as a premium mixing base for classic cocktails and as a sipping spirit for connoisseurs seeking agricultural provenance. Aged Rhum commands the deepest margin pools due to extended barrel inventory cycles and scarcity positioning. White Rhum dominates volume throughput in the on-trade channel where bartenders prize its grassy, vegetal intensity. Organic Rhum represents the fastest-growing product type as EU organic certification and consumer clean-label preferences reshape sourcing requirements.
French AOC regulations and EU Geographical Indication frameworks govern Martinique production standards, while the EU Spirits Regulation defines labeling and bottling requirements across member states. The French national fraud repression agency enforces compliance with cane juice content thresholds and aging claims, directly shaping competitive access for non-AOC producers. Stakeholders must monitor evolving organic certification demands and on-trade buyer consolidation patterns to calibrate portfolio and channel investments.
Market Dynamics
Fresh sugarcane juice fermentation protocols and Martinique AOC aging mandates are compressing production timelines while elevating quality thresholds, forcing distillers to balance inventory carrying costs against scarcity positioning in premium channels.
Growth Catalysts
- Craft cocktail culture:Specialty bars in New York, London, and Paris are expanding agricole programs as bartenders seek terroir-driven base spirits for elevated tiki and tropical drink formats.
- EU organic certification:Clean-label preferences are reshaping sourcing requirements, with EU organic standards enabling premium pricing tiers and retail shelf differentiation across member states.
- Controlled fermentation technology:Precision yeast management and temperature-controlled vats are reducing batch variation, enabling consistent flavor profiles that satisfy on-trade buyer specifications.
Market Restraints
- Sugarcane input volatility:Weather-driven yield fluctuations in Martinique and Guadeloupe create raw material cost instability that compresses margin predictability for estate producers.
- AOC geographic concentration:Martinique's finite arable land and strict appellation boundaries limit scalable volume expansion, constraining supply response to demand surges.
- Extended barrel inventory cycles:Minimum aging requirements tie up working capital for three to six years before aged expressions generate revenue, disadvantaging smaller distillers.
Strategic Opportunities
- United States craft spirits distribution:Underpenetrated markets in Texas, Florida, and California offer expansion vectors through specialized importers and regional distributor partnerships.
- Direct-to-consumer channel innovation:Estate tasting rooms and subscription-based allocation programs are bypassing traditional three-tier systems to capture full retail margin.
- Biodynamic and regenerative certification:Emerging sustainability frameworks beyond organic standards are creating new premium positioning tiers for early adopters in the EU and UK.
Industry Challenges
- Master distiller talent scarcity:Specialized expertise in cane juice fermentation and tropical aging protocols is concentrated among a small cohort of Martinique-trained professionals.
- Compliance documentation burden:French fraud repression agency verification of cane juice content and aging claims requires extensive record-keeping that strains smaller operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rhum Agricole Market |
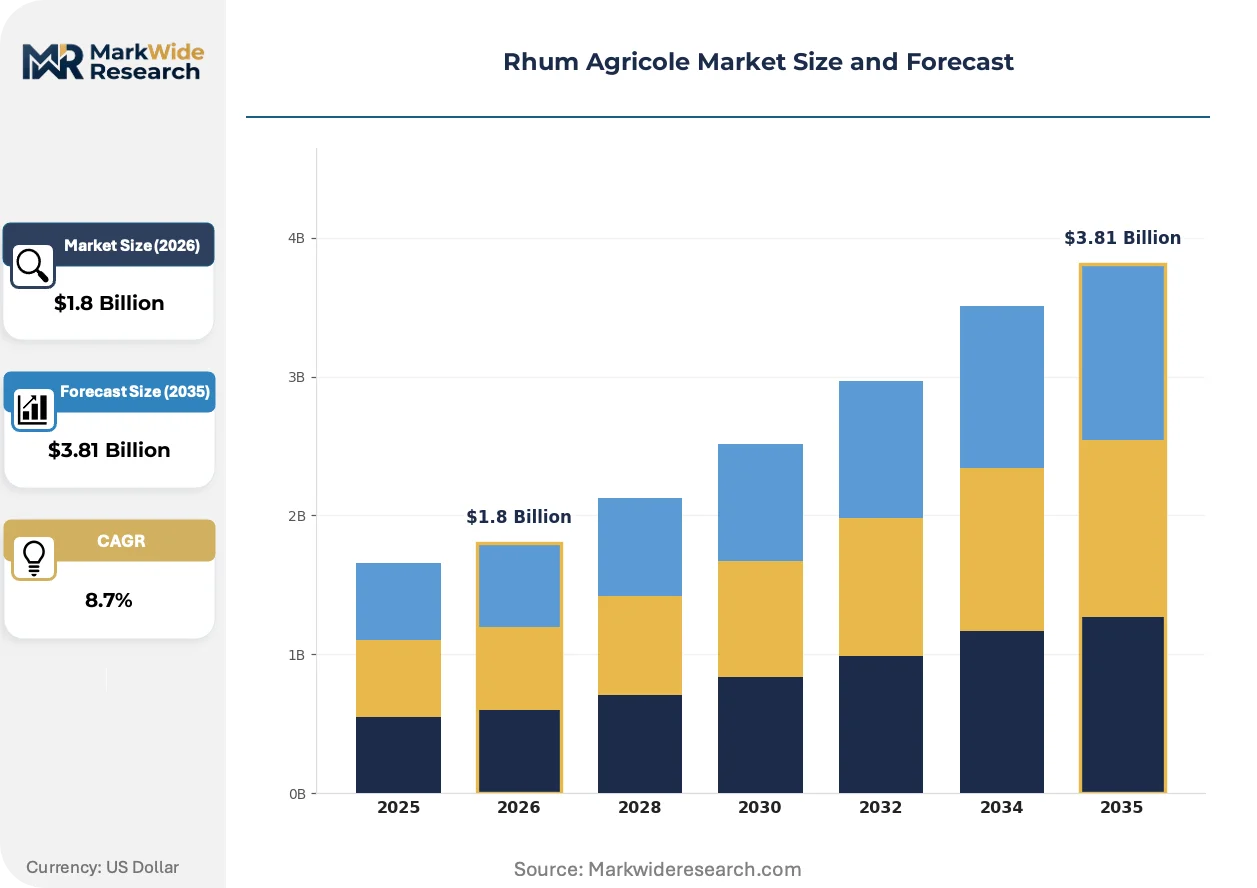
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Rhum, Aged Rhum, Flavored Rhum, Organic Rhum Distribution Channel: Online Retail, Off-Trade, On-Trade, Specialty Stores End User: Bars, Restaurants, Retail Consumers, Distilleries Packaging Type: Bottle, Cask, Tetra Pack, Bag-in-Box |
| Companies Covered | Groupe Bernard Hayot, Trois Rivières, La Martiniquaise, Neisson, Montebello Rhum Agricole, Rhum Clément, Karukera, Société du Rhum Barbancourt, Rhum J.M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rhum Agricole Market Strategic Shifts
Digital traceability systems and precision agriculture tools are reshaping how distillers demonstrate provenance and manage estate operations, while regulatory evolution and shifting buyer preferences create new competitive axes beyond traditional quality markers.
Near-infrared spectroscopy for real-time sugar content assessment is integrating into harvest logistics, enabling optimal cane cutting schedules that maximize aromatic compound retention. Estate producers in Martinique are deploying these sensors across multiple microclimates to segment harvests by terroir character. The technology is integrating field-level data with distillery batch records, creating granular traceability that satisfies AOC audit requirements and supports premium storytelling.
EU Spirits Regulation labeling harmonization is mandating clearer origin disclosure and production method transparency across member states. This regulatory shift is compressing competitive advantage for non-AOC producers who previously relied on ambiguous "cane juice rum" positioning. French overseas departments and AOC-certified estates are benefiting most visibly, as their protected status now carries stronger differentiation weight in continental European retail.
Specialty retailers and on-premise buyers are consolidating supplier relationships around fewer, deeper partnerships rather than broad portfolio sourcing. This concentration is displacing fragmented wholesale purchasing in metropolitan cocktail bar networks across the United States and France. The shift is most pronounced in New York and Paris, where beverage directors now demand exclusive allocations and collaborative product development as conditions for shelf placement.
Rhum Agricole Market Segmentation
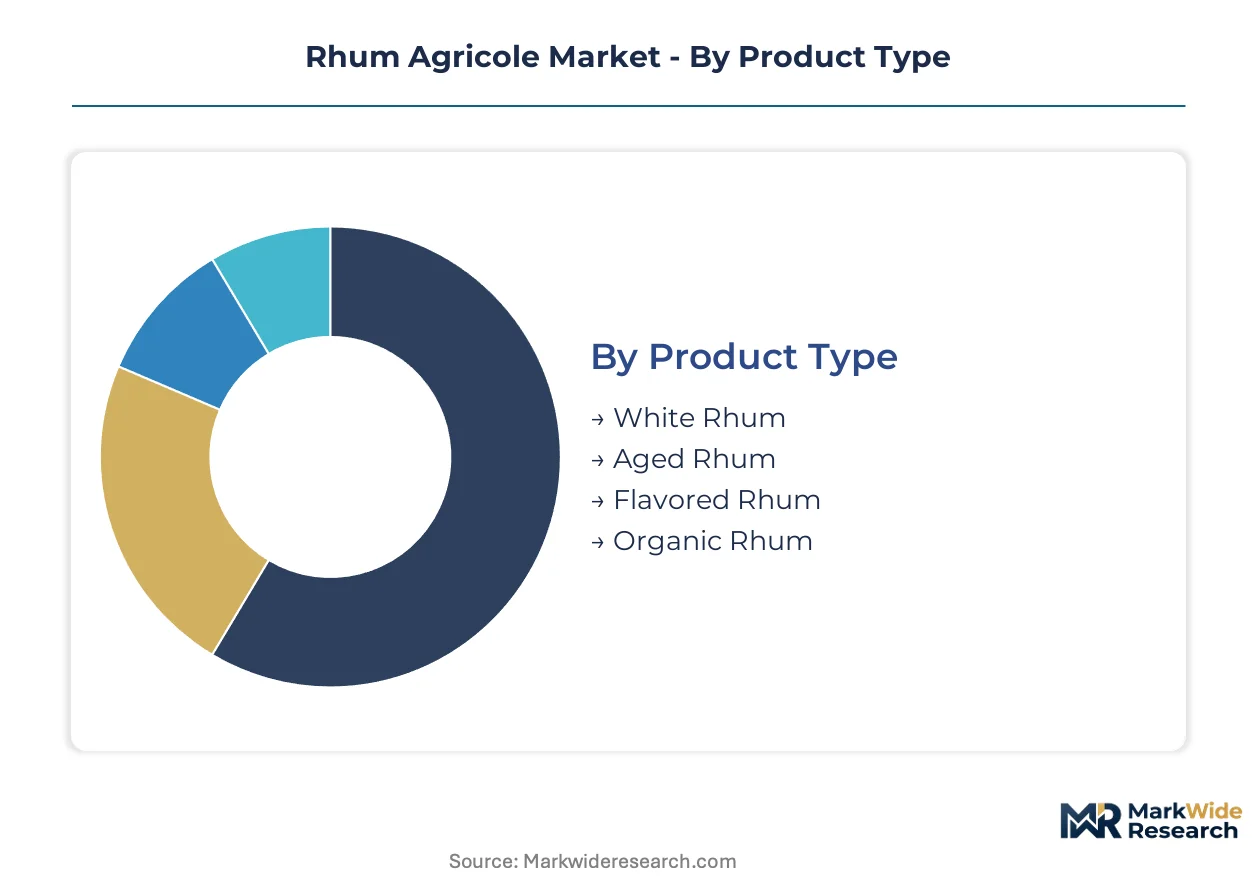
Rhum Agricole producers calibrate portfolio composition against channel-specific margin profiles and end-use consumption rituals. Segmentation strategy determines inventory allocation between high-volume mixing bases and scarcity-positioned sipping expressions.
Product Type:
Fresh cane juice fermentation protocols and barrel aging mandates differentiate product tiers by production timeline and aromatic complexity.
- White Rhum:Unaged cane juice distillate bottled immediately after production preserves grassy, vegetal aromatics. Bartenders in Paris and New York cocktail bars specify this category for classic Ti' Punch and elevated tiki formats. White Rhum leads on scale.
- Aged Rhum:Minimum three-year oak maturation under Martinique AOC rules develops vanilla, spice, and dried fruit complexity. Extended inventory cycles constrain supply response but enable premium pricing in French and American retail. Aged Rhum leads on margin capture.
- Flavored Rhum:Maceration of local botanicals or tropical fruits creates accessible entry points for casual consumers.
- Organic Rhum:EU-certified organic cane cultivation and chemical-free processing protocols command shelf differentiation across member states. Organic Rhum leads on momentum.
Aged expressions anchor producer profitability; organic certification is climbing the fastest.
Distribution Channel:
Channel selection determines margin retention, brand narrative control, and compliance documentation burden.
- On-Trade:Specialty cocktail bars and high-end restaurants concentrate buyer power through exclusive allocation demands. Beverage directors in London and Paris specify terroir documentation and collaborative product development as placement conditions. On-Trade leads on price realization.
- Specialty Stores:Independent spirits retailers and estate tasting rooms enable full-margin capture and direct consumer education. French overseas department producers leverage this channel to bypass continental distributor markups. Specialty Stores leads on narrative control.
- Off-Trade:Supermarket and hypermarket chains drive volume throughput with limited SKU breadth.
- Online Retail:Direct-to-consumer platforms and specialized e-commerce aggregators expand geographic reach beyond traditional import networks. Online Retail leads on momentum.
On-Trade concentrates value capture; online channels are expanding most quickly.
End User:
Consumption context shapes packaging format, proof requirements, and brand positioning investments.
- Bars:Mixology-focused establishments in metropolitan markets drive specification of high-proof, aromatically intense white expressions. Bartender education programs and competition sponsorships secure placement loyalty. Bars leads on volume throughput.
- Retail Consumers:Connoisseur collectors and home mixologists seek aged expressions with provenance documentation and limited releases. Subscription allocation programs and estate membership tiers cultivate repeat purchase. Retail Consumers leads on margin per liter.
- Restaurants:Fine dining beverage programs integrate agricole into dessert pairings and digestif service.
- Distilleries:Bulk supply contracts and private label production serve regional blenders and independent bottlers. Distilleries leads on contract scale.
Bars dominate volume; retail connoisseurs are gaining share fastest.
Packaging Type:
Format selection balances oxidation risk, logistics cost, and occasion-appropriate serving rituals.
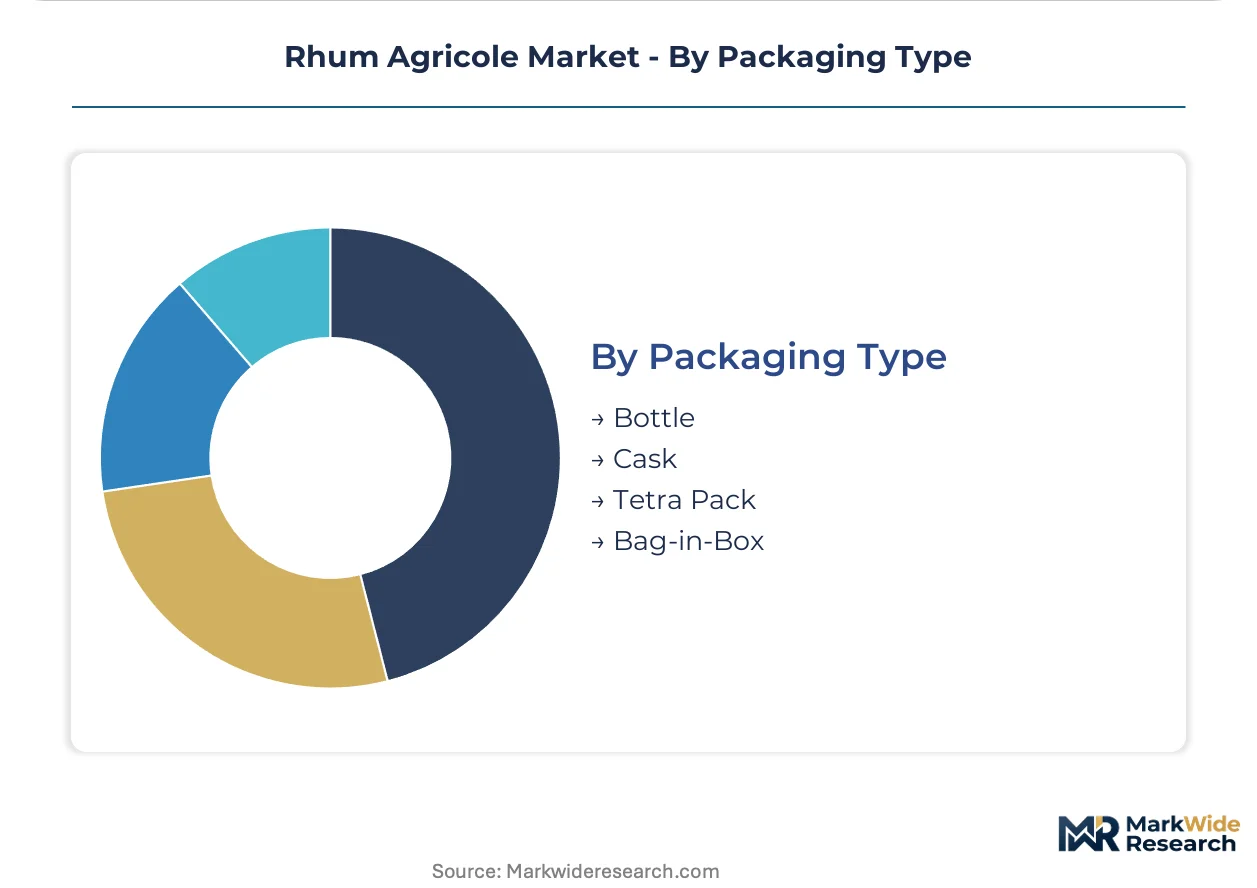
- Bottle:Glass packaging with cork or synthetic closures preserves aromatic integrity for premium sipping expressions. Standard 700ml and 1-liter formats align with EU Spirits Regulation labeling requirements and on-trade pouring protocols. Bottle leads on revenue concentration.
- Cask:Full barrel sales to private collectors and independent bottlers accelerate cash conversion for distillers. French fraud repression agency verification of age statements and origin claims protects buyer confidence. Cask leads on transaction value.
- Tetra Pack:Aseptic cartons reduce shipping weight for bulk white rum in Caribbean tourist markets.
- Bag-in-Box:Dispensing formats target hospitality volume accounts and event catering with reduced per-serve labor. Bag-in-Box leads on momentum.
Bottle formats anchor premium positioning; bag-in-box is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France commands the deepest consumer base for agricole rum, while the United States generates the fastest volume growth through craft cocktail adoption. Martinique's AOC framework shapes quality benchmarks that influence pricing power across both markets. Geographic proximity to cane sources and regulatory recognition determine competitive positioning in each territory.
France
Metropolitan Paris and Lyon cocktail bars drive premium white rhum specifications for classic Ti' Punch service. ANSM enforces labeling transparency under EU Spirits Regulation harmonization mandates. The Île-de-France region concentrates specialist importers and distributor headquarters managing allocation programs.
United States
New York, Miami, and Los Angeles beverage directors specify estate-provenanced expressions for elevated tiki programs. FDA and TTB govern import documentation and age statement verification for Caribbean-origin spirits. Brooklyn and Manhattan bar networks concentrate buyer power through exclusive allocation demands.
Martinique
Estate distilleries anchor supply for AOC-certified aged expressions with three-year minimum maturation requirements. French fraud repression agency audits cane juice content thresholds and barrel inventory records. The northern microclimates around Macouba and Basse-Pointe segment harvests by terroir character for premium positioning.
Guadeloupe
Grande-Terre and Basse-Terre producers supply cane juice rum outside strict AOC boundaries for flexible pricing tiers. EU Geographical Indication frameworks provide partial protection against non-authentic labeling claims. Pointe-à-Pitre serves as the commercial hub for bulk shipping to continental European blenders.
United Kingdom
London specialty retailers and Soho cocktail bars drive demand for organic-certified and limited-release expressions. FSA enforces allergen labeling and alcohol content disclosure under post-Brexit retained EU law. Shoreditch and Mayfair on-trade venues concentrate specification authority for premium agricole programs.
Rhum Agricole Market Competitive Environment
Martinique estate producers anchor the premium tier; Guadeloupe and Haitian specialists hold mid-market positioning through flexible sourcing. Market structure concentrates around AOC-certified estates with captive cane supply and extended barrel inventories. Three archetypes dominate: vertically integrated estate distillers, portfolio conglomerates with rum divisions, and independent family operations with heritage positioning. Competitive moves center on distributor exclusivity agreements and direct-to-consumer allocation programs that bypass wholesale markups.
Among Martinique-based estates, Rhum J.M, Trois Rivières, and Rhum Clément exemplify the integrated producer archetype through field-to-bottle control and terroir-specific harvest segmentation. These entities occupy positions defined by AOC compliance depth and aging inventory scale rather than active strategic initiatives. La Martiniquaise represents the portfolio conglomerate model with multi-price-tier coverage and continental European distribution infrastructure. Groupe Bernard Hayot sits within the diversified agricultural holding category with rum as one vertical among broader Caribbean operations.
| Leading Market Players |
|---|
| Groupe Bernard Hayot |
| Trois Rivières |
| La Martiniquaise |
| Neisson |
| Montebello Rhum Agricole |
| Rhum Clément |
| Karukera |
| Société du Rhum Barbancourt |
| Rhum J.M |
| Others |
Value Chain & Pricing Dynamics
Sugarcane futures volatility in the Caribbean basin cascades through Martinique estate operations into three distinct pricing tiers: AOC-certified aged expressions, white mixing rums, and organic-certified premiums. French fraud repression agency compliance costs and extended barrel inventory cycles amplify price spreads between estate bottlings and Guadeloupe bulk supply.
Pricing Analysis
Capacity additions in Guadeloupe are reshaping price floors for non-AOC cane juice rum, pressuring Martinique estates to differentiate through terroir documentation and extended aging. Three-tier pricing structure across premium estate bottlings, standard AOC releases, and economy bulk supply dominates the market. Price differentiation hinges on AOC certification depth and organic EU status. Cost compression in standard-tier aged expressions is intensifying because working capital constraints disadvantage smaller distillers. Supermarket chains exhibit highest price sensitivity; collector allocation programs show least.
Supply Chain Analysis
Fresh cane juice supply rests on Martinique, Guadeloupe, and Marie-Galante estate harvests with no viable substitution from molasses-based alternatives. Critical inputs include copper pot stills from Vendôme, French oak barrels from Limousin cooperages, and proprietary yeast strains maintained across generations. Single-source vulnerability concentrates in tropical aging warehouse capacity, where hurricane exposure threatens inventory. Distribution runs through specialized spirits importers in Paris and New York, bypassing commodity alcohol wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Rhum Agricole market compounds steadily as craft cocktail culture institutionalizes terroir-driven base spirits in metropolitan bar programs across Paris, New York, and London.
For Market Incumbents: Acquire aging warehouse capacity in northern Martinique microclimates to secure hurricane-resilient inventory positions. Consolidate distributor relationships in Texas and Florida before specialized importers capture shelf space. Threat from Guadeloupe bulk suppliers with flexible pricing requires AOC storytelling investment. Channel control through exclusive allocation programs represents the critical defensive lever. For New Entrants and Emerging Players: Specialized e-commerce aggregators offer the most accessible entry vector for organic-certified expressions targeting UK and German retail. California and Texas present the most penetrable geography given underdeveloped estate-provenance awareness. White rhum for tiki bar programs avoids extended capital lock-up. Direct-to-consumer subscription models bypass three-tier margin compression. For Investors and Strategic Acquirers: Asymmetric upside sits with family-owned Martinique estates possessing captive cane supply and three-year minimum aged inventory. Long-term viability frames around AOC regulatory moat durability and cocktail culture permanence. Acquisition targets should display field-to-bottle integration and existing US import partnerships. Watch for French fraud repression agency enforcement intensity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Terroir-Specific Harvest Segmentation | Near-infrared sensors in Macouba microclimates enable AOC audit-compliant batch differentiation. |
| Direct-to-Consumer Allocation Programs | Estate membership tiers bypass Paris distributor markups and capture full retail margin. |
| Organic Certification Investment | EU clean-label compliance commands shelf differentiation across German and UK specialty retailers. |
| Specialized Importer Partnerships | Brooklyn and Manhattan bar networks concentrate buyer power through exclusive collaborative development. |
| Biodynamic Certification Pilot | Regenerative agriculture frameworks create premium positioning beyond organic in London and Paris markets. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with master distillers, Paris beverage directors, specialty spirits importers, and French fraud repression agency officials with secondary validation. Customs records from French overseas departments, EU Spirits Regulation harmonization filings, AOC audit documentation, and on-trade procurement databases anchored volume estimates. Bottom-up distillery capacity assessments and top-down channel flow analysis triangulated market sizing.
Historical reference periods anchored volume and value projections across the analysis window through comparable-period growth patterning. Segmentation dimensions modeled include product type, distribution channel, end-user context, and packaging format alongside regional regulatory cluster differentiation. CAGRs derived from weighted average of historical trajectory and demand driver elasticity estimates. Forecast inputs incorporated craft cocktail bar expansion rates and organic certification adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hurricane frequency in the Caribbean, EU organic standard revisions, and US three-tier regulatory shifts. Assumptions reflect sustained AOC framework stability and continued metropolitan bartender education investment. Martinique land availability constraints, master distiller succession pipelines, and TTB labeling enforcement intensity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Hogshead Barrel Market
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
Mexico Tequila Market
Alcoholic Beverages
Whiskey Market
Alcoholic Beverages
Pisco Market
Alcoholic Beverages
Lager Market
Alcoholic Beverages
Global TCD Alcohol DM Market
Alcoholic Beverages
Dark Beer Market
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
Craft Wine Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Wine Bottle Sterilizer Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Wine Filling Machine Market