
 Beer Line Cooling System Market | 2026-2036
Beer Line Cooling System Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Line Cooling System Market Outlook
European component manufacturers is pivoting toward CO2-compatible compressor architectures as regulatory deadlines tighten. Micro Matic A/S leverages its draft-dispensing heritage to anchor integrated cooling-to-tap solutions across Nordic markets. Celli Group S.p.A. sustains competitive positioning through in-house production of glycol pump assemblies. Perlick Corporation dominates the premium bar segment in North America with stainless-steel construction standards.
Beer line cooling systems regulate beverage temperature from keg storage to point of dispense using forced-air circulation, glycol recirculation, or direct evaporator contact, typically maintaining beer at 0°C to 4°C to prevent foaming and microbial degradation. Glycol chiller systems occupy the largest product category due to their scalability for long-draw installations exceeding 25 feet. Smart controls represent the fastest-growing control mechanism segment as IoT-enabled temperature logging reduces waste and simplifies compliance documentation. Event venues drive mobile installation demand, though fixed indoor systems retain the deepest margin pools through recurring service contracts.
EPA SNAP regulations restrict high-GWP refrigerants in commercial foodservice equipment, compelling redesigns of compressor technology. The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon use, directly affecting glycol chiller specifications sold in member states. FDA food safety codes govern materials contacting beverage lines, specifying food-grade stainless steel or approved polymers. Stakeholders must weigh refrigerant transition timelines against existing installed-base service obligations when allocating R&D budgets.
Market Dynamics
Refrigerant phase-down mandates are compressing product development cycles as manufacturers redesign compressor architectures around CO2 and hydrocarbon alternatives before regulatory deadlines eliminate legacy hydrofluorocarbon options.
Growth Catalysts
- EU F-Gas Regulation:The phasedown schedule for high-GWP refrigerants is accelerating R&D investment in transcritical CO2 systems for long-draw installations.
- Craft brewery expansion:Small-batch producers scaling taproom operations generate demand for modular glycol chillers with 50-150 foot draw capabilities.
- Smart control adoption:IoT-enabled temperature logging is displacing manual compliance documentation in foodservice chains subject to FDA food safety audits.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger materials constitute 35-40% of chiller BOM costs, compressing margins when commodity markets spike.
- Specialized compressor supply concentration:German and Japanese manufacturers control 70% of CO2-compatible compressor production, creating bottleneck risk.
- Retrofit compatibility limits:Existing glycol infrastructure often requires complete replacement rather than component upgrade to meet refrigerant transition timelines.
Strategic Opportunities
- Mobile event infrastructure:Festival and stadium operators in Australia and Brazil are purchasing trailer-mounted cooling units for temporary dispensing operations.
- Service contract unbundling:Predictive maintenance subscriptions using pressure sensor telemetry create recurring revenue separate from equipment sales.
- Dual-use thermal systems:Brewpubs are integrating beer line cooling with fermentation temperature control through shared glycol loops.
Industry Challenges
- Refrigerant handling certification:EPA Section 608 technician requirements and EU F-Gas personnel certification create hiring bottlenecks as fleet conversion accelerates.
- Legacy control integration:BACnet and Modbus protocol mismatches between new IoT sensors and existing building management systems delay smart retrofit deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Line Cooling System Market |
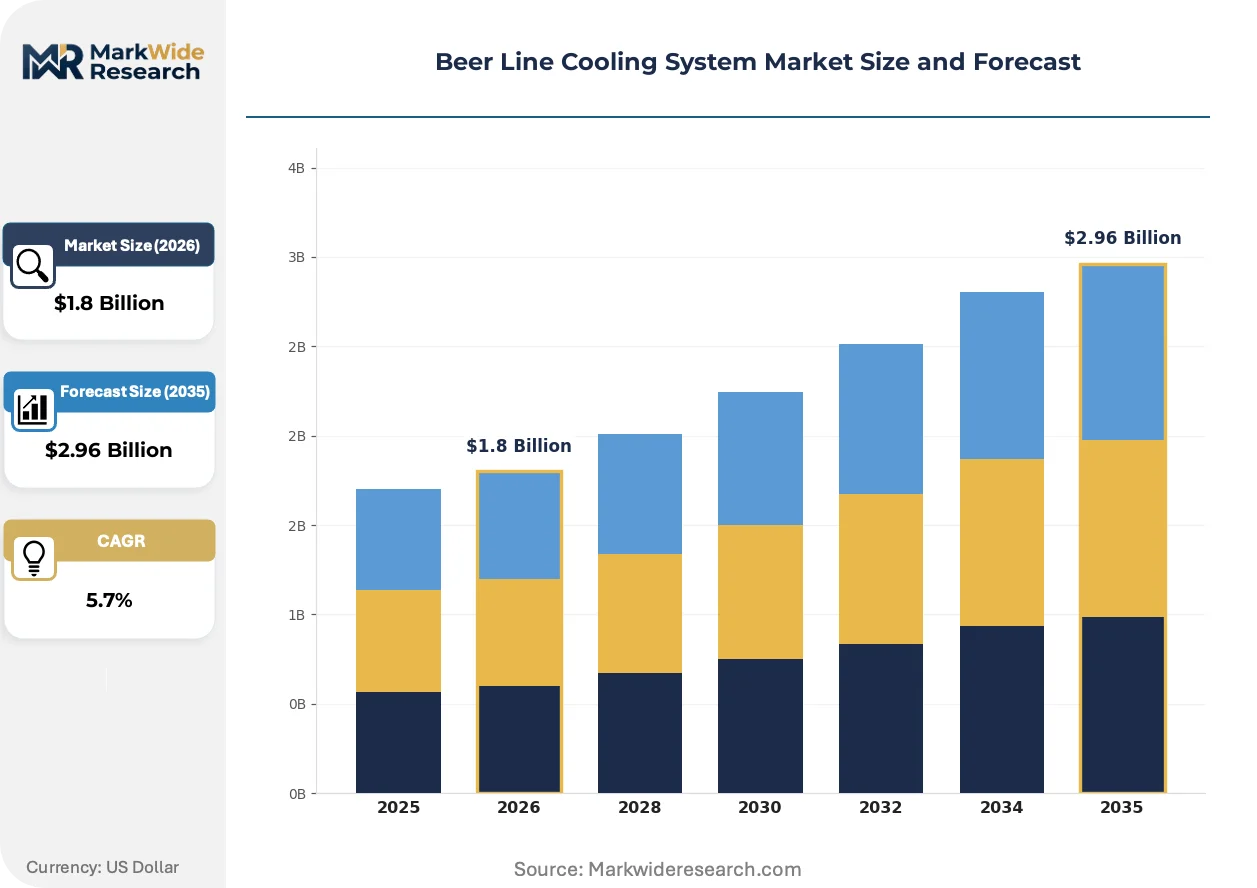
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Draw, Glycol Chiller, Ice Bank, Split System End User: Bars, Restaurants, Breweries, Event Venues Installation Type: Indoor, Outdoor, Mobile, Fixed Control Mechanism: Manual, Automated, Smart Controls, Hybrid |
| Companies Covered | Micro Matic A/S, Celli Group S.p.A., PowerPacker International B.V., Cool Fit Ltd., Bevco, Inc., True Manufacturing Co., Inc., Hoshizaki Corporation, Perlick Corporation, KegWorks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Line Cooling System Market Strategic Shifts
Equipment intelligence and thermal architecture convergence are redefining competitive differentiation beyond static cooling capacity metrics.
Variable-speed scroll compressors paired with electronic expansion valves are integrating adaptive capacity modulation that matches refrigeration load to real-time ambient conditions and tap draw rates. Regional brewpub chains in the Pacific Northwest are specifying these packages for 15-30% energy reduction against fixed-speed legacy units. The technology is integrating predictive algorithms that preempt compressor cycling before temperature excursions trigger foam loss.
The EPA SNAP program's latest rulemaking is prohibiting R-404A and R-507A in new commercial refrigeration equipment, forcing redesign of compact under-bar chillers before the 2025 compliance window. Manufacturers serving the North American market are accelerating transcritical CO2 platform launches originally developed for European supermarket applications. Draft system integrators are responding by expanding field service networks trained in high-pressure refrigerant handling.
Beverage distributors are consolidating procurement decisions at regional headquarters rather than individual account level, compressing vendor relationships from dozens to preferred-supplier frameworks with national service coverage. Independent draft technicians are losing access to specification influence as chain operators centralize equipment standardization. This concentration is most visible in the US Southeast, where multi-state beverage wholesalers are deploying uniform cooling specifications across hundreds of licensed accounts.
Beer Line Cooling System Market Segmentation
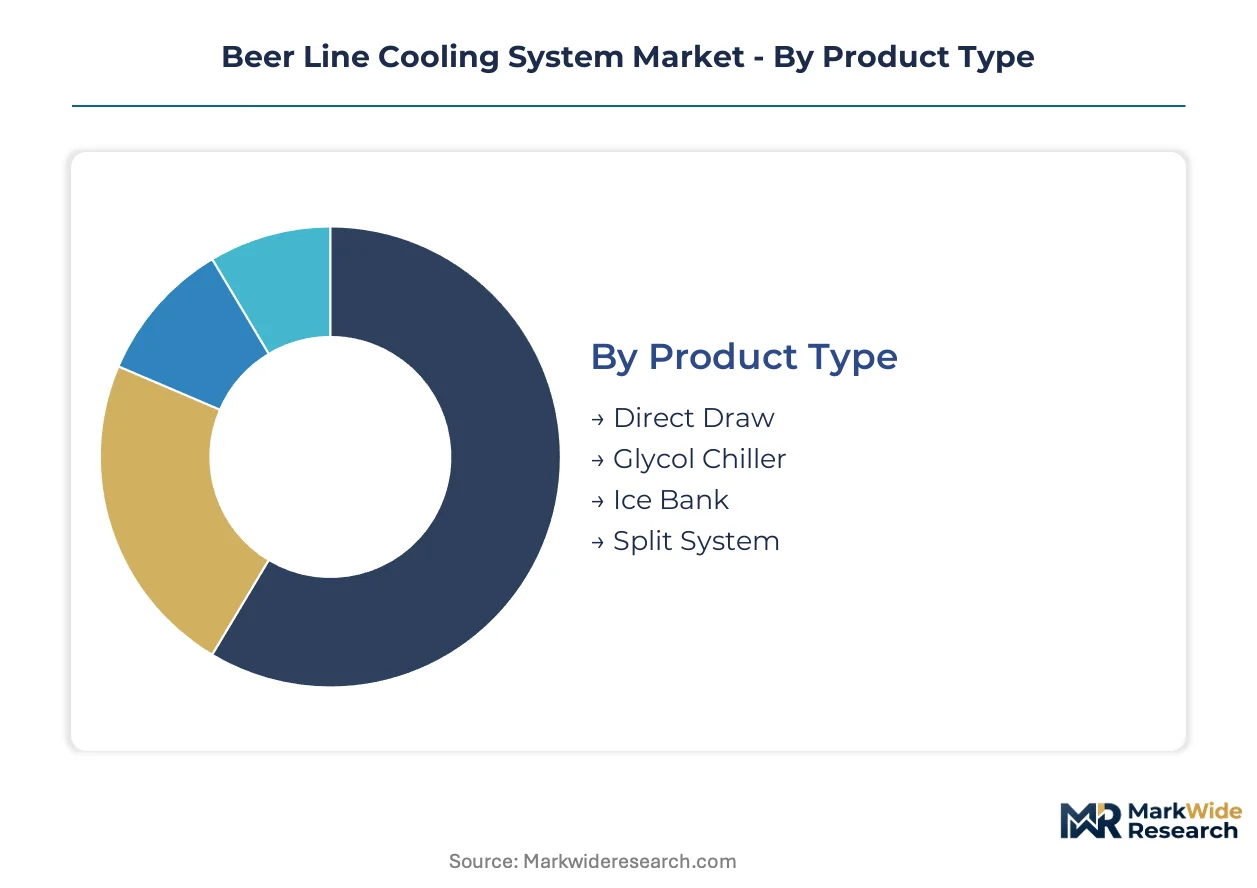
Beer line cooling systems serve heterogeneous operational contexts from high-volume stadium concessions to precision-focused craft taprooms. Segment boundaries reflect trade-offs between capital intensity, thermal performance, and regulatory compliance burden that reshape procurement criteria across buyer categories.
Product Type:
Application distance and refrigerant architecture drive equipment selection more than upfront cost alone.
- Glycol Chiller:Recirculating propylene glycol through insulated trunk lines enables draw lengths exceeding 25 feet without temperature stratification. Demand concentrates in brewpubs and multi-tap venues in Germany and the United States where long-draw installations dominate new construction.
- Direct Draw:Compact under-bar units position evaporators adjacent to keg storage, eliminating distribution lines entirely. Short-draw bars in Japan and urban Australia specify these systems where floor space commands premium lease rates and simplicity reduces service dependency.
- Ice Bank:Thermal mass storage using submerged cooling coils provides surge capacity for peak dispensing periods. Festival operators in Brazil and Australia deploy these for mobile event infrastructure where electrical supply fluctuates.
- Split System:Remote condensing units separate compressor noise from customer-facing areas. High-end hotel bars in Dubai and Singapore specify these configurations where acoustic comfort intersects with performance requirements.
Volume sits with Glycol Chiller installations; growth tilts toward Smart Controls integration across all product architectures.
End User:
Capital deployment cycles and regulatory exposure vary sharply across buyer sophistication tiers.
- Breweries:On-premise taproom expansion generates demand for modular systems with 50-150 foot draw capabilities and fermentation loop integration. Craft producers in the Pacific Northwest and Bavaria are specifying shared glycol infrastructure that serves both packaging lines and guest-facing dispensing.
- Bars:Independent operators prioritize reliability and service network proximity over feature depth. Neighborhood pubs in England and Ireland represent dense installed bases with recurring maintenance contract potential.
- Restaurants:Chain operators centralize procurement at regional headquarters, compressing vendor relationships toward preferred-supplier frameworks with national coverage. Multi-state beverage wholesalers in the US Southeast deploy uniform specifications across licensed accounts.
- Event Venues:Stadium and festival operators in Australia and Brazil are purchasing trailer-mounted cooling units for temporary dispensing operations where permanent infrastructure proves uneconomical.
Revenue concentrates with Bars; Breweries are expanding most quickly as production-scale operators verticalize into direct-to-consumer dispensing.
Installation Type:
Mobility requirements and environmental exposure dictate enclosure specifications and refrigerant charge limits.
- Fixed:Permanent indoor installations retain the deepest margin pools through recurring service contracts and predictive maintenance subscriptions. Full-service restaurants in Germany and the United States anchor this segment.
- Mobile:Trailer-mounted and skid-based units serve temporary events and construction-phase taprooms. Brazilian festival infrastructure and Australian outdoor venue operators drive specification innovation here.
- Indoor:Climate-controlled environments enable standard compressor architectures and reduced insulation specifications. Urban bars in Japan and Singapore dominate this category.
- Outdoor:Weather-resistant enclosures and extended operating temperature ranges command material cost premiums. Beer gardens in Bavaria and rooftop bars in Dubai require these hardened configurations.
Deployment volume favors Fixed installations; Mobile systems are gaining share fastest as event-temporary hybrid business models proliferate.
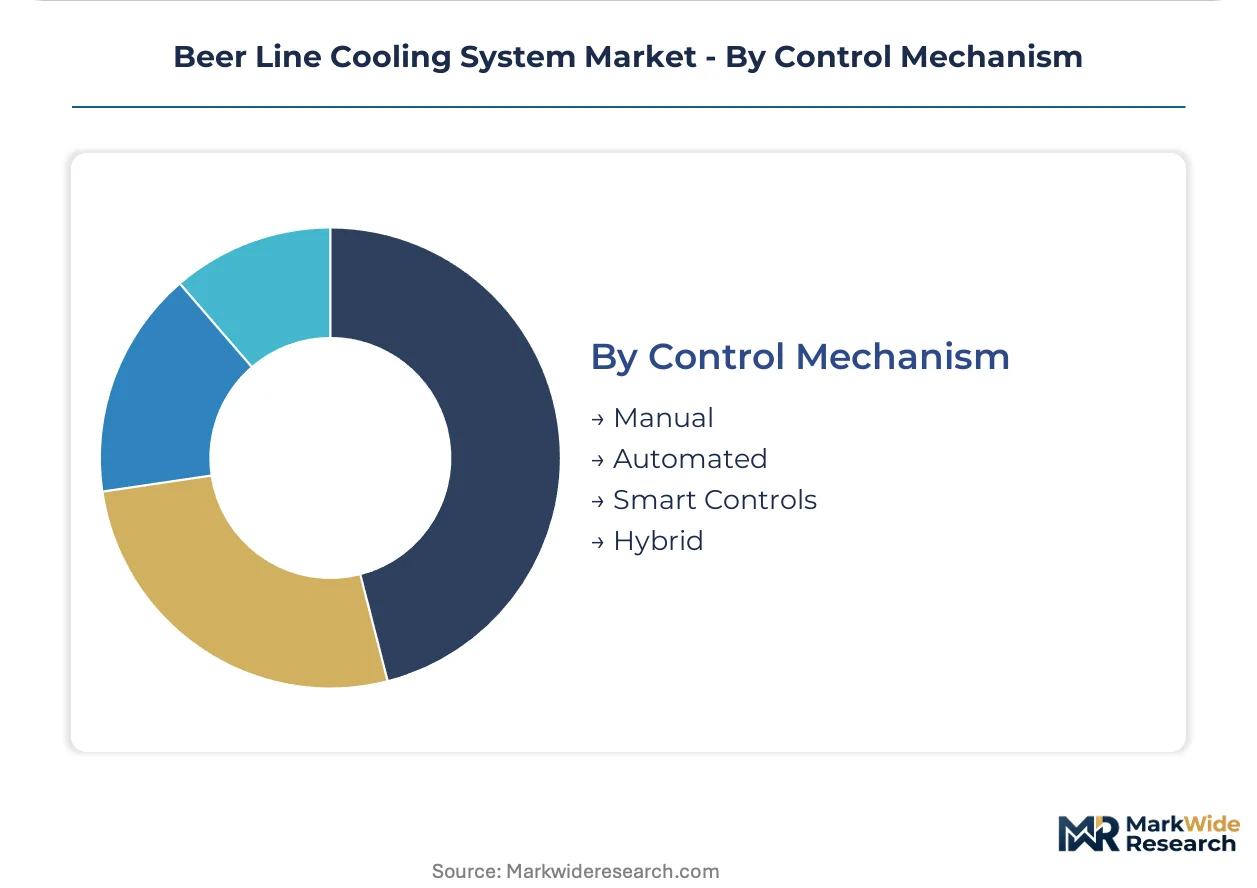
Control Mechanism:
Compliance documentation burden and labor cost trajectories are automating temperature monitoring decisions.
- Smart Controls:IoT-enabled temperature logging with cloud-based audit trails reduces waste and simplifies FDA food safety documentation. Chain foodservice operators in the United States facing audit frequency increases specify these systems.
- Automated:Programmable setpoint management with local alarm outputs bridges legacy infrastructure and digital oversight. Mid-size brewpubs in Germany and England adopt these for operational continuity without full connectivity investment.
- Manual:Dial thermostats and visual inspection protocols persist in cost-sensitive independent accounts with low regulatory exposure. Traditional neighborhood bars in Ireland and rural Australia maintain this equipment profile.
- Hybrid:Redundant control pathways combine local automation with remote monitoring capability. High-reliability venues in Singapore and Dubai specify these for critical dispensing operations.
Installed base remains Manual; Smart Controls are climbing the fastest as IoT sensor costs decline and audit documentation requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German stainless steel fabrication clusters anchor equipment supply chains for this market. Copper tube mills in Saxony and Bavaria feed heat exchanger production lines serving domestic brewers and export markets.
Germany
Bavarian beer gardens and Munich's brewing heritage sustain premium cooling infrastructure investment density. The EU F-Gas Regulation mandates hydrofluorocarbon phasedown, accelerating transcritical CO2 system adoption across Baden-Württemberg manufacturing zones. Stuttgart-area component producers are pivoting compressor architectures toward lower-GWP alternatives ahead of compliance deadlines.
United States
Craft brewery taproom expansion in the Pacific Northwest and Southeast generates modular glycol chiller demand for 50-150 foot draw installations. EPA SNAP regulations prohibit R-404A and R-507A in new commercial refrigeration equipment, forcing compressor redesigns before the 2025 compliance window. Multi-state beverage wholesalers in the US Southeast are consolidating procurement decisions toward preferred-supplier frameworks with national service coverage.
Australia
Stadium and festival operators in Queensland and New South Wales drive trailer-mounted mobile cooling unit specifications for temporary dispensing operations. The country's national environmental regulator enforces refrigerant handling certification requirements that create technician hiring bottlenecks during fleet conversion cycles. Sydney and Melbourne event infrastructure vendors are expanding rental fleets for outdoor venue operators.
Brazil
Festival operators in São Paulo and Rio de Janeiro states are purchasing skid-based cooling systems where permanent infrastructure proves uneconomical. ANVISA governs materials contacting beverage lines, specifying food-grade standards for polymer and stainless-steel components. São Paulo's brewing equipment distributors are building mobile rental capabilities to serve seasonal carnival and soccer event demand.
Japan
Urban bars in Tokyo and Osaka specify compact direct-draw systems where floor space commands premium lease rates. METI energy-efficiency standards shape commercial refrigeration equipment specifications for foodservice chains. Nagoya-area fabricators supply short-draw configurations that minimize service dependency for independent neighborhood pubs.
Beer Line Cooling System Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue smart control integration and refrigerant-transition niches. The vendor base spans Danish draft-dispensing heritage firms, Italian in-house component producers, and North American stainless-steel specialists. Three archetypes dominate: integrated cooling-to-tap solution providers, component-focused fabricators with captive glycol pump production, and premium construction standard bearers. Competitive moves concentrate on geographic expansion through distribution partnerships and portfolio diversification into adjacent beverage cooling applications.
Among European specialists, Micro Matic A/S and Celli Group S.p.A. represent contrasting integration strategies. Micro Matic exemplifies the heritage-anchored archetype leveraging draft-dispensing lineage across Nordic markets. Celli Group occupies a position within the vertical-component-control tier through in-house glycol pump assembly production. Perlick Corporation anchors the premium-bar segment archetype in North America. These three firms illustrate how competitive positioning diverges across geographic and tier vectors without requiring uniform strategic approaches.
| Leading Market Players |
|---|
| Micro Matic A/S |
| Celli Group S.p.A. |
| PowerPacker International B.V. |
| Cool Fit Ltd. |
| Bevco, Inc. |
| True Manufacturing Co., Inc. |
| Hoshizaki Corporation |
| Perlick Corporation |
| KegWorks |
| Others |
Value Chain & Pricing Dynamics
Transcritical CO2 compressor redesigns are simultaneously elevating R&D amortization burdens and concentrating procurement leverage among German and Japanese component specialists. This dual pressure reshapes how equipment vendors structure customer contracts and source critical subsystems.
Pricing Analysis
Warranty and predictive maintenance bundling now separates premium-tier vendors from transactional competitors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence and geographic service network density. Pricing pressure stems from copper and aluminum commodity volatility compressing heat exchanger margins. Independent neighborhood bars in Ireland and rural Australia exhibit highest price sensitivity, while chain foodservice operators in the United States prioritize compliance documentation over upfront cost.
Supply Chain Analysis
Certified refrigeration technician scarcity in Stuttgart manufacturing zones and Nagoya fabrication clusters constrains production scaling. Component supply draws from Germany, Japan, and Italy for compressor architectures, copper tube mills, and glycol pump assemblies. Raw material dependencies center on copper tubing, aluminum heat exchanger fins, and food-grade stainless steel. Single-source vulnerability concentrates in CO2-compatible compressor production. Distribution runs through beverage equipment distributors consolidating toward preferred-supplier frameworks with national service coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over glycol pump production and compressor sourcing determines margin capture. Players are pursuing backward integration into component manufacturing to defend positioning.
For Market Incumbents: Deploy captive glycol pump production to offset commodity volatility in heat exchanger inputs. Consolidate field service networks trained in high-pressure refrigerant handling before EPA Section 608 certification bottlenecks intensify. Lock in long-term compressor supply agreements with German and Japanese specialists to preempt allocation risk during fleet conversion cycles. For New Entrants and Emerging Players: Enter via mobile event infrastructure segments in Australia and Brazil where permanent installation economics fail and rental fleet gaps persist. Target festival operators and stadium concessionaires with trailer-mounted units. Pursue predictive maintenance subscription models using pressure sensor telemetry to establish recurring revenue independent of equipment sales cycles. For Investors and Strategic Acquirers: Re-rating potential sits with smart control integrators given IoT-enabled temperature logging adoption acceleration and FDA audit documentation tightening. Long-term viability favors vendors bridging BACnet and Modbus protocol mismatches for retrofit deployments. Watch refrigerant handling certification completion rates as inflection indicator for service capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glycol Pump Manufacturing | Captive production of pump assemblies insulates Celli Group from supplier concentration risk. |
| Transcritical CO2 Platform Launch | EPA SNAP compliance deadlines force compressor redesigns for North American market access. |
| Predictive Maintenance Subscription Rollout | Pressure sensor telemetry enables recurring revenue streams separate from equipment sales. |
| Mobile Event Infrastructure Expansion | Trailer-mounted units address Australian stadium and Brazilian festival operator demand. |
| Smart Control Protocol Integration | IoT-enabled temperature logging reduces FDA food safety audit documentation burden. |
Study Parameters
Document review covered EPA SNAP rulemakings, EU F-Gas Regulation amendments, and FDA food safety codes, complemented by interviews with brewery operations directors, draft system integrators, refrigeration component procurement managers, and beverage distributor category buyers. Secondary validation drew from customs trade data, SEC equipment manufacturer filings, and ANVISA polymer certification databases. Bottom-up demand modeling triangulated against top-down market sizing.
Segment-level outputs across product type, end user, installation configuration, and control mechanism dimensions were generated through the projection horizon. CAGRs were derived from regression analysis against craft brewery taproom expansion trajectories and regulatory compliance deadline schedules. Industry-specific inputs included refrigerant phasedown timelines and IoT sensor cost decline curves.
Revisions become necessary when copper and aluminum commodity volatility exceeds historical bands or when EPA Section 608 certification bottlenecks constrain technician availability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Malt Beverages Market
Alcoholic Beverages
Chocolate Beer Market
Alcoholic Beverages
Edible Alcohol Market
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market
Alcoholic Beverages
Bahrain Alcoholic Beverages Market
Alcoholic Beverages
India Gin Market
Alcoholic Beverages
Chardonnay Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market
Alcoholic Beverages
Luxury Wines and Spirits Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
Commercial Beer Tap System Market
Alcoholic Beverages
Commercial Wine Dispenser Market
Alcoholic Beverages
Global TCD Alcohol DM Market
Alcoholic Beverages
Coffee Beer Market
Alcoholic Beverages
Moscato Wine Market
Alcoholic Beverages
Hard Kombucha Market