
 Moscato Wine Market | 2026-2036
Moscato Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Moscato Wine Market Insights
The capital-intensity divergence between estate-owned Piedmont vineyards and large-scale California bulk operations is bifurcating competitive dynamics. E. & J. Gallo Winery leverages massive distribution infrastructure across North American off-premise channels. Azienda Agricola Saracco sustains artisanal scarcity through limited-production Asti DOCG releases. Barefoot Cellars dominates mass-market still Moscato with aggressive price positioning in supermarket chains.
Moscato wine denotes wines produced primarily from Muscat blanc à petits grains and related Muscat varieties, characterized by pronounced floral aromatics, residual sugar typically ranging from 5 to 150 grams per liter, and moderate alcohol levels often below 7% ABV for Asti styles. Its primary commercial purpose centers on accessible, fruit-forward consumption occasions targeting younger and newer wine drinkers. Sparkling Moscato commands premium positioning in on-premise and celebratory settings, while still variants anchor volume in retail. Online retailers represent the fastest-growing sales channel as direct-to-consumer platforms reshape wine distribution economics.
EFSA and DG Agriculture frameworks govern EU labeling, origin designation, and sweetness classification for Moscato wines, while the Alcohol and Tobacco Tax and Trade Bureau oversees US federal compliance for alcohol content and appellation claims. These regulatory structures shape product formulation decisions and market access costs on both sides of the Atlantic. Stakeholders must monitor evolving digital-age labeling requirements and e-commerce alcohol shipping regulations as channel mix continues shifting.
Market Dynamics
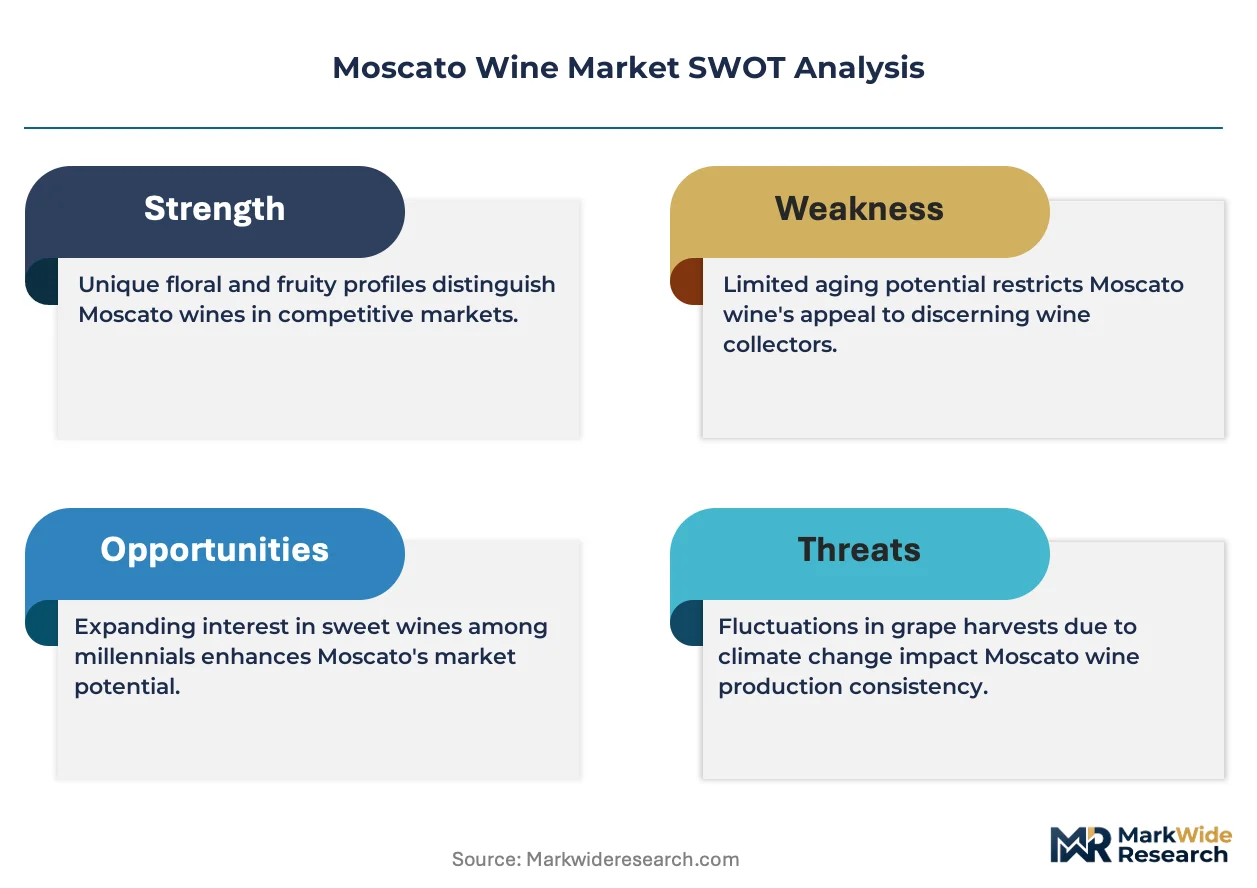
The Moscato wine market is bifurcating around production scale: estate-owned Piedmont vineyards command scarcity premiums through DOCG-certified Asti production, while bulk operations in California's Central Valley compete on volume and price accessibility across mass retail channels.
Growth Catalysts
- EFSA Labeling Reforms:The European Food Safety Authority's tightened origin and sweetness disclosure standards are reinforcing consumer trust in premium Asti DOCG provenance, accelerating demand for certified Italian imports.
- On-Premise Hospitality Adoption:United States bars and restaurants are expanding Moscato-by-the-glass programs as younger consumers seek lower-alcohol, sweeter wine alternatives to traditional dry whites.
- Direct-to-Consumer Platforms:Online wine retailers are capturing share from traditional three-tier distribution, enabling boutique Piedmont producers to reach end buyers without distributor markups.
Market Restraints
- Muscat Grape Supply Concentration:Premium Asti DOCG production depends on Muscat blanc à petits grains cultivation concentrated in Italy's Langhe hills, exposing supply to vintage variation and climate risk.
- US Alcohol and Tobacco Tax and Trade Bureau Compliance Costs:Federal appellation verification and alcohol content testing create fixed cost burdens that disadvantage small-volume importers against Gallo-scale distributors.
- Hard Seltzer Substitution:Flavored malt beverages and canned cocktails are capturing younger drinkers seeking sessionable sweetness, compressing Moscato's entry-level positioning.
Strategic Opportunities
- India's Emerging Wine Culture:Urban millennials in Mumbai and Bangalore are developing taste for sweeter wine profiles, creating first-mover advantage for Italian exporters establishing import partnerships.
- Sparkling Moscato in Celebratory Occasions:Prosecco-trained consumers are trading into Asti DOCG for weddings and holidays, expanding premium sparkling positioning beyond traditional dessert wine associations.
- EU Green Deal Agricultural Transition:Carbon footprint labeling and sustainable viticulture incentives are rewarding organic-certified Piedmont estates with preferential retail placement in Northern European markets.
Industry Challenges
- Enologist Talent Scarcity:Traditional Asti spumante production requires specialized knowledge of Charmat method fermentation and residual sugar management, with retiring Piedmont masters outpacing trained replacements.
- Cold Chain Integrity for Export:Temperature-controlled logistics from Italian cellars to US and Asian markets demands capital investment in reefer containers and bonded warehouse infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moscato Wine Market |
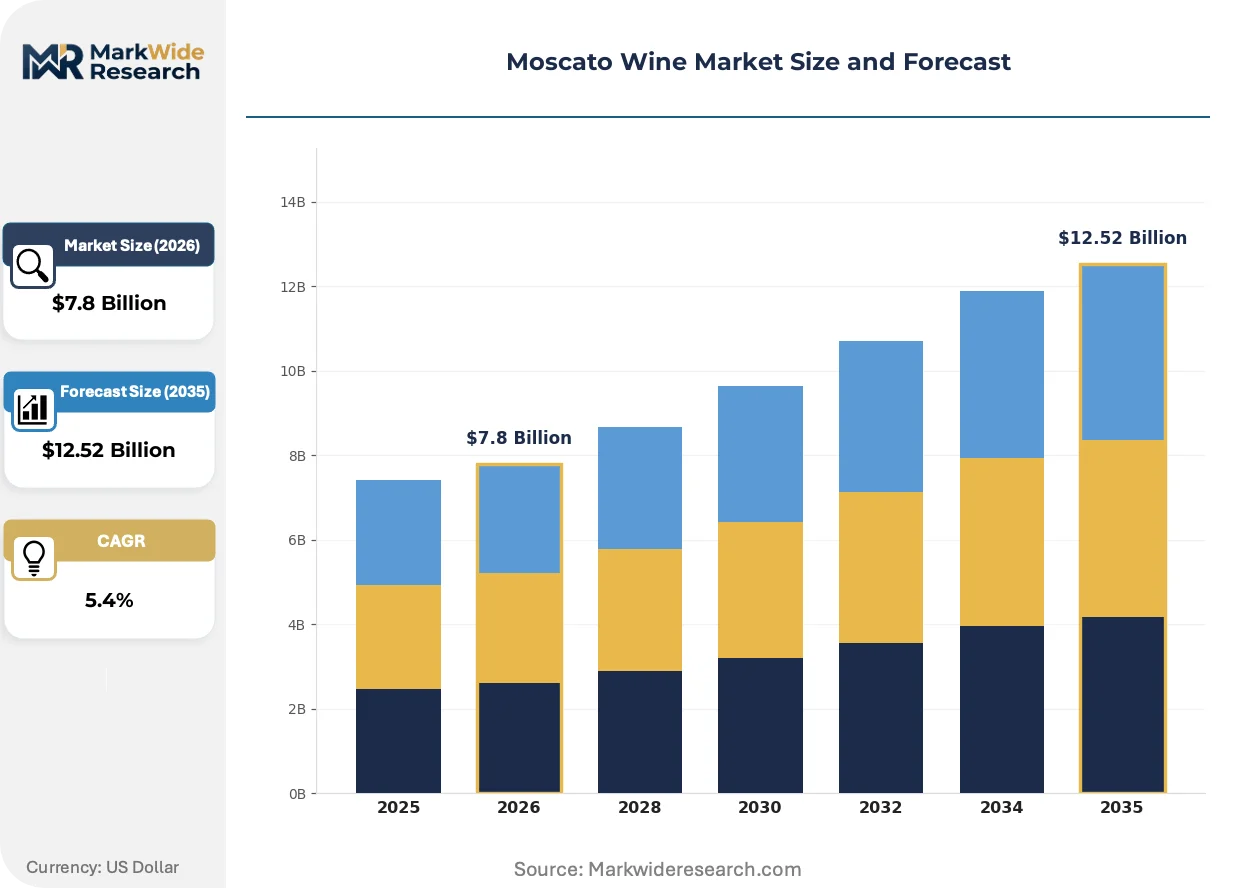
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Demi-Sec, Dry, Sparkling, Still Sales Channel: Online Retailers, Supermarkets, Specialty Stores, Wine Clubs Consumer Demographics: Millennials, Gen X, Baby Boomers, Women Packaging Type: Bottle, Can, Box, Tetra Pak |
| Companies Covered | COPPO S.R.L., MICHELE CHIARLO, Barefoot Cellars, Azienda Agricola Saracco, Stella Rosa, Sutter Home Winery, Inc., Bartenura, La Spinetta, E. & J. Gallo Winery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moscato Wine Market Trends and Innovations
Digital traceability and precision viticulture are reshaping how Moscato producers authenticate origin and optimize harvest timing. Three developments are restructuring competitive advantage across the value chain.
Precision fermentation monitoring using IoT-enabled tank sensors is displacing traditional manual brix testing in Asti DOCG cellars. Saracco and comparable artisanal producers are adopting real-time sugar tracking to tighten residual sugar consistency. This technology is compressing batch variation and enabling smaller production runs with reliable sweetness profiles.
REACH-aligned chemical disclosure requirements in European markets are mandating detailed allergen and additive labeling for imported wines. The regulation is forcing reformulation of certain mass-market still Moscatos that rely on permitted but declarable acidity adjusters. Italian exporters to Germany and the Netherlands are responding by simplifying ingredient decks and pursuing organic certification to bypass disclosure complexity.
Subscription-based wine clubs are capturing younger drinkers who prioritize discovery over brand loyalty. These platforms are replacing supermarket aisle browsing as the primary acquisition channel for new Moscato consumers. California-based direct-to-consumer operators are seeing strongest traction among 25-34 year olds seeking curated sweeter wine selections.
Moscato Wine Market Segmentation
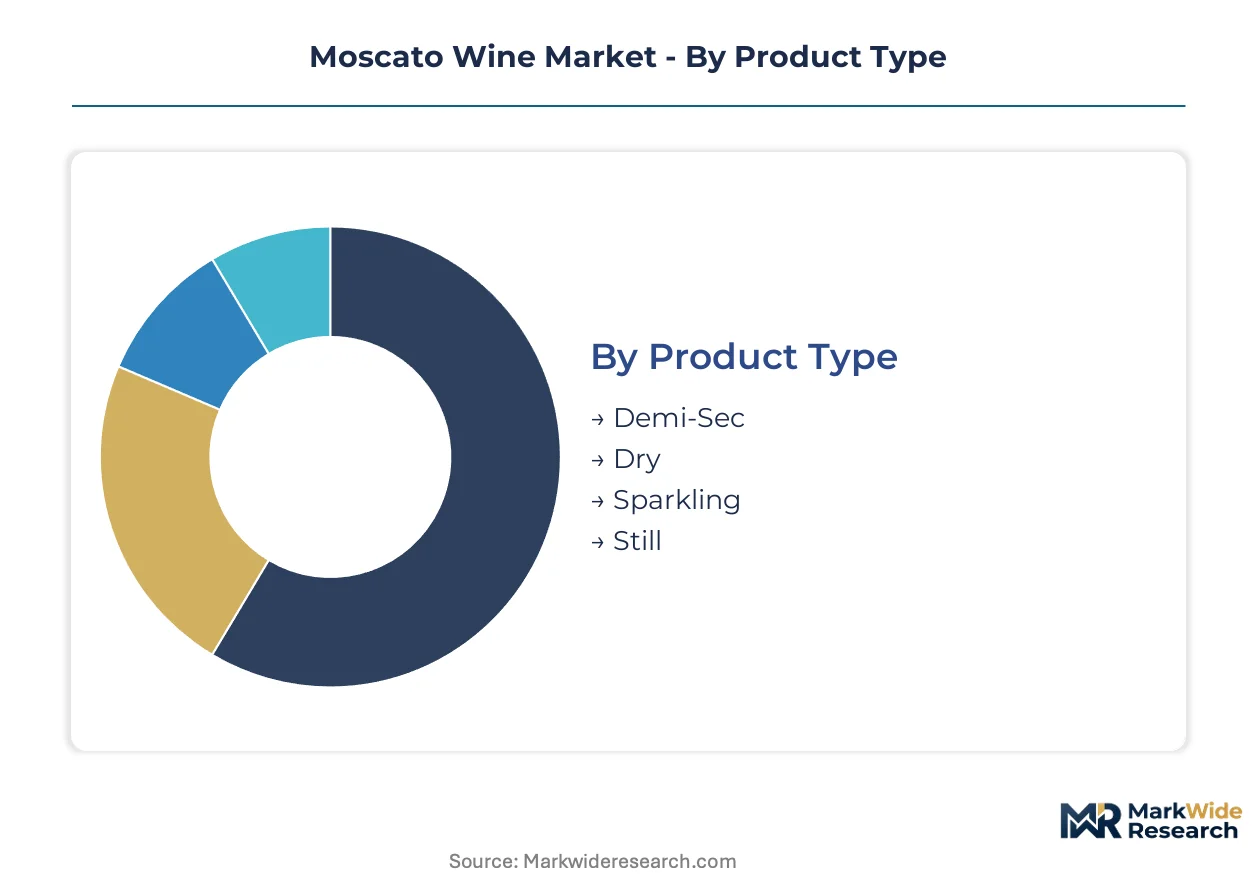
Moscato's positioning across sweetness levels, distribution channels, and generational cohorts determines vulnerability to hard seltzer substitution and direct-to-consumer disruption. Producers must align formulation and packaging investments with where drinker preferences are fragmenting fastest.
Product Type:
Sparkling and still variants face divergent substitution pressures as hard seltzers target the same sessionable sweetness profile that anchored Moscato's mass-market growth.
- Sparkling:Charmat-method fermentation produces the fine, persistent mousse characteristic of Asti DOCG. Wedding and holiday occasion demand concentrates in Italy's Piedmont region, where DOCG certification commands shelf price premiums in German and Dutch retail.
- Still:Lower production complexity enables California Central Valley bulk operations to flood supermarket chains with sub-premium price positioning. Volume concentrates in US off-premise retail, where Barefoot Cellars and Gallo-scale distributors dominate aisle placement.
- Demi-Sec:Residual sugar levels of 32-50 grams per liter bridge dessert and aperitif occasions. Italian estates pursue this midpoint to capture Prosecco-trained consumers trading into sweeter profiles.
- Dry:Sub-10 grams per liter residual sugar appeals to experienced wine drinkers seeking Muscat aromatics without cloying finish. Limited commercial traction outside niche on-premise programs in New York and San Francisco.
Still Moscato retains volume leadership; Sparkling holds the steepest expansion curve as celebratory occasion positioning displaces dessert wine associations.
Sales Channel:
Channel economics are restructuring around tariff exposure and cold chain requirements, with direct-to-consumer platforms compressing traditional three-tier margins fastest.
- Online Retailers:Temperature-controlled fulfillment from bonded warehouses enables boutique Piedmont producers to bypass distributor markups. Subscription algorithms are displacing supermarket discovery among 25-34 year olds seeking curated sweeter wine selections.
- Wine Clubs:Recurring revenue models prioritize discovery over brand loyalty, capturing younger drinkers who abandoned traditional retail browsing. California-based operators see strongest traction in urban coastal markets.
- Supermarkets:Gallo-scale distribution infrastructure dominates North American off-premise placement, leveraging slotting fee leverage to secure end-cap positioning for mass-market still variants.
- Specialty Stores:Sommelier-curated assortments concentrate DOCG-certified imports in high-income urban zip codes, where provenance storytelling justifies price multiples over bulk alternatives.
Supermarkets retain volume leadership; Online Retailers are gaining share fastest as platform economics reshape wine distribution.
Consumer Demographics:
Generational turnover is accelerating flavor preference shifts, with younger cohorts driving demand for lower-alcohol, sweeter profiles that older drinkers dismiss.
- Millennials:Digital-native acquisition patterns favor subscription discovery and social media-influenced trial. Urban millennials in Mumbai and Bangalore are developing taste for sweeter wine profiles, creating first-mover openings for Italian exporters.
- Women:Primary household wine purchasers show higher incidence of Moscato trial in US market research, with floral aromatics and moderate ABV aligning with sessionable consumption preferences.
- Gen X:Established brand loyalty and higher disposable income support premium Asti DOCG trading, particularly in celebratory gift-giving occasions.
- Baby Boomers:Declining category participation as dry wine preferences solidify; residual concentration in traditional dessert wine occasions.
Women retain volume leadership; Millennials are expanding most quickly as digital-native acquisition patterns reshape category entry.
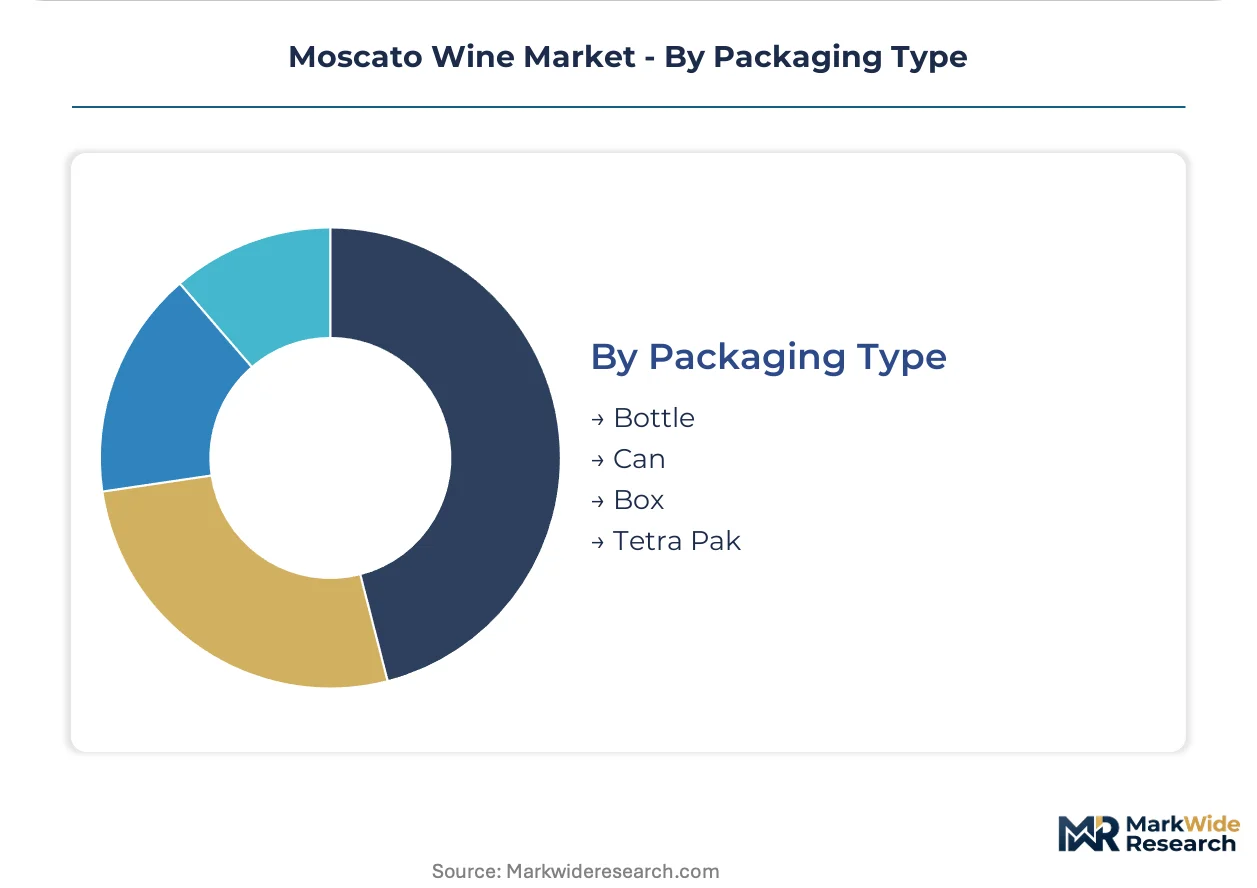
Packaging Type:
Format innovation is fragmenting around occasion portability and sustainability signaling, with aluminum and aseptic options challenging glass bottle hegemony.
- Bottle:750ml standard remains the default for DOCG-certified Asti, where label real estate communicates provenance and production method. Italian estates resist format experimentation to protect premium positioning.
- Can:Single-serve 250ml aluminum formats target outdoor and festival occasions, where glass restrictions and portability needs align with younger drinker consumption patterns. Hard seltzer packaging infrastructure enables supplier crossover.
- Box:Bag-in-box 3-liter formats concentrate in European supermarket private label, where value positioning and reduced per-milliliter cost drive repeat purchase.
- Tetra Pak:Aseptic carton technology enables ambient distribution in emerging markets with limited cold chain infrastructure, though wine category adoption lags juice and dairy applications.
Bottle retains volume leadership; Can is climbing the fastest as occasion portability and hard seltzer crossover reshape format acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across consuming markets, with Italy running substantial trade surpluses in DOCG-certified Asti while the United States absorbs bulk still volumes from domestic Central Valley production. Germany and the Netherlands anchor European import demand through preferential retail placement of certified provenance. Asian markets present asymmetric growth profiles as urban millennials in India and established drinkers in Japan pursue divergent sweetness preferences.
United States
On-premise hospitality venues in New York and California are expanding Moscato-by-the-glass programs as younger consumers seek lower-alcohol alternatives. The Alcohol and Tobacco Tax and Trade Bureau enforces federal appellation verification and alcohol content testing that creates fixed cost burdens for small-volume importers. California's Central Valley concentrates bulk still production where Gallo-scale distributors leverage massive infrastructure across supermarket chains.
Germany
Prosecco-trained consumers in Berlin and Munich are trading into Asti DOCG for celebratory occasions, expanding premium sparkling positioning. REACH-aligned chemical disclosure requirements mandate detailed allergen and additive labeling that forces reformulation of certain mass-market imports. The Rhine-Main region concentrates wine import logistics where temperature-controlled bonded warehouses enable efficient distribution to Northern European markets.
Italy
Piedmont's Langhe hills anchor global supply of Muscat blanc à petits grains for DOCG-certified Asti production, with estate-owned vineyards commanding scarcity premiums. EFSA tightened origin and sweetness disclosure standards that reinforce consumer trust in premium provenance and accelerate demand for certified domestic releases. Asti DOCG production concentrates around the provinces of Asti and Alessandria where traditional Charmat-method cellars face enologist talent scarcity as retiring masters outpace trained replacements.
India
Urban millennials in Mumbai and Bangalore are developing taste for sweeter wine profiles, creating first-mover advantage for Italian exporters establishing import partnerships. The Food Safety and Standards Authority of India governs additive thresholds and labeling requirements for imported alcoholic beverages. Maharashtra state concentrates domestic wine distribution infrastructure where specialty retailers in Mumbai's Bandra and Lower Parel districts curate emerging import selections.
Japan
Established wine drinkers in Tokyo and Osaka maintain preference for drier profiles, limiting Moscato penetration to dessert wine occasions and female-targeted marketing. The Ministry of Economy, Trade and Industry oversees food labeling standards including alcohol content and origin disclosure for imported wines. The Kanto region concentrates premium on-premise consumption where sommelier-curated programs in Ginza and Roppongi districts feature limited Asti DOCG placements.
Moscato Wine Market Competitive Landscape
Concentration sits with estate-owned Piedmont vineyards and Gallo-scale distributors operating at opposite ends of the production scale spectrum. The competitive field splits between artisanal scarcity players leveraging DOCG certification and mass-market volume operators competing on price accessibility across retail channels. Two strategic archetypes dominate: heritage Italian estates commanding provenance premiums through limited releases, and California-based bulk producers flooding supermarket aisles with aggressive slotting fee leverage. Dominant competitive moves include direct-to-consumer platform expansion bypassing traditional three-tier distribution, and organic certification pursuit to secure preferential retail placement under EU Green Deal agricultural incentives.
Within the heritage estate tier, Azienda Agricola Saracco and La Spinetta exemplify artisanal scarcity strategies through DOCG-certified Asti production. Among mass-market operators, Barefoot Cellars and E. & J. Gallo Winery occupy positions defined by scale-driven distribution infrastructure across North American off-premise channels. These named entities represent the bifurcation between provenance-authenticated premium positioning and price-accessible volume dominance that structures competitive dynamics across the value chain.
| Leading Market Players |
|---|
| COPPO S.R.L. |
| MICHELE CHIARLO |
| Barefoot Cellars |
| Azienda Agricola Saracco |
| Stella Rosa |
| Sutter Home Winery, Inc. |
| Bartenura |
| La Spinetta |
| E. & J. Gallo Winery |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day harvest-to-bottle lead times for Asti DOCG producers compress inventory windows while amplifying scarcity premiums in Piedmont, directly linking supply-chain tightness to pricing power for estate-owned vineyards against California bulk operations.
Pricing Analysis
The customization-premium spread separates DOCG-certified Asti releases from mass-market still variants by a factor driven by certification grade and provenance storytelling. Three-tier pricing structure across premium, standard, and economy levels dominates: estate-bottled Piedmont DOCG commands top tier, private-label supermarket placements anchor bottom tier, and regional Italian still Moscatos occupy middle ground. Cost compression in the economy tier intensifies because hard seltzer substitution pressures shelf-space economics. Millennial trial-seekers through wine clubs show lowest price sensitivity; supermarket bulk buyers exhibit highest.
Supply Chain Analysis
Strategic-stockpile preferences dominate among Asti DOCG producers who cellar reserve vintages against climate variation, while California bulk operators run just-in-time grape contracts with Central Valley growers. Supply concentrates in Italy, the United States, and Australia for Muscat cultivation and wine production. Production rests on Muscat blanc à petits grains grapes, glass bottle supply, and cold-chain logistics infrastructure. Single-source vulnerability sits with Piedmont's Langhe hills for premium grape supply. Distribution runs through three-tier wholesale in the United States, direct-to-consumer platforms in Northern Europe, and bonded warehouse networks in Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Moscato wine sits in early-cycle expansion as on-premise hospitality adoption and direct-to-consumer platform growth extend category penetration beyond traditional dessert wine occasions into sessionable aperitif positioning.
For Market Incumbents: Secure DOCG certification moats through vineyard acquisition in Asti and Alessandria provinces, insulating against bulk import erosion. Deepen vertical integration into temperature-controlled logistics to protect cold-chain integrity for export markets. Channel control through exclusive sommelier partnerships in Tokyo and New York defends premium positioning against Gallo-scale distributor encroachment.
For New Entrants and Emerging Players: Lead with subscription-based discovery platforms targeting Mumbai and Bangalore urban millennials where import partnership infrastructure remains underdeveloped. White-space concentrates in India's emerging wine culture and in demi-sec sparkling positioning for Prosecco-trained celebratory occasions. Go-to-market angle: curated Italian estate portfolios bypassing traditional three-tier markups through bonded warehouse direct fulfillment.
For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned Piedmont estates facing enologist succession gaps without next-generation management. Long-term viability frames around DOCG-protected origin designation sustaining pricing power through generational turnover. Acquisition archetype: artisanal producers with organic certification and established direct-to-consumer subscriber bases. Signal to watch: EFSA enforcement intensity on sweetness disclosure standards tightening import compliance costs for mass-market competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| DOCG Certification Investment | EFSA labeling reforms reward certified Piedmont producers with preferential German and Dutch retail placement. |
| Direct-to-Consumer Platform Launch | Subscription algorithms displace supermarket discovery among 25-34 year olds seeking curated sweeter wine selections. |
| Organic Certification Pursuit | EU Green Deal agricultural incentives secure shelf positioning in Northern European markets demanding carbon footprint labeling. |
| Cold Chain Infrastructure Expansion | Reefer container and bonded warehouse investment protects Asti DOCG quality through temperature-controlled export logistics. |
| India Import Partnership Establishment | FSSAI compliance pathways in Maharashtra state unlock first-mover positioning among Mumbai and Bangalore urban millennials. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, EU regulatory filings, and bonded warehouse import databases. Primary interviews engaged enologists at Asti DOCG cellars, procurement directors at North American distributors, sommeliers in Tokyo and New York on-premise programs, and supply planners at California Central Valley bulk operations. Secondary validation drew from EFSA guidance documents, Alcohol and Tobacco Tax and Trade Bureau compliance bulletins, and temperature-controlled logistics trade publications. Bottom-up volume modeling triangulated against top-down category spending analysis.
Segmentation dimensions modeled span product type across sparkling, still, demi-sec, and dry variants; sales channel through online retailers, wine clubs, supermarkets, and specialty stores; consumer demographics across generational cohorts; and packaging format from traditional bottle to aluminum can. CAGRs derived from category velocity trends and channel shift assumptions across the projection horizon. Forecast inputs incorporated climate vintage variation patterns and hard seltzer substitution elasticity estimates.
The analysis sits within stated boundaries; outcomes outside sustained on-premise hospitality recovery or stable EU-India trade terms would require recalibration. Forecasts reflect assumptions around generational taste preference persistence and regulatory enforcement continuity. Revision becomes warranted when hard seltzer innovation crosses sweetness-alcohol thresholds that accelerate Moscato displacement or when EFSA disclosure mandates trigger mass-market reformulation costs exceeding importer absorption capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
White Wine Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
Irish Whiskey Market
Alcoholic Beverages
Gluten-Free Beer Market
Alcoholic Beverages
Spirit-Based RTD Mixes Market
Alcoholic Beverages
Saffron Beer Market
Alcoholic Beverages
India Gin Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Puncheon Barrel Market
Alcoholic Beverages
Japan Beer Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
Cider and Perry Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Canada Tequila Market