
 Hogshead Barrel Market | 2026-2036
Hogshead Barrel Market Size, Share, and Industry Trends Forecast 2026-2036
Hogshead Barrel Market Outlook
Char-level specification upgrades across medium-plus and heavy-char tiers is collapsing the gap between premium bourbon programs and mass-market offerings. Independent Stave Company leverages its stave seasoning yards in Missouri and Kentucky to control raw material quality from forest to finished barrel. Buffalo Trace Distillery sustains one of the largest single-site aging inventories in North America, anchoring demand for consistent hogshead supply at scale. Kelvin Cooperage competes through family-operated craftsmanship combined with modern milling precision, occupying a mid-tier position between industrial cooperages and boutique suppliers.
A hogshead barrel is a large-capacity cask, traditionally constructed from American white oak or European oak staves with a typical capacity range of 230–250 liters, featuring a bulging cylindrical body bound by metal hoops and designed for liquid maturation or bulk transport. The wooden product type dominates bonded spirits applications where oak lactones and tannin extraction govern flavor development, while composite variants serve chemical transport where inert lining prevents contamination. Within applications, alcohol storage generates the deepest margin pools due to multi-year holding periods and brand-critical quality outcomes, whereas food processing represents a faster-growing segment driven by fermented product expansion and pickling operations.
The FDA governs food-contact surfaces and finishing substances for barrels used in beverage and food applications, while the EPA regulates volatile organic compound emissions from cooperage toasting and charring operations. The EU's REACH framework restricts certain wood preservatives and surface treatments, compelling exporters to maintain dual compliance documentation for transatlantic shipments. Stakeholders must monitor evolving fire-safety codes for on-site aging warehouses and assess whether carbon-accounting rules will eventually credit extended barrel reuse cycles in spirits production.
Market Dynamics
Scotch whisky distillers are driving capacity expansion across cooperage networks as extended maturation programs require larger-format casks with standardized char profiles. This structural pull is reshaping supplier relationships and raw material sourcing patterns across the oak stave supply chain.
Growth Catalysts
- EU F-Gas Regulation:Compliance mandates for low-global-warming-potential materials in transport and storage applications are accelerating adoption of wooden hogsheads over composite alternatives in European spirits logistics.
- Speyside Distillery Cluster:Concentrated investment in aging warehouse infrastructure across Scotland's northeast is generating sustained demand for 250-liter capacity barrels with heavy-char specifications.
- Oak Lactone Extraction Science:Advances in stave seasoning and toasting protocols are enabling distillers to achieve targeted flavor compounds faster, validating larger cask formats for premium product lines.
Market Restraints
- American White Oak Supply Concentration:Dependence on Appalachian and Ozark forest regions for stave-quality timber creates vulnerability to climate-driven harvest disruptions and export quota fluctuations.
- REACH Surface Treatment Restrictions:The EU's chemical framework limits certain wood preservatives and finishing agents, forcing dual-compliance production lines for transatlantic shipments.
- Steel Hoop Price Volatility:Galvanized metal binding components face input cost pressure from energy-intensive smelting operations, compressing margins on standard-grade barrel production.
Strategic Opportunities
- India Fermented Foods Segment:Traditional pickling and aging practices in Maharashtra and Karnataka present untapped demand for food-grade hogsheads with FDA-compliant linings.
- Carbon Accounting Integration:Extended barrel reuse cycles in spirits production may qualify for emissions credits under evolving EU Green Deal implementation rules.
- Direct Cooperage Relationships:Distillers are bypassing distributors to contract stave-to-finished-barrel programs, capturing quality control and traceability premiums.
Industry Challenges
- Master Cooper Apprenticeship Gaps:The skilled trade pipeline struggles to replace retiring craftsmen in Kentucky and Scotland, constraining capacity expansion timelines.
- Fire-Safe Warehouse Retrofitting:Aging facilities in Scotland's Highland region require sprinkler system upgrades and structural reinforcement to meet revised on-site storage codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hogshead Barrel Market |
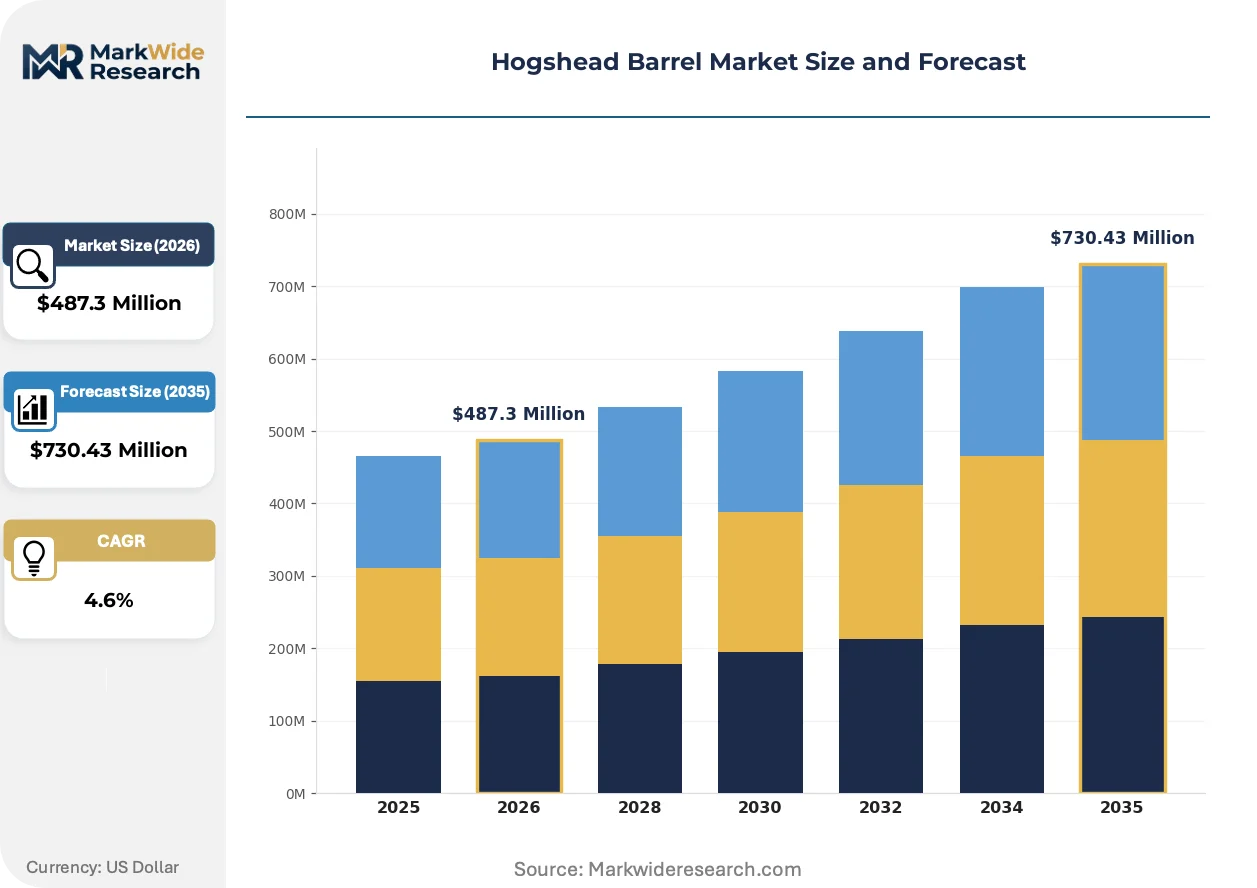
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden, Metal, Composite, Fiberglass Application: Alcohol Storage, Chemical Transport, Food Processing, Agricultural Use End User: Beverage Industry, Pharmaceutical Companies, Food Manufacturers, Distilleries Capacity: 100 Liters, 200 Liters, 250 Liters, 300 Liters |
| Companies Covered | Hogshead, Sazerac, Buffalo Trace Distillery, Independent Stave Company, Kelvin Cooperage, Jack Moore & Co., Speyside Cooperage, Stave & Hoop, Barrel Vault, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hogshead Barrel Market Strategic Shifts
Digital stave tracking and precision toasting controls are converging with traditional cooperage craft, compressing quality variance and enabling batch-level flavor reproducibility. These shifts are redrawing competitive boundaries between industrial-scale and artisanal suppliers.
Precision moisture sensing technology embedded in stave seasoning yards is decomposing the historical reliance on time-based aging protocols. Kentucky distilleries are adopting sensor-driven kiln schedules to accelerate oak preparation without sacrificing extractable compound profiles. This capability is compressing the gap between mass-market cooperages and heritage producers on consistency metrics.
REACH compliance documentation requirements for wood preservatives and surface treatments are forcing exporters to maintain parallel production certifications. The regulatory burden falls heaviest on mid-tier suppliers serving both European and North American markets. Dual-track finishing lines are becoming standard infrastructure for transatlantic shippers.
Distillers are consolidating supplier relationships around stave-to-barrel contract programs that bundle raw material sourcing with finished goods delivery. This model displaces spot-market purchasing for aging inventory commitments. Scotland's Speyside region exhibits the most pronounced shift toward captive cooperage arrangements.
Hogshead Barrel Market Segmentation
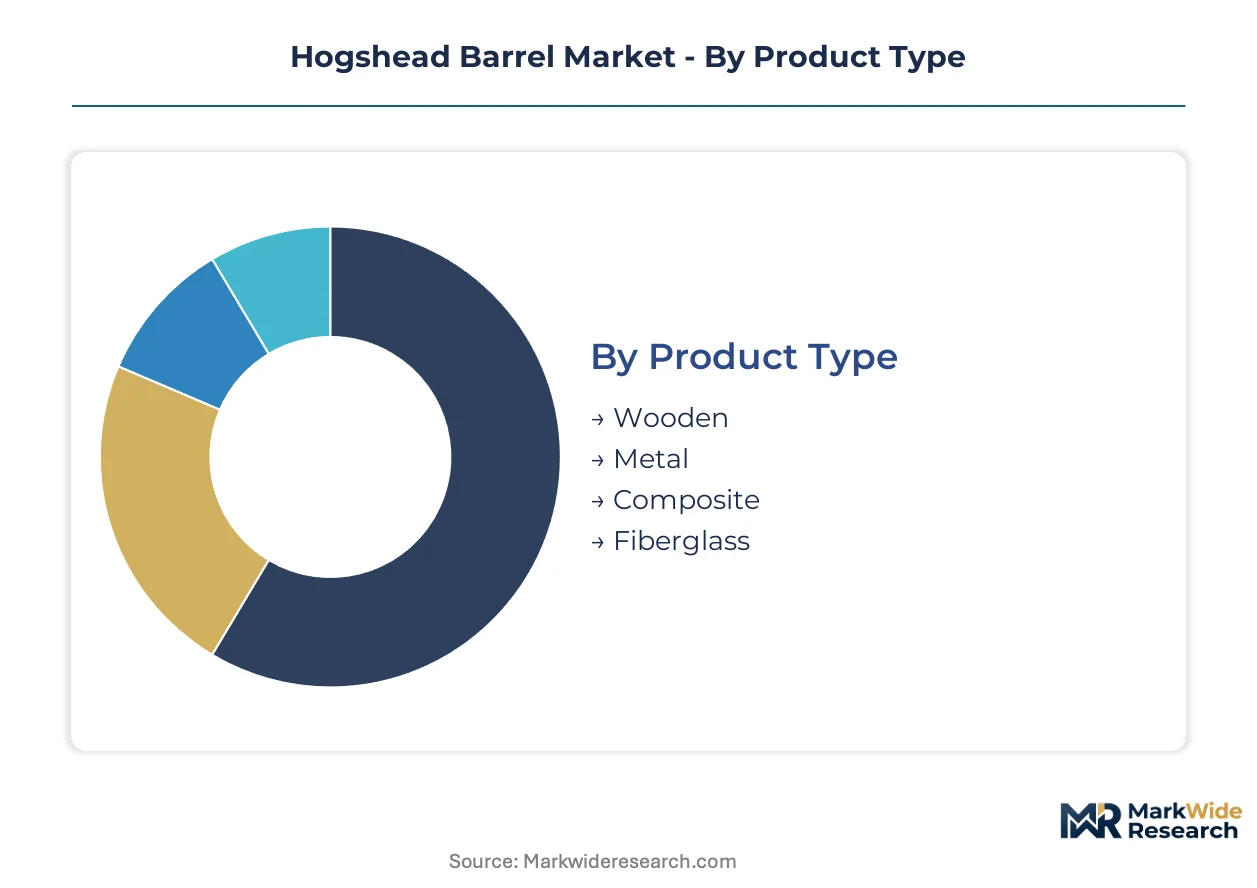
Hogshead barrel segmentation reveals divergent supply chain configurations across material classes and end-use specifications. Distillers, chemical handlers, and food processors each impose distinct performance thresholds that reshape manufacturing priorities and geographic sourcing patterns.
Product Type:
Wooden variants dominate domestic maturation programs across Kentucky and Scotland, while composite and metal formats concentrate in export-oriented chemical logistics.
- Wooden:American white oak and European oak staves deliver extractable oak lactones and tannins for spirits maturation. Scottish Speyside distillers and Kentucky bourbon programs anchor demand for heavy-char specifications with standardized 250-liter capacity.
- Metal:Stainless steel and aluminum constructions serve chemical transport where inert surfaces prevent contamination. REACH-compliant surface treatments are mandatory for EU-bound shipments, compressing margins on standard-grade production.
- Composite:Reinforced polymer liners bonded to structural shells address corrosion resistance in industrial applications.
- Fiberglass:Lightweight, corrosion-resistant barrels target niche agricultural and marine transport segments.
Wooden construction commands the established base. The steepest expansion runs through composite formats.
Application:
Margin structures diverge sharply between multi-year holding periods and rapid-turn logistics uses.
- Alcohol Storage:Extended maturation cycles in bonded warehouses generate the deepest margin pools. FDA-compliant finishing and fire-safe storage codes govern facility design across US and Scottish operations.
- Food Processing:Fermented product expansion and traditional pickling operations in India and Eastern Europe drive adoption of food-grade linings with FSSAI and FDA dual compliance.
- Chemical Transport:Inert lining requirements and UN-certified stacking strength specifications dominate procurement criteria.
- Agricultural Use:Lower-specification barrels serve feed storage and on-farm liquid handling with minimal regulatory burden.
Alcohol storage anchors revenue concentration. Food processing is gaining share fastest.
End User:
Customer scale determines contract structure, with integrated distillers bypassing distributors for direct cooperage relationships.
- Beverage Industry:Multi-year inventory commitments and brand-critical quality outcomes sustain premium pricing for traceable stave-to-barrel programs.
- Distilleries:Captive cooperage arrangements concentrate in Scotland's Highland region where warehouse expansion timelines constrain capacity.
- Pharmaceutical Companies:GMP-compliant documentation and batch-level traceability requirements elevate specification thresholds.
- Food Manufacturers:FDA food-contact surface rules and accelerated turnover cycles favor standardized, reusable formats.
Distilleries maintain the deepest supplier relationships. Food manufacturers are scaling procurement fastest.
Capacity:
Volume selection correlates directly with maturation science and warehouse economics.
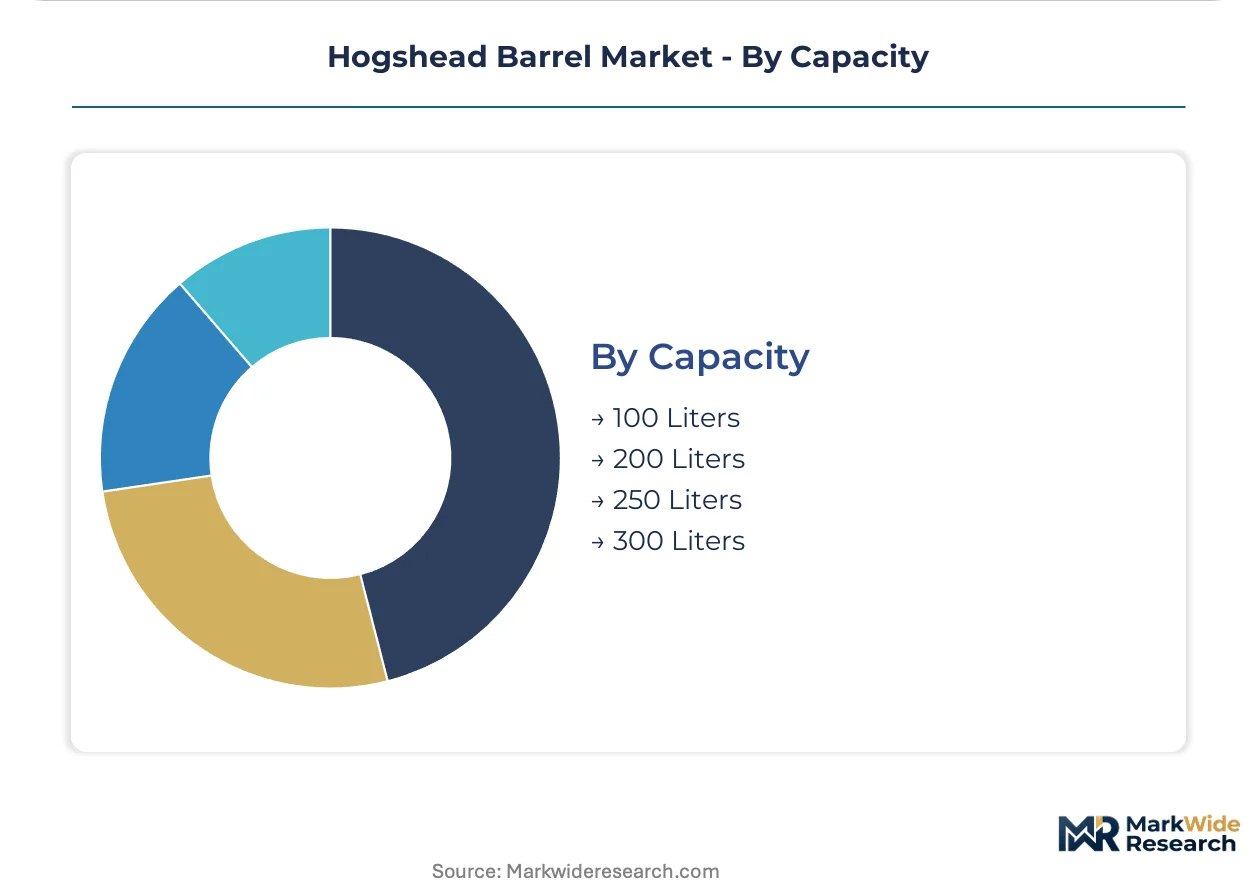
- 250 Liters:The industry standard for Scotch whisky and bourbon maturation balances extraction efficiency with warehouse density. Speyside cooperage networks optimize tooling around this specification.
- 200 Liters:Intermediate format serves craft distilleries and experimental finishing programs where smaller batches enable flavor innovation.
- 100 Liters:Compact barrels address limited warehouse footprints and accelerated extraction protocols.
- 300 Liters:Bulk transport and industrial storage applications favor maximum volume efficiency over flavor development precision.
250-liter capacity dominates installed base. 200-liter formats are climbing the fastest among craft producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scottish cooperages export finished hogsheads to Kentucky distilleries under long-term supply contracts, creating a transatlantic trade corridor that shapes capacity planning on both sides.
United States
Kentucky bourbon programs and Tennessee whiskey distillers drive demand for 250-liter capacity with heavy-char specifications. The EPA regulates volatile organic compound emissions from cooperage toasting operations, forcing facility upgrades across Appalachian stave yards. Louisville and Bardstown anchor North American barrel production, where Independent Stave Company controls seasoning-to-finished-goods pipelines.
United Kingdom
Scotch whisky maturation programs in Speyside and Highland regions require extended-hold inventory with standardized extraction profiles. REACH compliance documentation for wood preservatives and surface treatments dominates export preparation protocols. Dufftown and Craigellachie cluster aging warehouse infrastructure, with cooperage capacity expansion tracking distillery scale-up timelines.
India
Fermented food processing in Maharashtra and Karnataka generates emerging demand for food-grade hogsheads with FSSAI-compliant linings. The FSSAI governs food-contact surfaces and finishing substances for barrels used in traditional pickling operations. Mumbai-Pune industrial corridor distributors are establishing direct relationships with cooperage suppliers to bypass import intermediaries.
Germany
Chemical transport applications favor inert-lined composite barrels for corrosive liquid logistics across Rhine-Ruhr industrial zones. The EU F-Gas Regulation mandates low-global-warming-potential materials in transport equipment, accelerating wooden format adoption for spirits logistics. Hamburg port facilities handle transshipment of cooperage exports to Baltic and Nordic markets.
Japan
Whisky distillers in Yamanashi and Hokkaido prefectures source European oak staves for premium maturation programs with distinct lactone profiles. METI standards govern industrial packaging specifications for chemical and food transport applications. Yoichi and Hakushu production sites maintain captive cooperage relationships to secure traceable stave supply.
Hogshead Barrel Market Competitive Environment
Listed leaders compete with private specialists across capital access and operational flexibility, producing a tiered structure where scale advantages concentrate at the top and craftsmanship differentiation anchors the mid-market. Consolidation pressure runs through industrial cooperages while fragmentation persists among regional stave suppliers and boutique barrel makers. Three archetypes dominate: integrated forest-to-barrel operators controlling seasoning yards, contract-focused cooperages serving distillery direct relationships, and component specialists supplying staves and hoops to third-party assemblers. Capacity expansion and backward integration into stave production represent the dominant competitive moves.
Among heritage cooperage operators, Kelvin Cooperage and Speyside Cooperage exemplify the family-operated craftsmanship tier, occupying positions between industrial-scale producers and artisanal suppliers. Buffalo Trace Distillery represents the captive-demand archetype, anchoring one of North America's largest single-site aging inventories and sustaining consistent hogshead procurement at scale. Jack Moore & Co. sits within the component-specialist segment, supplying binding hardware and stave preparation services to regional barrel assemblers.
| Leading Market Players |
|---|
| Hogshead |
| Sazerac |
| Buffalo Trace Distillery |
| Independent Stave Company |
| Kelvin Cooperage |
| Jack Moore & Co. |
| Speyside Cooperage |
| Stave & Hoop |
| Barrel Vault |
| Others |
Value Chain & Pricing Dynamics
Long-term stave-to-barrel offtake contracts dominate procurement between Kentucky distilleries and Appalachian cooperages, locking in multi-year price visibility while securing priority access to heavy-char specifications ahead of spot-market competitors. This structure concentrates pricing power with integrated forest-to-barrel operators who control seasoning yard capacity across Missouri and Kentucky.
Pricing Analysis
Char-generation pricing gaps separate heavy-char premium tiers from medium-plus and light-char standards across Scotch whisky and bourbon programs. Three-tier pricing structure across premium, standard, and economy levels stratifies by stave provenance, with Independent Stave Company commanding traceability premiums while mid-tier suppliers compete on volume scale. Cost compression in standard-grade production is intensifying because galvanized steel hoop smelting faces energy input volatility. Craft distilleries exhibit highest price sensitivity due to limited warehouse footprint economics, while integrated beverage conglomerates prioritize consistency over unit cost.
Supply Chain Analysis
Inventory lead times for stave-quality American white oak now stretch across three growing seasons, forcing distilleries to extend seasoning yard commitments. Supply concentrates in the United States, Spain, and France, with Appalachian and Ozark forests feeding Kentucky cooperages while European oak draws from French Limousin and Spanish Galicia. Raw material dependencies rest on stave-grade timber, galvanized steel hoops, and REACH-compliant surface treatments. Single-source vulnerability runs through Appalachian forest regions exposed to climate-driven harvest disruptions. Distribution runs through direct cooperage relationships displacing traditional distributor networks across Scotland's Speyside region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrel refurbishment and rechar services represent a service-attach opportunity expanding faster than new barrel hardware as extended reuse cycles qualify for carbon accounting credits under EU Green Deal implementation.
For Market Incumbents: Secure captive seasoning yard capacity in Missouri and Kentucky to defend against stave-quality timber scarcity from climate-driven harvest disruptions. Invest in dual-compliance finishing lines for REACH and FDA surface treatment documentation to maintain transatlantic shipment flexibility. Backward integration into stave production remains the priority lever against spot-market price volatility. For New Entrants and Emerging Players: Anchor in India's Maharashtra and Karnataka fermented food processing segment where FSSAI-compliant food-grade hogshead demand outpaces established supplier presence. Target food manufacturers scaling procurement fastest with FDA-compliant linings for traditional pickling operations. A direct cooperage relationship model bypassing Mumbai-Pune import intermediaries offers the clearest go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated forest-to-barrel operators controlling seasoning-to-finished-goods pipelines across multi-year distillery contracts. Long-term viability over a five-to-ten year window favors acquisition targets with established stave-to-barrel programs and traceability documentation systems. Monitor EU carbon accounting rule finalization as the signal to watch for emissions credit eligibility inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stave Production | Captive supply of Appalachian and Ozark timber secures quality control against climate-driven harvest disruptions. |
| Dual-Compliance Finishing Line Investment | Parallel REACH and FDA certification enables uninterrupted transatlantic shipments to Speyside and Kentucky distilleries. |
| Direct Cooperage Relationship Expansion | Bypassing distributors captures traceability premiums from beverage industry multi-year inventory commitments. |
| Barrel Refurbishment Service Launch | Extended reuse cycles align with EU Green Deal carbon accounting credit eligibility for spirits producers. |
| India Market Entry Partnership | FSSAI-compliant food-grade hogshead supply addresses Maharashtra and Karnataka fermented food processing demand. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from publicly listed cooperage operators, EPA emissions documentation, and EU REACH regulatory filings. Primary interviews engaged master coopers, distillery procurement directors, stave yard operations managers, and forest products sourcing leads. Secondary validation drew from bonded warehouse inventory disclosures, FERC filings for energy-intensive smelting operations, and customs records of transatlantic barrel shipments. Bottom-up demand aggregation from distillery capacity expansion announcements triangulates against top-down market sizing from trade association production statistics.
Segmentation dimensions modeled include material class, application type, end-user scale, and capacity specification across the projection horizon. The analytical framework applies volume and value outputs derived from stave-to-barrel contract value aggregation, seasoning yard capacity utilization rates, and distillery warehouse expansion timelines. CAGRs were computed from installed base growth and replacement cycle analysis. Industry-specific forecast inputs incorporate REACH compliance cost burdens and EPA emissions control capital expenditure requirements.
Decision-makers should treat outputs as directional under assumptions of sustained distillery scale-up timelines and stable Appalachian forest harvest quotas; material deviation from stave-quality timber availability or EU carbon accounting rule implementation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Distillers Malt Market
Alcoholic Beverages
Black Beer Market
Alcoholic Beverages
Spirit-Based RTD Mixes Market
Alcoholic Beverages
Industrial Alcohol Market
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market
Alcoholic Beverages
Asia Pacific Wine Coolers Market
Alcoholic Beverages
Beer Kegs Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Balsam Bottle Market
Alcoholic Beverages
Global Red Wine Market
Alcoholic Beverages
Coffee Beer Market
Alcoholic Beverages
Beer Dispensing Machine Market
Alcoholic Beverages
North America Spirits Market
Alcoholic Beverages
Moscato Wine Market
Alcoholic Beverages
Canada Alcohol E-Commerce Market
Alcoholic Beverages
South America Wine Market