
 Global Tissue Regeneration Market | 2026-2036
Global Tissue Regeneration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tissue Regeneration Market Outlook
Decellularized extracellular matrix technology is reconfiguring how tissue repair products achieve functional integration with host biology. Organogenesis Holdings Inc. leverages porcine-derived matrix platforms to dominate chronic wound applications. Medtronic anchors its position through surgical technique integration across orthopedic and cardiovascular suites. Integra LifeSciences Corporation specializes in dermal regeneration constructs for burn and reconstructive procedures.
Tissue regeneration encompasses the clinical restoration of damaged tissues through scaffold-guided cellular infiltration, growth factor signaling, and stem cell differentiation, typically requiring biocompatible substrates with pore sizes between 100-400 micrometers to permit vascular ingrowth. Scaffolds command the largest revenue share due to their role as the physical substrate enabling cell attachment and extracellular matrix deposition across orthopedics and dermatology. Cell therapy represents the fastest-expanding segment as autologous and allogeneic stem cell platforms advance through late-stage clinical validation in cardiovascular and neurology applications.
The FDA regulates tissue-engineered products under its regenerative medicine framework, while the EMA enforces centralized marketing authorization through its advanced therapy medicinal products pathway. Japan's PMDA operates accelerated review channels for regenerative therapies under its Sakigake designation system. Stakeholders must monitor evolving reimbursement decisions for cell-based therapies across Medicare, national health systems, and private payers to determine commercial viability timelines.
Market Dynamics
FDA's regenerative medicine advanced therapy designation compresses clinical timelines for cell-based platforms, while procurement centralization at US hospital systems and German university hospitals concentrates purchasing power among fewer buyers.
Growth Catalysts
- EMA Advanced Therapy Medicinal Products pathway:Centralized marketing authorization accelerates cross-border commercialization for scaffold and cell therapy developers targeting European hospital networks.
- Japan's Sakigake designation system:PMDA's priority review channel compresses approval timelines for autologous stem cell platforms addressing cardiovascular and neurology indications.
- Aging demographics in developed economies:Chronic wound incidence among populations over 65 drives hospital procurement of dermal regeneration constructs and matrix-guided repair products.
Market Restraints
- Porcine-derived raw material concentration:Reliance on decellularized porcine extracellular matrix creates supply vulnerability to livestock disease outbreaks and religious dietary restrictions in Middle Eastern markets.
- Reimbursement uncertainty:Medicare's evolving coverage determinations for cell-based therapies delay commercial viability timelines for cardiovascular regeneration platforms.
- Autologous cell processing costs:Patient-specific manufacturing requirements limit economies of scale and constrain pricing flexibility relative to allogeneic alternatives.
Strategic Opportunities
- German outpatient wound care clinics:Underpenetrated channel for matrix-based chronic wound products outside hospital procurement networks.
- 3D bioprinting convergence with decellularization:Hybrid manufacturing approaches enable patient-specific scaffold geometries with preserved native extracellular matrix signaling.
- India's CDSCO fast-track pathway:Accelerated review for regenerative therapies creates first-mover positioning in Asia-Pacific's largest chronic disease population.
Industry Challenges
- Bioprocessing talent scarcity:Shortage of cell culture specialists and GMP manufacturing engineers constrains scale-up capacity for late-stage clinical programs.
- ISO 14155 compliance complexity:Clinical investigation standards for medical devices create documentation burden when scaffolds incorporate biologic components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tissue Regeneration Market |
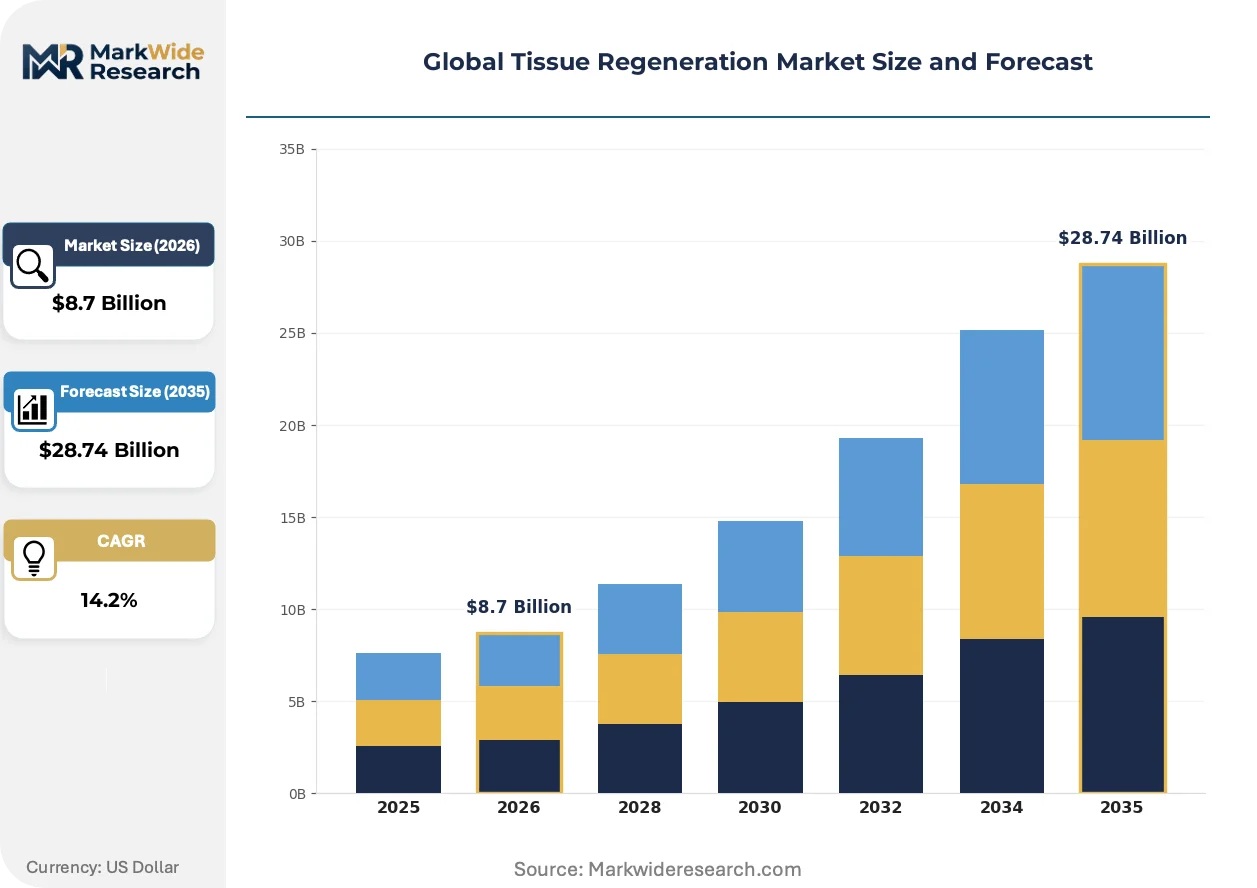
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scaffolds, Growth Factors, Cytokines, Cell Therapy Technology: 3D Bioprinting, Stem Cell Technology, Gene Therapy, Surgical Techniques Application: Orthopedics, Cardiovascular, Dermatology, Neurology End User: Hospitals, Research Laboratories, Clinics, Biotechnology Companies |
| Companies Covered | Organogenesis Holdings Inc., Medtronic, Integra LifeSciences Corporation, Zimmer Biomet, Stryker, MiMedx, ACell, Athersys, Tissue Regenix Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tissue Regeneration Market Strategic Shifts
Cell sourcing and manufacturing automation are compressing production economics while regulatory harmonization efforts across FDA, EMA, and PMDA reshape competitive entry barriers.
Decellularized extracellular matrix derived from human allograft tissue is rendering obsolete synthetic polymer scaffolds in burn and reconstructive applications. Academic medical centers in the United States and Japan are transitioning procurement specifications toward biologically active substrates. This shift compresses addressable market share for polyglycolic acid and polylactic acid platforms that lack native growth factor retention.
REACH regulation amendments on animal-derived materials in medical devices are forcing European manufacturers to document supply chain traceability for porcine and bovine tissue inputs. Industrial consequence includes accelerated investment in recombinant protein expression systems as alternative matrix sources. German and French orthopedic device suppliers are responding with dual-track sourcing strategies to maintain CE marking compliance.
Hospital value analysis committees now require health economic evidence for wound care product formulary inclusion, displacing traditional physician preference item purchasing. Group purchasing organizations consolidate contract negotiations for dermal regeneration products across multi-hospital systems. This behavioral shift is most visible in United States integrated delivery networks where procurement officers override individual surgeon brand requests.
Global Tissue Regeneration Market Segmentation
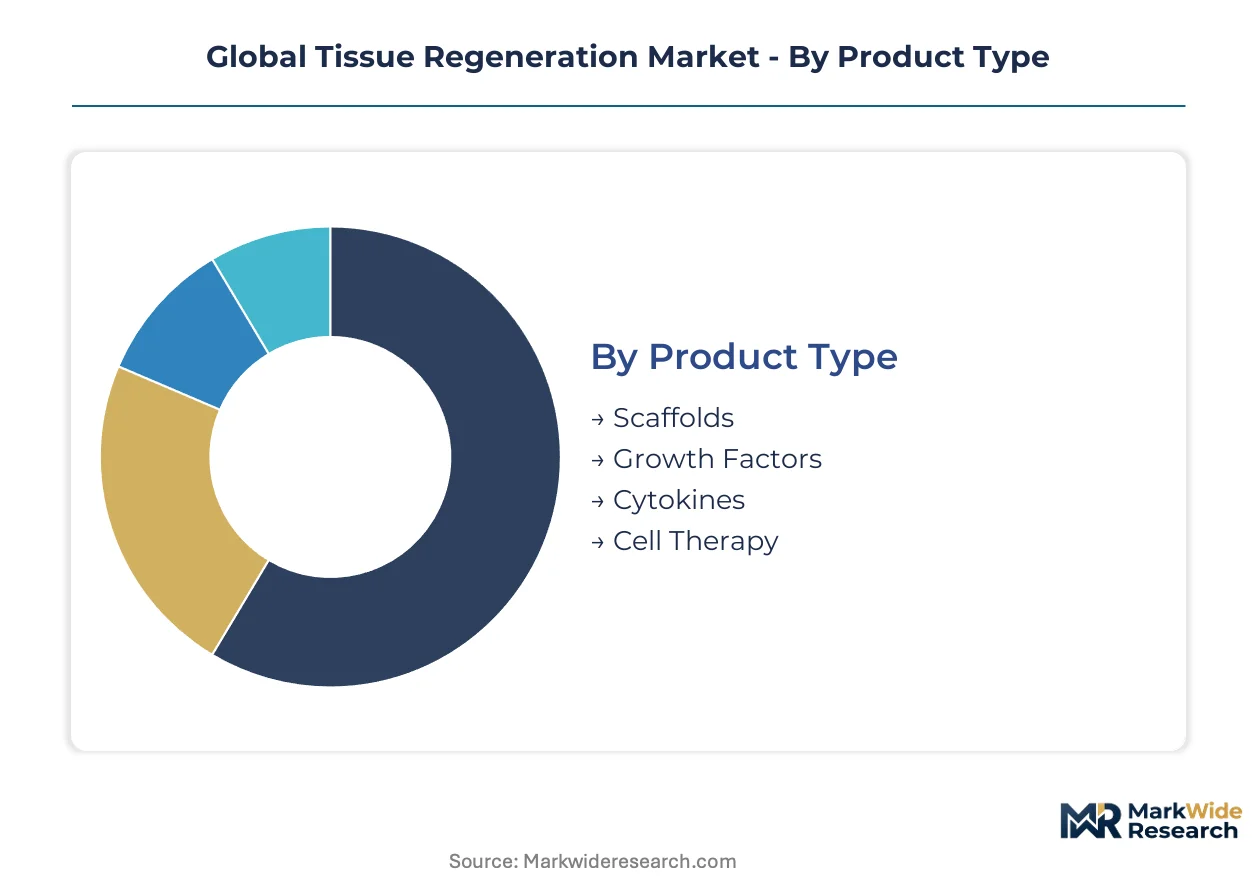
Tissue regeneration markets fragment across biological product categories, manufacturing technologies, clinical specialties, and institutional purchasing channels. Each segmentation axis reveals distinct margin structures, regulatory pathways, and competitive entry barriers that shape vendor positioning.
Product Type:
Mature scaffold platforms coexist with emerging cell therapy modalities at opposite ends of the clinical validation spectrum.
- Scaffolds:Biocompatible substrates with engineered pore architectures between 100-400 micrometers enable vascular ingrowth and extracellular matrix deposition. Demand concentrates in United States burn centers and German university hospitals where decellularized porcine matrices displace synthetic polymers. Supply chain traceability requirements under REACH amendments are forcing European manufacturers toward recombinant protein alternatives.
- Cell Therapy:Autologous and allogeneic stem cell platforms advance through late-stage cardiovascular and neurology trials. Japan's PMDA Sakigake designation accelerates approval timelines for induced pluripotent stem cell applications. Manufacturing automation is compressing production economics for patient-specific therapies.
- Growth Factors:Recombinant signaling proteins direct cellular proliferation and differentiation in wound healing applications.
- Cytokines:Immune-modulatory proteins regulate inflammatory responses during tissue repair processes.
Scaffolds retain volume leadership; cell therapy holds the steepest expansion curve.
Technology:
Cost tiers separate capital-intensive bioprinting systems from established surgical methodologies with minimal equipment requirements.
- 3D Bioprinting:Layer-by-layer fabrication enables patient-specific scaffold geometries with embedded living cells. Research laboratories in the United States and Japan drive capital equipment procurement for vascularized tissue constructs. Hybrid approaches combining bioprinting with decellularized matrix preservation are advancing toward clinical translation.
- Stem Cell Technology:Pluripotent and adult stem cell sourcing platforms underpin autologous therapy manufacturing. Biotechnology companies in Germany and Japan concentrate bioprocessing capacity for cardiovascular regeneration indications.
- Gene Therapy:Viral and non-viral vector delivery modifies cellular behavior for enhanced tissue repair.
- Surgical Techniques:Established operative methods integrate scaffold implantation with conventional reconstructive procedures.
Stem cell technology commands premium pricing; 3D bioprinting is climbing the fastest.
Application:
Customer types range from high-volume orthopedic departments to specialized neurology referral centers with constrained case volumes.
- Dermatology:Chronic wound and burn reconstruction applications drive formulary inclusion of dermal regeneration constructs. United States integrated delivery networks centralize procurement through value analysis committees requiring health economic evidence. Hospital systems override individual surgeon preferences for matrix-based products.
- Orthopedics:Cartilage and bone regeneration scaffolds integrate with arthroscopic and open surgical procedures. German and French orthopedic device suppliers maintain dual-track sourcing strategies for CE marking compliance.
- Cardiovascular:Myocardial regeneration and vascular graft applications advance through cardiac surgery suites.
- Neurology:Neural tissue repair indications remain in early clinical development with limited commercial penetration.
Dermatology retains volume leadership; neurology holds the steepest expansion curve.
End User:
Procurement concentration varies from consolidated hospital systems to fragmented research laboratory purchasing.
- Hospitals:Value analysis committees centralize formulary decisions for wound care and surgical regeneration products. United States group purchasing organizations consolidate contract negotiations across multi-hospital networks. Procurement officers now require outcome-based evidence for dermal matrix inclusion.
- Biotechnology Companies:Cell therapy developers and scaffold manufacturers drive demand for raw materials and manufacturing equipment. CDSCO's fast-track pathway in India attracts first-mover investment for Asia-Pacific market positioning.
- Research Laboratories:Academic medical centers evaluate emerging technologies prior to clinical adoption.
- Clinics:German outpatient wound care facilities represent underpenetrated channels for matrix-based chronic wound products.
Hospitals retain volume leadership; biotechnology companies hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospitals export decellularized matrix platforms to United States burn centers, establishing a transatlantic trade corridor in biologic wound care products.
United States
FDA's regenerative medicine advanced therapy designation compresses approval timelines for cardiovascular stem cell platforms. Medicare coverage determinations for cell-based therapies remain under active review, creating reimbursement uncertainty for developers. Boston and San Francisco biotech clusters concentrate venture financing for autologous cell processing automation.
Germany
REACH regulation amendments enforce supply chain traceability for porcine-derived medical device inputs. EMA's advanced therapy medicinal products pathway accelerates cross-border commercialization for scaffold developers. Baden-Württemberg orthopedic device suppliers deploy dual-track sourcing strategies to maintain CE marking compliance.
Japan
PMDA's Sakigake designation system prioritizes induced pluripotent stem cell applications for neurology indications. Aging demographics above age 65 drive chronic wound incidence in Tokyo and Osaka metropolitan areas. Kansai region academic medical centers transition procurement specifications toward biologically active substrates.
India
CDSCO's fast-track pathway for regenerative therapies attracts first-mover investment targeting Asia-Pacific's largest chronic disease population. Maharashtra and Karnataka biotechnology parks expand GMP manufacturing capacity for cell therapy production. Mumbai and Bangalore hospital systems centralize wound care procurement through value analysis committees.
United Kingdom
Medicines and Healthcare products Regulatory Agency enforces post-Brexit alignment with EMA advanced therapy standards. London and Cambridge regenerative medicine clusters specialize in 3D bioprinting research for vascularized tissue constructs. NHS England's specialized commissioning frameworks determine reimbursement for dermal regeneration products.
Global Tissue Regeneration Market Competitive Environment
Channel-controlling players compete with product-specialist players across hospital procurement networks and research laboratory channels. The vendor base organizes into three tiers: diversified medical technology conglomerates with surgical suite integration capabilities, dedicated regenerative medicine companies with matrix platform specialization, and emerging cell therapy developers with late-stage clinical assets. Consolidation pressure intensifies as group purchasing organizations centralize contract negotiations across multi-hospital systems. Strategic moves concentrate on M&A for bioprocessing capacity and technology licensing for decellularization protocols.
Among diversified medical technology conglomerates, Medtronic and Stryker exemplify channel-control archetypes through surgical technique integration across orthopedic and cardiovascular suites. Within the dedicated regenerative medicine tier, Organogenesis Holdings Inc. and Integra LifeSciences Corporation represent matrix-platform specialists with established chronic wound and burn reconstruction positions. MiMedx occupies a position bridging hospital procurement networks with specialized biologic product portfolios.
| Leading Market Players |
|---|
| Organogenesis Holdings Inc. |
| Medtronic |
| Integra LifeSciences Corporation |
| Zimmer Biomet |
| Stryker |
| MiMedx |
| ACell |
| Athersys |
| Tissue Regenix Group |
| Others |
Value Chain & Pricing Dynamics
Porcine-derived extracellular matrix concentration in United States and German processing facilities anchors margin capture downstream at hospital procurement networks and specialty clinic chains. REACH traceability mandates and livestock disease risk premiums feed directly into pricing power for recombinant protein alternatives.
Pricing Analysis
Next-generation decellularized human allograft scaffolds command premium positioning against prior-generation synthetic polymer platforms and economy-tier porcine matrices. Three-tier pricing structure across premium, standard, and economy levels stratifies by biologic activity retention and FDA regenerative medicine designation status. Cost compression in synthetic polymer tiers is intensifying because academic medical centers are transitioning procurement specifications toward biologically active substrates. Biotechnology companies exhibit lowest price sensitivity due to R&D amortization structures, while German outpatient wound care clinics demonstrate highest sensitivity to per-unit material costs.
Supply Chain Analysis
Extended payment terms from United States hospital systems and supply-chain finance facilities from German orthopedic device suppliers are restructuring working capital requirements for matrix platform manufacturers. Raw material sourcing draws from United States allograft tissue banks, German porcine processing facilities, and Indian recombinant protein expression systems. Decellularization protocol standardization and GMP bioprocessing capacity represent critical component dependencies. Single-source vulnerability concentrates in porcine-derived inputs exposed to livestock disease outbreaks. Distribution runs through group purchasing organizations and integrated delivery networks with consolidated contract negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's regenerative medicine advanced therapy designation and PMDA's Sakigake system are compressing clinical timelines and creating first-mover premium capture for cell therapy platforms.
For Market Incumbents: Pre-empt displacement by recombinant protein alternatives through backward integration into human allograft tissue sourcing and accelerated investment in 3D bioprinting hybrid manufacturing. Secure GMP bioprocessing talent pools in Boston and San Francisco clusters before capability scarcity constrains scale-up capacity for late-stage cardiovascular programs. For New Entrants and Emerging Players: German outpatient wound care clinics represent the most penetrable entry point for matrix-based chronic wound products outside consolidated hospital procurement networks. India's CDSCO fast-track pathway offers regulatory arbitrage for Asia-Pacific market positioning. Target value analysis committee bypass strategies through direct clinician education on health economic outcomes. For Investors and Strategic Acquirers: Capital is best deployed toward cell therapy developers with late-stage cardiovascular assets and established GMP manufacturing footprints. Long-term viability hinges on reimbursement pathway clarity across Medicare and European national health systems. Monitor Medicare coverage determinations for cell-based therapies as the critical inflection signal for commercial viability timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Regenerative Medicine Designation | Accelerates approval timelines for cardiovascular stem cell platforms entering pivotal trials. |
| CE Marking Pathway | EMA's advanced therapy medicinal products route enables cross-border European hospital network access. |
| Hospital System Partnership | Value analysis committee relationships secure formulary inclusion for dermal regeneration constructs. |
| Manufacturing Scale-Up | GMP bioprocessing capacity expansion addresses talent scarcity constraining late-stage clinical programs. |
| Reimbursement Strategy | Medicare coverage determination navigation determines commercial viability for cell-based cardiovascular therapies. |
Study Parameters
A standing panel of GMP manufacturing engineers, hospital procurement managers, regulatory affairs specialists, and formulary directors provided ongoing calibration across primary interview cycles and secondary source validation. FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases anchored quantitative bottom-up modeling. Top-down triangulation cross-referenced venture financing disclosures and academic technology transfer metrics.
Scenario-bracketing around regulatory approval timelines and reimbursement pathway outcomes shaped analytical framework construction across the projection horizon. Segmentation dimensions modeled include product type, technology platform, clinical application specialty, and institutional purchasing channel. CAGRs derived from procedure volume elasticity, pricing trajectory assumptions, and technology substitution curves. Stem cell manufacturing automation rates and decellularized matrix clinical adoption thresholds served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth rates or biologic raw material commodity prices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization progress and reimbursement decision timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Europe Viral Vector Purification Market
Cell & Gene Therapy
Mrna Vaccines and Therapeutics Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
Stem Cell Therapy Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Cell Expansion Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Cell Therapy Technologies Market
Cell & Gene Therapy
Asia-Pacific Viral Vector Purification Market
Cell & Gene Therapy
Retinal Gene Therapy Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market