
 RNAI Technology Market | 2026-2036
RNAI Technology Market Size, Share, and Industry Trends Forecast 2026-2036
RNAI Technology Market Outlook
Oncology applications are repositioning RNAi investment away from broad genetic disorder platforms toward targeted cancer mechanisms. Alnylam Pharmaceuticals dominates commercial RNAi therapeutic validation through its liver-targeted siRNA franchise. Thermo Fisher Scientific leverages reagent and instrumentation scale to anchor supply chain security for drug developers. Arrowhead Pharmaceuticals specializes in extrahepatic delivery, extending addressable disease categories beyond liver-localized targets.
RNA interference denotes a conserved biological pathway wherein double-stranded RNA triggers sequence-specific messenger RNA degradation, typically employing 21–23 nucleotide small interfering RNA duplexes with 2-nucleotide 3' overhangs to silence gene expression. The technology serves industrial and commercial purposes ranging from functional genomics screening to validated human therapeutics requiring precise, durable target knockdown. Small interfering RNA products capture the dominant therapeutic revenue pool given validated manufacturing and established regulatory precedents, while lipid nanoparticle delivery methods command premium positioning due to complex formulation requirements and protected intellectual property estates. Vector-based RNAi retains academic research intensity but faces translational bottlenecks in clinical scalability.
FDA nucleic acid guidance and EMA Committee for Medicinal Products for Human Use opinions shape RNAi clinical trial design, manufacturing quality benchmarks, and post-market surveillance obligations for sponsors. The EPA and OSHA frameworks govern oligonucleotide synthesis scale-up, particularly solvent handling and waste streams at multi-kilogram commercial production facilities. Stakeholders must monitor evolving pharmacovigilance expectations for long-acting gene silencing agents as treatment durations extend and combination regimens proliferate across oncology and cardiometabolic indications.
Market Dynamics
FDA accelerated approval pathways for nucleic acid therapies are compressing clinical-to-commercial timelines, forcing biopharmaceutical sponsors to front-load manufacturing scale-up and regulatory strategy before Phase II data readouts.
Growth Catalysts
- EMA PRIME eligibility:RNAi therapeutics targeting rare diseases gain priority medicines designation, truncating scientific advice timelines and enabling parallel EMA-FDA briefing strategies.
- Oncology pipeline expansion:Tumor-targeted siRNA conjugates are displacing broad genetic disorder platforms as the primary investment focus among venture-backed biotechs.
- Lipid nanoparticle manufacturing:Multi-kilogram commercial production facilities in Massachusetts and California clusters anchor supply security for late-stage drug developers.
Market Restraints
- Input cost volatility:Phosphoramidite monomer and specialized lipid prices fluctuate with semiconductor-grade solvent availability, squeezing contract manufacturing margins.
- Delivery limitation:Extrahepatic tissue targeting remains technically constrained, restricting addressable disease categories despite validated liver-localized mechanisms.
- Substitution threat:Antisense oligonucleotides and CRISPR-based gene editing platforms compete for the same rare disease and oncology indication budgets.
Strategic Opportunities
- Underpenetrated CNS applications:Blood-brain barrier penetration technologies for glioblastoma and neurodegenerative targets remain commercially undeveloped.
- Japanese regulatory tailwind:PMDA's Sakigake designation system offers expedited review for innovative nucleic acid therapies with preliminary clinical evidence.
- Technology convergence:siRNA-antibody conjugates and targeted peptide delivery systems are opening solid tumor categories previously inaccessible to naked RNAi constructs.
Industry Challenges
- Toxicology expertise gap:Qualified preclinical safety assessors for long-acting gene silencing agents remain scarce relative to small molecule and biologic talent pools.
- Capex intensity:Commercial-scale oligonucleotide synthesis suites require specialized containment infrastructure for solvent handling and waste stream management.
- Pharmacovigilance complexity:Extended treatment durations and combination regimens across oncology and cardiometabolic indications strain post-market surveillance systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RNAI Technology Market |
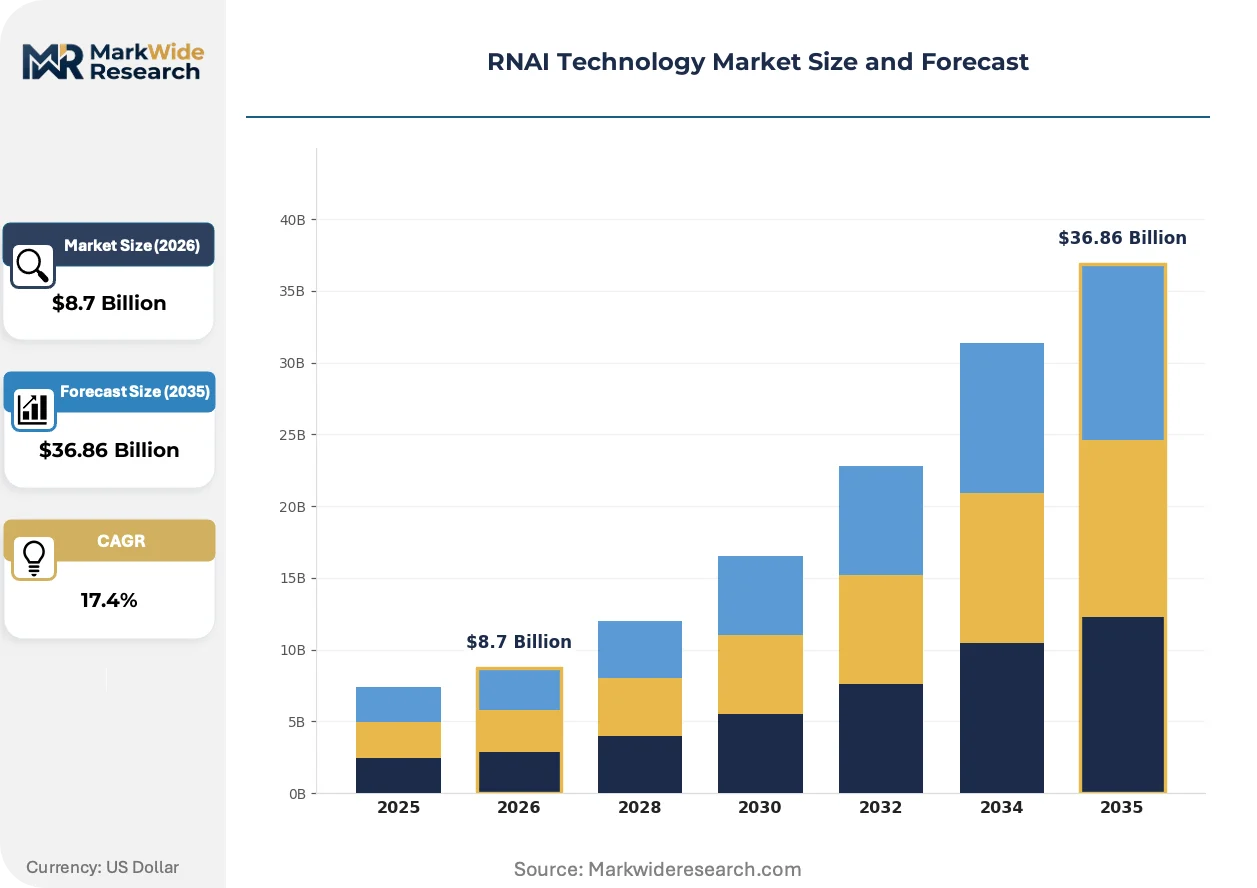
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $36.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antisense Oligonucleotides, Small Interfering RNA, Vector-Based RNAi, MicroRNA Inhibitors Delivery Method: Lipid Nanoparticles, Viral Vectors, Polymer-Based, Electroporation End User: Biopharmaceutical Companies, Academic Research Institutes, Contract Research Organizations, Diagnostic Labs Application: Cancer Therapy, Genetic Disorders, Infectious Diseases, Nervous System Disorders |
| Companies Covered | Alnylam Pharmaceuticals, Thermo Fisher Scientific, Merck KGaA, Arrowhead Pharmaceuticals, Silence Therapeutics, Revvity, GenScript, Promega Corporation, OriGene Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RNAI Technology Market Strategic Shifts
Delivery platform diversification is fragmenting competitive advantage away from liver-targeted franchises toward tissue-specific engineering capabilities. This shift rewards specialized chemistry and formulation expertise over traditional target biology.
GalNAc-siRNA conjugate technology is electrifying hepatocyte-targeted therapeutic development through high-affinity asialoglycoprotein receptor binding. Biopharmaceutical sponsors are adopting this platform across metabolic and cardiovascular portfolios with unprecedented speed. The technology is compressing development timelines for validated liver disease targets while raising barriers for competing delivery modalities.
REACH chemical registration requirements for novel lipid excipients are extending European supply qualification timelines by 12-18 months. Manufacturers must submit full toxicity dossiers for each proprietary lipid component before commercial batch release. This regulatory friction is concentrating European supply relationships among established lipid suppliers with existing registration portfolios.
Integrated development and manufacturing organization contracts are displacing fragmented CMO sourcing for Phase III RNAi assets. Sponsors are consolidating oligonucleotide synthesis, lipid formulation, and fill-finish under single-provider agreements to reduce technology transfer risk. This procurement consolidation is most visible among Massachusetts and California-based biotechs with multiple clinical-stage programs.
RNAI Technology Market Segmentation
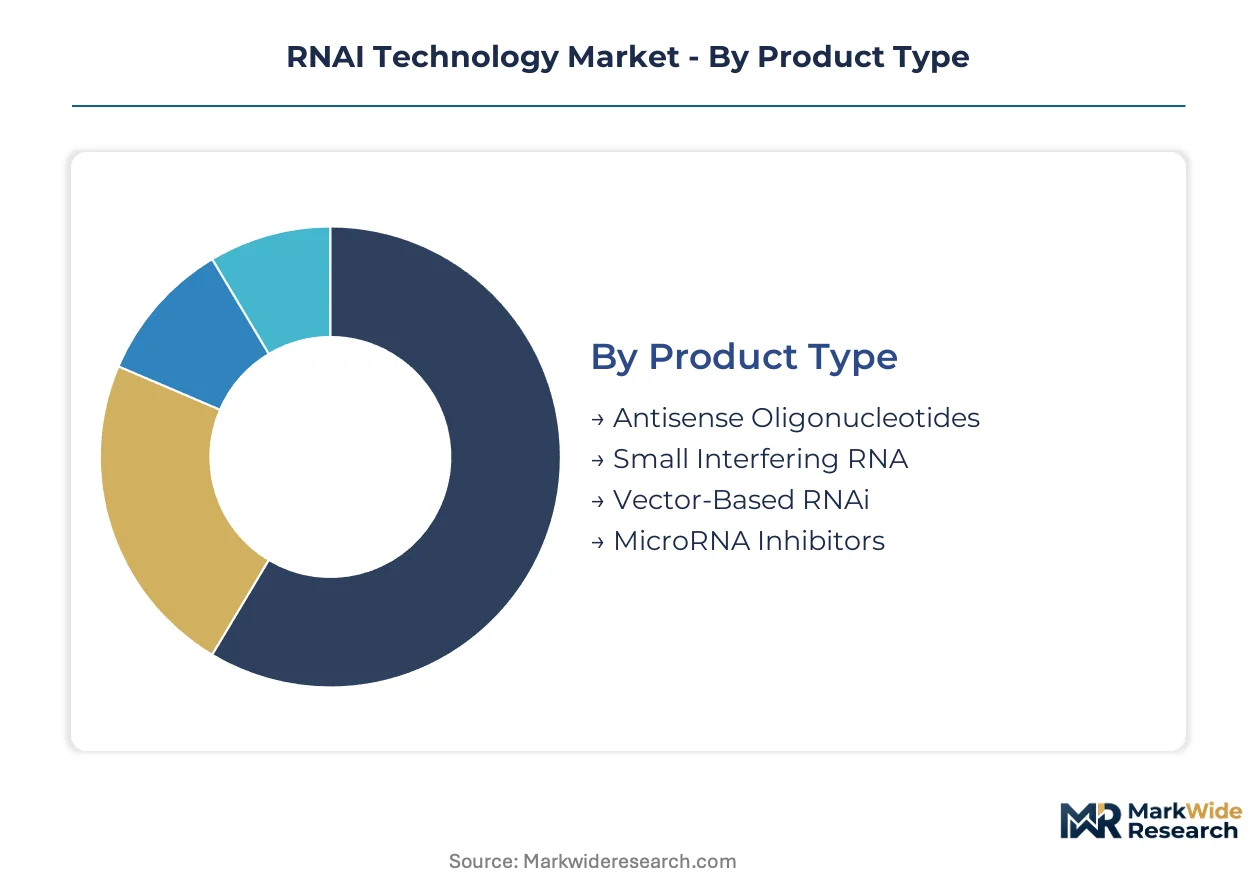
RNAi technology segmentation reveals distinct regulatory and manufacturing requirements across therapeutic modalities. Each product type and delivery method carries specific FDA, EMA, and PMDA approval burdens that shape commercialization timelines and capital allocation strategies for sponsors.
Product Type:
Antisense oligonucleotides and small interfering RNA products face divergent EMA PRIME and FDA accelerated approval pathways based on liver-targeting validation and manufacturing complexity.
- Antisense Oligonucleotides:Single-stranded DNA analogs with phosphorothioate backbones achieve splice modulation through steric hindrance of spliceosome machinery. FDA has granted priority review vouchers for inherited metabolic targets, with Massachusetts-based sponsors dominating late-stage pipelines.
- Small Interfering RNA:21–23 nucleotide duplexes with 2-nucleotide 3' overhangs trigger RISC-mediated mRNA cleavage for durable gene silencing. GalNAc-conjugate chemistry from California clusters commands premium positioning due to validated hepatocyte delivery and established CMC packages.
- Vector-Based RNAi:Adeno-associated and lentiviral constructs enable stable shRNA expression for extended knockdown duration.
- MicroRNA Inhibitors:Antagomir chemistries target endogenous miRNA families with broad regulatory networks.
Small interfering RNA sits at the top of the volume ranking, with vector-based RNAi climbing the fastest as durable expression platforms gain oncology traction.
Delivery Method:
Cost tier stratification separates complex lipid formulations from accessible electroporation systems, with capital requirements ranging from specialized containment suites to standard laboratory equipment.
- Lipid Nanoparticles:Ionizable cationic lipids complexed with siRNA enable endosomal escape and cytosolic release. Multi-kilogram commercial facilities in Massachusetts and California anchor supply security, though REACH registration extends European qualification timelines.
- Viral Vectors:AAV and lentiviral particles achieve nuclear delivery and persistent expression for single-administration regimens. Toxicology expertise gaps for long-acting gene silencing constrain preclinical safety assessment capacity relative to sponsor demand.
- Polymer-Based:Polyethylenimine and dendrimer systems offer synthetic alternatives with reduced immunogenicity profiles.
- Electroporation:Pulsed electrical fields transiently permeabilize cell membranes for naked RNAi uptake in ex vivo applications.
Lipid nanoparticles dominate commercial revenue, with polymer-based delivery gaining share fastest as synthetic alternatives reduce cold-chain dependencies.
End User:
Customer type determines procurement scale and integration depth, from fully outsourced CMO relationships to captive manufacturing investments by top-tier biopharmaceuticals.
- Biopharmaceutical Companies:Integrated development and manufacturing organization contracts consolidate synthesis, formulation, and fill-finish under single-provider agreements to reduce technology transfer risk.
- Academic Research Institutes:Vector-based RNAi retains intensity for functional genomics screening despite translational bottlenecks in clinical scalability.
- Contract Research Organizations:Toxicology expertise scarcity creates service differentiation for qualified preclinical safety assessors.
- Diagnostic Labs:Companion RNAi biomarker development supports patient stratification for oncology and cardiometabolic indications.
Biopharmaceutical companies anchor demand volume, with contract research organizations expanding most quickly as sponsors externalize specialized capabilities.
Application:
Clinical maturity varies sharply across disease categories, with liver-localized mechanisms validated in metabolic targets while CNS penetration remains technically constrained.
- Cancer Therapy:Tumor-targeted siRNA conjugates displace broad genetic disorder platforms as primary venture capital focus. siRNA-antibody conjugates and targeted peptide delivery systems open solid tumor categories previously inaccessible to naked constructs.
- Genetic Disorders:Transthyretin amyloidosis and acute hepatic porphyria indications establish regulatory precedents for rare disease RNAi therapeutics. EMA PRIME eligibility truncates scientific advice timelines for sponsors pursuing parallel EMA-FDA briefing strategies.
- Infectious Diseases:Host-directed RNAi targets viral replication machinery with reduced resistance pressure versus direct-acting antivirals.
- Nervous System Disorders:Blood-brain barrier penetration technologies for glioblastoma and neurodegenerative targets remain commercially undeveloped despite substantial unmet need.
Genetic disorders command current revenue concentration, with cancer therapy showing the steepest expansion trajectory as oncology pipelines displace earlier therapeutic focuses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting RNAi manufacturing investment toward jurisdictions with streamlined nucleic acid oversight, as REACH chemical registration timelines in Europe extend qualification windows by 12-18 months relative to North American and Asian pathways.
United States
FDA accelerated approval pathways for nucleic acid therapies compress clinical-to-commercial timelines, forcing sponsors to front-load manufacturing scale-up before Phase II readouts. Massachusetts and California clusters anchor commercial-scale oligonucleotide synthesis and lipid nanoparticle formulation capacity, with integrated development contracts consolidating synthesis and fill-finish under single-provider agreements.
Germany
EMA PRIME eligibility for rare disease RNAi therapeutics truncates scientific advice timelines and enables parallel EMA-FDA briefing strategies. REACH registration requirements for novel lipid excipients extend European supply qualification, concentrating relationships among established suppliers with existing registration portfolios in the Rhine-Ruhr industrial corridor.
Japan
PMDA's Sakigake designation system offers expedited review for innovative nucleic acid therapies with preliminary clinical evidence, attracting sponsors seeking earlier market entry in Asia-Pacific. Tokyo-Osaka biopharmaceutical corridors host specialized toxicology expertise for long-acting gene silencing agents that remains scarce in other regional talent pools.
United Kingdom
MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for nucleic acid therapies with orphan drug status. London-Oxford-Cambridge golden triangle clusters retain functional genomics research intensity for vector-based RNAi despite translational bottlenecks in clinical scalability.
China
NMPA priority review pathways for innovative biologics are shortening approval timelines for liver-targeted siRNA constructs with validated manufacturing packages. Yangtze River Delta biotech corridors are scaling phosphoramidite monomer and specialized lipid production to reduce import dependency for domestic RNAi pipelines.
RNAI Technology Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated biopharmaceuticals capturing therapeutic revenue pools while reagent suppliers anchor research-tool ecosystems. The vendor base concentrates around three strategic archetypes: liver-targeted siRNA franchise holders, extrahepatic delivery specialists, and supply-chain-anchored reagent scale providers. Dominant competitive moves include integrated development and manufacturing organization contract consolidation and GalNAc-conjugate chemistry platform licensing.
Among franchise-validated developers, Alnylam Pharmaceuticals and Arrowhead Pharmaceuticals exemplify divergent delivery specialization archetypes, with the former representing hepatocyte-targeted commercial validation and the latter occupying extrahepatic extension positions. Thermo Fisher Scientific anchors reagent and instrumentation scale, securing supply chain relationships with Massachusetts and California-based biotechs running multiple clinical-stage programs.
| Leading Market Players |
|---|
| Alnylam Pharmaceuticals |
| Thermo Fisher Scientific |
| Merck KGaA |
| Arrowhead Pharmaceuticals |
| Silence Therapeutics |
| Revvity |
| GenScript |
| Promega Corporation |
| OriGene Technologies |
| Others |
Value Chain & Pricing Dynamics
Integrated biopharmaceutical sponsors running multiple clinical-stage programs command substantial pricing leverage through consolidated procurement contracts that bundle oligonucleotide synthesis, lipid formulation, and fill-finish under single-provider agreements. This buyer concentration anchors premium positioning for GalNAc-conjugate chemistry platforms while squeezing margins for fragmented contract manufacturing organizations competing on spot-market terms.
Pricing Analysis
Distributor and contract manufacturing margins stratify across three tiers: premium GalNAc-conjugate platforms with validated CMC packages, standard phosphoramidite-based oligonucleotides, and economy-grade research-use reagents. Price differentiation rests on regulatory certification tier and manufacturing scale, with FDA-validated commercial batches commanding substantial premiums over GMP-compliant clinical materials. Cost compression in standard-tier synthesis is intensifying because phosphoramidite monomer and specialized lipid prices fluctuate with semiconductor-grade solvent availability. Academic research institutes exhibit highest price sensitivity, while late-stage biopharmaceutical sponsors prioritize supply security over unit cost.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive lipid nanoparticles remain underdeveloped, creating write-off risks for cold-chain excursions during last-mile delivery. Manufacturing gravity centers on the United States, Germany, and China, with Massachusetts and California clusters anchoring commercial-scale oligonucleotide synthesis and Yangtze River Delta corridors scaling phosphoramidite monomer production. The supply chain rests on ionizable cationic lipids, phosphoramidite monomers, and specialized containment infrastructure. Single-source vulnerability for novel lipid excipients concentrates risk among established suppliers with existing REACH registration portfolios. Distribution runs through integrated development and manufacturing organization contracts rather than fragmented CMO sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH chemical registration timelines in Europe extend supply qualification windows by 12-18 months relative to FDA accelerated pathways in the United States, rewarding sponsors who front-load manufacturing scale-up in North American jurisdictions.
For Market Incumbents: Hedge against substitution threats from antisense oligonucleotides and CRISPR-based gene editing platforms by deepening captive supply of specialized lipid excipients and securing parallel EMA-FDA briefing strategies. Prioritize backward integration into phosphoramidite monomer production to buffer input cost volatility. Lock in long-term offtake agreements with Massachusetts and California-based biotechs before Phase II data readouts compress competitive timelines. For New Entrants and Emerging Players: The mid-tier pricing gap between validated GalNAc-conjugate platforms and research-grade reagents offers entry latitude for synthetic polymer-based delivery systems with reduced cold-chain dependencies. Target CNS applications for glioblastoma and neurodegenerative targets where blood-brain barrier penetration technologies remain commercially undeveloped. Pursue PMDA Sakigake designation in Japan as a differentiated regulatory pathway with expedited review timelines. For Investors and Strategic Acquirers: Large-cap biopharmaceuticals with metabolic and cardiovascular portfolios are the most active acquirers in this space, seeking delivery platform diversification beyond liver-targeted franchises. Long-term viability centers on tissue-specific engineering capabilities rather than target biology expertise. Monitor EMA PRIME eligibility decisions and FDA accelerated approval grants for nucleic acid therapies as inflection indicators for platform validation and competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| GalNAc-Conjugate Platform Licensing | Accelerates hepatocyte-targeted therapeutic development through validated asialoglycoprotein receptor binding chemistry. |
| Integrated Development and Manufacturing Organization Consolidation | Reduces technology transfer risk by unifying oligonucleotide synthesis, lipid formulation, and fill-finish under single-provider contracts. |
| Extrahepatic Delivery Technology Investment | Extends addressable disease categories beyond liver-localized targets through siRNA-antibody conjugates and targeted peptide systems. |
| REACH Registration Portfolio Expansion | Secures European supply relationships by preempting 12-18 month qualification delays for novel lipid excipients. |
| Toxicology Expertise Capacity Building | Addresses scarcity of qualified preclinical safety assessors for long-acting gene silencing agents in oncology and cardiometabolic indications. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and contract manufacturing procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and SEC 10-K disclosures. Bottom-up patient-flow modeling and top-down market sizing triangulated volume and value estimates across therapeutic modalities.
Segment-weighting approaches distributed revenue projections across product type, delivery method, end user, and application dimensions, with regional regulatory clusters and manufacturing geography treated as cross-cutting analytical layers. CAGRs were derived from fitted growth curves anchored to historical approval timelines and pipeline-stage transitions. Forecast inputs incorporated lipid nanoparticle manufacturing capacity expansion, phosphoramidite monomer supply elasticity, and EMA-FDA regulatory pathway convergence patterns.
Caveats apply where REACH registration delays, phosphoramidite monomer price volatility, or toxicology expertise scarcity could materially shift the outlook for European supply qualification and preclinical safety assessment capacity. Practitioners should monitor FDA accelerated approval grant rates, EMA PRIME designation decisions, and PMDA Sakigake designations for early signals of competitive timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Oncolytic Virus Cancer Therapy Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Asia-Pacific Gene Therapy Market
Cell & Gene Therapy
Cancer Therapeutics Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Global Dendritic Cell Cancer Vaccines Market
Cell & Gene Therapy
Europe Stem Cell Therapy Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Global Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
Stem Cell Therapy Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
Hemophilia Therapeutics Market