
 Gluten-Free Pasta Market | 2026-2036
Gluten-Free Pasta Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten-Free Pasta Market Analysis
Premium certified-organic ingredient tiers is redrawing competitive boundaries in gluten-free pasta. Barilla G. e R. F.lli S.p.A. leverages its Italian milling heritage to sustain quality consistency across rice and legume flour lines. Jovial Foods Inc. anchors its position through specialized einkorn and brown rice sourcing from dedicated farms. Dr. Schär AG differentiates via deep European pharmacy and retail channel control.
Gluten-free pasta denotes dried or fresh noodle products formulated without wheat, barley, or rye proteins, typically employing rice flour, corn flour, quinoa flour, or legume flour as structural bases, with hydration levels and extrusion temperatures calibrated to mimic al dente texture in finished dishes. Its primary commercial purpose centers on delivering safe, sensorially acceptable carbohydrate staples to celiac patients, gluten-intolerant consumers, and health-aware households avoiding wheat. Penne and fusilli shapes command structural advantages in food service applications where sauce retention determines repeat procurement. Legume flour formulations capture the fastest-growing ingredient slot as protein content and lower glycemic indices attract health-conscious diners. Rice flour maintains volume leadership through cost efficiency and neutral flavor profiles suited to mass retail consumers.
FDA gluten-free labeling rules in the United States mandate sub-20 ppm gluten thresholds, while EFSA enforces comparable standards across EU member states and Health Canada administers parallel purity requirements. These frameworks elevate compliance costs for new entrants but simultaneously validate premium pricing for certified manufacturers. Stakeholders must monitor evolving allergen detection methodologies and emerging national fortification mandates that could reshape formulation requirements.
Market Dynamics
Legume flour extrusion technology is compressing cost premiums against rice-based alternatives while EFSA purity mandates force reformulation investments across European manufacturing footprints.
Growth Catalysts
- EFSA Gluten Threshold Enforcement:Sub-20 ppm labeling standards validate premium positioning for certified producers and accelerate pharmacy channel penetration across Italy, Germany, and Spain.
- Pharmacy Distribution Expansion:Celiac diagnosis protocols in France and Italy route patients through pharmacy networks where gluten-free pasta commands higher margins and repeat purchase loyalty.
- Legume Flour Protein Positioning:Chickpea and lentil formulations attract health-conscious households seeking low-glycemic meal solutions beyond strict medical necessity.
Market Restraints
- Quinoa Supply Concentration:Bolivian and Peruvian harvest volatility exposes premium positioning brands to input cost spikes and sourcing disruption.
- Extrusion Equipment Capex:Dedicated gluten-free production lines require stainless steel infrastructure that small Italian millers cannot amortize against limited batch volumes.
- Wheat Flour Price Arbitrage:Conventional pasta maintains a 40-60% cost advantage at retail, compressing mass-market penetration for economy-tier gluten-free alternatives.
Strategic Opportunities
- US Foodservice White Space:Italian-themed restaurant chains in California and New York lack consistent gluten-free pasta supply for celiac-safe menu expansion.
- E-Commerce Subscription Models:Direct-to-consumer platforms bypass supermarket slotting fees and capture recurring revenue from diagnosed celiac households.
- EU Organic Certification Convergence:Dual gluten-free and organic labeling commands shelf price premiums in German and Austrian retail channels.
Industry Challenges
- Cross-Contamination Protocol Talent:Certified production facilities require specialized sanitation staff that Italian milling regions struggle to recruit and retain.
- Multi-Certification Timeline Compression:Simultaneous pursuit of gluten-free, organic, and non-GMO approvals extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten-Free Pasta Market |
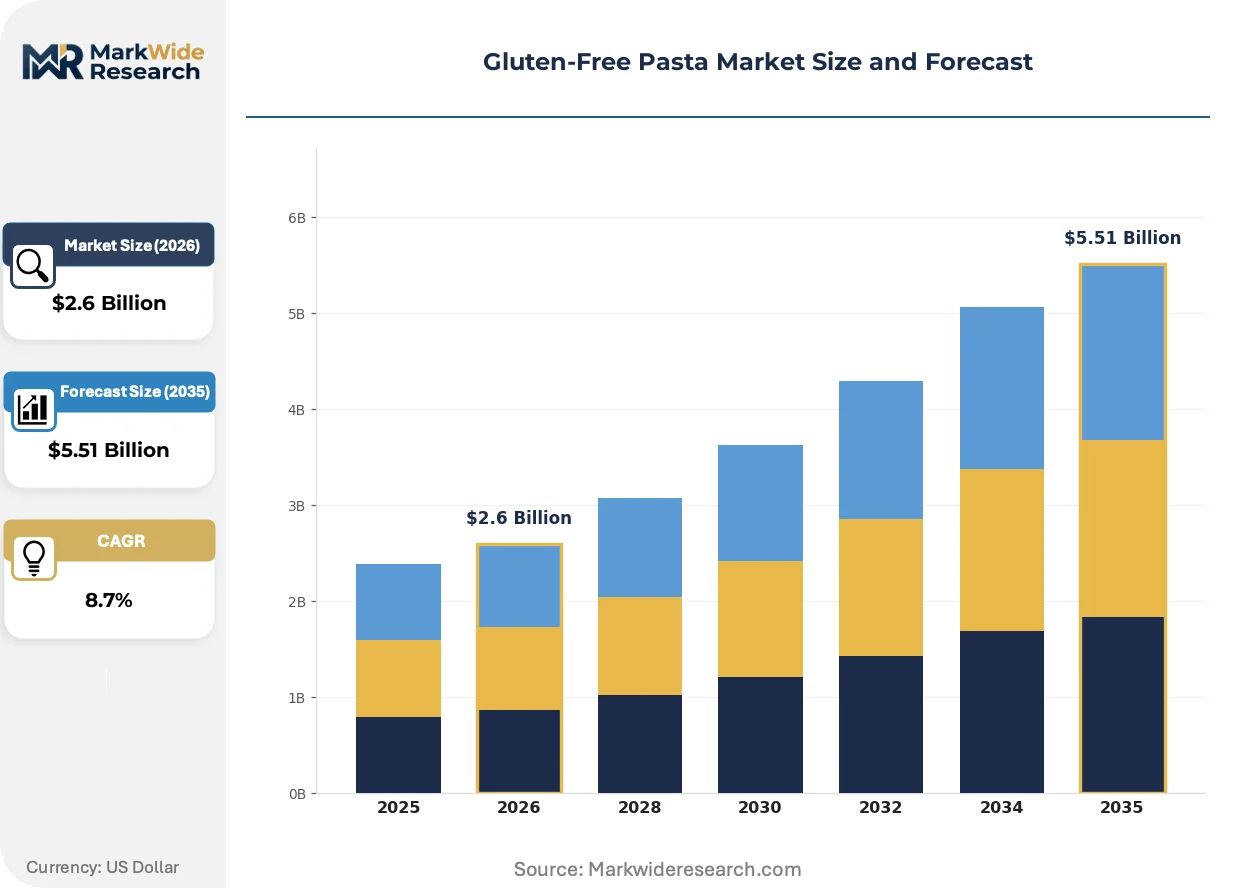
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $5.51 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spaghetti, Fusilli, Penne, Lasagna Ingredient Type: Rice Flour, Corn Flour, Quinoa Flour, Legume Flour End User: Retail Consumers, Food Service, Health-conscious Diners, Celiacs Packaging Type: Bags, Boxes, Tubs, Bulk |
| Companies Covered | Barilla G. e R. F.lli S.p.A., Jovial Foods Inc., The Kraft Heinz Company, Banza LLC, Doves Farm Foods Ltd, Dr. Schär AG, Ebro Foods S.A., Quinoa Corporation, LE VENEZIANE SRL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten-Free Pasta Market Emerging Trajectories
High-pressure extrusion and novel binding systems are redefining texture benchmarks while regulatory harmonization pressures force consolidation of quality assurance protocols.
Extrusion die technology is decomposing the structural gap between gluten-free and wheat pasta. Italian equipment manufacturers now supply modified screw configurations that align starch gelatinization with protein network simulation. Foodservice distributors in Milan and Rome are specifying these systems for contract supply agreements, compressing the sensory differentiation that previously justified wheat pasta premiums.
EFSA's 2023 updated guidance on gluten-free threshold testing methods is tightening laboratory verification requirements. Manufacturers must now employ ELISA and mass spectrometry dual confirmation for batch release. Small-scale producers in Southern Italy face disproportionate compliance burdens, accelerating partnerships with third-party testing laboratories in Bologna and Padua.
Retail buyers are consolidating supplier relationships around vertically integrated millers who control flour sourcing through dedicated gluten-free grain handling. Italian supermarket chains now require single-source traceability documentation from field to package. This concentration pattern favors established rice and legume processors in the Po Valley who invested in segregated supply infrastructure before certification mandates tightened.
Gluten-Free Pasta Market Segmentation
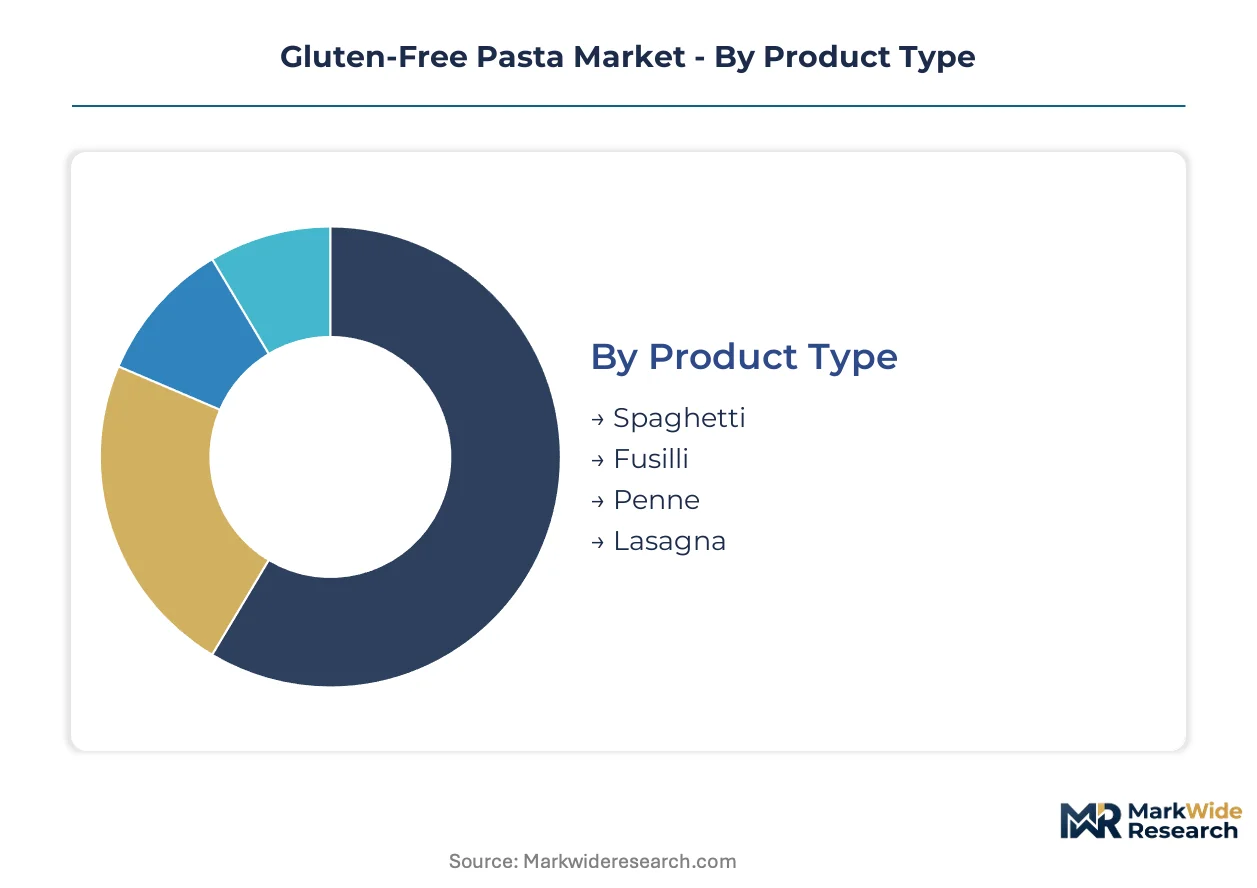
Gluten-free pasta segmentation reflects divergent regulatory thresholds across distribution channels. Ingredient composition and shape geometry determine compliance costs and end-use viability for celiac-safe positioning.
Product Type:
EFSA labeling mandates and FDA thresholds apply uniformly across shapes, yet extrusion complexity varies with surface-area-to-volume ratios.
- Penne:Tubular geometry with angled ends maximizes sauce retention in food service applications. Italian restaurant chains in Milan and Rome specify penne for celiac-safe menu lines where repeat procurement depends on consistent cooking performance.
- Fusilli:Helical ridges trap particulate sauces through mechanical interlocking rather than absorption. Health-conscious diners in German retail channels favor fusilli for vegetable-forward preparations where texture visibility matters.
- Spaghetti:Long cylindrical strands demand precise starch gelatinization to prevent clumping during service.
- Lasagna:Broad flat sheets require structural integrity through multiple bake cycles without disintegration.
Established volume favors Penne; emerging adoption favors Fusilli.
Ingredient Type:
Cost tiers separate commodity inputs from protein-fortified premium positioning.
- Legume Flour:Chickpea and lentil bases deliver elevated protein content and lower glycemic indices through complex carbohydrate structures. Health-conscious diners seeking meal solutions beyond strict medical necessity drive pharmacy channel expansion in France and Italy.
- Rice Flour:Neutral flavor profiles and cost efficiency sustain mass retail dominance. Supermarket buyers in the Po Valley consolidate procurement around rice-based lines for economy-tier positioning.
- Corn Flour:Yellow and white varietals offer visual differentiation for private-label programs.
- Quinoa Flour:Andean sourcing exposes brands to Bolivian harvest volatility and input cost spikes.
Volume concentration remains with Rice Flour; steepest expansion trajectory belongs to Legume Flour.
End User:
Channel-specific purity protocols create margin stratification across customer types.
- Retail Consumers:Supermarket and e-commerce purchases concentrate among diagnosed celiac households seeking certified-safe pantry staples. Italian retail chains require single-source traceability documentation that favors vertically integrated suppliers.
- Celiacs:Medically diagnosed patients route through pharmacy networks in Italy and France where gluten-free pasta commands higher margins and subscription loyalty. EFSA sub-20 ppm thresholds validate premium pricing for this segment.
- Food Service:Italian-themed restaurants in California and New York lack consistent supply for celiac-safe menu expansion.
- Health-conscious Diners:Wellness-motivated buyers without medical necessity seek legume-based protein positioning.
Pharmacy penetration favors Celiacs; direct-to-consumer scaling favors Retail Consumers.
Packaging Type:
Format selection tracks channel economics and contamination risk management.
- Bags:Flexible film structures minimize unit costs for high-velocity supermarket SKUs.
- Boxes:Rigid cartons protect shape integrity through distribution and communicate certification marks prominently on shelf.
- Tubs:Reclosable rigid containers suit fresh pasta formats requiring refrigeration.
- Bulk:Food service operators in Rome and Milan specify bulk formats for back-of-house portion control.
Retail shelf presence favors Boxes; food service efficiency favors Bulk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian milling clusters dominate gluten-free pasta manufacturing through vertically integrated rice and legume processing infrastructure. EFSA purity mandates have concentrated certified production in the Po Valley corridor where segregated grain handling systems already exist.
Italy
Pharmacy channel expansion and celiac diagnosis protocols drive certified product demand through Lombardy and Emilia-Romagna retail networks. EFSA sub-20 ppm labeling standards validate premium positioning for domestic producers. The Po Valley milling belt around Parma and Bologna concentrates gluten-free extrusion capacity with dedicated production lines.
Germany
Dual gluten-free and organic certification commands shelf price premiums across Bavarian and North Rhine-Westphalian supermarket chains. EFSA threshold enforcement aligns with national Lebensmittel- und Futtermittelgesetzbuch purity requirements. Berlin-Brandenburg distribution hubs consolidate procurement for pharmacy network supply into northern European markets.
United States
FDA sub-20 ppm labeling rules sustain certified manufacturer premiums while California and New York restaurant chains seek consistent food service supply. Health Canada administers parallel purity requirements affecting cross-border trade flows. Italian-themed restaurant clusters in Los Angeles and Manhattan represent underpenetrated food service demand.
France
Celiac diagnosis protocols route patients through pharmacy networks where gluten-free pasta commands repeat purchase loyalty in Île-de-France and Auvergne-Rhône-Alpes. ANSM oversight of food allergen labeling converges with EFSA guidelines. Lyon distribution centers channel certified products into southeastern European export corridors.
Spain
Supermarket consolidation around vertically integrated suppliers intensifies in Catalonia and Madrid retail markets. EFSA testing method updates force laboratory verification investments from Barcelona-based processors. Valencia port infrastructure supports Andean quinoa flour import for premium legume-blend formulations.
Gluten-Free Pasta Market Vendor Landscape
Concentration sits with heritage Italian millers and specialized health-food specialists who control pharmacy channel access. The vendor base separates into three functional tiers: multinational FMCG conglomerates with gluten-free portfolio extensions, dedicated gluten-free specialists with certification depth, and regional Italian millers with segregated production infrastructure. Competitive moves center on backward integration into dedicated grain sourcing and pharmacy distribution partnership exclusivity.
Among Italian heritage millers, Barilla G. e R. Flli S.p.A. and LE VENEZIANE SRL exemplify vertically integrated production archetypes with Po Valley milling infrastructure. Dr. Schär AG occupies a position within the European pharmacy channel specialist tier. Jovial Foods Inc. represents the North American health-food specialist archetype with dedicated farm sourcing relationships.
| Leading Market Players |
|---|
| Barilla G. e R. F.lli S.p.A. |
| Jovial Foods Inc. |
| The Kraft Heinz Company |
| Banza LLC |
| Doves Farm Foods Ltd |
| Dr. Schär AG |
| Ebro Foods S.A. |
| Quinoa Corporation |
| LE VENEZIANE SRL |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for Andean quinoa flour concentrate margin exposure among premium-positioned brands, binding pricing power to harvest volatility while compressing working capital efficiency across Italian milling networks. EFSA sub-20 ppm certification costs feed directly into shelf price premiums, creating structural separation between certified pharmacy-channel products and mass retail economy tiers.
Pricing Analysis
EFSA gluten threshold enforcement dictates the pricing tier structure across European gluten-free pasta, separating pharmacy-certified premiums from supermarket economy lines. Three-tier pricing structure across premium legume-based, standard rice-based, and economy corn-based levels reflects certification depth and protein positioning. Cost compression in rice-based tiers is intensifying because Brazilian harvest expansion feeds raw material oversupply. Retail consumers seeking certified-safe pantry staples demonstrate highest price sensitivity, while diagnosed celiac households routing through pharmacy networks accept premium positioning for guaranteed purity.
Supply Chain Analysis
Italy and Bolivia anchor gluten-free pasta supply chains through Po Valley milling infrastructure and Andean quinoa cultivation. Production draws from rice flour sourced via Lombardy processors, chickpea flour from North American pulse growers, and quinoa flour subject to South American harvest variability. Single-source vulnerability in Andean grain supply exposes premium brands to input disruption during drought cycles. Distribution runs through pharmacy networks in Italy and France, supermarket chains in Germany and Spain, and direct-to-consumer platforms capturing subscription revenue from diagnosed households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gluten-free pasta demand tracks cyclical recovery patterns in celiac diagnosis rates, with EFSA regulatory harmonization accelerating pharmacy channel penetration as the core cyclical driver.
For Market Incumbents: Compound certification depth through dual organic-gluten-free labeling investments that German and Austrian retail buyers reward with shelf price premiums. Defend against legume flour extrusion technology cost compression by locking multi-year supply agreements with Po Valley rice processors. Prioritize pharmacy distribution exclusivity in Lombardy and Emilia-Romagna where diagnosis protocols concentrate repeat purchase loyalty. For New Entrants and Emerging Players: Anchor in US foodservice white space where Italian-themed restaurant chains in California and New York lack consistent celiac-safe supply. Target e-commerce subscription models bypassing supermarket slotting fees to capture recurring revenue from diagnosed households. Deploy direct-to-consumer sampling programs that build trial among health-conscious diners seeking protein-fortified meal solutions. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because EFSA purity mandates and multi-certification timelines create barriers that favor incumbents with established laboratory relationships and segregated production infrastructure. Focus acquisition screening on Italian millers with captive rice and legume flour sourcing through dedicated gluten-free grain handling. Monitor pharmacy channel penetration rates in France and Italy as the signal for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy Distribution Partnership | EFSA-certified producers capture repeat purchase loyalty through Italy's diagnosis-routed pharmacy networks. |
| Legume Flour Extrusion Scale-Up | Chickpea and lentil processing investments compress cost premiums against rice-based alternatives. |
| Dual Certification Investment | Combined gluten-free and organic labeling commands shelf price premiums in German retail channels. |
| E-Commerce Subscription Launch | Direct-to-consumer platforms bypass supermarket slotting fees and capture recurring celiac household revenue. |
| Andean Sourcing Diversification | Quinoa flour supply hedging mitigates Bolivian harvest volatility exposure for premium positioning brands. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EFSA guidance documents, Italian supermarket chain procurement specifications, and pharmacy network distribution data. Primary interviews engaged gluten-free product managers at heritage millers, category buyers at Lombardy and Emilia-Romagna retail chains, regulatory affairs specialists navigating multi-certification timelines, and supply chain directors managing segregated grain handling. Secondary sources included customs records for rice and legume flour trade flows, ANSM allergen labeling filings, and Po Valley processor capacity disclosures. Bottom-up volume modeling triangulated against top-down market sizing across ingredient type and channel segments.
Segmentation dimensions modeled include ingredient composition, product shape geometry, end-user channel, and packaging format across the projection horizon. CAGRs derived from regression analysis of historical pharmacy channel penetration, celiac diagnosis rate trajectories, and legume flour adoption curves. Industry-specific forecast inputs incorporated EFSA testing method update implementation timelines and extrusion technology cost reduction slopes.
Decision-makers should treat outputs as directional under assumptions of sustained EFSA enforcement rigor and stable Andean quinoa harvest conditions; material deviation in regulatory stringency or South American climate patterns would warrant model refresh. Recalibration cycles align with material shifts in certification mandate timing and pharmacy reimbursement policy adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Allergen Free Food Products Market
Food Intolerance Products
South America Gluten Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Food Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Global Lactose Intolerance Treatment Market
Food Intolerance Products
Allergen Free Food Market
Food Intolerance Products
Europe Gluten-Free Oats Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Food Intolerance Products Market
Food Intolerance Products
Fermented Garlic and Onion Digestive Comfort Bases Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market
Food Intolerance Products
United States Gluten Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
Dyspepsia Market
Food Intolerance Products
Food Allergy and Intolerance Products Market