
 Bolivian Rose Salt Market | 2026-2036
Bolivian Rose Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Bolivian Rose Salt Market Analytics
Bolivia's Salar de Uyuni brine expansion is reconfiguring upstream supply availability for premium pink salt exporters. SaltWorks leverages direct sourcing partnerships with Bolivian cooperatives to control trace mineral consistency across its wholesale portfolio. San Francisco Salt Company anchors its brand narrative on Andean provenance and unrefined harvesting methods. Frontier Co-Op competes through fair-trade certification and organic distribution channels in North American natural food retail.
Bolivian rose salt denotes halite crystals harvested from ancient evaporite deposits in Bolivia's central plateau, distinguished by iron oxide and trace mineral inclusions that yield a pale pink coloration and measured sulfur content below 0.05 percent. The salt serves primarily as a finishing mineral for high-heat cooking and table presentation, where its moisture retention and crystalline structure provide tactile differentiation from refined sodium chloride. Coarse salt and block salt command premium positioning in specialty retail, with block salt generating elevated margins through extended-use kitchen applications and serving-plate utility. Fine salt occupies volume leadership in food processor procurement, though flavored salt segments accelerate through fusion cuisine adoption in urban restaurant clusters.
Bolivia's Ministry of Mining and Metallurgy sets extraction quotas and environmental compliance protocols for salar operations, while the Servicio Nacional de Sanidad Agropecuaria e Inocuidad Alimentaria monitors heavy-metal thresholds in exported food-grade salt. REACH compliance in European import jurisdictions and FDA recognition of GRAS status in the United States shape cross-border market access and label claim permissibility. Stakeholders must track pending revisions to Bolivia's lithium-bromine-salt co-extraction licensing, as overlapping brine rights could constrain rose salt yield from shared salar resources.
Market Dynamics
Bolivia's lithium-bromine-salt co-extraction licensing revisions are tightening brine access rights across shared salar resources, compressing available yield for artisanal rose salt harvesters while industrial operators secure priority allocations.
Growth Catalysts
- REACH compliance:European importers recognize Bolivian rose salt's GRAS-adjacent mineral profile, accelerating customs clearance for food-grade crystalline exports into EEA markets.
- Fusion cuisine adoption:Urban restaurant clusters in metropolitan culinary markets drive flavored salt segment velocity through high-heat finishing applications.
- Andean provenance marketing:Unrefined harvesting narratives differentiate coarse and block salt positioning in specialty retail channels.
Market Restraints
- Brine rights overlap:Pending revisions to Bolivia's lithium-bromine-salt co-extraction licensing constrain rose salt yield from shared Salar de Uyuni and Coipasa resources.
- Heavy-metal thresholds:Servicio Nacional de Sanidad Agropecuaria e Inocuidad Alimentaria monitoring protocols create batch-testing delays for export certification.
- Moisture-retention substitutes:Himalayan pink salt and Peruvian Maras salt compete on trace mineral coloration and crystalline structure in finishing salt applications.
Strategic Opportunities
- Block salt serving-plate utility:Extended-use kitchen applications generate elevated margins through thermal mass cooking and presentation tableware.
- Fair-trade certification:Organic distribution channels in natural food retail reward cooperative sourcing structures with shelf placement premiums.
- Salar de Coipasa expansion:Secondary brine deposits offer upstream supply diversification beyond Uyuni concentration.
Industry Challenges
- Trace mineral consistency:Batch-to-batch iron oxide variation complicates wholesale portfolio standardization for direct sourcing partnerships.
- Extraction quota compliance:Bolivia's Ministry of Mining and Metallurgy environmental protocols require capital investment in salar-edge evaporation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bolivian Rose Salt Market |
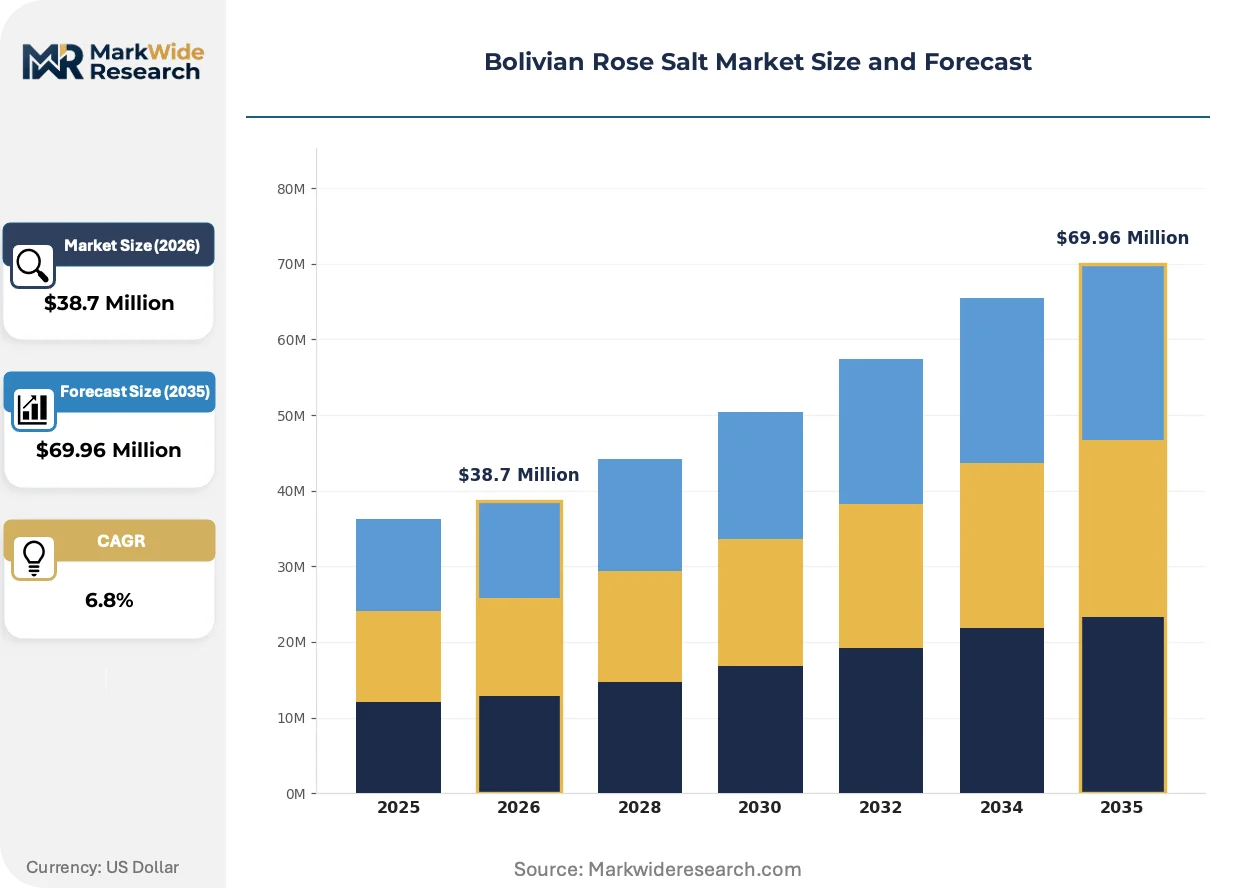
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $69.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coarse Salt, Fine Salt, Flavored Salt, Block Salt Packaging Type: Bags, Jars, Pouches, Bulk Packaging End User: Household, Restaurants, Food Processors, Health Stores Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | SaltWorks, McCormick & Company Inc, K+S AG, Cargill Inc., Morton Salt Inc., Compass Minerals International Inc., San Francisco Salt Company, Frontier Co-Op, Tata Chemicals Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bolivian Rose Salt Market Evolving Landscape
Mechanized brine harvesting and crystallization monitoring are compressing traditional extraction timelines while digital provenance tracking reshapes buyer trust mechanisms across premium salt categories.
Solar-assisted evaporation ponds with automated salinity sensors are collapsing the seasonal production window for artisanal harvesters. Gourmet food processors and specialty retailers adopt these monitored crystallization systems to secure year-round supply consistency. The technology is collapsing price premiums previously attached to limited-harvest vintage batches.
Bolivia's Ministry of Mining and Metallurgy extraction quota protocols are tightening environmental compliance thresholds for salar-edge operations. Industrial salt operators face capital requirements for wastewater containment and evaporation efficiency upgrades. Coarse salt exporters bear the highest compliance burden as block salt margins absorb infrastructure amortization.
Chef-driven direct sourcing is displacing traditional distributor intermediaries in metropolitan culinary markets. High-end restaurants in North American and European urban clusters now contract directly with Bolivian cooperatives for crystalline structure specifications. This channel compression is most visible in San Francisco, New York, and London restaurant procurement patterns.
Bolivian Rose Salt Market Segmentation
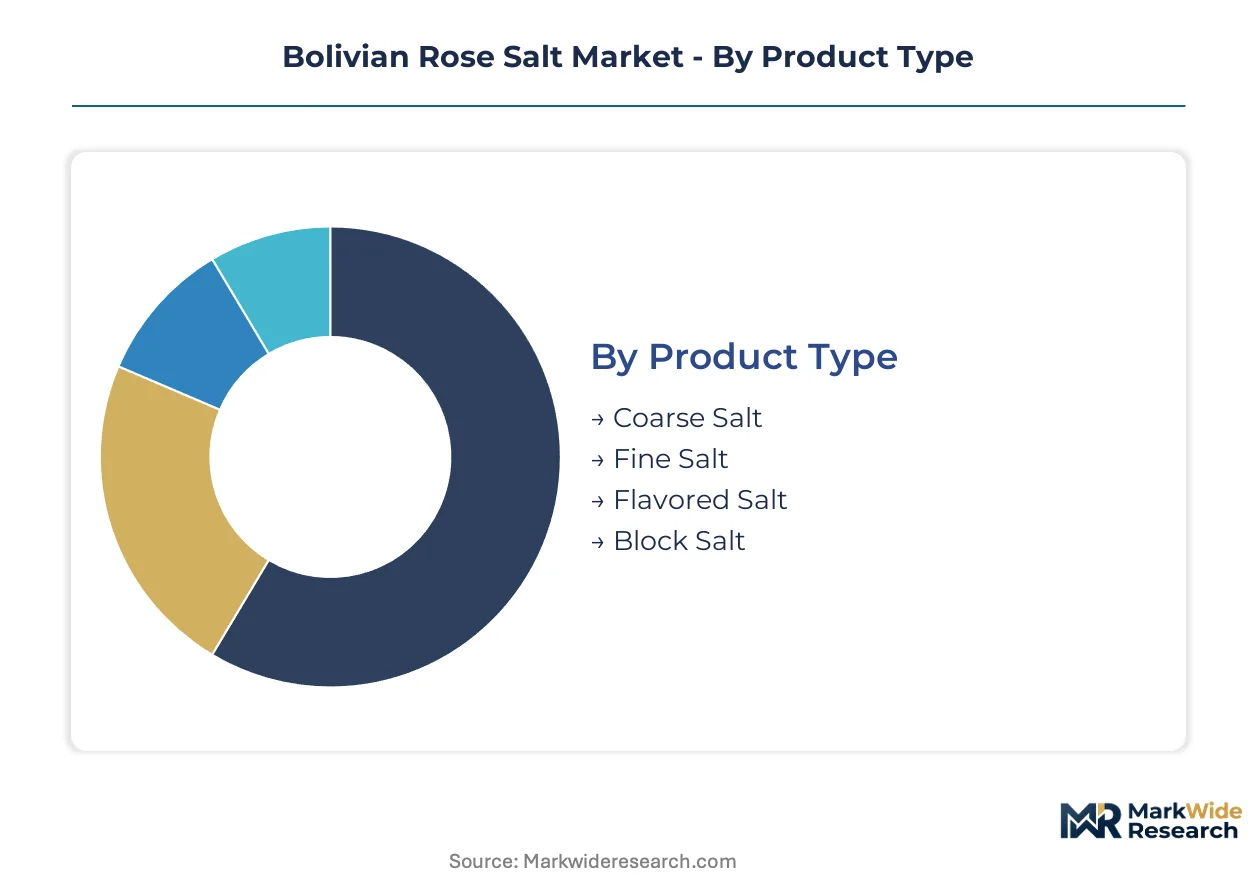
Segmentation in the Bolivian rose salt market reflects divergent crystalline specifications, packaging economics, and procurement channel preferences. Each dimension captures distinct margin structures and regulatory exposure profiles that shape competitive positioning across artisanal and industrial supply tiers.
Product Type:
Mature coarse and fine salt formats dominate current throughput, while block salt and flavored variants represent emerging growth vectors with differentiated margin profiles.
- Coarse Salt:Large halite crystals retain moisture and provide tactile finishing texture for high-heat cooking applications. Gourmet restaurants in metropolitan culinary markets drive procurement, constrained by batch-to-batch iron oxide variation that complicates wholesale standardization.
- Block Salt:Solid mineral slabs function as thermal mass cooking surfaces and presentation tableware, generating elevated margins through extended-use kitchen utility. Artisanal food retail channels in North America and Europe absorb premium positioning for this format.
- Fine Salt:Ground crystalline particles serve volume food processor procurement for ingredient blending and uniform seasoning distribution.
- Flavored Salt:Fusion cuisine adoption in urban restaurant clusters accelerates velocity for infused crystalline variants.
Coarse salt handles the majority of throughput; block salt is expanding most quickly on share.
Packaging Type:
Cost tier stratification separates premium presentation formats from bulk logistics efficiency, with mid-range options capturing specialty retail placement premiums.
- Bulk Packaging:Industrial totes and sacks minimize per-unit logistics cost for food processor procurement at scale. Direct sourcing partnerships with Bolivian cooperatives favor this format for wholesale portfolio consistency.
- Jars:Glass containers with sealed closures preserve moisture retention and support Andean provenance branding on specialty retail shelves. Natural food retail channels reward fair-trade certification with placement premiums for jarred presentation.
- Bags:Flexible film packaging balances unit economics with shelf visibility for mainstream grocery distribution.
- Pouches:Resealable flexible formats target household convenience segments with portion control features.
Bulk packaging commands the highest volume throughput; jars are gaining share fastest among premium-positioned formats.
End User:
Application-driven demand concentration separates artisanal table use from industrial ingredient processing, with intermediary food service capturing margin between procurement tiers.
- Restaurants:Chef-driven direct sourcing from Bolivian cooperatives is displacing traditional distributor intermediaries in San Francisco, New York, and London procurement patterns. High-heat finishing applications specify crystalline structure requirements.
- Food Processors:Ingredient manufacturers procure fine salt for uniform blending into packaged goods, subject to Servicio Nacional de Sanidad Agropecuaria e Inocuidad Alimentaria heavy-metal threshold compliance.
- Household:Consumer pantry replenishment concentrates in supermarket and online retail channels.
- Health Stores:Natural food retail rewards organic distribution channel alignment and unrefined harvesting narrative positioning.
Restaurants absorb the largest revenue concentration; food processors are climbing the fastest on volume share.
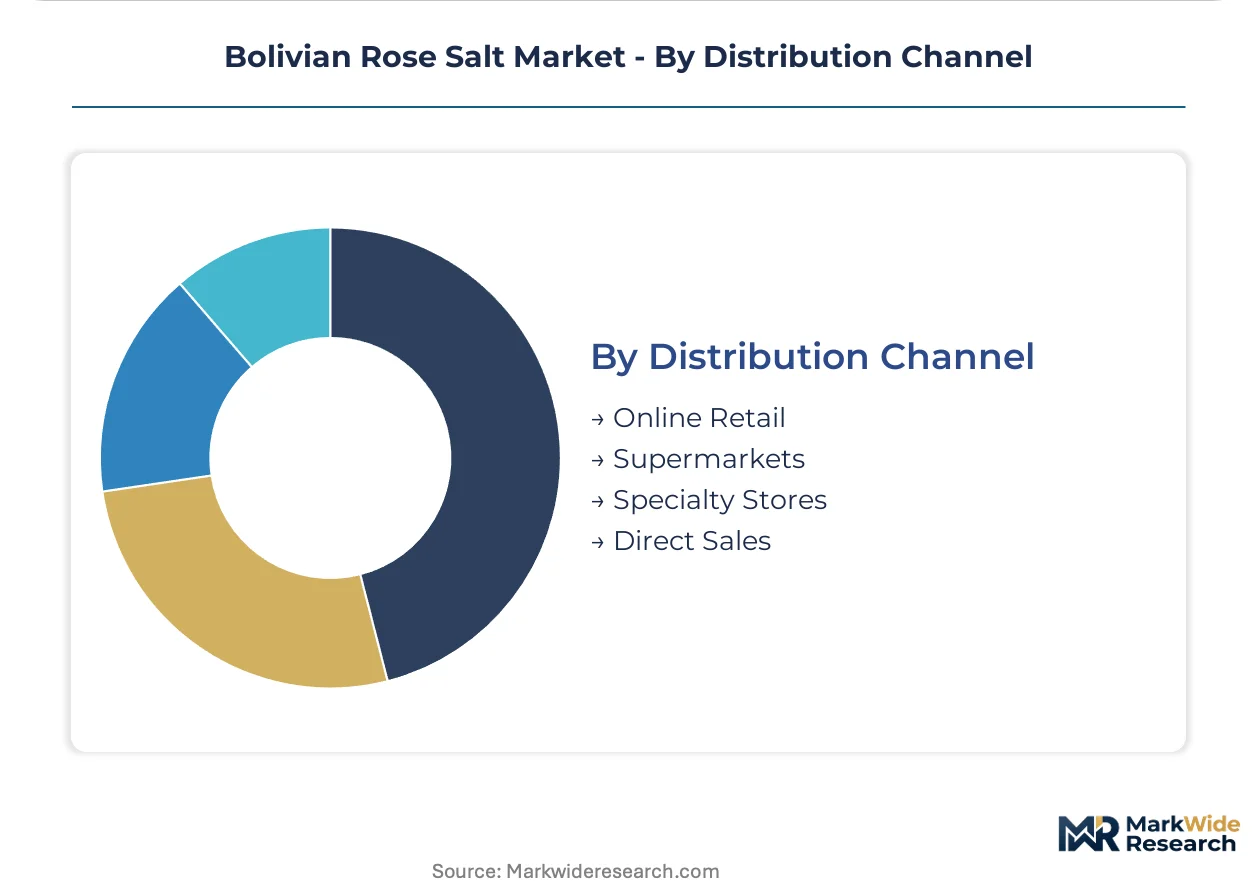
Distribution Channel:
Customer type determines channel preference, with institutional buyers favoring direct relationships while fragmented household demand routes through retail intermediaries.
- Specialty Stores:Curated artisanal food retail in metropolitan culinary markets provides tactile product evaluation and Andean provenance storytelling. Shelf placement premiums reward cooperative sourcing structures.
- Direct Sales:Chef-driven procurement contracts specify trace mineral consistency and crystalline structure, compressing traditional distributor margins. Bolivia's Ministry of Mining and Metallurgy extraction quotas shape available supply for direct allocation.
- Supermarkets:Mass retail channels distribute jarred and bagged formats to household segments.
- Online Retail:E-commerce platforms extend geographic reach for block salt and flavored variants with premium shipping economics.
Specialty stores move the highest value throughput; direct sales are expanding most steeply on margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA recognition of GRAS status anchors United States demand, while REACH compliance shapes European import velocity. Bolivia's national mining code governs extraction quotas that constrain supply availability across all import markets.
United States
Gourmet restaurants in San Francisco, New York, and Los Angeles drive chef-driven direct sourcing contracts for crystalline structure specifications. FDA GRAS status recognition accelerates customs clearance and label claim permissibility for food-grade imports. The San Francisco Bay Area culinary cluster anchors premium block salt procurement through cooperative partnerships with Bolivian harvesters.
Germany
Natural food retail channels in Berlin, Munich, and Hamburg reward fair-trade certification with shelf placement premiums for jarred presentation formats. REACH compliance requirements and ECHA registration protocols govern heavy-metal threshold documentation for imported crystalline salt. The Bavarian organic distribution network concentrates procurement for artisanal food retail segments.
United Kingdom
Fusion cuisine adoption in London restaurant clusters accelerates flavored salt segment velocity through high-heat finishing applications. Food Standards Agency import monitoring aligns with EU-originated safety protocols during the post-Brexit transition period. The London metropolitan culinary market channels direct procurement contracts bypassing traditional distributor intermediaries.
France
Specialty retail placement in Paris and Lyon culinary districts emphasizes Andean provenance branding for coarse and block salt formats. ANSM food contact material regulations and CNIL data governance shape digital provenance tracking requirements for imported goods. The Île-de-France gastronomic cluster absorbs elevated margins for thermal mass cooking applications.
Canada
Health Stores in Toronto, Vancouver, and Montreal concentrate demand for unrefined harvesting narrative positioning in natural food retail. Health Canada and PMRA monitoring protocols govern heavy-metal thresholds in imported food-grade salt. The Ontario-Quebec corridor channels bulk procurement for food processor ingredient blending applications.
Bolivian Rose Salt Market Competitive Landscape
Specialty salt importers and diversified chemical conglomerates split the market between premium artisanal positioning and volume-driven commodity supply. The vendor base concentrates around direct sourcing partnerships with Bolivian cooperatives versus traditional distributor-mediated channels. Three archetypes dominate: provenance-focused specialty brands, fair-trade certified organic distributors, and industrial mineral processors with salt portfolio extensions. Capacity expansion in solar-assisted evaporation infrastructure and strategic partnerships with salar-edge cooperatives represent the dominant competitive moves.
Among North American specialty importers, SaltWorks and San Francisco Salt Company exemplify the provenance-focused archetype through direct cooperative sourcing arrangements. Frontier Co-Op occupies a position within the fair-trade certified tier, leveraging organic distribution channel alignment for shelf placement premiums. McCormick & Company Inc represents diversified food ingredient conglomerates with salt portfolio extensions into premium crystalline categories.
| Leading Market Players |
|---|
| SaltWorks |
| McCormick & Company Inc |
| K+S AG |
| Cargill Inc. |
| Morton Salt Inc. |
| Compass Minerals International Inc. |
| San Francisco Salt Company |
| Frontier Co-Op |
| Tata Chemicals Limited |
| Others |
Value Network & Pricing Analysis
Undercapacity at Salar de Coipasa extraction sites is compressing available yield for artisanal harvesters while concentrating pricing power among cooperatives with Ministry of Mining and Metallurgy quota allocations. This utilization squeeze elevates block salt premiums and forces food processors toward longer-term offtake contracts to secure crystalline consistency.
Pricing Analysis
North American metropolitan culinary markets command 15-25% premiums over European natural food retail channels for equivalent coarse salt grades. Three-tier pricing structure across block, coarse, and fine salt levels separates thermal mass cooking applications from commodity ingredient blending. Cost compression in fine salt is intensifying because mechanized brine harvesting collapses seasonal production premiums. Food processors exhibit highest price sensitivity due to uniform seasoning volume requirements, while chef-driven direct sourcing shows lowest sensitivity for crystalline structure specifications.
Supply Chain Analysis
Bolivia's lithium-bromine-salt co-extraction licensing revisions function as de facto export controls limiting brine access rights for rose salt harvesters. Supply concentrates in Bolivia's central plateau with secondary sourcing from Peruvian Maras salt deposits as contingency. Solar-assisted evaporation infrastructure and automated salinity sensors anchor capital requirements. Single-source vulnerability stems from overlapping mineral rights at shared salar resources. Distribution runs through specialty stores and direct sales channels for premium tiers, with bulk logistics serving food processor procurement at scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
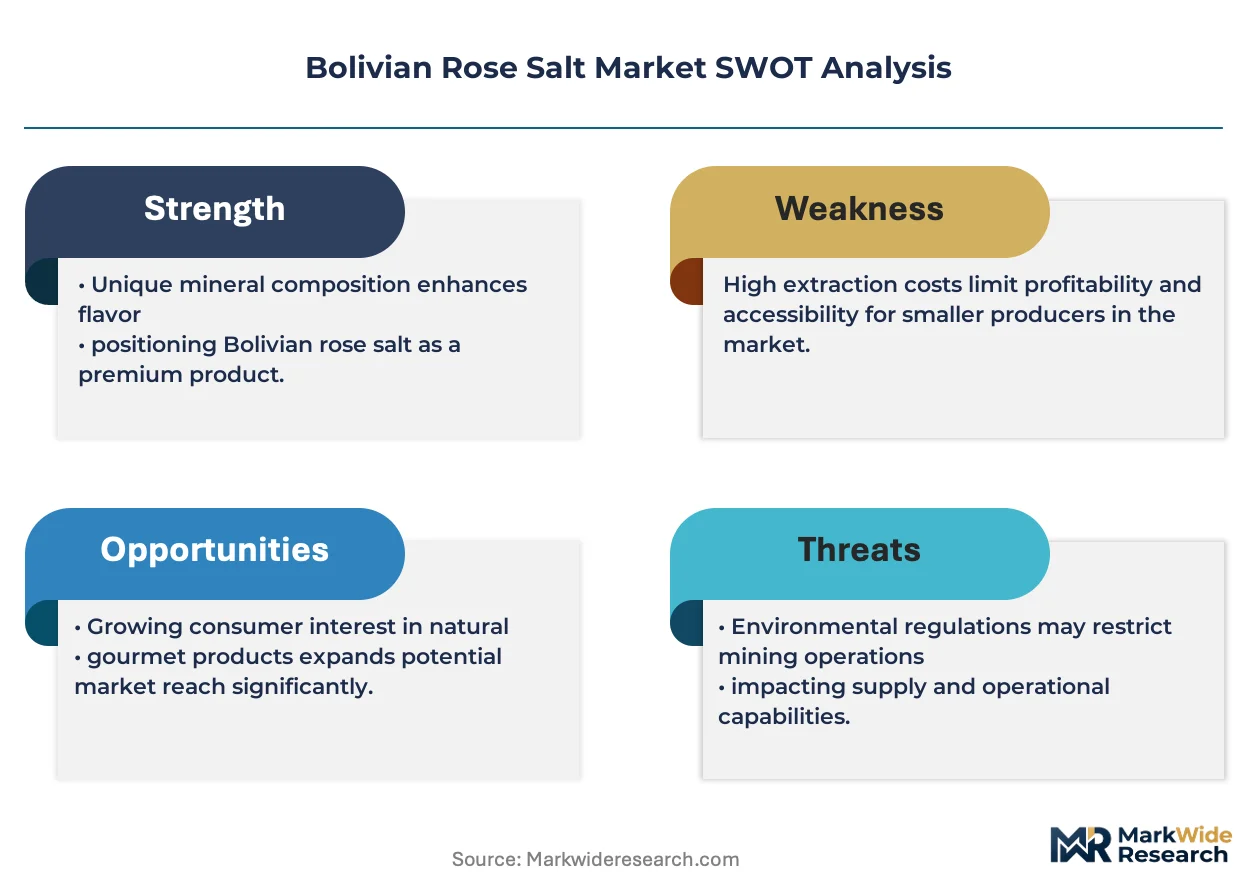
This market requires substitution defense against Himalayan pink salt and Peruvian Maras salt incursions that compete on trace mineral coloration and crystalline finishing applications. Incumbents must differentiate through provenance authentication and supply security.
For Market Incumbents: Build cooperative exclusivity moats through multi-year quota allocation agreements with Salar de Uyuni and Coipasa harvesters. Secure solar-assisted evaporation infrastructure investments to collapse seasonal production windows and defend against mechanized competitors. Counter Peruvian Maras salt substitution threats by emphasizing Andean provenance narratives in San Francisco and London restaurant procurement.
For New Entrants and Emerging Players: Build out Salar de Coipasa secondary deposit access before industrial lithium operators consolidate remaining brine rights. Target health store segments in Toronto and Vancouver where unrefined harvesting narratives command shelf placement premiums with lower competitive density. Penetrate through fair-trade certification alignment with organic distribution channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct sourcing partnerships with metropolitan restaurant clusters that specify multi-year crystalline structure contracts. Five-to-ten year viability hinges on lithium-bromine licensing resolution and environmental compliance threshold stability. Monitor Bolivia's Ministry of Mining and Metallurgy extraction quota revisions as the critical inflection signal for available artisanal yield.
| Strategic Initiative | Industry Significance |
|---|---|
| Cooperative Quota Lock-Up | Long-term brine rights agreements with Salar de Uyuni harvesters secure upstream supply consistency against lithium operator encroachment. |
| Solar Evaporation Infrastructure | Automated salinity sensors collapse seasonal production windows and enable year-round crystalline standardization for wholesale portfolios. |
| Direct Sourcing Partnerships | Chef-driven contracts in San Francisco and London bypass distributor intermediaries and capture margin compression benefits. |
| Fair-Trade Certification Investment | Organic distribution channel alignment with Berlin and Munich natural food retailers commands shelf placement premiums. |
| Block Salt Thermal Mass Applications | Extended-use kitchen utility and serving-plate functionality generate elevated margins through differentiated presentation tableware. |
Research Methodology
A spread of perspectives from cooperative harvester representatives, specialty salt importers, gourmet restaurant procurement directors, natural food retail category managers, and Ministry of Mining and Metallurgy officials converged on the working assumptions. Primary field engagement combined with secondary validation from Bolivia customs export records, Servicio Nacional de Sanidad Agropecuaria e Inocuidad Alimentaria certification databases, FDA GRAS recognition filings, and REACH compliance documentation. Bottom-up crystalline salt volume estimates triangulated against top-down gourmet food retail market assessments.
Demand-supply balance modeling across product type, packaging format, end user, and distribution channel dimensions shaped analytical framework construction. Segmentation captured coarse, block, fine, and flavored salt variants alongside bulk, jar, bag, and pouch presentations. CAGRs derived from compound annual trajectory analysis of chef-driven procurement velocity and food processor ingredient blending requirements. Forecast inputs incorporated lithium-bromine licensing revision timelines and solar evaporation technology adoption curves.
Sensitivities concentrate around pending extraction quota revisions, heavy-metal threshold enforcement variability, and substitute salt incursion rates. Forecasts reflect documented assumptions on brine rights allocation priorities and metropolitan culinary market expansion trajectories. Material shifts in Bolivia's lithium-bromine-salt co-extraction licensing framework would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Dried Herbs Market
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
Organic Saffron Market
Spices and Seasonings
Cardamom Market
Spices and Seasonings
Seasonings Market
Spices and Seasonings
Jalapeno Salt Market
Spices and Seasonings
Middle East and Africa Food Micronized Salt Market
Spices and Seasonings
Boutique Salt Market
Spices and Seasonings
Spices and Seasonings Market
Spices and Seasonings
Pink Himalayan Salt Market
Spices and Seasonings
Incense Sticks (Agarbatti) Market
Spices and Seasonings
Garlic Salt Market
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
Asafoetida Market
Spices and Seasonings
Carthamus Yellow Market
Spices and Seasonings
Malaysia Spices and Seasonings Market