
 Europe Gluten Free Foods and Beverages Market | 2026-2036
Europe Gluten Free Foods and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gluten Free Foods and Beverages Market Analysis
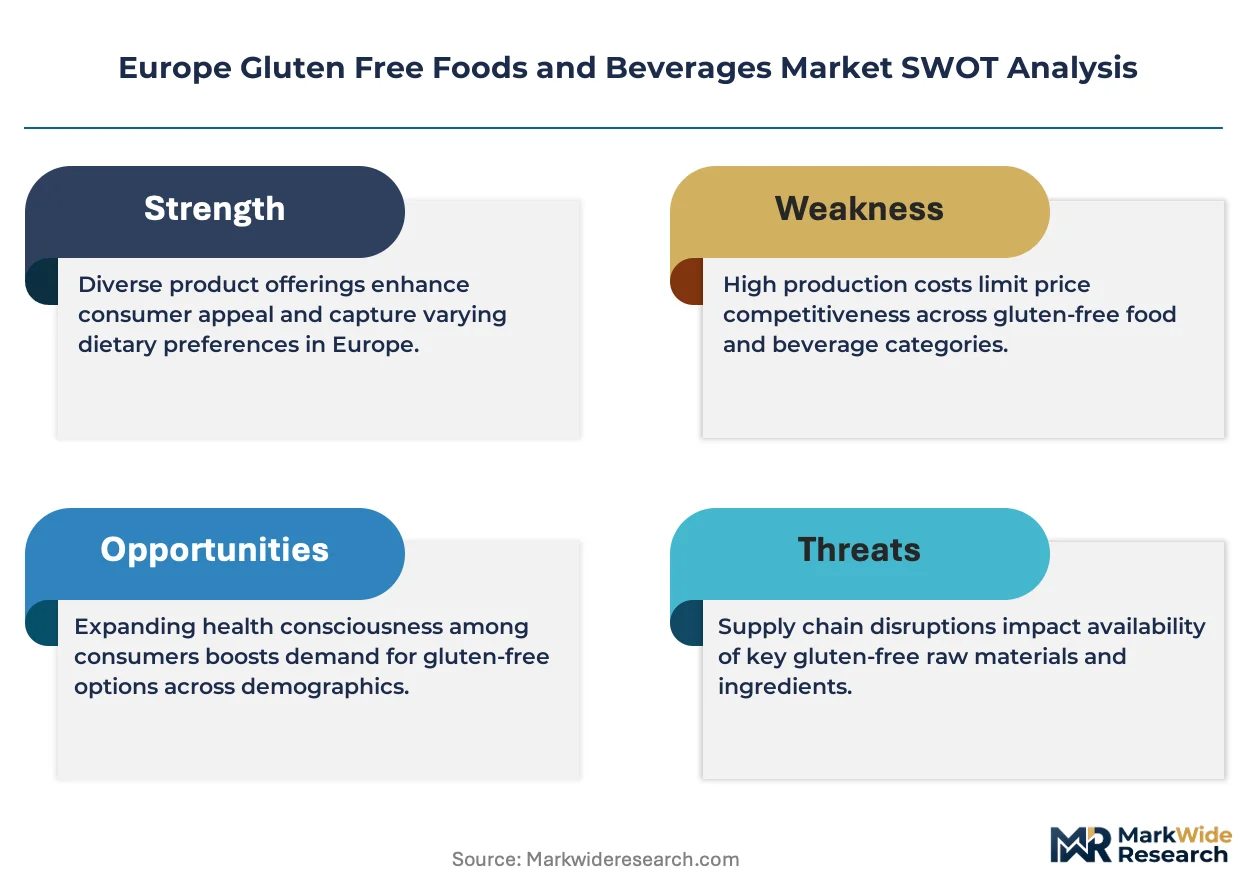
Asset-light contract manufacturing and white-label financing is rewriting competitive entry barriers for new gluten-free brands across Europe. Dr. Schär AG/SPA leverages its integrated Italian-Austrian production network to dominate specialized retail channels. General Mills Inc. competes through scaled bakery operations that sustain consistent supply to major supermarket chains. Danone S.A. positions its beverage portfolio to capture growing dairy-alternative demand within the gluten-free category.
Europe gluten free foods and beverages comprise products formulated without wheat, barley, rye, or their crossbred variants, typically substituting rice flour, tapioca starch, or pulse-derived proteins to achieve comparable texture and shelf stability. These formulations serve clinical dietary management for celiac disease patients alongside lifestyle consumers seeking perceived digestive wellness. Breads and snacks anchor current revenue pools due to daily consumption frequency and established manufacturing expertise, while beverages represent the fastest-growing product type as functional hydration concepts gain traction. Distribution through supermarkets controls the majority of volume flows, though online retail is capturing disproportionate growth among subscription-based repeat purchasers seeking niche ingredient variants.
EFSA allergen thresholds and EU Regulation 1169/2011 on food information to consumers mandate strict gluten content labeling below 20 mg/kg for "gluten-free" claims, shaping both formulation investment and packaging compliance costs. The EU Green Deal's Farm to Fork strategy pressures ingredient sourcing transparency, pushing manufacturers toward certified organic and locally traceable supply chains. Stakeholders must monitor evolving national reimbursement policies for celiac prescription foods in France, Italy, and Spain, as these programs directly influence household purchasing power and brand loyalty dynamics.
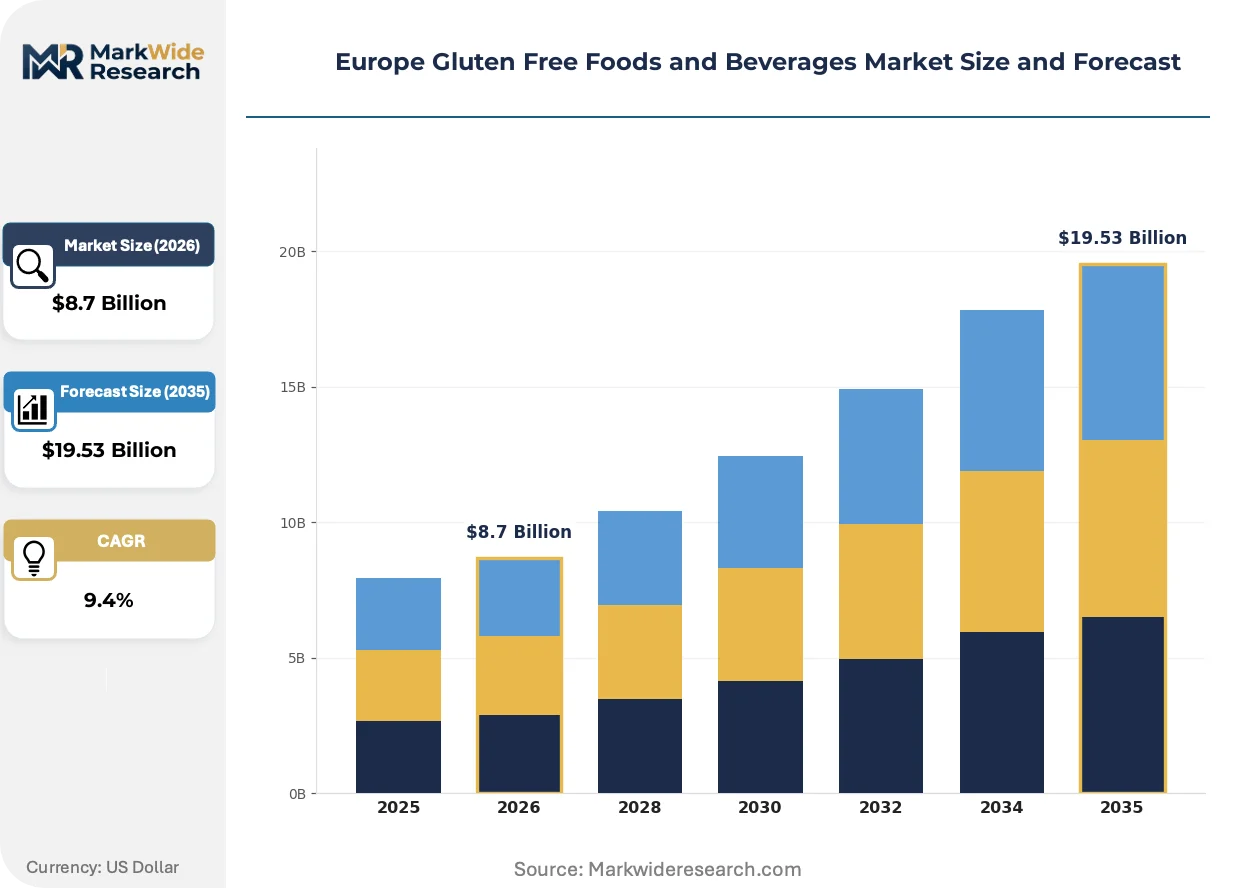
Market Dynamics
EFSA allergen thresholds and EU Regulation 1169/2011 are compressing formulation timelines while forcing manufacturers to rebuild supply chains around certified gluten-free ingredient streams.
Growth Catalysts
- EFSA 20 mg/kg gluten threshold:Strict labeling mandates create compliance-driven product refresh cycles that expand shelf space for verified brands in German and Italian retail.
- Pulse protein extrusion:Advanced texturization of fava bean and lentil isolates is closing the sensory gap with wheat-based equivalents in bakery applications.
- Urban health clusters:Concentrated celiac diagnosis rates in London, Milan, and Berlin generate predictable repeat-purchase cohorts for subscription delivery models.
Market Restraints
- Ingredient cost volatility:Tapioca starch and rice flour prices fluctuate with Thai and Vietnamese harvest cycles, compressing margin stability for mid-tier producers.
- Single-source supply risk:European quinoa protein concentrate relies on Andean import corridors vulnerable to Peruvian export licensing delays.
- Cross-contamination protocols:Dedicated production line requirements under EU gluten-free certification add fixed overhead that blocks small bakery entry.
Strategic Opportunities
- Spanish prescription reimbursement:Pending national celiac food subsidy expansion in Madrid and Barcelona would unlock institutional channel volume.
- Fermented beverage convergence:Kombucha and water kefir positioned as functional gluten-free hydration targets convenience retail in Scandinavian markets.
- Farm to Fork traceability:EU Green Deal procurement incentives reward organic-certified oat supply chains with preferential listing terms.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in hydrocolloid stabilization for gluten-free dough systems commands premium compensation in the Netherlands and Belgium.
- Dual certification timelines:Parallel organic and gluten-free audits stretch product development cycles by eight to fourteen months.
- Legacy equipment retrofitting:Conventional wheat bakery lines require complete sanitation overhaul rather than modular adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gluten Free Foods and Beverages Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Snacks, Pasta, Beverages Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores End User: Individuals, Restaurants, Hotels, Cafes Ingredient Source: Locally Sourced, Imported, Organic, Conventional |
| Companies Covered | Dr. Schär AG/SPA, General Mills Inc., Warburtons Ltd, Genius Foods Ltd, Hain Celestial Group, Conagra Brands Inc., The Kraft Heinz Company, Premier Foods PLC, Danone S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gluten Free Foods and Beverages Market Emerging Trajectories
Digital supply chain verification and precision fermentation are displacing traditional ingredient sourcing models across European gluten-free manufacturing.
Enzymatic gluten degradation technology is virtualizing the traditional separation-based approach to gluten-free production. Danish and Dutch ingredient suppliers deploy endopeptidase treatments that neutralize gluten fragments in situ rather than excluding wheat entirely. This molecular approach is virtualizing the category's reliance on specialty grain silos and dedicated milling infrastructure.
EU Green Deal Farm to Fork traceability mandates are forcing ingredient provenience disclosure down to the cultivar level. Manufacturers must now document oat variety, harvest batch, and transport chain for every production run. German and Austrian organic processors face the steepest compliance curves as their private-label retail contracts specify blockchain-verified origin data.
Subscription-based direct-to-consumer replenishment is capturing urban celiac households seeking ingredient transparency unavailable in mass retail. French and UK platforms now offer personalized flour blends matched to individual tolerance thresholds and recipe preferences. This channel shift concentrates lifetime value in data-rich relationships outside traditional supermarket loyalty programs.
Europe Gluten Free Foods and Beverages Market Segmentation
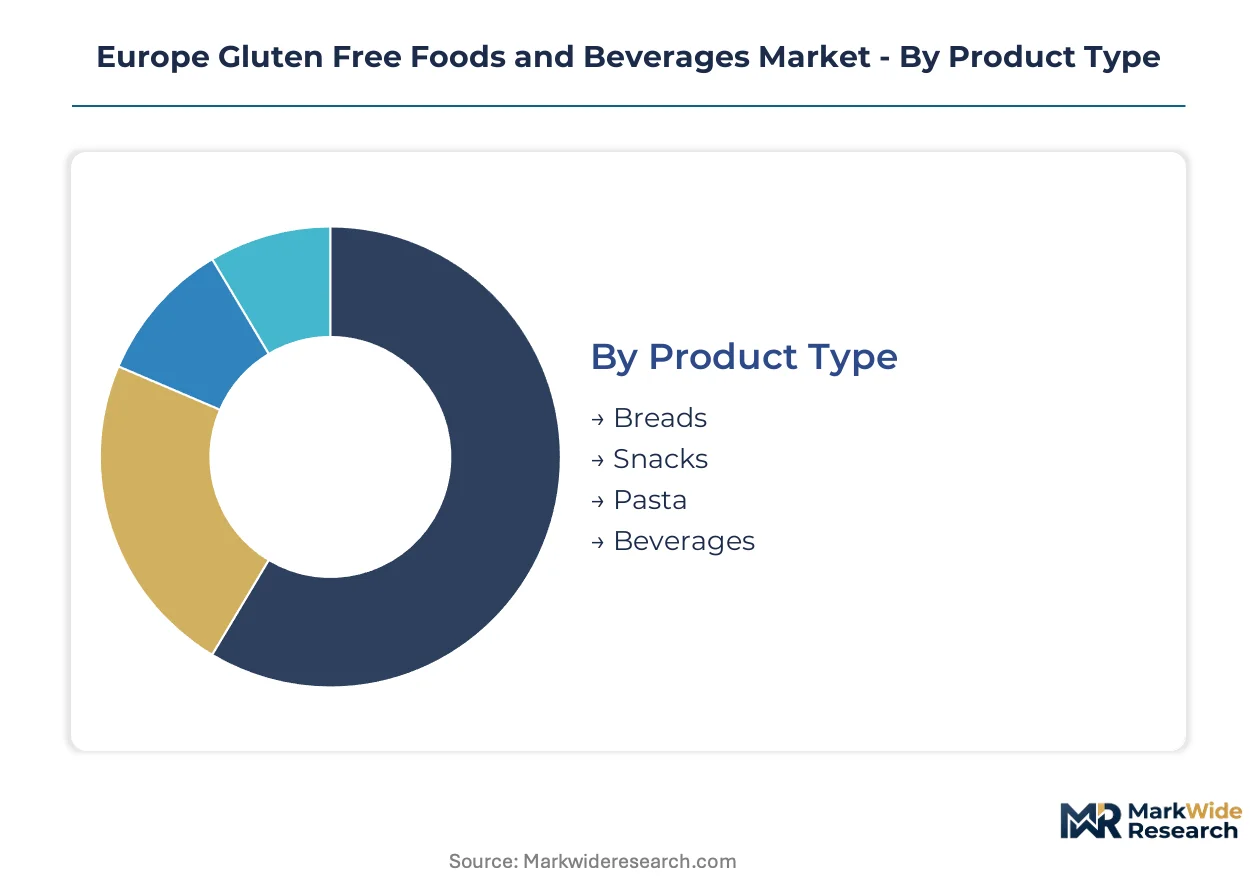
Segmentation in Europe's gluten-free market determines manufacturing scale, certification investment, and channel strategy. EFSA thresholds and national reimbursement policies create divergent profitability profiles across product formats and buyer types.
Product Type:
After-sales intensity varies sharply across formats—breads demand freshness guarantees and return protocols, while beverages require temperature-controlled logistics and batch traceability.
- Breads:Formulations rely on hydrocolloid-stabilized rice and tapioca dough systems to achieve crumb structure comparable to wheat equivalents. German and Italian retail chains dominate procurement, with shelf-life anxiety driving frequent delivery schedules and dedicated gluten-free bakery lines.
- Beverages:Functional hydration concepts—oat milk, fermented drinks, protein waters—target urban celiac households seeking digestive wellness beyond clinical necessity. Scandinavian convenience retail and UK subscription platforms concentrate uptake, with kombucha and water kefir variants gaining shelf space fastest.
- Snacks:Extruded pulse crisps and seed-based bars command impulse purchase placement in airport and railway retail across France and the Netherlands.
- Pasta:Corn and legume flour extrusions serve family meal occasions, with Italian domestic consumption anchoring volume despite premium pricing over conventional durum.
By volume, breads leads. By growth pace, beverages is ahead.
Distribution Channel:
Cost tier stratification separates premium health stores from mass-market supermarkets, with margin structures dicturing which manufacturers can sustain presence in each tier.
- Supermarkets:Controlled by four major retail groups across Germany, the UK, and France, these channels demand private-label supply capacity and promotional funding. Dedicated gluten-free shelf sections in Berlin, London, and Milan stores expand as diagnosis rates climb.
- Online Retail:Subscription replenishment models capture celiac households seeking ingredient transparency unavailable in mass retail. French and UK platforms personalize flour blends to individual tolerance thresholds, concentrating lifetime value in data-rich direct relationships.
- Health Stores:Independent organic specialists in Austria and Switzerland stock certified organic variants with full provenance documentation, serving price-insensitive clinical consumers.
- Convenience Stores:Grab-and-go snack placement targets urban commuters in Stockholm and Copenhagen, with single-serve packaging formats optimized for refrigerated display.
Supermarkets move the most units. Online retail expands most quickly.
End User:
Application logic separates institutional foodservice from household purchase, with HACCP compliance and bulk pricing terms distinguishing B2B contracts.
- Individuals:Clinical celiac patients and lifestyle consumers drive repeat purchase loyalty, with Italian and Spanish national reimbursement programs directly influencing brand selection and volume.
- Restaurants:Dedicated gluten-free kitchen protocols and staff training investments concentrate in London, Paris, and Berlin, where tourism and business dining create liability-sensitive demand.
- Hotels:Breakfast buffet segregation requirements and cross-contamination prevention drive certified supplier relationships, particularly in Alpine tourism corridors.
- Cafes:Artisan bakery-cafes in Copenhagen and Amsterdam compete on in-house gluten-free pastry production, sourcing specialty flour blends through direct mill relationships.
Individuals account for the largest spend. Restaurants gain share fastest.
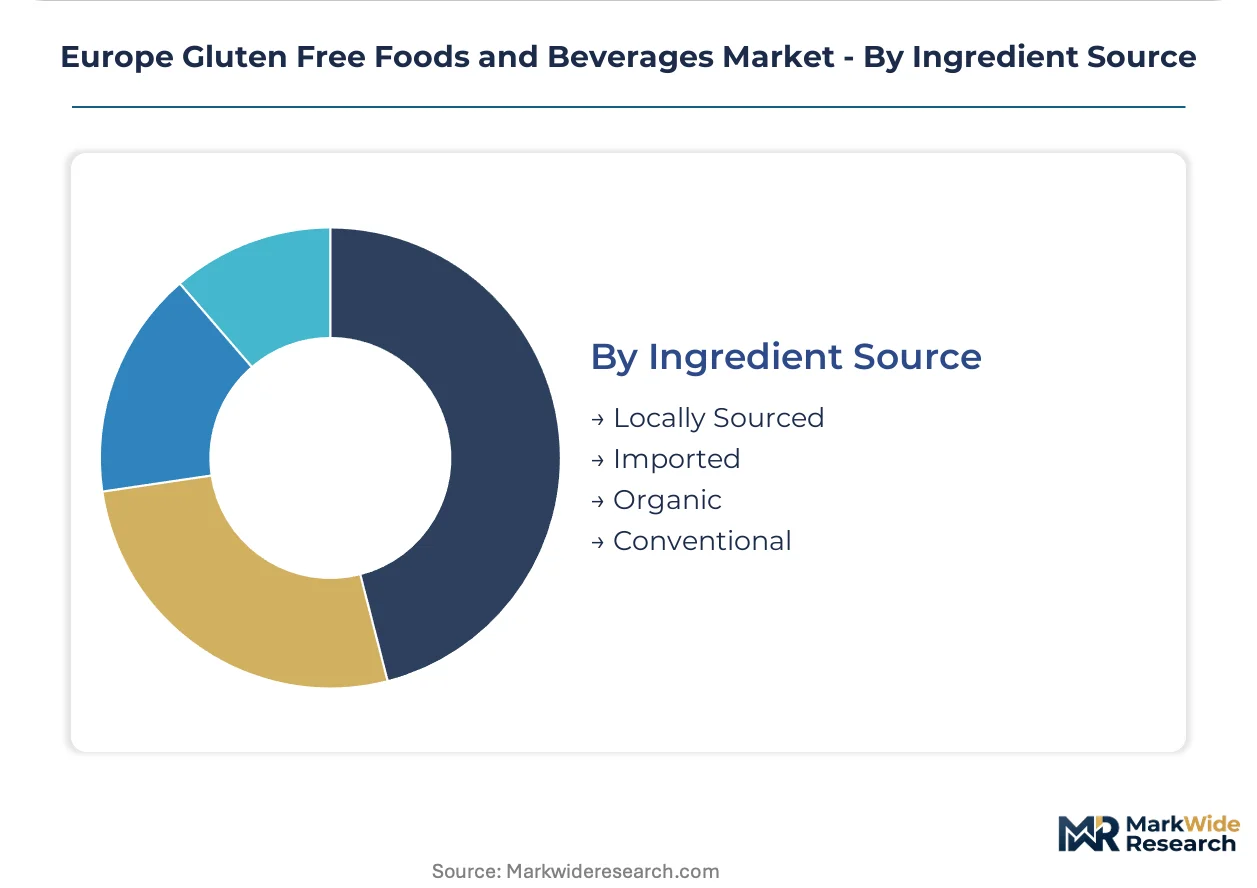
Ingredient Source:
Supply concentration in Andean quinoa and Southeast Asian tapioca creates sourcing risk that organic and local alternatives attempt to mitigate.
- Organic:EU Green Deal Farm to Fork traceability mandates force cultivar-level documentation, with German and Austrian processors facing steepest compliance curves as private-label contracts specify blockchain-verified origin data.
- Locally Sourced:Oat and pulse protein from Nordic and Baltic cultivation regions shortens transport chains, appealing to sustainability-positioned brands in Swedish and Finnish retail.
- Imported:Thai tapioca starch and Vietnamese rice flour remain cost-competitive despite currency and harvest volatility, sustaining mid-tier producer margins.
- Conventional:Non-certified conventional sourcing serves price-driven private-label programs, though EFSA gluten thresholds still mandate strict segregation protocols.
Imported ingredients dominate volume. Organic sourcing climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's gluten-free trade balance tilts toward ingredient imports, with Thai tapioca starch and Andean quinoa protein entering through Rotterdam and Hamburg ports while finished goods circulate within the single market.
Germany
Berlin and Munich sustain the continent's densest celiac diagnosis clusters, driving prescription bread reimbursement through statutory health insurers. EFSA allergen thresholds under EU Regulation 1169/2011 mandate sub-20 mg/kg gluten labeling that German processors embed into blockchain-verified supply chains. The Baden-Württemberg organic milling corridor around Stuttgart now certifies oat cultivars to cultivar-level traceability standards.
Italy
Domestic pasta consumption anchors volume despite 40% premiums over conventional durum, with Lombardy households claiming national celiac food subsidies. Rome's Ministry of Health maintains Europe's most generous prescription reimbursement program, directly influencing brand loyalty dynamics. Bologna's food technology cluster hosts extrusion research facilities advancing pulse-protein texturization for bakery applications.
United Kingdom
London's urban health-conscious population drives subscription-based direct-to-consumer replenishment for ingredient-transparent flour blends. The Food Standards Agency enforces EFSA-aligned gluten thresholds while post-Brexit import checks delay Andean quinoa protein at Dover. Manchester's bakery-cafe density supports artisan gluten-free pastry production through direct mill relationships.
Spain
Madrid and Barcelona await pending national celiac food subsidy expansion that would unlock institutional channel volume for certified suppliers. Spanish organic processors face compressed compliance timelines under EU Green Deal Farm to Fork mandates requiring harvest-batch documentation. Valencia's rice flour milling infrastructure supplies Mediterranean private-label programs.
France
Parisian retail chains demand promotional funding and private-label supply capacity that favors scaled bakery operations over artisan entrants. ANSM food safety inspections enforce gluten segregation protocols that add fixed overhead for small producers. The Auvergne-Rhône-Alpes organic oat cultivation belt shortens transport chains for sustainability-positioned brands.
Europe Gluten Free Foods and Beverages Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated multinational bakery networks, specialized gluten-free pure-plays, and private-label contract manufacturers. Multinationals leverage scaled production to secure shelf space in German and UK supermarket chains. Pure-plays dominate health stores and prescription channels through certification depth. Contract manufacturers capture mid-tier volume via asset-light white-label financing. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Within the specialized pure-play tier, Dr. Schär AG/SPA and Genius Foods Ltd exemplify certification-first positioning that commands premium placement in Italian and UK health channels. Among diversified multinationals, General Mills Inc. and Danone S.A. occupy positions leveraging scaled bakery and beverage operations respectively to sustain consistent supply across European retail formats. Warburtons Ltd represents the heritage bakery archetype adapting wheat-dominant expertise toward segregated gluten-free production lines.
| Leading Market Players |
|---|
| Dr. Schär AG/SPA |
| General Mills Inc. |
| Warburtons Ltd |
| Genius Foods Ltd |
| Hain Celestial Group |
| Conagra Brands Inc. |
| The Kraft Heinz Company |
| Premier Foods PLC |
| Danone S.A. |
| Others |
Supply Flow & Price Mechanics
Thai tapioca starch harvest volatility determines both pricing tier spreads and supply chain shape across European gluten-free manufacturing, compressing mid-tier producer margins while forcing premium brands toward Nordic oat and Baltic pulse protein alternatives. EFSA certification costs and EU Green Deal traceability mandates layer fixed compliance overhead onto ingredient sourcing decisions, widening the gap between economy private-label and certified organic positioning.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that sustain volume commitments from German and Italian bakery networks. Price differentiation separates certified organic oat cultivars with blockchain-verified provenance from economy rice flour blends serving price-driven private-label programs. Cost compression in the mid-tier is intensifying because Thai harvest volatility feeds directly into tapioca starch input costs. Clinical celiac households seeking prescription reimbursement show least price sensitivity, while convenience retail snack purchasers exhibit highest elasticity.
Supply Chain Analysis
EU Regulation 1169/2011 and EFSA gluten threshold enforcement restrict ingredient flows through mandatory segregation protocols that block uncertified suppliers from verified channels. Raw material sourcing draws from Thai tapioca starch corridors, Vietnamese rice flour milling, and Andean quinoa protein concentrate import routes. Single-source vulnerability concentrates in Peruvian export licensing delays for quinoa protein. Distribution runs through Rotterdam and Hamburg port entry points for ingredient imports, with finished goods circulating via dedicated gluten-free logistics networks to German, Italian, and UK retail consolidation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as celiac diagnosis clusters concentrate in urban health corridors, creating niche subscription and specialty retail channels outside supermarket consolidation. Lifestyle consumers seeking digestive wellness diverge from clinical patients on ingredient transparency priorities, opening positioning space for differentiated entrants.
For Market Incumbents: Insulate prescription channel relationships in Italy and Spain through deepening certification investment and national reimbursement program compliance. Threat from enzymatic gluten degradation technology neutralizing specialty grain silo advantages demands accelerated R&D in precision fermentation alternatives. Vertical integration into Nordic oat cultivation secures cultivar-level traceability for EU Green Deal procurement incentives.
For New Entrants and Emerging Players: Build out direct-to-consumer subscription platforms targeting London and Berlin celiac households with personalized flour blend formulations. Scandinavian fermented beverage convergence offers most penetrable white-space for kombucha and water kefir variants. Go-to-market angle should leverage Farm to Fork organic certification for preferential listing terms in Austrian and Swiss health stores.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized gluten-free pure-plays with certification depth over diversified multinationals. Long-term viability over the next decade hinges on traceability infrastructure and prescription channel access. Acquisition target archetype: mid-tier contract manufacturers with asset-light white-label capacity and existing EFSA compliance protocols. Signal to watch is Spanish national celiac food subsidy expansion unlocking institutional volume.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Certification Investment | Blockchain-verified supply chains secure preferential shelf placement in German organic retail. |
| Pulse Protein Extrusion Scale-Up | Fava bean and lentil texturization closes sensory gaps with wheat-based bakery equivalents. |
| Direct-to-Consumer Platform Launch | Subscription replenishment captures lifetime value from data-rich celiac household relationships. |
| Nordic Oat Supply Agreement | Farm to Fork traceability mandates reward locally sourced organic cultivation with procurement preference. |
| Prescription Channel Expansion | National reimbursement program alignment in Italy and Spain locks in institutional volume commitment. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with product development directors at gluten-free manufacturers, category buyers at German and UK supermarket chains, regulatory affairs specialists navigating EFSA compliance, and supply chain managers overseeing Andean quinoa import corridors. Secondary validation drew from EFSA allergen threshold documentation, EU Regulation 1169/2011 filings, Farm to Fork strategy implementation reports, and national celiac association prescription reimbursement databases. Bottom-up volume modeling triangulated against top-down market sizing across ingredient source, product format, and distribution channel dimensions.
Calibration anchored volume and value outputs to historical diagnosis rate trajectories, reimbursement policy expansion timelines, and retail shelf space allocation patterns across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end user category, and ingredient certification tier. CAGRs were derived from trend extrapolation adjusted for regulatory implementation lag effects and supply chain infrastructure buildout pace. Industry-specific forecast inputs incorporated EFSA compliance cost curves and organic certification adoption rates.
Stress conditions across Thai harvest volatility bands, Peruvian export licensing delays, and Spanish subsidy expansion scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on diagnosis rate growth, retail consolidation trajectories, and traceability technology diffusion. Material shifts in EFSA threshold revisions or EU Green Deal procurement incentive restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Food Intolerance Products Market
Food Intolerance Products
Allergen Free Food Market
Food Intolerance Products
Italy Gluten-Free Foods and Beverages Market
Food Intolerance Products
Egg Allergy Market
Food Intolerance Products
Dyspepsia Market
Food Intolerance Products
Global Gluten Free Prepared Foods Market
Food Intolerance Products
Allergen Free Food Products Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
Global Gluten-Free Ready Meals Market
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market
Food Intolerance Products
Gluten-Free Pasta Market
Food Intolerance Products
Food Allergy and Intolerance Products Market
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
United States Gluten Free Foods and Beverages Market
Food Intolerance Products
North America Free from Food Market