
 Ethical Label Market | 2026-2036
Ethical Label Market Size, Share, and Industry Trends Forecast 2026-2036
Ethical Label Market Analysis
Recycled fiber substrates is shifting toward bioplastic alternatives as converters seek lower-carbon footprints in label construction. Unilever leverages its Sustainable Living Plan to mandate ethical label compliance across third-party suppliers. Nestlé sustains strict internal certification protocols that exceed baseline Fair Trade requirements. Danone competes through geographic dominance in European dairy segments where organic label penetration remains highest.
Ethical labels are adhesive-backed or direct-printed markings that communicate verified social or environmental claims through certified symbols, material provenance data, and chain-of-custody documentation; they function as trust mechanisms enabling consumers to identify products meeting defined labor, ecological, or animal welfare standards. Organic labels and Fair Trade labels anchor the value pool, with the former commanding premium positioning in fresh produce and processed foods while the latter deepens penetration in coffee and cocoa supply chains. Bioplastics within the material dimension represents the fastest-growing substrate category as converters respond to brand-owner mandates for petroleum reduction.
The EU Green Deal and REACH frameworks in Europe enforce chemical transparency and recyclability thresholds that reshape adhesive formulation and substrate selection for label producers. USDA Organic and Fair Trade Certified standards in the United States create dual-compliance burdens for multinational food brands operating across Atlantic markets. Stakeholders must monitor evolving compostability certifications and polymer traceability requirements as retailer procurement codes tighten ahead of regulatory deadlines.
Market Dynamics
Retailer procurement mandates are compressing compliance timelines for label converters, forcing simultaneous reformulation of adhesives and substrates to satisfy both EU Green Deal chemical thresholds and chain-of-custody documentation requirements.
Growth Catalysts
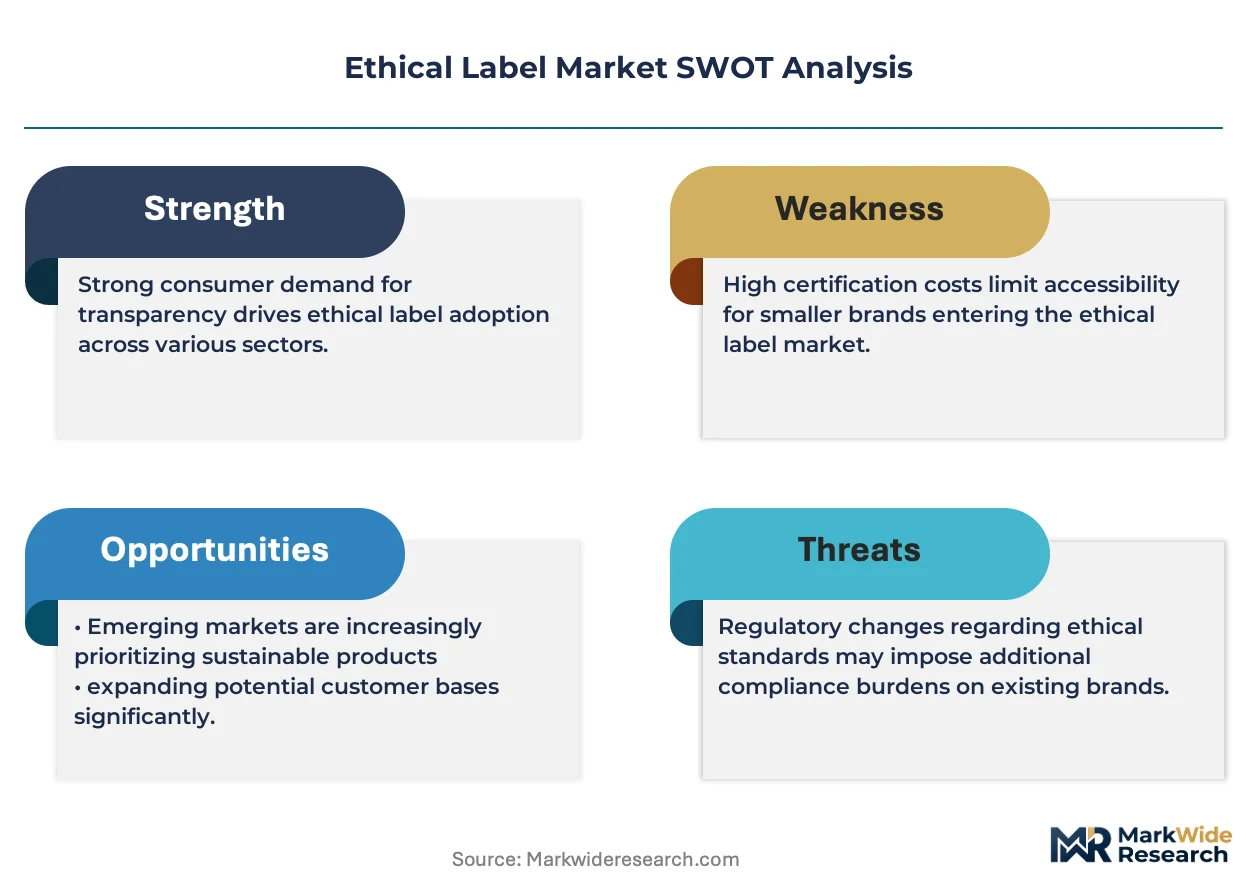
- EU Green Deal chemical transparency mandates:REACH enforcement compels converters to disclose polymer origins, accelerating substrate innovation cycles.
- Bioplastic substrate adoption:Brand-owner petroleum reduction targets pull polylactic acid and starch-based films into premium label constructions.
- German retail concentration:Rewe, Aldi, and Lidl procurement standards cascade through centralized converter networks, standardizing ethical label specifications across European supply chains.
Market Restraints
- Adhesive raw material volatility:Petroleum-derived acrylic resins face price swings that compress converter margins on fixed-price retail contracts.
- Certification timeline friction:Fair Trade and organic label approvals stretch 12-18 months, delaying product launches for seasonal food categories.
- Compostable film performance gaps:Current bioplastic barriers exhibit moisture sensitivity that limits deployment in refrigerated dairy applications.
Strategic Opportunities
- Blockchain-enabled traceability:Distributed ledger systems for chain-of-custody documentation differentiate premium label offerings.
- Direct-to-brand digital channels:E-commerce platforms bypass traditional distributor markups for mid-size organic food producers.
- EU CSRD reporting alignment:Corporate sustainability disclosure requirements create bundled demand for environmental labels and accompanying data services.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for bio-based adhesives concentrates in German and Dutch research clusters, constraining converter hiring pipelines.
- Legacy printing press retrofit costs:Water-based ink systems for compostable substrates demand capital outlays that strain mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethical Label Market |
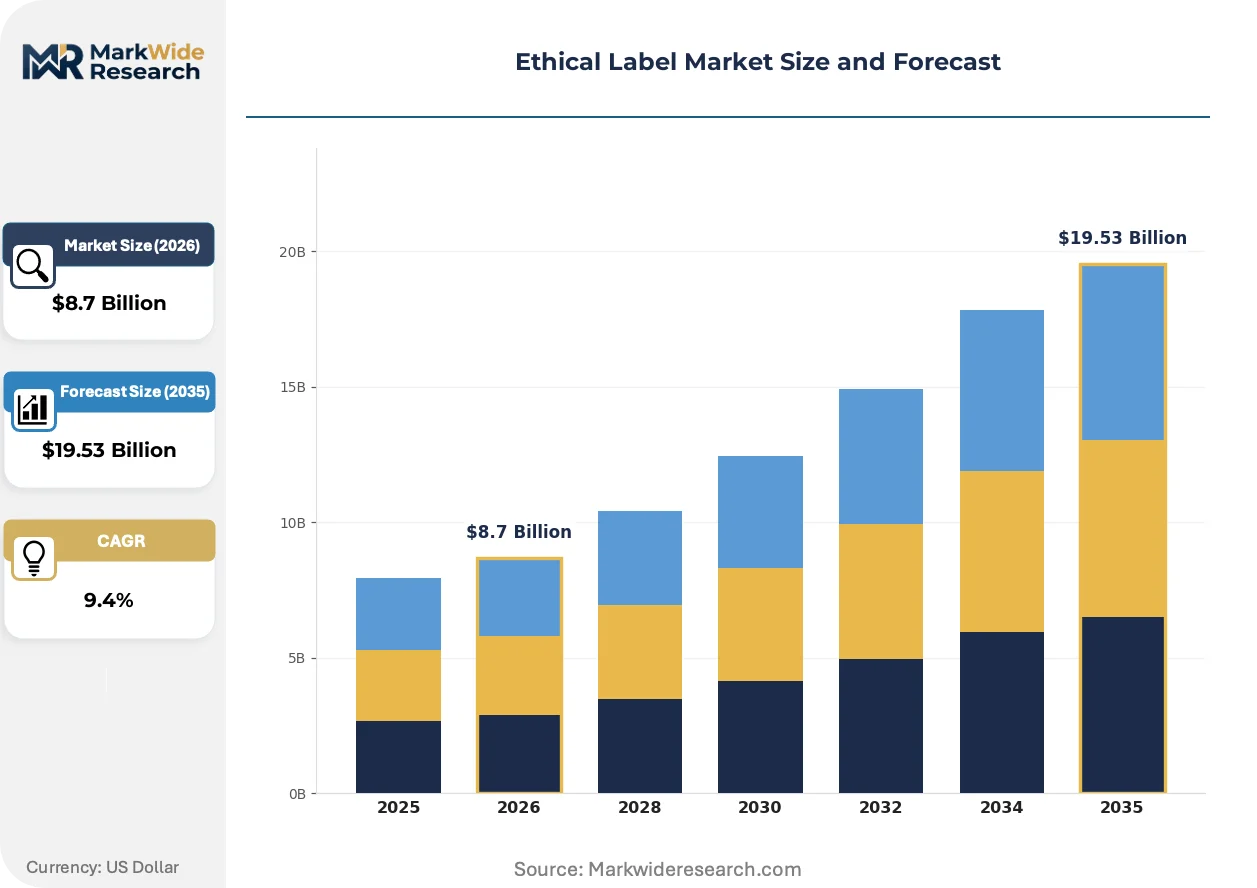
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Labels, Fair Trade Labels, Eco-Friendly Labels, Vegan Labels End User: Retailers, Manufacturers, Distributors, Consumers Material: Paper, Polyester, Bioplastics, Recycled Materials Certification: ISO 14001, USDA Organic, Fair Trade Certified, Others |
| Companies Covered | Unilever, Nestlé, Danone, Cargill, Archer-Daniels-Midland Company, The Body Shop, Patagonia, PepsiCo, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethical Label Market Emerging Trajectories
Material science breakthroughs and regulatory disclosure mandates are converging to redefine what constitutes a verifiable ethical claim, shifting competitive advantage toward converters with integrated testing and certification capabilities.
Near-field communication chips embedded in pressure-sensitive labels is integrating product-level traceability data directly into consumer smartphone interactions. Specialty food brands in Nordic markets are piloting these constructions at 15-20% volume premiums. The technology is integrating physical product authentication with digital storytelling platforms, compressing the distance between farm-origin documentation and point-of-sale verification.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon elimination from label drying and curing processes. Converters serving frozen food segments must retool thermal transfer equipment by mandated deadlines. German packaging clusters are absorbing compliance costs fastest, while Southern European converters lag in capital deployment.
Certification-driven preference shifts are restructuring buyer-supplier contracting patterns. Major retail chains now specify dual organic-Fair Trade compliance in produce category tenders, displacing single-certification suppliers. This concentration is most visible in Dutch and Belgian supermarket private label programs, where procurement teams consolidate vendor bases to reduce audit overhead.
Ethical Label Market Segmentation
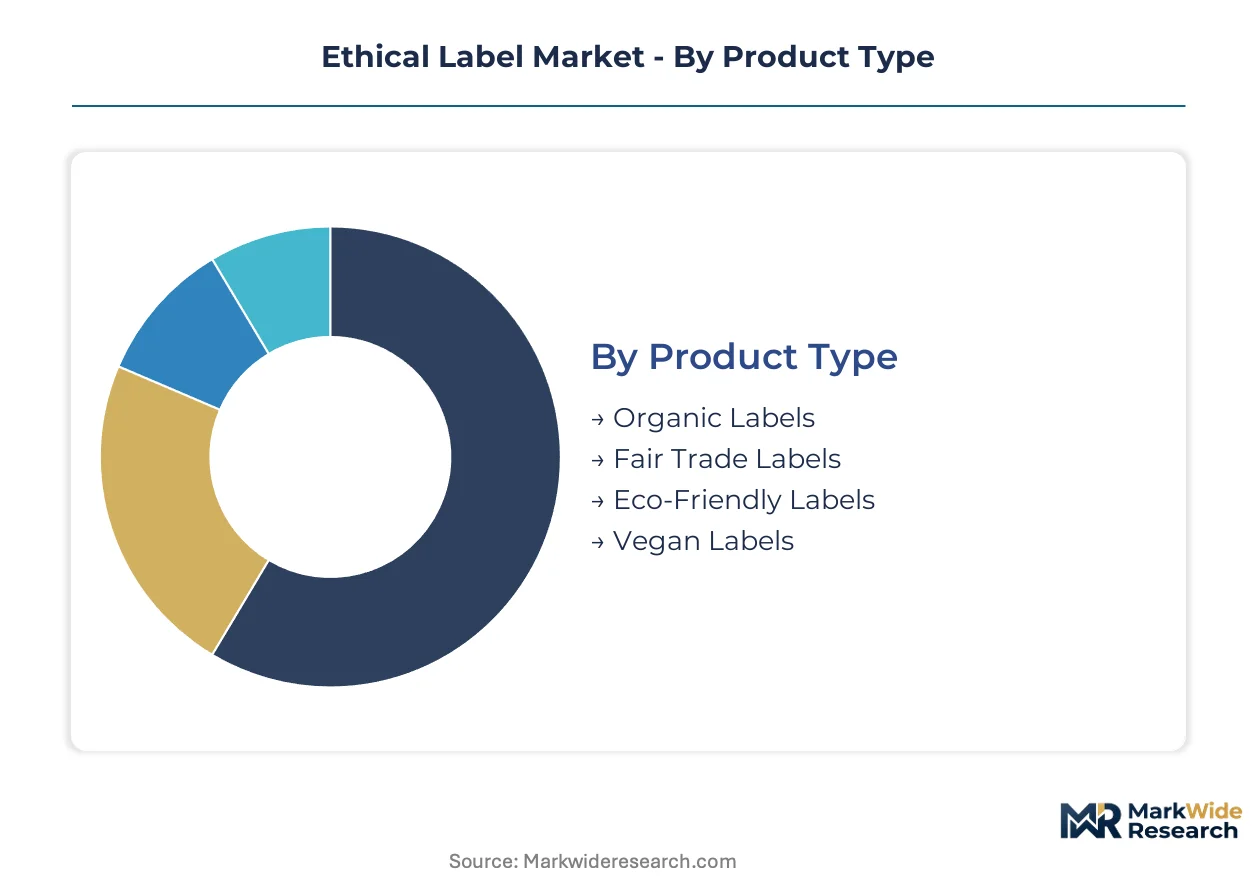
Ethical label converters must align substrate specifications, certification tiers, and end-user procurement protocols simultaneously. Segmentation reveals where formulation investments generate compliance premiums versus commodity positioning.
Product Type:
Upgrade cycles in food packaging are accelerating as retailers consolidate supplier bases around dual-certification standards.
- Organic Labels:These constructions incorporate USDA Organic or EU organic seal compliance with substrate traceability documentation. Demand clusters in German fresh produce supply chains where Rewe and Aldi mandate chain-of-custody verification for private label programs.
- Fair Trade Labels:Certified marks verifying labor standards and minimum price guarantees in agricultural supply chains. Coffee and cocoa processors in the Netherlands and Belgium specify these labels for retail-facing packaging, driven by concentrated buyer procurement codes.
- Eco-Friendly Labels:Broad environmental claims without single-certification lock-in, often combining recycled content with reduced adhesive mass.
- Vegan Labels:Animal-derivative-free verification marks expanding in European dairy alternatives and confectionery segments.
Volume placements concentrate in Organic Labels; the faster expansion belongs to Vegan Labels.
End User:
Cost tier differentiation separates enterprise procurement teams with dedicated sustainability officers from price-sensitive intermediaries.
- Retailers:Centralized buyers at Lidl, Aldi, and Rewe dictate substrate specifications through master service agreements that cascade to converter networks.
- Manufacturers:Nestlé and Unilever maintain internal certification protocols exceeding baseline requirements, creating premium tier demand for integrated testing capabilities.
- Distributors:Intermediate logistics players with limited influence over label specifications, capturing residual volume in fragmented regional markets.
- Consumers:Direct purchasers of specialty food products where NFC-enabled labels support smartphone verification at 15-20% price premiums in Nordic markets.
Margin capture concentrates with Manufacturers; the steepest expansion trajectory sits with Retailers consolidating vendor bases.
Material:
Application requirements in refrigerated versus ambient storage are forcing substrate specialization across converter portfolios.
- Paper:Recycled fiber constructions face displacement pressure as bioplastic barriers improve moisture resistance for frozen food segments.
- Polyester:Petroleum-derived films dominate durable goods labeling but face regulatory pressure under EU Green Deal chemical transparency mandates.
- Bioplastics:Polylactic acid and starch-based films are gaining share fastest as brand-owner petroleum reduction targets pull these substrates into premium constructions. REACH enforcement on polymer origin disclosure accelerates formulation innovation cycles in German packaging clusters.
- Recycled Materials:Post-consumer content specifications vary by retailer procurement code, creating compliance complexity for multi-market suppliers.
Current volume concentrates in Polyester; bioplastic substitution is climbing the fastest.
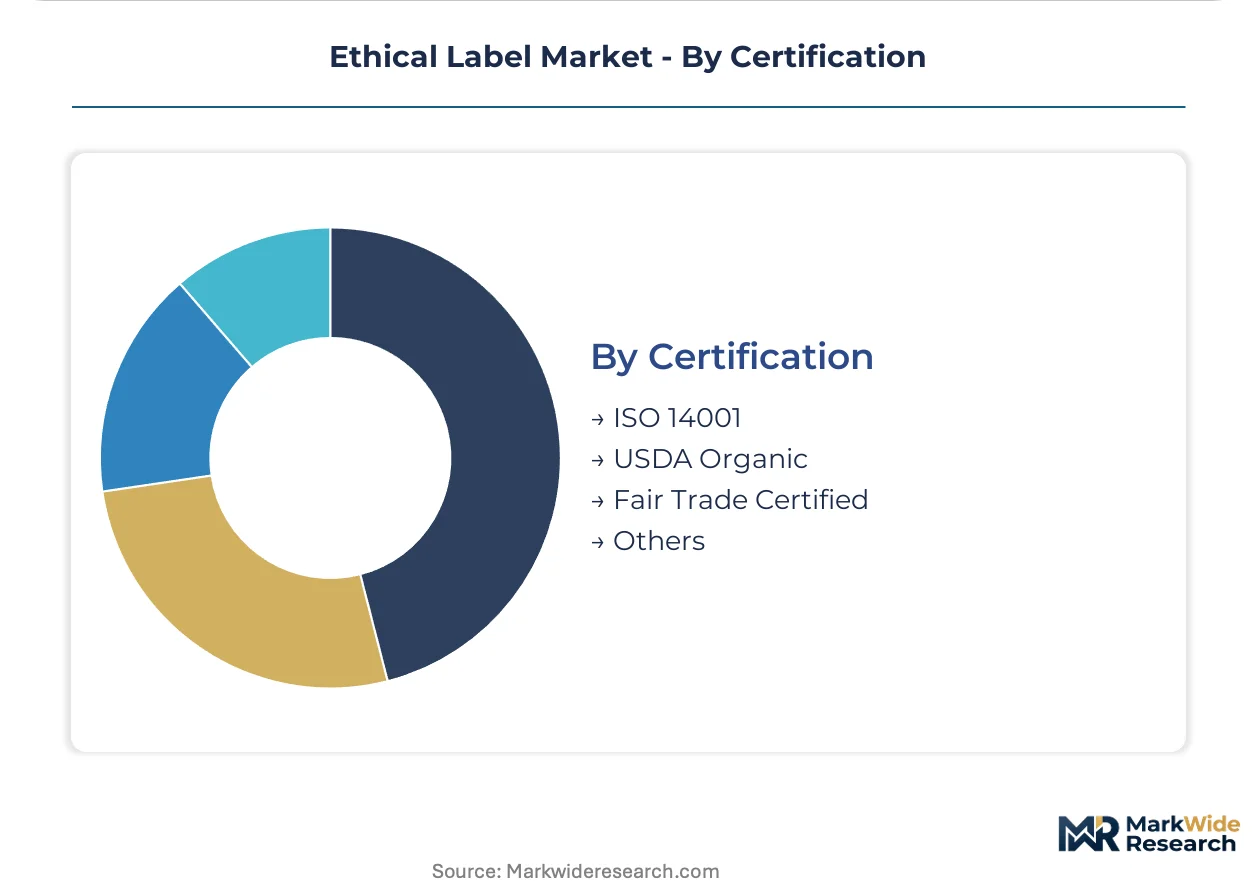
Certification:
Supply concentration in German and Dutch testing clusters creates capability scarcity for multi-standard compliance.
- ISO 14001:Environmental management system certification providing baseline credibility for industrial label converters serving pan-European manufacturers.
- USDA Organic:United States standard creating dual-compliance burdens for Atlantic-spanning food brands, with approval timelines stretching 12-18 months.
- Fair Trade Certified:Labor and pricing verification mark with deepest penetration in coffee supply chains, where Dutch and Belgian supermarket private label programs now mandate dual organic-Fair Trade compliance.
- Others:Emerging compostability certifications and polymer traceability standards ahead of tightening retailer deadlines.
Audit volume concentrates in Fair Trade Certified; ISO 14001 is gaining share fastest among mid-tier converters seeking operational credibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German packaging clusters anchor European ethical label production, with the Rhine-Ruhr and Baden-Württemberg regions concentrating converter capacity near centralized retail procurement headquarters.
Germany
Rewe, Aldi, and Lidl procurement standards cascade through converter networks, mandating dual organic-Fair Trade compliance for private label programs. REACH enforcement from ECHA compels polymer origin disclosure, accelerating bioplastic formulation cycles. The Stuttgart packaging corridor houses specialized adhesive labs serving frozen food segments facing F-Gas Regulation retooling deadlines.
Netherlands
Dutch supermarket private label programs now specify dual certification in produce tenders, displacing single-certification suppliers. The country's national food safety authority enforces chain-of-custody documentation aligned with EU Green Deal transparency mandates. Rotterdam-Antwerp logistics corridors concentrate label distribution for Atlantic-spanning food brands managing USDA Organic dual-compliance burdens.
Belgium
Coffee and cocoa processors in Flanders specify Fair Trade labels for retail-facing packaging, driven by concentrated buyer procurement codes. Federal environmental regulations enforce chemical transparency thresholds that reshape substrate selection. The Ghent biotech corridor hosts certification testing clusters where approval timelines stretch 12-18 months for seasonal food categories.
United States
USDA Organic and Fair Trade Certified standards create dual-compliance burdens for multinational food brands operating across Atlantic markets. FDA food labeling requirements intersect with state-level extended producer responsibility laws in California and New York. Midwestern printing clusters around Chicago absorb retrofit costs for water-based ink systems serving compostable substrate demand.
France
ANSM and CNIL oversight intersects with EU Green Deal implementation, creating layered disclosure requirements for label converters. Île-de-France retail headquarters drive national procurement standardization for organic label penetration in fresh produce. The Lyon chemicals corridor supplies bio-based adhesive formulations as petroleum-derived acrylic resin volatility compresses converter margins.
Ethical Label Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational food corporations maintaining internal certification protocols while mid-tier converters serve fragmented regional markets. Three archetypes dominate: brand owners with captive sustainability mandates, independent converters with integrated testing capabilities, and commodity suppliers competing on volume scale. M&A activity concentrates certification assets in German and Dutch clusters, while strategic partnerships between converters and bioplastic resin suppliers accelerate substrate innovation cycles.
Among brand-owner archetypes, Unilever, Nestlé, and Danone exemplify divergent compliance strategies. Unilever leverages its Sustainable Living Plan to mandate ethical label compliance across third-party suppliers. Nestlé sustains strict internal certification protocols that exceed baseline Fair Trade requirements. Danone competes through geographic dominance in European dairy segments where organic label penetration remains highest.
| Leading Market Players |
|---|
| Unilever |
| Nestlé |
| Danone |
| Cargill |
| Archer-Daniels-Midland Company |
| The Body Shop |
| Patagonia |
| PepsiCo |
| Kerry Group |
| Others |
Supply Flow & Price Mechanics
Bioplastic substrate formulation is compressing cost economics for mid-tier converters while concentrating supply leverage among German adhesive labs with REACH-compliant polymer expertise. Rewe and Aldi procurement mandates force simultaneous price and specification compliance, squeezing converters without backward integration into resin supply.
Pricing Analysis
Volume placements cluster in standard-tier polyester labels while premium margins concentrate in bioplastic constructions with dual organic-Fair Trade certification. Price differentiation hinges on certification grade and petroleum-derived versus bio-based substrate sourcing. Cost compression in standard tiers is intensifying because petroleum resin volatility collides with fixed-price retail contracts. Distributors exhibit highest price sensitivity; brand owners with captive sustainability mandates absorb premium tier increases.
Supply Chain Analysis
Freight cost differentials between Rotterdam-Antwerp corridors and Southern European distribution networks favor Rhine-Ruhr converter concentration. Raw material supply draws from German petrochemical corridors for acrylic resins, Dutch biotech clusters for polylactic acid feedstock, and Belgian testing facilities for certification documentation. Single-source vulnerability sits with petroleum-derived adhesive precursors facing ECHA disclosure mandates. Distribution runs through centralized retail procurement headquarters in Stuttgart and Düsseldorf before cascading to converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ethical label market is becoming a vertical-integration race as converters pursue captive supply of bio-based adhesives to escape petroleum resin margin volatility.
For Market Incumbents: Lock in polymer formulation expertise through German and Dutch research cluster partnerships before bioplastic chemist scarcity worsens. Defend margin position by retrofitting water-based ink systems ahead of F-Gas Regulation deadlines, as Southern European converters lag in capital deployment and will cede frozen food segment share. For New Entrants and Emerging Players: Launch via direct-to-brand digital channels serving mid-size organic food producers in Nordic markets where NFC-enabled labels command smartphone-verified premiums. White-space sits in vegan label constructions for European dairy alternatives, where certification testing capacity has not matched demand expansion. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of integrated testing-and-certification assets in Belgian and Dutch clusters where approval timelines create bottleneck value. Long-term viability favors converters with backward integration into bioplastic resin supply and blockchain-enabled traceability capabilities. Watch compostable film moisture resistance breakthroughs as the inflection signal for refrigerated dairy penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bioplastic Resin Supply | Captive polylactic acid sourcing insulates converters from petroleum price volatility under REACH enforcement. |
| Blockchain-Enabled Traceability Deployment | NFC chip integration differentiates premium offerings for Nordic specialty food brands seeking farm-to-shelf verification. |
| Water-Based Ink System Retrofit | Compostable substrate compatibility satisfies EU Green Deal chemical thresholds ahead of regulatory deadlines. |
| Dual Certification Testing Investment | Integrated organic-Fair Trade capabilities capture Dutch and Belgian retail procurement consolidation. |
| Direct-to-Brand Digital Channel Launch | E-commerce platforms bypass distributor markups for mid-tier organic producers with compressed compliance timelines. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with label converter plant managers, retail procurement leads at Rewe and Aldi, bioplastic R&D directors, and certification testing facility operators. ECHA polymer disclosure databases, EU Green Deal implementation trackers, and frozen food segment equipment expenditure reports provided validation layers. Bottom-up volume estimates triangulated against top-down retail procurement mandate analysis.
Data-stream reconciliation across substrate shipment records, adhesive formulation patent filings, and certification approval timelines generated consistent growth trajectories. Segmentation modeling spanned product type, material substrate, certification tier, end-user archetype, and regional regulatory cluster. CAGRs derived from polynomial trend fitting to historical placement volumes, adjusted for procurement mandate acceleration effects and bioplastic substitution elasticity parameters.
Regulatory deadline delays, bioplastic moisture resistance breakthrough timing, and petroleum resin price spike duration are the dominant revision risks to forecast assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Security Labels Market
Labels
Direct Thermal Linerless Labels Market
Labels
Metallic Labels Market
Labels
Multi-Part Labels Market
Labels
Eco-Friendly Labels Market
Labels
Screen Print Label Market
Labels
APAC on-Demand Color Labels Market
Labels
Oxygen Indicator Labels Market
Labels
BOPP Labels Market
Labels
Barcode Label Printer Market
Labels
Canning Labels Market
Labels
Barcode Label Market
Labels
United States Print Label Market
Labels
GCC Labels and Release Liners Market
Labels
Global Waterproof Labels Market
Labels
Wire Marking Labels Market