
 Non-Adhesive Tags Market | 2026-2036
Non-Adhesive Tags Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Adhesive Tags Market Analytics
Multi-source procurement among tag converters is broadening as brand owners seek supply resilience against resin and pulp volatility. CCL Industries Inc. anchors North American capacity through in-house film extrusion and print finishing. Avery Dennison Corporation leverages its materials science portfolio to dominate premium plastic tag segments for apparel and logistics. Brady Corporation specializes in durable metal tags for industrial asset tracking, competing on chemical resistance specifications.
Non-adhesive tags are identification and information carriers manufactured without pressure-sensitive backing, typically incorporating eyelets, slots, ties, or clips for mechanical attachment; substrates range from coated paper and synthetic fabrics to anodized aluminum and laser-markable stainless steel, with thickness tolerances often specified between 0.15 mm and 1.2 mm depending on end-use durability requirements. Plastic tags lead unit volume due to moisture resistance in outdoor logistics and food processing environments, while fabric tags capture premium positioning in apparel branding where soft-hand feel and sew-on compatibility command higher unit margins. Paper tags retain cost sensitivity in retail pricing and fast-fashion applications where single-use cycles dominate.
FDA traceability rules for food and pharmaceutical packaging shape substrate selection and print permanence requirements in the United States, while REACH and RoHS compliance in Europe restrict certain halogenated compounds in plastic tag formulations. ISO 15415 and GS1 standards govern barcode print quality and data syntax, directly affecting equipment investment and qualification protocols for tag producers. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to internalize recycling infrastructure or partner with specialized waste handlers.
Market Dynamics
RFID-enabled non-adhesive tags are compressing replacement cycles across logistics and retail as automated sortation systems demand machine-readable durability that printed barcodes cannot deliver.
Growth Catalysts
- EU Green Deal packaging directives:Recyclable paper and fabric substrates gain preference as brand owners face extended producer responsibility obligations across Germany, France, and Italy.
- Automotive supply chain traceability:German industrial labeling standards mandate durable metal and synthetic tags for component tracking from Tier 3 suppliers through final assembly.
- Laser-markable stainless steel:Chemical-resistant substrates penetrate pharmaceutical cold chains where FDA traceability rules require permanent identification through temperature cycling.
Market Restraints
- Pulp and resin input volatility:Coated paper and polypropylene substrate costs fluctuate with energy-intensive production concentrated in Gulf Coast petrochemical corridors.
- REACH and RoHS compliance friction:Halogenated compound restrictions in EU plastic formulations force reformulation cycles that extend qualification timelines for tag converters.
- Adhesive label substitution in low-durability applications:Pressure-sensitive alternatives capture fast-fashion pricing tags where single-use economics dominate unit volume.
Strategic Opportunities
- India pharmaceutical export compliance:CDSCO traceability alignment with FDA and EMA standards creates demand for ISO 15415-compliant barcode permanence in bulk drug packaging.
- RFID-inlay convergence with fabric substrates:Apparel brand owners embed EPC Gen2 tags in sew-on labels for inventory accuracy without secondary attachment.
- Direct-to-retailer digital procurement platforms:Tag converters bypass distributor markups through B2B portals that specify substrate, print method, and GS1 data syntax in unified workflows.
Industry Challenges
- Print permanence certification timelines:ISO 15415 barcode quality validation requires capital-intensive verifier equipment and operator training that stretches onboarding for new production lines.
- Legacy WMS integration friction:Warehouse management systems built for linear barcode scanning require middleware development to parse RFID tag data streams without forklift hardware replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Adhesive Tags Market |
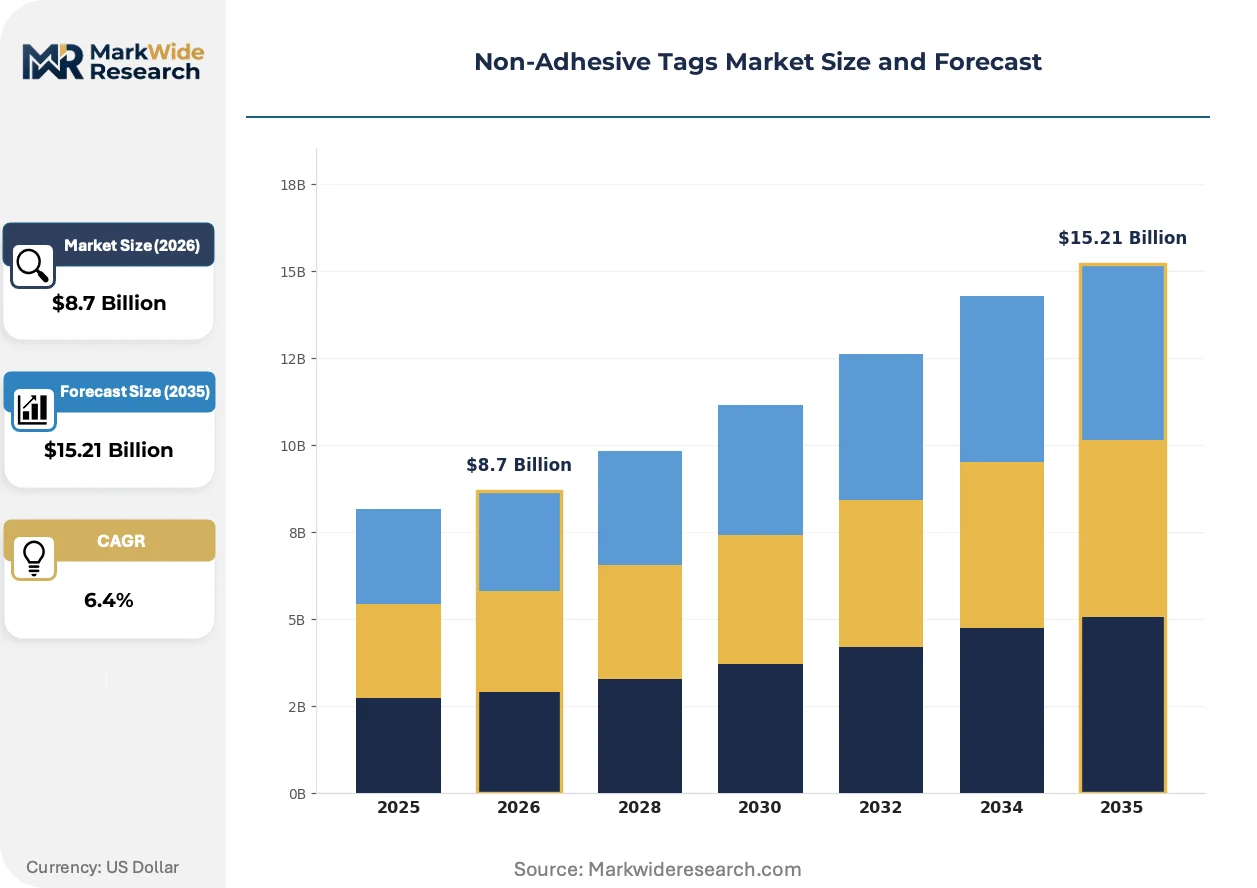
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Tags, Fabric Tags, Plastic Tags, Metal Tags Application: Pricing, Branding, Inventory Management, Event Identification End User: Retailers, Manufacturers, Logistics Providers, Event Organizers Size: Small, Medium, Large, Extra Large |
| Companies Covered | Avery Dennison Corporation, CCL Industries Inc., Zebra Technologies Corporation, Brady Corporation, UPM Raflatac, Sato Holdings Corporation, 3M, LINTEC Corporation, Mondi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Adhesive Tags Market Evolving Landscape
Material science advances and regulatory stringency are compressing substrate selection criteria while expanding functional expectations for traceability and circularity.
Laser-markable anodized aluminum is overtaking printed polyester in industrial asset tracking applications. Automotive and aerospace maintenance operations specify metal tags that withstand solvent exposure and UV degradation without ink degradation. This substrate transition is compressing margin pools for conventional thermal transfer ribbon suppliers while elevating capital requirements for fiber laser marking equipment.
REACH substance restrictions are tightening halogenated flame retardant tolerances in plastic tag formulations across EU member states. Tag converters reformulate polypropylene and polyethylene substrates to maintain UL94 ratings without restricted compounds. German automotive suppliers accelerate qualification of compliant alternatives ahead of 2025 enforcement milestones to avoid supply disruption.
Brand owners now specify substrate recyclability in RFQ documentation as a scored evaluation criterion. Fast-fashion retailers in the United States and Western Europe award contracts to converters offering closed-loop paper fiber recovery or chemically recyclable polyester alternatives. This preference shift elevates unit margins for certified sustainable substrates while squeezing undifferentiated commodity tag producers.
Non-Adhesive Tags Market Segmentation
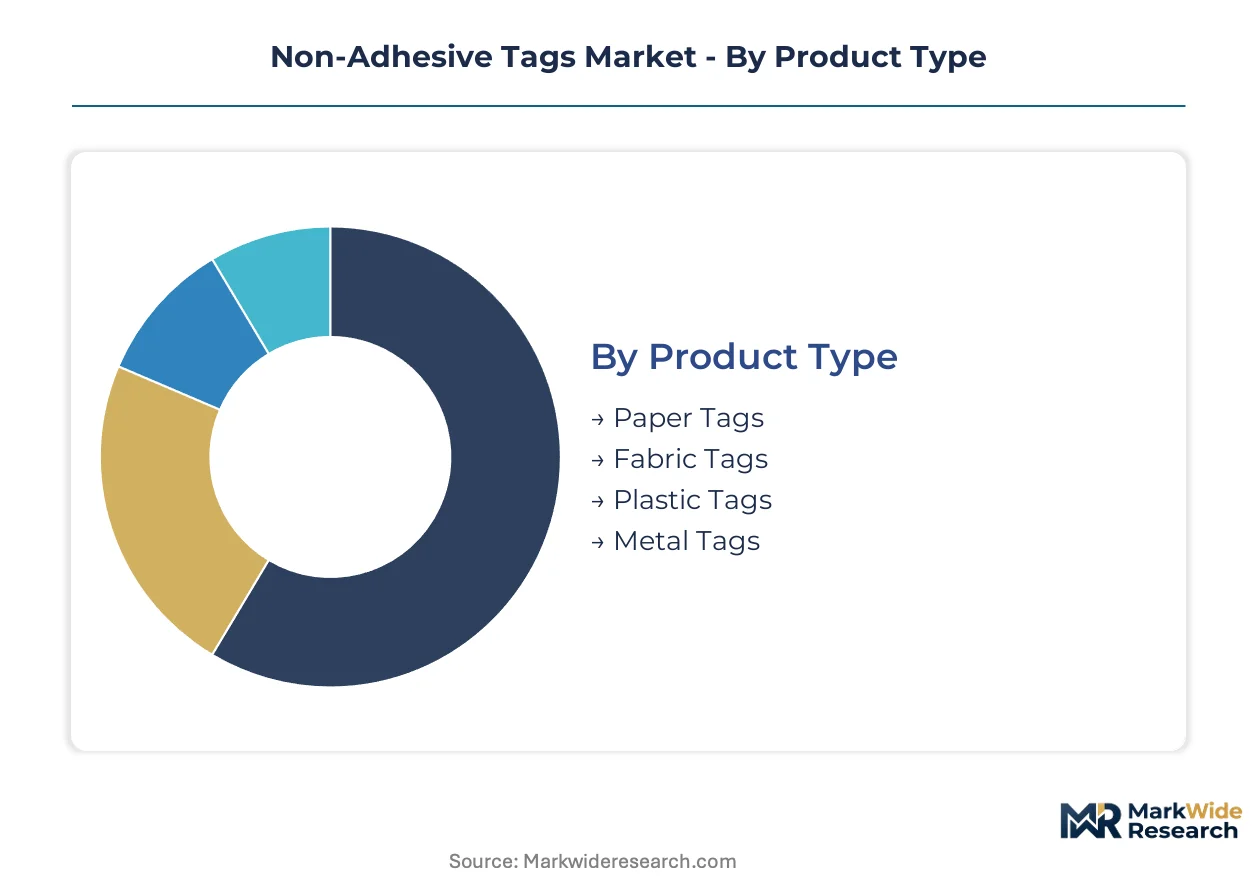
Non-adhesive tags serve divergent functional requirements across substrate durability, attachment mechanics, and data permanence. Segmentation reveals how material science investments and regulatory compliance reshape procurement patterns among converters and end-users.
Product Type:
Substrate selection hinges on environmental exposure, attachment method, and lifecycle duration rather than unit cost alone.
- Paper Tags:Coated kraft and synthetic paper stocks dominate fast-fashion pricing applications where single-use economics prevail. Demand concentrates in United States retail apparel where thin-gauge substrates reduce shipping cube and support sustainability claims under FTC Green Guides.
- Plastic Tags:Polypropylene and polyethylene formulations deliver moisture resistance for outdoor logistics and food processing environments. German automotive suppliers specify halogen-free grades to satisfy REACH substance restrictions ahead of enforcement milestones.
- Fabric Tags:Woven polyester and cotton substrates command premium positioning in apparel branding through soft-hand feel and sew-on compatibility.
- Metal Tags:Anodized aluminum and laser-markable stainless steel serve industrial asset tracking where chemical resistance and UV stability outweigh substrate cost.
Plastic tags lead on scale; metal tags lead on momentum as laser marking displaces thermal transfer in industrial applications.
Application:
Use-case segmentation tracks how tag function determines substrate specification and print permanence requirements.
- Pricing:Paper and thin-gauge plastic tags dominate retail price marking where rapid attachment and disposal economics govern selection. United States big-box retailers source high-volume contracts through digital procurement platforms that specify GS1 data syntax compliance.
- Branding:Fabric and premium plastic substrates carry logo embroidery, foil stamping, and tactile finishes that support brand equity. European luxury apparel houses specify OEKO-TEX certified fabrics to align with EU Green Deal circularity objectives.
- Inventory Management:RFID-enabled plastic and metal tags enable automated warehouse sortation and asset tracking. Logistics providers in Germany deploy EPC Gen2 inlays on polypropylene tags to meet automotive supply chain traceability mandates.
- Event Identification:Tyvek and synthetic paper wristbands serve access control and crowd management at festivals and conferences. Event organizers in France favor recyclable substrates to satisfy extended producer responsibility frameworks.
Inventory management applications are climbing the fastest as RFID convergence automates legacy barcode workflows.
End User:
Procurement sophistication varies sharply across customer types, from specification-heavy industrial buyers to cost-sensitive retail operators.
- Retailers:Apparel and general merchandise chains specify tag substrates through centralized sourcing functions that score sustainability certification. Fast-fashion retailers in Italy prioritize closed-loop paper fiber recovery to meet packaging waste directive obligations.
- Manufacturers:Automotive, pharmaceutical, and electronics producers mandate durable metal and synthetic tags for component-level traceability. German Tier 1 suppliers enforce ISO 15415 barcode quality validation across their converter networks.
- Logistics Providers:Third-party warehousing and parcel carriers drive RFID tag volume for automated sortation infrastructure. United States express carriers specify moisture-resistant plastic tags for cross-dock environments.
- Event Organizers:Sports venues and festival operators purchase disposable identification products through seasonal procurement cycles. Security-focused buyers specify tamper-evident closure mechanisms over substrate durability.
Manufacturers lead on specification complexity; logistics providers lead on volume expansion as automated handling networks proliferate.
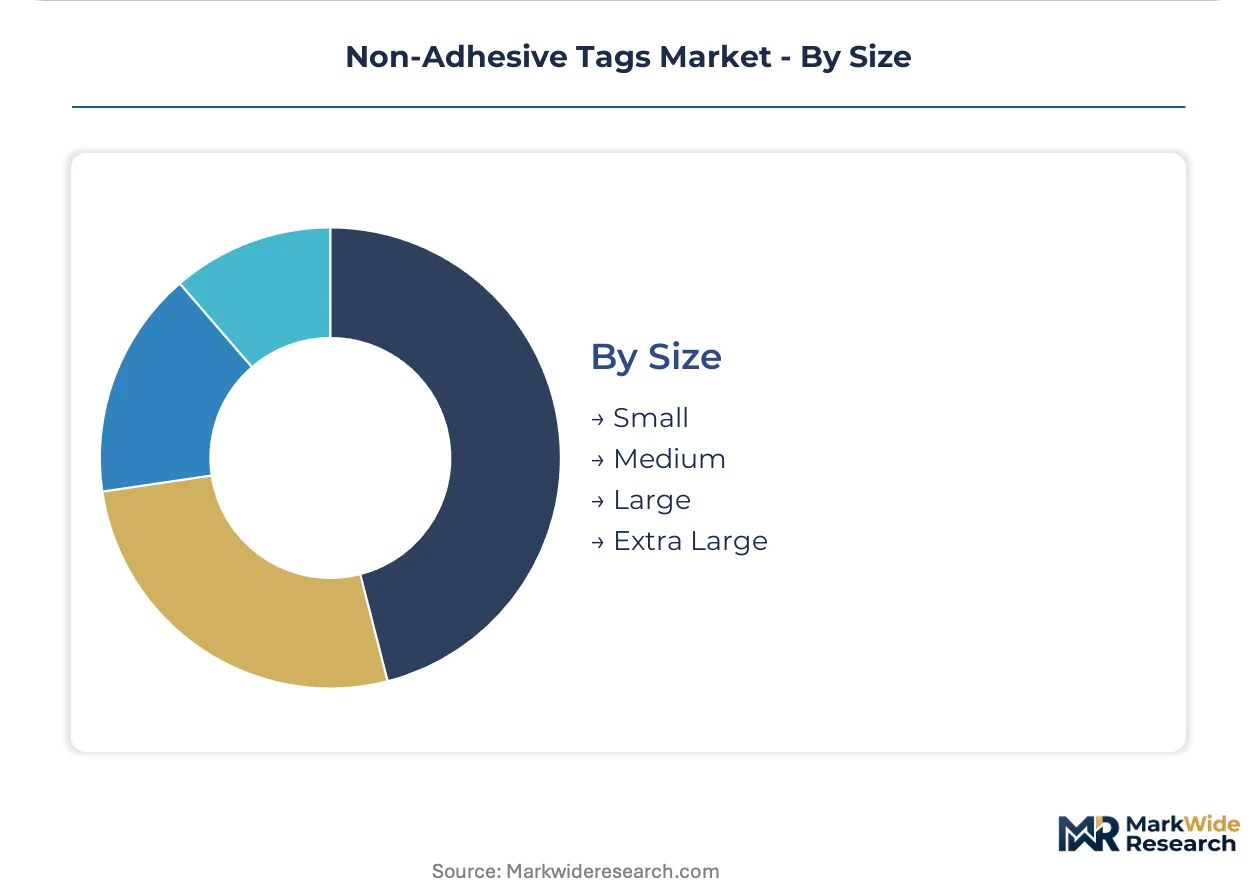
Size:
Dimensional segmentation governs printable area, attachment hardware compatibility, and shipping logistics rather than end-use function alone.
- Small:Compact formats suit jewelry, eyewear, and small electronics where display space constrains tag geometry. Pharmaceutical blister packs in India require CDSCO-compliant small-format tags for export traceability.
- Medium:Standard apparel and consumer goods dimensions balance information density with handling efficiency. This segment captures the broadest cross-section of retail and industrial applications.
- Large:Expanded printable area accommodates regulatory text, multi-language labeling, and bold barcode scanning zones. Agricultural equipment and industrial machinery tags specify large formats for outdoor readability.
- Extra Large:Oversized tags serve pallet-level identification, container marking, and facility signage where remote scanning distance matters. Logistics hubs in the United States deploy extra-large RFID tags for yard management automation.
Medium sizes lead on unit volume; extra-large formats are gaining share fastest as supply chain digitization extends beyond item-level tagging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive clusters anchor non-adhesive tag demand through Tier supplier traceability mandates. Logistics automation in the United States and pharmaceutical export compliance in India reshape procurement patterns across substrate categories.
United States
FDA traceability rules for food and pharmaceutical packaging drive laser-markable metal tag adoption. Logistics providers deploy RFID-enabled plastic tags for automated sortation at Memphis and Louisville air cargo hubs. Express carriers specify moisture-resistant substrates for cross-dock environments.
Germany
Automotive supply chain mandates from KBA and industrial labeling standards enforce durable metal and synthetic tags. REACH substance restrictions accelerate halogen-free polypropylene qualification ahead of enforcement milestones. Stuttgart and Wolfsburg clusters demand component-level tracking from Tier 3 suppliers through final assembly.
India
CDSCO traceability alignment with FDA and EMA standards creates demand for ISO 15415-compliant barcode permanence in bulk drug packaging. Pharmaceutical exporters in Hyderabad and Ahmedabad specify small-format tags for blister pack traceability. Domestic logistics modernization drives RFID adoption in warehouse automation.
China
GB standards for product traceability and MIIT smart logistics initiatives expand RFID tag deployment. Yangtze River Delta manufacturing clusters specify durable synthetic tags for electronics component tracking. E-commerce fulfillment centers drive volume for automated sortation infrastructure.
France
EU Green Deal packaging waste directives and extended producer responsibility frameworks favor recyclable paper and fabric substrates. Luxury apparel houses in Paris specify OEKO-TEX certified fabrics for brand equity alignment. Event organizers favor recyclable Tyvek wristbands for festival access control.
Non-Adhesive Tags Market Competitive Landscape
Global majors compete with regional champions across substrate technology and vertical specialization. The vendor base organizes around materials science depth, print finishing integration, and RFID inlay capabilities. Three archetypes dominate: diversified materials conglomerates with captive film extrusion, precision printing specialists with laser marking equipment, and auto-ID technology vendors with embedded RFID portfolios. Competitive moves concentrate on backward integration into substrate production and geographic expansion through distributor acquisition.
Within the diversified materials tier, CCL Industries Inc. and Avery Dennison Corporation exemplify scale-driven positioning through in-house production of films and adhesives. Brady Corporation occupies a specialist position in durable identification, representing the precision printing archetype with metal substrate focus. These three anchors demonstrate how competitive advantage derives from vertical control over substrate supply and qualification depth for regulated end-uses.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| CCL Industries Inc. |
| Zebra Technologies Corporation |
| Brady Corporation |
| UPM Raflatac |
| Sato Holdings Corporation |
| 3M |
| LINTEC Corporation |
| Mondi |
| Others |
Value Network & Pricing Analysis
Polypropylene resin indices on the US Gulf Coast cascade through substrate converters into three distinct pricing tiers, with coated paper grades absorbing pulp volatility fastest and laser-markable metal substrates commanding premiums through qualification depth.
Pricing Analysis
Input-cost pass-through from petrochemical corridors shapes contract negotiations between tag converters and brand owners. Pricing stratifies across premium laser-markable stainless steel, standard halogen-free polypropylene, and economy coated paper tiers based on certification grade and volume scale. Cost compression in paper substrates is intensifying because fast-fashion retailers squeeze single-use tag economics. Logistics providers prove least price-sensitive, prioritizing RFID durability over unit cost in automated sortation procurement.
Supply Chain Analysis
Freight cost spikes from Asia-Pacific manufacturing hubs to European automotive clusters are accelerating regional substrate production investments. Raw material supply concentrates in China for synthetic fabrics, Germany for specialty coated papers, and the United States for extruded polypropylene films. Converter networks draw from pulp mills in Scandinavia, petrochemical complexes on the Texas Gulf Coast, and anodizing facilities in the Yangtze River Delta. Single-source vulnerability in RFID inlay supply from Southeast Asian assembly plants poses structural risk. Distribution runs through converter-direct portals and industrial distributor networks serving tiered end-user segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH substance restrictions and FDA traceability mandates create sustained demand for qualified substrates.
For Market Incumbents: Cement backward integration into halogen-free polypropylene extrusion to defend against resin price volatility and emerging Asian substrate suppliers. Lock in multi-year qualification contracts with German automotive Tier 1 suppliers ahead of enforcement milestones. Prioritize ISO 15415 barcode validation equipment to maintain converter network exclusivity. For New Entrants and Emerging Players: RFID-inlay convergence with OEKO-TEX certified fabric substrates offers the most penetrable wedge into European luxury apparel supply chains. Target Indian pharmaceutical exporters in Hyderabad and Ahmedabad seeking CDSCO-compliant small-format tags for blister pack traceability. Pursue direct-to-retailer digital procurement platforms to bypass entrenched distributor markups. For Investors and Strategic Acquirers: Asymmetric upside sits with precision printing specialists possessing fiber laser marking equipment and existing automotive qualification depth. Long-term viability favors converters with closed-loop paper fiber recovery infrastructure aligned to EU Green Deal circularity mandates. Watch for RFID tag data integration mandates from major logistics carriers as the inflection signal for accelerated automation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Extrusion | CCL Industries and Avery Dennison anchor margin control through captive polypropylene film production. |
| RFID Inlay Qualification Investment | Logistics providers at Memphis and Louisville hubs demand EPC Gen2 durability for automated sortation. |
| Halogen-Free Formulation Certification | German automotive suppliers accelerate compliant polypropylene qualification ahead of REACH enforcement. |
| Laser Marking Equipment Deployment | Brady Corporation and precision specialists displace thermal transfer ribbon in industrial asset tracking. |
| Closed-Loop Fiber Recovery Partnership | Fast-fashion retailers in Italy award contracts based on packaging waste directive compliance scores. |
Research Methodology
Multiple input streams — converter production data, brand owner procurement specifications, and regulatory filing documentation — were reconciled across primary interviews with tag converter operations managers, automotive Tier 1 supplier procurement leads, logistics warehouse automation directors, pharmaceutical packaging compliance officers, and retail sustainability sourcing heads. Secondary validation drew from customs trade databases, SEC filings of publicly traded materials companies, ECHA substance restriction notifications, and GS1 standards documentation. Bottom-up substrate volume estimates and top-down end-use demand projections were triangulated to anchor market sizing.
Data-stream reconciliation across the projection horizon employed a segmented analytical framework modeling substrate type, attachment mechanism, print permanence requirement, end-use industry vertical, and regional regulatory cluster. CAGRs were derived from elasticity modeling against automotive production forecasts, pharmaceutical export volumes, and logistics automation capex cycles. Industry-specific inputs included RFID tag adoption curves in United States express carrier networks and REACH compliance timelines for halogenated compound restrictions.
The model holds under stable petrochemical feedstock pricing and sustained regulatory enforcement timelines; deviation in pulp futures volatility or delayed automotive traceability mandates would shift substrate mix assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Linerless Labels Market
Labels
Wash Off Labels Market
Labels
Tags Market
Labels
Stand Alone Label Applicator Market
Labels
Wet Glue Labeling Machines Market
Labels
United States Print Label Market
Labels
India Print Label Market
Labels
GCC Labeling Market
Labels
Self-Laminating Labels Market
Labels
Inventory Tags Market
Labels
Fiber Optic Labels Market
Labels
Europe Self Adhesives Label Market
Labels
Laser Markable Labels Market
Labels
Printable Tags Market
Labels
Industrial Label Printers Market
Labels
Glue-Applied Labels Market