
 Global Waterproof Labels Market | 2026-2036
Global Waterproof Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Waterproof Labels Market Foresight
Market Context
Project finance for coating and lamination lines is narrowing the competitive field to firms with balance-sheet capacity for capital-intensive barrier-film investments. CCL Industries leverages backward integration into resin compounding to control substrate quality across its label films division. Avery Dennison sustains technology leadership through R&D intensity focused on adhesive chemistry for extreme moisture environments. UPM Raflatac anchors its position via geographic dominance in European sustainable labelstock supply, competing against Tesa SE's specialized industrial tape-to-label crossover portfolio.
Technical Definition and Segment Structure
Waterproof labels are pressure-sensitive or adhesive-backed substrates engineered with polypropylene, polyester, or vinyl face stocks combined with moisture-blocking laminates and synthetic adhesives to maintain legibility, barcode scannability, and aesthetic integrity under immersion, condensation, or chemical exposure. These labels serve critical tracking, branding, and compliance functions across supply chains where paper-based alternatives degrade. Polyester face stocks command premium positioning in pharmaceutical and electronics applications where autoclave sterilization and solvent resistance justify higher unit economics. Digital printing technology is capturing share fastest among short-run, variable-data applications in cosmetics production and craft beverage bottling, while flexographic output still dominates volume in food & beverage and chemical processing due to speed and ink economics at scale.
Regulatory Framework and Outlook
FDA regulations on pharmaceutical labeling durability and the EU's F-Gas Regulation on fluorinated compound restrictions are reshaping adhesive and laminate formulation requirements across export-oriented converters. ECHA's REACH framework governs substance restrictions that filter through to labelstock chemistry, particularly for personal care and household item applications with skin-contact exposure risk. China's GB standards and NMPA labeling rules for drug traceability are raising substrate performance benchmarks in Asia-Pacific supply chains. Stakeholders must monitor evolving extended producer responsibility schemes in Europe and state-level packaging regulations in the United States to anticipate substrate specification shifts before they disrupt existing qualification pipelines.
Market Dynamics
Pharmaceutical serialization mandates across Germany, China, and the United States are forcing label converters to qualify durable synthetic substrates that survive cold-chain logistics, autoclave sterilization, and multi-year archival requirements without degradation.
Growth Catalysts
- Cold-chain logistics expansion:Food and beverage bottlers in Germany and the Netherlands are adopting synthetic paper labels for refrigerated and frozen supply chains where condensation destroys conventional paper stocks.
- REACH substance restrictions:ECHA's evolving framework on low-migration adhesives is pulling converters toward compliant formulations for skin-contact personal care applications.
- Digital printing adoption:Short-run variable-data production for craft beverages and cosmetics is accelerating equipment replacement cycles among mid-size converters.
Market Restraints
- Resin price volatility:Polypropylene and polyester face stock costs fluctuate with petrochemical feedstock indices, compressing converter margins during upstream spikes.
- Adhesive qualification timelines:FDA and EMA pharmaceutical labeling durability requirements demand 12-24 month validation cycles that freeze supplier switches.
- Fluorinated compound restrictions:The EU's F-Gas Regulation is eliminating certain moisture-barrier chemistries, forcing laminate reformulation investments.
Strategic Opportunities
- Indian pharmaceutical export growth:CDSCO traceability rules for drug packaging are creating demand for autoclave-resistant polyester labels among export-oriented manufacturers in Mumbai and Hyderabad.
- Extended producer responsibility schemes:EU packaging regulations are rewarding recyclable mono-material label constructions with preferential compliance pathways.
- UV-LED curing convergence:Integration of UV-LED inkjet with synthetic substrates is opening premium short-run applications in electronics and medical device labeling.
Industry Challenges
- Adhesive chemist scarcity:Formulation expertise for low-migration, extreme-moisture environments concentrates among senior technologists at a handful of European and North American compounders.
- Coating line capex requirements:Barrier-film lamination capacity demands project finance thresholds that exclude smaller converters from pharmaceutical qualification pipelines.
- Multi-jurisdiction compliance stacking:Simultaneous FDA, REACH, and NMPA submissions strain regulatory affairs teams at mid-size labelstock producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Waterproof Labels Market |
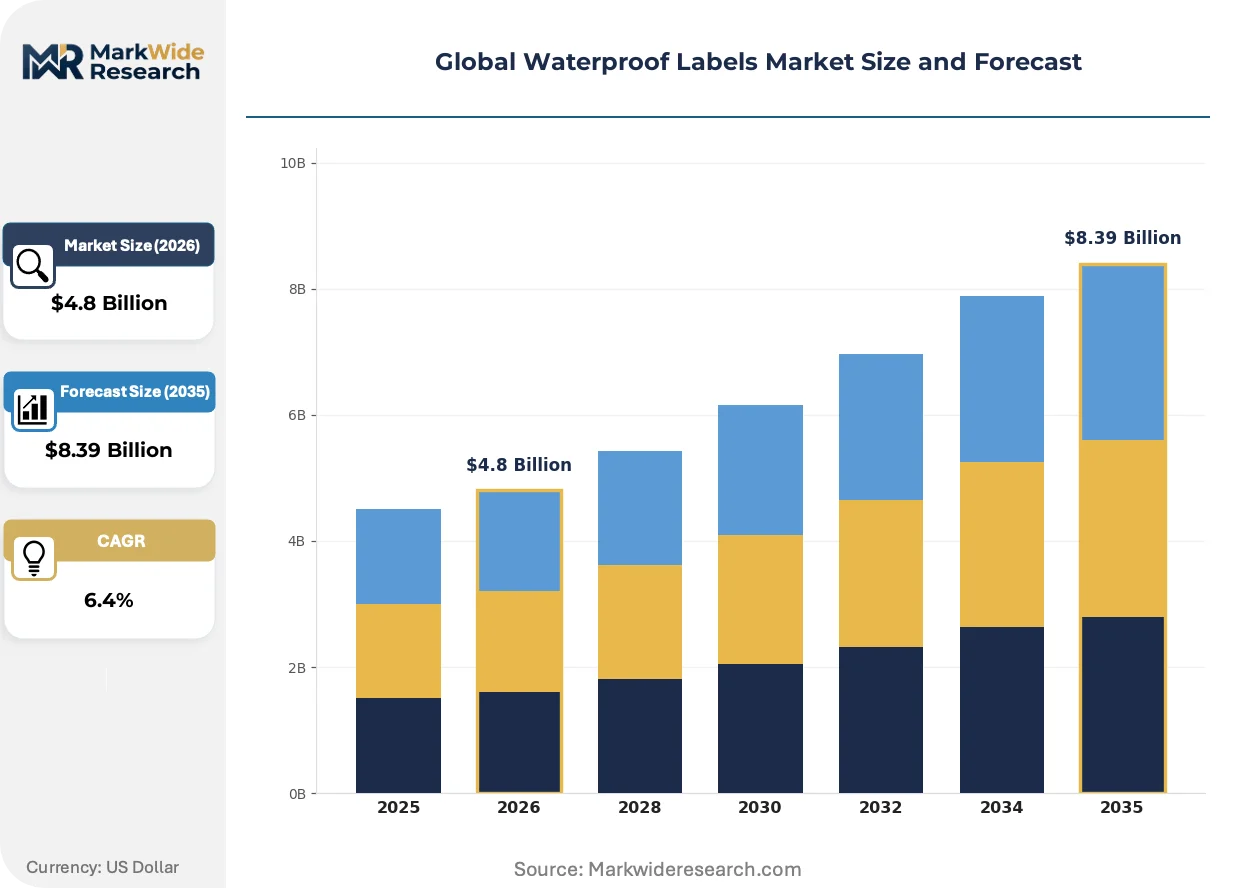
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, Polyester, Vinyl, Synthetic Paper, Polyethylene, BOPP Application: Food & Beverage, Personal Care Products, Pharmaceuticals, Chemical Products, Electronics, Household Items Printing Technology: Flexographic, Digital, Offset, Screen, Thermal Transfer, Gravure End User Industry: Consumer Goods, Pharmaceuticals Manufacturing, Electronics Assembly, Chemical Processing, Cosmetics Production, Beverage Bottling |
| Companies Covered | Avery Dennison, CCL Industries, UPM Raflatac, 3M, Lintec Corporation, Tesa SE, Brady Corporation, Fuji Seal, Herma GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Waterproof Labels Market Shifts & Advancements
Label production technology is bifurcating between high-speed flexographic volume lines for food and chemical processing and agile digital systems serving variable-data cosmetics and beverage applications.
Water-based UV-LED curable inks formulated for synthetic polypropylene and polyester face stocks are rendering obsolete solvent-based flexographic systems in short-run pharmaceutical and electronics labeling. Mid-size converters in Germany and Switzerland are retrofitting hybrid presses to capture craft beverage and medical device contracts. The technology is compressing make-ready times from hours to minutes while eliminating volatile organic compound emissions.
The EU's F-Gas Regulation on fluorinated greenhouse gases is eliminating perfluorinated moisture barriers from laminate formulations. Converters are qualifying silicone-based and bio-derived barrier coatings for personal care and household chemical applications. Pharmaceutical labelstock suppliers in Germany and France face the steepest reformulation deadlines due to parallel EMA durability requirements.
Direct-to-brand procurement is consolidating converter relationships among multinational food and beverage bottlers. Procurement teams in the United States and Germany are reducing qualified supplier lists from dozens to single-digit panels with dedicated capacity allocations. The shift is most visible in carbonated soft drink and craft beer segments where traceability and brand consistency requirements have intensified.
Global Waterproof Labels Market Segmentation
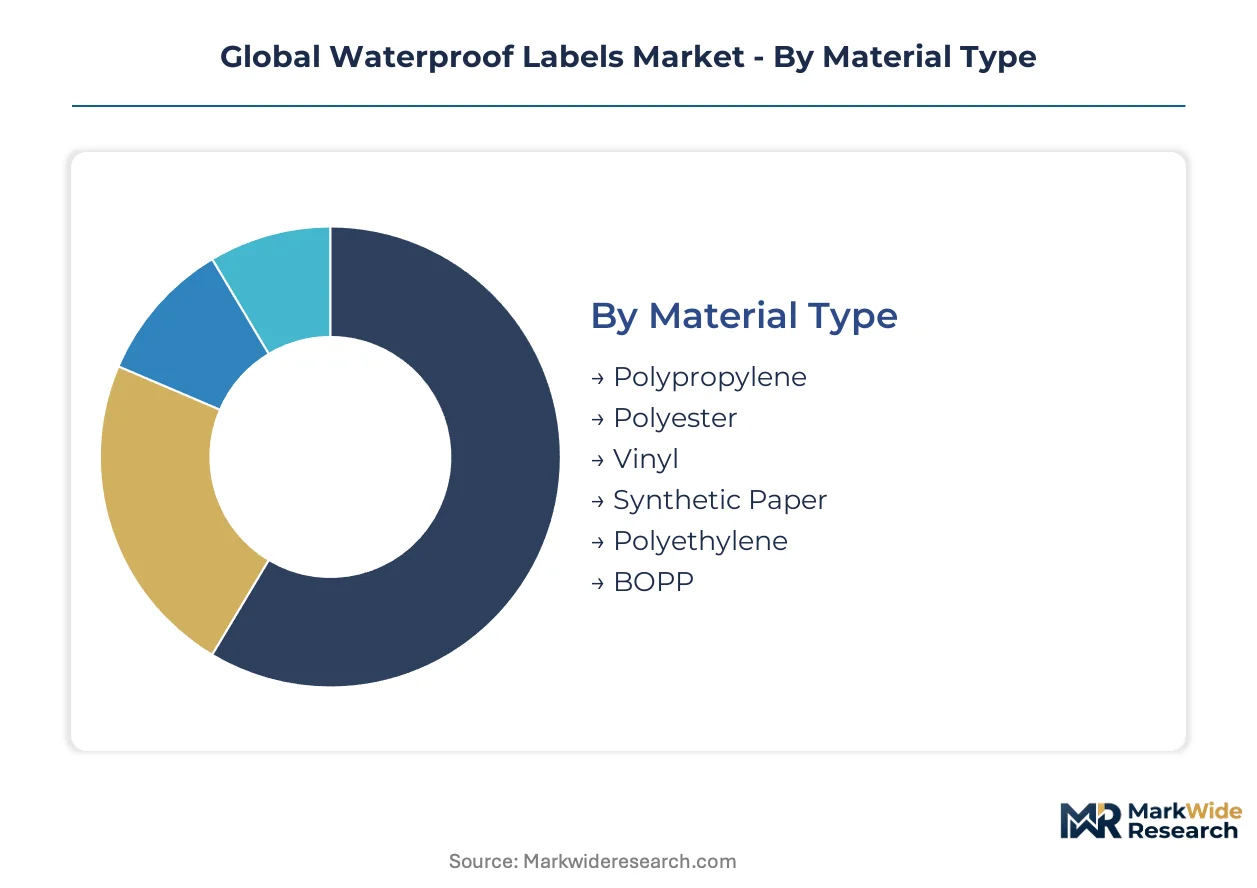
Waterproof label specifications diverge sharply across material chemistry, application environment, and production economics. Each segmentation dimension carries distinct qualification barriers and margin structures that shape converter strategy.
Material Type:
Cost tier determines substrate selection trade-offs between barrier performance and unit economics.
- Polypropylene:Biaxially oriented polypropylene delivers moisture resistance at mid-range cost, dominating food and beverage applications where condensation tolerance meets budget constraints. German beverage bottlers specify BOPP for refrigerated supply chains.
- Polyester:PET face stocks withstand autoclave sterilization and solvent exposure, commanding premium positioning in pharmaceutical serialization where EMA durability mandates apply. Demand concentrates among Mumbai and Hyderabad export manufacturers facing CDSCO traceability rules.
- Vinyl:PVC-based substrates offer chemical resistance for industrial labeling.
- Synthetic Paper:Polyolefin-based sheets bridge paper-like printability with moisture immunity.
- Polyethylene:Lower stiffness suits squeezable personal care containers.
- BOPP:Specialized orientation variants target high-clarity cosmetics applications.
Polyester holds installed capacity for pharmaceutical qualification pipelines. Synthetic paper is rotating up the share rankings among craft beverage bottlers.
Application:
End-use environment dictates laminate specifications and adhesive migration limits.
- Food & Beverage:Cold-chain logistics demand synthetic substrates that survive condensation, freezing cycles, and refrigerated transport. Dutch and German bottlers lead adoption of polypropylene labels with silicone-based moisture barriers.
- Pharmaceuticals:Serialization mandates across Germany, China, and the United States require polyester face stocks with archival-grade adhesives. NMPA traceability rules in China and FDA durability standards impose 12-24 month validation timelines.
- Personal Care Products:Skin-contact applications face REACH low-migration adhesive requirements.
- Chemical Products:Solvent-resistant vinyl dominates drum and container labeling.
- Electronics:UV-LED curable inks on polyester serve short-run device identification.
- Household Items:Cost-driven polyethylene labels suit detergent and cleaner bottles.
Food & Beverage anchors volume demand. Pharmaceuticals is climbing the fastest on regulatory compulsion.
Printing Technology:
Production volume and run length determine technology selection economics.
- Flexographic:High-speed rotary printing dominates food, beverage, and chemical label volumes where ink cost efficiency at scale outweighs make-ready time. German converters maintain installed base for multinational bottler contracts.
- Digital:Inkjet and toner systems capture variable-data cosmetics and craft beverage applications where short runs and rapid changeovers justify higher per-label cost. Mid-size German and Swiss converters retrofit hybrid presses for medical device contracts.
- Offset:Sheet-fed lithography persists in premium cosmetics cartons.
- Screen:Thick-film deposition suits industrial safety labels.
- Thermal Transfer:On-demand printing serves logistics and warehousing applications.
- Gravure:Long-run publication and decorative labels retain niche use.
Flexographic holds installed capacity for commodity volume. Digital is rotating up the share rankings on UV-LED curing convergence.
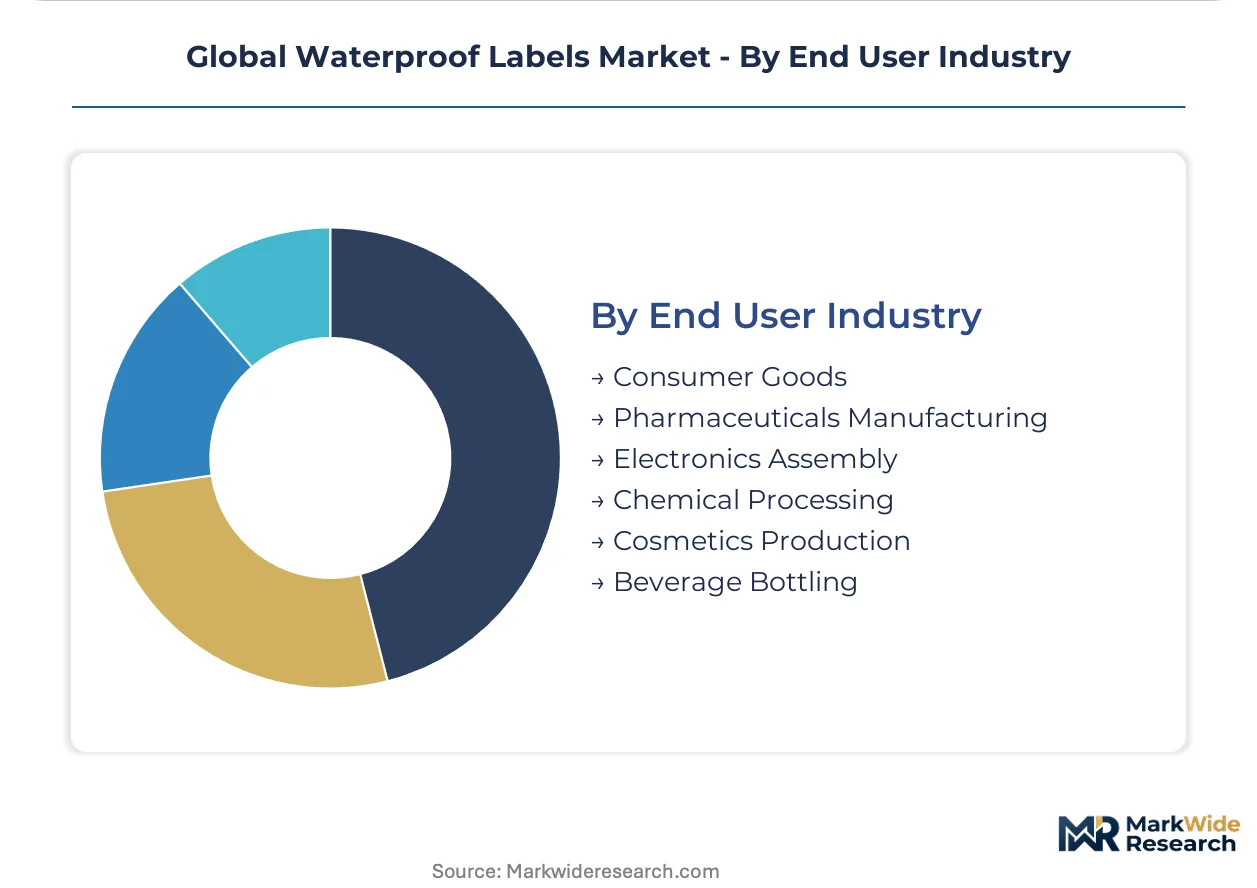
End User Industry:
Customer procurement concentration shapes converter relationship structures.
- Pharmaceuticals Manufacturing:Serialization mandates and multi-jurisdiction compliance stack qualification barriers. German and Indian export manufacturers specify autoclave-resistant polyester with EMA, FDA, and CDSCO submissions.
- Beverage Bottling:Direct-to-brand procurement consolidation reduces qualified supplier panels to single-digit rosters with dedicated capacity. US and German carbonated soft drink and craft beer segments drive synthetic paper adoption.
- Consumer Goods:Mass-market pricing pressures favor polypropylene economies.
- Electronics Assembly:Short-run, high-mix production suits digital printing.
- Chemical Processing:Bulk drum labeling demands solvent-resistant vinyl.
- Cosmetics Production:Premium positioning supports specialty substrate premiums.
Pharmaceuticals Manufacturing holds installed capacity for barrier-film investments. Beverage Bottling is rotating up the share rankings on direct procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical serialization mandates and cold-chain logistics expansion concentrate buyer demand among German pharmaceutical exporters, US beverage bottlers, and Indian drug manufacturers facing traceability compliance deadlines.
Germany
EMA durability requirements for pharmaceutical labeling drive polyester labelstock demand among export-oriented drug manufacturers. REACH low-migration adhesive rules filter through to personal care applications with skin-contact exposure. The Rhine-Main cluster around Frankfurt anchors converter capacity serving multinational pharmaceutical serialization contracts.
United States
FDA pharmaceutical labeling durability standards and beverage bottler direct procurement consolidation shape synthetic substrate specifications. State-level packaging regulations in California and New York anticipate extended producer responsibility schemes. Midwest converter networks around Chicago supply carbonated soft drink labels with dedicated capacity allocations to reduced supplier panels.
China
NMPA drug traceability rules elevate substrate performance benchmarks for domestic and export pharmaceutical packaging. GB standards govern label durability requirements across personal care and household chemical segments. The Yangtze River Delta manufacturing corridor concentrates converter investments serving both domestic consumption and export qualification pipelines.
India
CDSCO serialization mandates for pharmaceutical exports create demand for autoclave-resistant polyester labels among Mumbai and Hyderabad manufacturers. DGFT traceability requirements align with EU and US regulatory submissions for generic drug exporters. The Mumbai-Pune pharmaceutical belt drives converter qualification timelines for barrier-film labelstock.
Netherlands
Food and beverage cold-chain logistics adoption spreads synthetic paper labels for refrigerated transport and condensation-prone environments. ECHA REACH compliance requirements influence adhesive formulation selections for European export markets. The Rotterdam-Antwerp logistics corridor concentrates label demand from multinational bottlers with integrated European distribution networks.
Global Waterproof Labels Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Consolidated multinational converters with captive resin compounding and coating line capacity dominate pharmaceutical qualification pipelines. Mid-size regional specialists capture craft beverage and cosmetics variable-data contracts through digital press flexibility. Technology licensors and adhesive compounders supply formulation expertise to converters lacking in-house chemistry capabilities. Competitive moves center on barrier-film lamination capacity expansion and strategic partnerships for multi-jurisdiction regulatory submission support.
Among North American-based material science conglomerates, Avery Dennison exemplifies technology leadership through adhesive chemistry specialization for extreme moisture environments. CCL Industries anchors the integrated converter tier through backward integration into resin compounding that controls substrate quality across label films divisions. UPM Raflatac occupies a position within the European sustainable labelstock supply tier, competing against Tesa SE's industrial tape-to-label crossover portfolio.
| Leading Market Players |
|---|
| Avery Dennison |
| CCL Industries |
| UPM Raflatac |
| 3M |
| Lintec Corporation |
| Tesa SE |
| Brady Corporation |
| Fuji Seal |
| Herma GmbH |
| Others |
Supply & Pricing Matrix
The Rhine-Main cluster around Frankfurt concentrates barrier-film lamination capacity, granting German converters pricing leverage over pharmaceutical qualification pipelines where EMA durability mandates enforce 12-24 month validation timelines. Cost compression in standard-grade polypropylene labels intensifies as Asian resin compounders expand BOPP output for food and beverage bottlers.
Pricing Analysis
Certification level (FDA-grade, EMA-grade, CE-marked) creates the primary spread between premium polyester pharmaceutical stock and economy polypropylene beverage labels. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and consumer-grade tiers stratifies by adhesive migration limits and laminate barrier performance. Pricing pressure stems from resin price volatility tied to petrochemical feedstock indices, squeezing converter margins during upstream spikes. Beverage bottlers exhibit highest price sensitivity through consolidated direct procurement panels, while pharmaceutical manufacturers accept premium positioning for autoclave-resistant serialization substrates.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities anchor working capital structures between German resin compounders and mid-size European converters. Raw material supply concentrates in Germany, China, and South Korea for biaxially oriented polypropylene and polyester face stocks, drawing from petrochemical feedstock and specialty adhesive chemistries. Single-source vulnerability concentrates in fluorinated barrier coating formulations facing EU F-Gas Regulation phaseouts. Distribution runs through converter-direct relationships with multinational pharmaceutical and beverage bottlers, bypassing traditional distributor tiers for qualified supplier panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across regulatory jurisdictions and application-specific qualification requirements creates specialist niches for targeted entrants. Digital printing adoption for short-run variable-data cosmetics and craft beverage labels accelerates equipment replacement demand among mid-size converters lacking hybrid press capacity.
For Market Incumbents: Harden barrier-film lamination capacity positions through captive resin compounding investments in the Rhine-Main cluster, defending against Asian BOPP compounders expanding into European pharmaceutical qualification pipelines. Prioritize low-migration adhesive R&D to maintain EMA and FDA submission leadership as REACH substance restrictions tighten skin-contact application requirements.
For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical export manufacturing serving Mumbai and Hyderabad generic drug producers facing CDSCO serialization deadlines. Target UV-LED curable inkjet retrofit services for German and Swiss mid-size converters seeking medical device contract diversification without greenfield press investments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors adhesive chemistry specialists with formulation expertise for extreme moisture environments and multi-jurisdiction regulatory submission capabilities. Long-term viability hinges on qualification pipeline depth rather than commodity volume scale. Watch for EU F-Gas Regulation enforcement acceleration as inflection indicator for silicone-based barrier coating adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | CCL Industries controls substrate quality across pharmaceutical qualification pipelines through captive polypropylene and polyester supply. |
| UV-LED Curing Technology Adoption | Mid-size German and Swiss converters compress make-ready times from hours to minutes while eliminating volatile organic compound emissions. |
| Low-Migration Adhesive Formulation Investment | REACH compliance for skin-contact personal care applications filters through to labelstock chemistry requirements. |
| Direct-to-Brand Procurement Consolidation | US and German beverage bottlers reduce qualified supplier panels from dozens to single-digit rosters with dedicated capacity allocations. |
| Silicone-Based Barrier Coating Qualification | EU F-Gas Regulation phaseout of perfluorinated moisture barriers forces laminate reformulation investments among pharmaceutical labelstock suppliers. |
Research Methodology
Operator-level perspectives from coating line managers, adhesive formulation chemists, pharmaceutical regulatory affairs leads, beverage bottler procurement directors, and label converter plant engineers anchored the qualitative base. Primary interview insights triangulated against secondary sources including ECHA REACH substance restriction databases, FDA pharmaceutical labeling durability guidance, CDSCO traceability rule filings, customs trade data for polypropylene and polyester imports, and SEC 10-K disclosures from listed material science conglomerates. Bottom-up demand modeling across application segments and end-use industries converged with top-down market sizing from resin consumption and printing press installation data.
Scenario-bracketing around resin price volatility, regulatory enforcement intensity, and digital printing adoption pace shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry tier, application environment, printing technology, and end-user industry procurement concentration. CAGRs derived from elasticity-adjusted volume projections incorporating converter capacity utilization rates and qualification pipeline backlogs. Industry-specific inputs encompassed pharmaceutical serialization mandate implementation timelines and cold-chain logistics expansion trajectories in European beverage distribution networks.
Sensitivities concentrate around EU F-Gas Regulation enforcement acceleration, petrochemical feedstock price spikes, and multi-jurisdiction compliance stacking delays at mid-size labelstock producers. Forecasts reflect documented assumptions regarding regulatory adherence timelines and technology substitution elasticities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Security Labels Market
Labels
Global Automotive Labels Market
Labels
India Print Label Market
Labels
Global Laminated Labels Market
Labels
Healthcare and Laboratory Labels Market
Labels
Die Cut Labels Market
Labels
Sustainable Labels Market
Labels
Canning Labels Market
Labels
Stretch Sleeve Labels Market
Labels
Pressure Sensitive Labels Market
Labels
Glue-Applied Labels Market
Labels
Metallic Labels Market
Labels
Foil Labels Market
Labels
Sheeted Labels Market
Labels
Pre-Gummed Labels Market
Labels
Coated Wet Glue Label Market