
 Global Pressure Labels Market | 2026-2036
Global Pressure Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pressure Labels Market Outlook
Asset-light leasing models for coating and converting equipment is fragmenting competitive dynamics among mid-tier converters. Avery Dennison Corporation leverages its captive film supply to sustain margin control across premium substrates. CCL Industries Inc. anchors North American healthcare labeling through specialized cleanroom manufacturing. 3M Company competes on adhesive chemistry leadership for extreme-temperature applications.
Pressure labels are substrate-adhesive constructions applied without heat or solvent activation, typically incorporating facestocks from 50 to 100 micrometers with permanent or removable acrylic, rubber, or silicone adhesives. Their primary function is to convey variable information, branding, and regulatory data across automated high-speed packaging lines. Paper-based facestocks dominate volume in retail and logistics, while polyester and polypropylene substrates capture margin pools in electronics and healthcare where chemical resistance and dimensional stability are critical. Tamper-evident constructions are gaining structural importance in pharmaceutical distribution as serialization mandates expand.
FDA enforces label adhesion and legibility standards for pharmaceutical and medical device applications, directly shaping material selection and validation protocols. REACH restricts adhesive monomers and film plasticizers in European supply chains, forcing reformulation investments. China's GB standards and SAMR labeling rules govern domestic product compliance, creating divergent testing requirements for multinational suppliers. Stakeholders must monitor regulatory divergence between major economies as it increasingly determines regional sourcing strategies and capital allocation priorities.
Market Dynamics
Smart labeling mandates for pharmaceutical traceability and EU Packaging and Packaging Waste Regulation compliance are forcing converters to restructure substrate sourcing and validation workflows.
Growth Catalysts
- E-commerce fulfillment automation:China domestic logistics infrastructure expansion is pulling demand for high-speed applicator-compatible labels.
- REACH chemical restrictions:European adhesive reformulation requirements are accelerating migration to bio-based acrylic systems.
- Food traceability mandates:Smart labeling integration with blockchain verification is penetrating premium retail packaging.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyester resin prices fluctuate with crude oil benchmarks, compressing converter margins.
- Adhesive monomer supply concentration:Specialty acrylic ester production clusters in Germany and Japan create geographic vulnerability.
- Paper substrate substitution ceiling:Moisture sensitivity limits paper facestock penetration in chilled food and beverage applications.
Strategic Opportunities
- India pharmaceutical serialization:CDSCO track-and-trace deadlines are opening cleanroom label demand in an underpenetrated market.
- RFID-NFC convergence:Passive inlay integration with pressure-sensitive constructions enables item-level authentication for luxury goods.
- Digital print-on-demand:Short-run variable data production is collapsing minimum order quantities for regional brand launches.
Industry Challenges
- Cleanroom certification timelines:ISO 14644 compliance validation for healthcare label production extends facility qualification by 12-18 months.
- Legacy ERP integration:Serialization data management systems require custom middleware development for mid-tier converters.
- Adhesive chemist talent scarcity:Formulation expertise for extreme-temperature silicone systems concentrates among retiring specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pressure Labels Market |
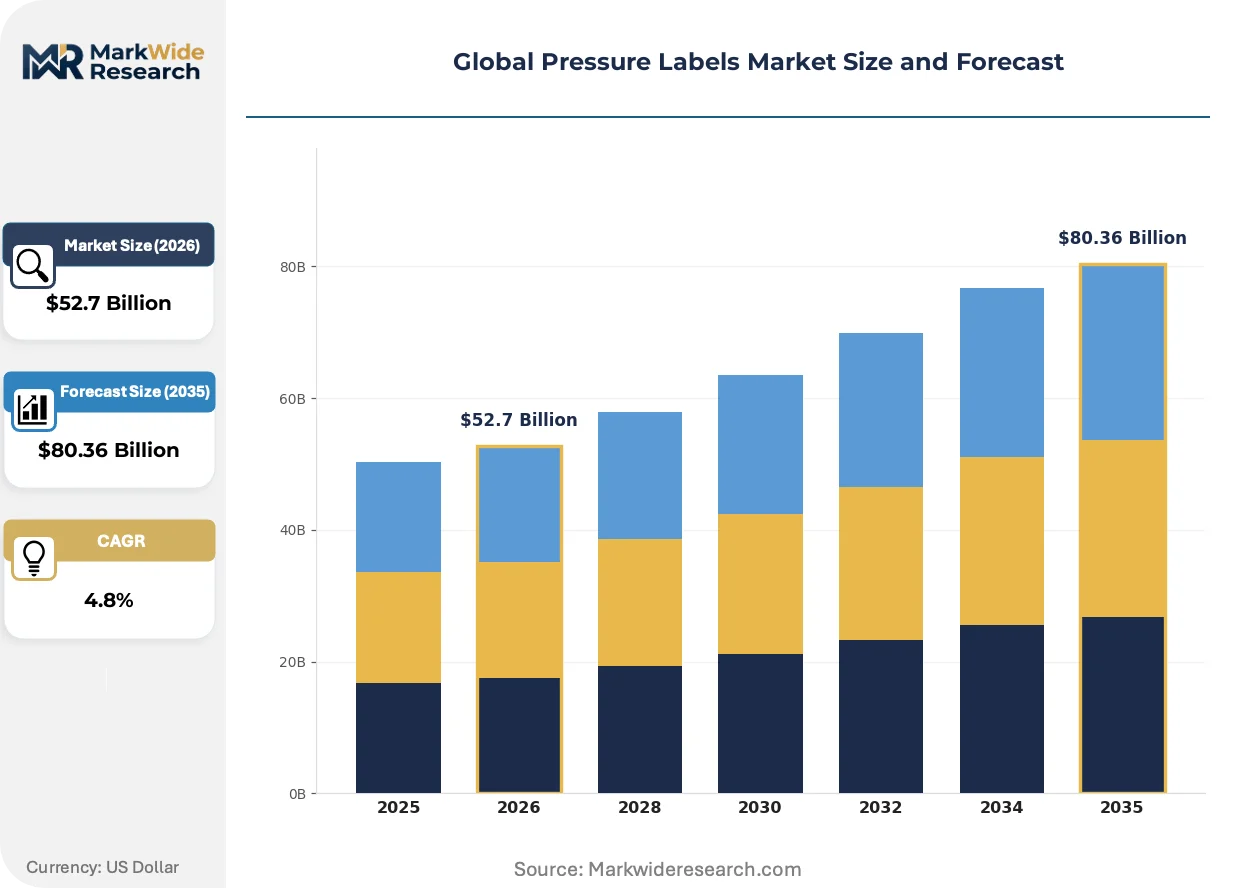
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive, Heat-Sensitive, Waterproof, Tamper-Evident Material: Vinyl, Paper, Polypropylene, Polyester End User: Food & Beverage, Healthcare, Electronics, Retail Application: Packaging, Inventory Management, Shipping Labels, Asset Tracking |
| Companies Covered | Avery Dennison Corporation, CCL Industries Inc., 3M Company, Multi-Color Corporation, UPM Raflatac, LINTEC Corporation, Constantia Flexibles, Huhtamäki Oyj, Fuji Seal International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pressure Labels Market Strategic Shifts
Digital printing convergence with intelligent substrate development is collapsing traditional volume thresholds and enabling mass customization at unit economics previously reserved for commodity production.
Laser die-cutting technology is collapsing mechanical tooling requirements for complex label geometries. Pharmaceutical and medical device manufacturers are adopting this for serialization-ready formats. The elimination of hard-tool lead times is compressing product development cycles from weeks to days.
EU Packaging and Packaging Waste Regulation recyclability mandates are forcing adhesive and release liner redesign. Converters must validate compatibility with paper-stream recycling infrastructure. Healthcare and food contact applications face the steepest reformulation timelines due to dual safety and circularity requirements.
Brand procurement teams are consolidating label suppliers to capture volume leverage and simplify ESG reporting. This supplier base reduction is displacing fragmented regional converter relationships. The concentration is most visible in European FMCG and North American beverage verticals where sustainability scorecarding dominates vendor selection.
Global Pressure Labels Market Segmentation
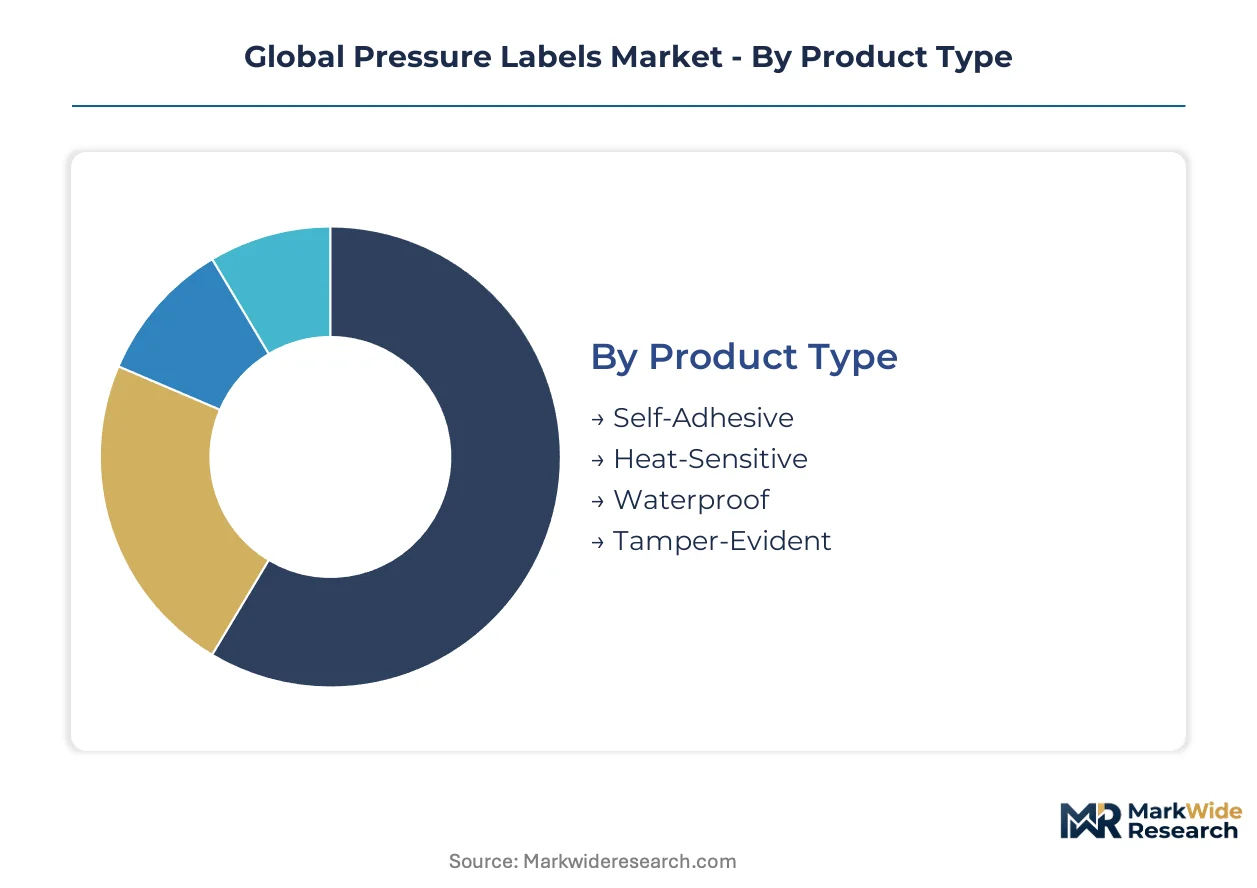
Segmentation in pressure labels determines converter capital allocation, adhesive chemistry investments, and regulatory compliance pathways. Material selection and end-use specifications create divergent margin profiles that shape competitive positioning across the value chain.
Product Type:
Mature constructions dominate volume throughput while emerging formats capture specification-driven premiums in regulated verticals.
- Self-Adhesive:Acrylic or rubber-based adhesive coatings on facestock substrates enable pressure-only application without thermal or solvent activation. Food and beverage packaging lines in China pull the majority of global volume as domestic e-commerce fulfillment infrastructure scales.
- Heat-Sensitive:Thermal transfer or direct thermal coatings react to printhead energy to produce variable data images without ink ribbons. Healthcare specimen labeling and logistics tracking in Germany concentrate demand as ECHA REACH compliance forces adhesive reformulation investments.
- Waterproof:Synthetic facestocks with moisture-barrier adhesives maintain adhesion and legibility under saturated conditions. Marine equipment and chilled beverage applications specify these constructions.
- Tamper-Evident:Frangible films or destructible adhesives reveal removal attempts through visible damage patterns. Pharmaceutical distribution serialization mandates in India and the EU drive specification growth.
Self-Adhesive handles the majority of throughput; Tamper-Evident is expanding most quickly on share as pharmaceutical traceability mandates proliferate.
Material:
Cost tier separation between commodity substrates and performance-engineered films determines converter equipment configuration and customer targeting.
- Vinyl:Polyvinyl chloride facestocks offer conformability to curved surfaces and outdoor durability against UV degradation. Automotive aftermarket and industrial equipment labeling in the US specify vinyl for weathering resistance.
- Paper:Uncoated or coated cellulose facestocks from 60 to 100 gsm provide print receptivity and cost efficiency for high-volume applications. Retail shelf labels and logistics barcodes consume the largest share of paper substrate output.
- Polypropylene:Biaxially oriented polypropylene films deliver chemical resistance and dimensional stability at lower cost than polyester. Electronics and household chemical labeling favor this substrate for moisture and solvent resistance.
- Polyester:Polyethylene terephthalate films provide maximum tensile strength, temperature tolerance, and optical clarity. Medical device identification and harsh-environment industrial tracking command polyester specifications despite premium pricing.
Paper commands the greatest volume throughput; Polyester is gaining share fastest as healthcare and electronics specifications tighten.
End User:
Application requirements across customer verticals create distinct adhesive performance specifications and validation protocols.
- Food & Beverage:Labels must withstand moisture, temperature cycling, and migration limits for indirect food contact. FDA and EU EFSA compliance frameworks govern adhesive selection for primary packaging.
- Healthcare:Sterilization resistance, biocompatibility testing, and cleanroom production standards define this segment. CDSCO track-and-trace deadlines in India are opening cleanroom label demand in an underpenetrated market.
- Electronics:Static-dissipative adhesives and ultra-thin profiles accommodate miniaturized component identification. Polypropylene and polyester substrates dominate for chemical resistance and dimensional stability.
- Retail:Promotional variable data and shelf-edge pricing demand short-run digital print compatibility. RFID-NFC convergence enables item-level authentication for luxury goods.
Food & Beverage anchors volume throughput; Healthcare is climbing the fastest as serialization mandates expand across pharmaceutical supply chains.
Application:
Functional use case determines label durability requirements, information density, and integration with automated systems.
- Packaging:Primary and secondary container decoration combined with regulatory information display. Smart labeling integration with blockchain verification is penetrating premium retail packaging.
- Inventory Management:Cycle counting, warehouse location marking, and stock rotation tracking. Barcode and RFID formats enable ERP system integration.
- Shipping Labels:Variable address data, routing codes, and handling instructions for parcel distribution. China domestic logistics infrastructure expansion pulls demand for high-speed applicator-compatible constructions.
- Asset Tracking:Fixed asset identification, maintenance scheduling, and lifecycle management. Laser die-cutting technology compresses product development cycles from weeks to days for serialization-ready formats.
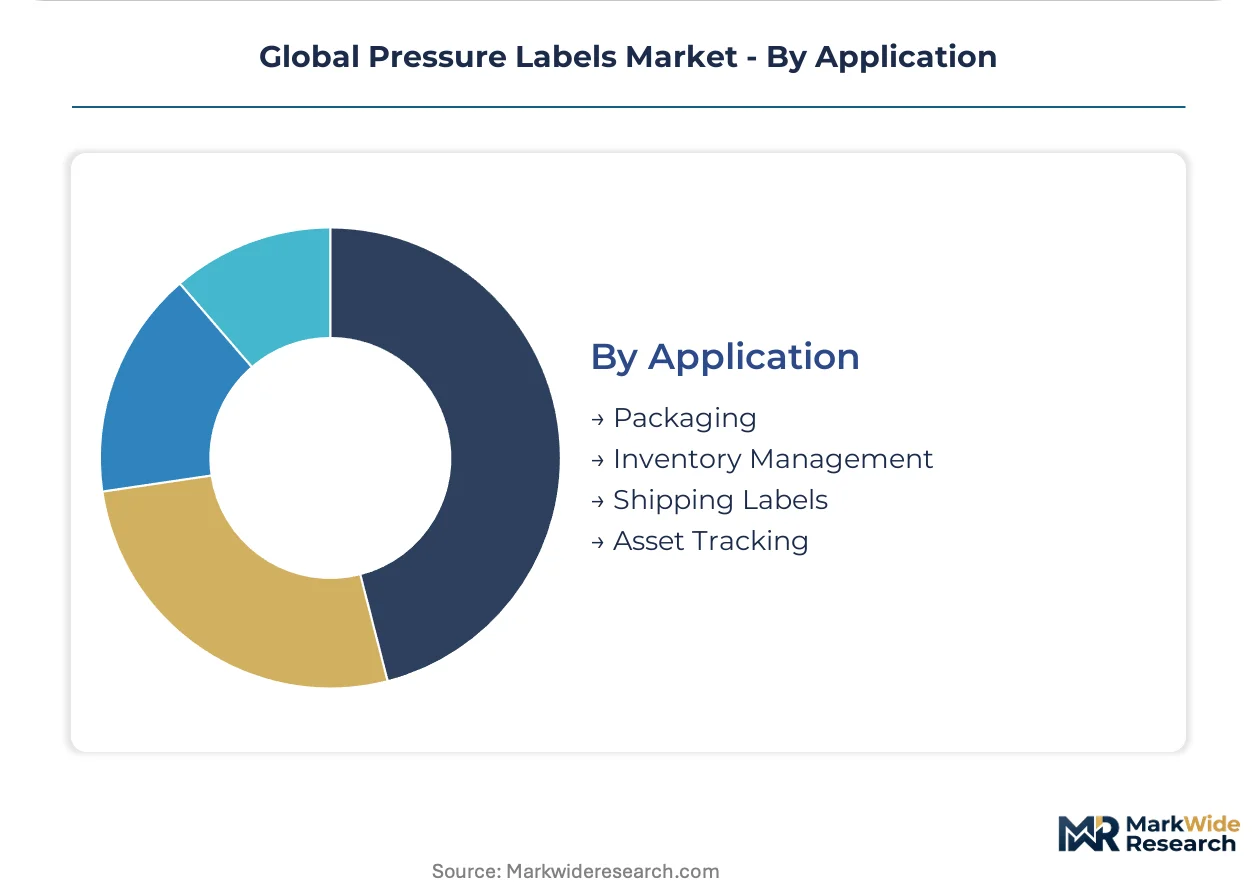
Packaging handles the majority of throughput; Asset Tracking is advancing fastest as enterprise digitization extends to physical equipment monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical serialization mandates and e-commerce fulfillment automation concentrate demand among healthcare procurement teams in Germany, logistics operators in China, and food safety regulators across multiple jurisdictions.
United States
FDA label adhesion standards for pharmaceutical and medical device applications drive material validation investments. The agency enforces legibility requirements that shape substrate selection protocols. Chicago and Minneapolis host specialized cleanroom manufacturing clusters serving North American healthcare labeling demand.
Germany
ECHA REACH restrictions on adhesive monomers and film plasticizers force reformulation investments across European supply chains. EMA pharmaceutical serialization mandates accelerate tamper-evident label specifications. The Rhine-Ruhr industrial corridor concentrates converter capacity for extreme-temperature adhesive chemistry.
China
Domestic e-commerce fulfillment infrastructure expansion pulls demand for high-speed applicator-compatible constructions. SAMR labeling rules and GB standards govern product compliance for multinational suppliers. The Yangtze River Delta hosts the largest concentration of coating and converting equipment serving Asia-Pacific volume requirements.
India
CDSCO track-and-trace deadlines for pharmaceutical serialization open cleanroom label demand in an underpenetrated market. FSSAI food contact compliance frameworks govern adhesive selection for primary packaging. Maharashtra and Gujarat industrial corridors attract converter investments targeting domestic and export healthcare specifications.
Japan
PMDA pharmaceutical labeling requirements and METI industrial standards shape material selection for precision electronics applications. JIS standards govern dimensional stability specifications for miniaturized component identification. The Kansai region maintains specialized capacity for silicone adhesive systems serving automotive and electronics verticals.
Global Pressure Labels Market Competitive Environment
Channel-controlling players compete with product-specialist players across substrate technology, adhesive chemistry, and cleanroom certification tiers. The vendor base separates into film-integrated manufacturers, standalone converters, and equipment-leasing operators. Three archetypes dominate: captive film suppliers preserving margin control, healthcare specialists anchoring regulated verticals, and asset-light regional converters capturing short-run digital demand. M&A activity concentrates among mid-tier converters seeking cleanroom certifications, while strategic partnerships link adhesive formulators with substrate innovators.
Within the integrated-film tier, Avery Dennison Corporation occupies a position representing captive supply chain control, while CCL Industries Inc. exemplifies healthcare-focused cleanroom manufacturing specialization. 3M Company anchors the adhesive chemistry leadership archetype for performance-engineered applications.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| CCL Industries Inc. |
| 3M Company |
| Multi-Color Corporation |
| UPM Raflatac |
| LINTEC Corporation |
| Constantia Flexibles |
| Huhtamäki Oyj |
| Fuji Seal International, Inc. |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's freight rate volatility transmits directly into pressure label converter margins, concentrating pricing power among film-integrated manufacturers while fragmenting regional players across substrate tiers and adhesive chemistries.
Pricing Analysis
Cost-plus contracts indexed to polypropylene and acrylic monomer spot benchmarks dominate long-term supply agreements between substrate suppliers and mid-tier converters. Three-tier pricing structure across premium, standard, and economy levels separates cleanroom-certified healthcare constructions from general industrial labels and commodity paper facestocks. Pricing pressure stems from petrochemical feedstock volatility compressing converter margins, particularly for non-integrated players lacking captive resin supply. Brand procurement teams at multinational FMCG corporations exhibit highest price sensitivity through consolidated volume tenders, while pharmaceutical manufacturers prioritize validation reliability over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from petrochemical majors anchor working capital structures for coating and converting equipment operators across Germany, China, and Japan. Raw material flows draw from specialty acrylic ester production clusters in the Rhine-Ruhr corridor, biaxially oriented polypropylene film extrusion in the Yangtze River Delta, and silicone adhesive formulation in the Kansai region. Single-source vulnerability concentrates in German and Japanese monomer production, exposing converters to geographic disruption. Distribution runs through converter-direct relationships with brand procurement teams, supplemented by distributor networks serving fragmented regional label buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Pressure Labels Market sits in early-cycle expansion as pharmaceutical serialization mandates and smart labeling integration create specification-driven demand tailwinds across healthcare and premium retail verticals.
For Market Incumbents: Entrench cleanroom certification advantages through ISO 14644 facility investments targeting CDSCO track-and-trace deadlines in India and EMA serialization requirements in Europe. Deepen backward integration into captive film extrusion to defend margin control against petrochemical feedstock volatility eroding converter economics.
For New Entrants and Emerging Players: Establish a beachhead in digital print-on-demand services for short-run variable data production, where collapsing minimum order quantities open regional brand launch opportunities. Target RFID-NFC convergence applications for luxury goods authentication, leveraging laser die-cutting technology to compress product development cycles without mechanical tooling capital.
For Investors and Strategic Acquirers: Asset-light regional converters with digital printing capabilities and established brand relationships represent the most attractive acquisition archetype for platform consolidation plays. Watch cleanroom certification backlog timelines as the inflection signal—extended ISO 14644 validation queues indicate demand saturation and pricing power shift toward qualified capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Certification Investment | ISO 14644 compliance opens pharmaceutical serialization contracts under CDSCO and EMA mandates. |
| Backward Integration into Film Extrusion | Captive polypropylene supply insulates margins from petrochemical volatility in Rhine-Ruhr and Yangtze Delta. |
| Digital Print-on-Demand Scale-Up | Laser die-cutting and short-run variable data production collapses minimum order quantities for regional launches. |
| RFID-NFC Inlay Integration | Passive inlay convergence with pressure-sensitive constructions enables luxury goods authentication at item level. |
| Bio-Based Acrylic Reformulation | REACH-compliant adhesive chemistry captures European market share as ECHA restrictions force monomer substitution. |
Study Parameters
A standing panel of coating equipment operators, adhesive formulation chemists, brand procurement managers, and cleanroom validation specialists provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with converter technical directors and pharmaceutical packaging engineers, validated against secondary sources including ECHA REACH substance databases, FDA label adhesion guidance documents, and customs trade flow records for polypropylene film and acrylic ester monomers. Bottom-up volume modeling across substrate tiers and adhesive chemistries triangulated with top-down value estimates from regional production cluster analysis.
Scenario-bracketing around petrochemical price volatility, regulatory timeline acceleration, and e-commerce fulfillment automation penetration shaped the analytical framework across the projection horizon. Segmentation dimensions included material substrate, adhesive chemistry, end-use vertical, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating converter capacity utilization rates and brand procurement consolidation patterns. Industry-specific inputs encompassed pharmaceutical serialization mandate deadlines and smart labeling technology adoption curves.
Sensitivities concentrate around CDSCO track-and-trace deadline delays, EU Packaging and Packaging Waste Regulation recyclability timeline extensions, and crude oil benchmark movements affecting polypropylene resin economics. Forecasts reflect documented assumptions on regulatory enforcement consistency and converter qualification throughput. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Waterproof Labels Market
Labels
Thermal Labels Market
Labels
Tags Market
Labels
Shrink and Stretch Sleeve Labels Market
Labels
United States Print Label Market
Labels
Self-Adhesive Labels Market
Labels
Variable Data Printing Labels Market
Labels
Stand Alone Label Applicator Market
Labels
Oxygen Indicator Labels Market
Labels
Global Cryogenic Label Market
Labels
Pre-Gummed Labels Market
Labels
Self-Laminating Tags Market
Labels
Indicative Seals Market
Labels
GCC Labeling Market
Labels
Foam Labels Market
Labels
Global Label Market