
 Global Wireless Gas Detection Market | 2026-2036
Global Wireless Gas Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wireless Gas Detection Market Intelligence
Revenue from cloud-connected monitoring services is tilting the market's profit pool away from standalone hardware sales. Honeywell International leverages its extensive industrial software portfolio to capture this value shift. MSA Safety sustains its market position through a focus on ruggedized hardware for harsh environments. Siemens integrates its gas detection systems within broader digital factory and process automation platforms.
Wireless gas detection systems comprise sensor nodes that identify and quantify specific airborne gases without physical cabling. These systems typically use communication protocols like Wi-Fi or proprietary mesh networks to transmit data on gas concentrations, often measured in parts per million (PPM), to a central controller. Infrared technology leads for hydrocarbon detection due to its reliability, while electrochemical sensors dominate toxic gas monitoring. Systems for oil & gas extraction and chemical processing plants constitute the largest application segments due to inherent operational risks.
Product design and market access are governed by a complex web of safety and environmental regulations. These include OSHA's permissible exposure limits in the United States, Europe's ATEX directives for explosive atmospheres, and emissions standards set by China's Ministry of Ecology and Environment (MEE). Vendor success will depend on navigating these fragmented regional certification requirements while innovating in sensor accuracy and battery life.
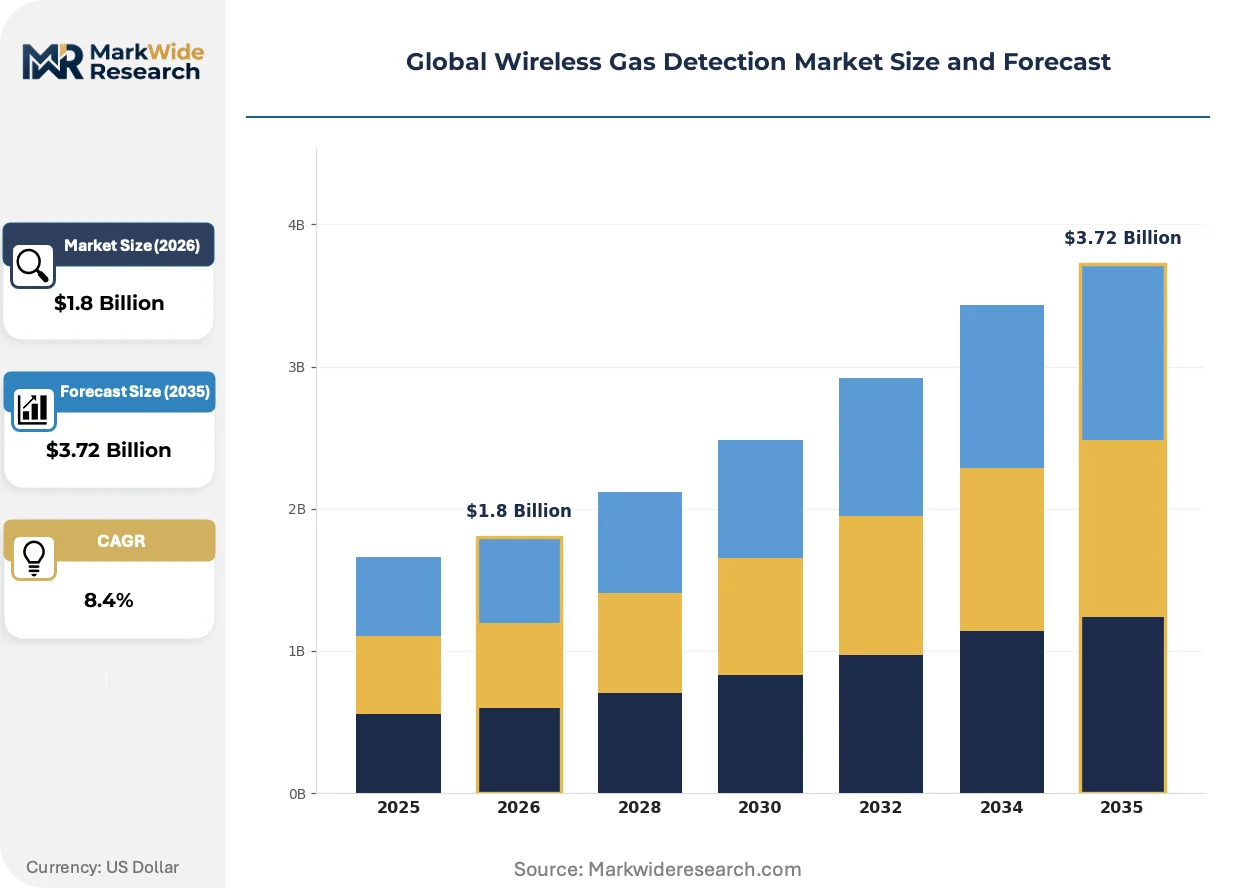
Market Dynamics
The convergence of stringent environmental regulations and enterprise-level safety mandates is the central force shaping the wireless gas detection market. Pressure from bodies like the US EPA on fugitive emissions, combined with internal corporate ESG goals, compels investment beyond basic compliance.
Growth Catalysts
- Petrochemical Investment:Significant capital expenditure on new petrochemical facilities, particularly in Saudi Arabia and the UAE, creates baseline demand for extensive wireless monitoring systems to ensure operational safety from project inception.
- Regulatory Mandates:Europe's ATEX directives, which govern equipment used in explosive atmospheres, necessitate certified wireless detection systems in chemical processing, refining, and pharmaceutical manufacturing environments.
- Network Technology Advancement:The maturation of proprietary mesh networks and LoRaWAN protocols enhances system reliability and range, enabling large-scale deployments across sprawling industrial sites like oilfields and LNG terminals where traditional Wi-Fi is unfeasible.
Market Restraints
- High Initial Capital Outlay:The upfront cost of purchasing and installing a comprehensive network of wireless sensor nodes, gateways, and central controllers remains a significant barrier for small to mid-sized industrial operators.
- Sensor Battery Life:Limited battery longevity in sensor nodes creates a substantial operational burden and total cost of ownership, requiring frequent maintenance cycles for replacement, especially in remote or difficult-to-access locations.
- Fragmented Certification Requirements:Navigating disparate regional safety and performance certifications, such as ATEX in Europe, IECEx for international use, and specific standards from China's MEE, complicates product design and market access for vendors.
Strategic Opportunities
- Wastewater and Utilities Sector:Underpenetrated applications in municipal water and wastewater treatment plants present a key growth area, driven by the need to monitor for toxic gases like hydrogen sulfide and chlorine in confined spaces.
- AI and Predictive Analytics:Integrating sensor data with AI-powered analytics platforms allows for predictive maintenance alerts and proactive leak identification, shifting the value proposition from reactive alarms to preventative asset management.
- Industrial Expansion in Southeast Asia:Rapid industrialization in countries like Vietnam and Indonesia, particularly in manufacturing and chemical production, offers a new geographic frontier for wireless gas detection system deployment.
Industry Challenges
- Legacy System Integration:The complexity of interfacing modern wireless gas detection systems with older, existing plant-wide Distributed Control Systems (DCS) or SCADA platforms often leads to implementation delays and additional costs.
- Wireless Network Security:Protecting data transmitted from sensors against cyber threats is a critical challenge, as a compromised network could lead to missed alerts or false alarms, with severe safety implications.
- Specialized Talent Shortage:A deficit of technicians with hybrid expertise in both industrial instrumentation and wireless IT networking can hinder the effective installation, commissioning, and maintenance of advanced detection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wireless Gas Detection Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Infrared, Ultrasonic, Electrochemical, Catalytic Bead, Photoionization, Semiconductor Application: Oil & Gas Extraction, Chemical Processing Plants, Confined Space Entry, Fire & Explosion Monitoring, Environmental Surveillance, Mining Operations End User: Petrochemical Firms, Utility Providers, Construction Contractors, Hazardous Waste Handlers, Manufacturing Facilities, Emergency Responders Deployment Mode: Cloud-Connected, Edge Computing, Standalone Units, Mesh Network Systems, Centralized Monitoring, Remote Monitoring |
| Companies Covered | Honeywell International, MSA Safety, Drägerwerk, Siemens, Yokogawa Electric Corporation, Crowcon Detection Instruments, Tyco Gas & Flame Detection, Emerson Electric, Detector Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wireless Gas Detection Market Strategic Shifts & Innovations
The market's center of gravity is shifting from one-time hardware sales toward recurring revenue from cloud-based monitoring and data analytics services. This evolution transforms gas detectors from simple alert devices into nodes within a broader industrial intelligence network.
Miniature electrochemical and non-dispersive infrared (NDIR) sensors form the technological core of modern wireless systems. Oil & gas and chemical processing firms are rapidly adopting these for continuous, facility-wide monitoring. This proliferation of low-power sensor nodes is digitizing plant safety protocols, replacing periodic manual spot-checks with a persistent, real-time view of environmental hazards.
Stricter enforcement of fugitive emission standards by regulators, including the US Environmental Protection Agency (EPA), is a powerful demand signal. This compels continuous monitoring for methane and volatile organic compounds (VOCs) in oil refineries, gas processing plants, and chemical facilities. The upstream and midstream oil & gas segments are most affected, accelerating investment in systems with infrared and photoionization detectors to ensure regulatory compliance.
A clear behavioral shift toward "Detection-as-a-Service" (DaaS) models is underway. This service-based approach unbundles the hardware purchase from ongoing system management, with specialist providers handling calibration, maintenance, and data reporting for a recurring fee. This trend is most visible in large-scale North American and Middle Eastern industrial complexes where operators seek to outsource non-core operational overhead.
Global Wireless Gas Detection Market Segmentation
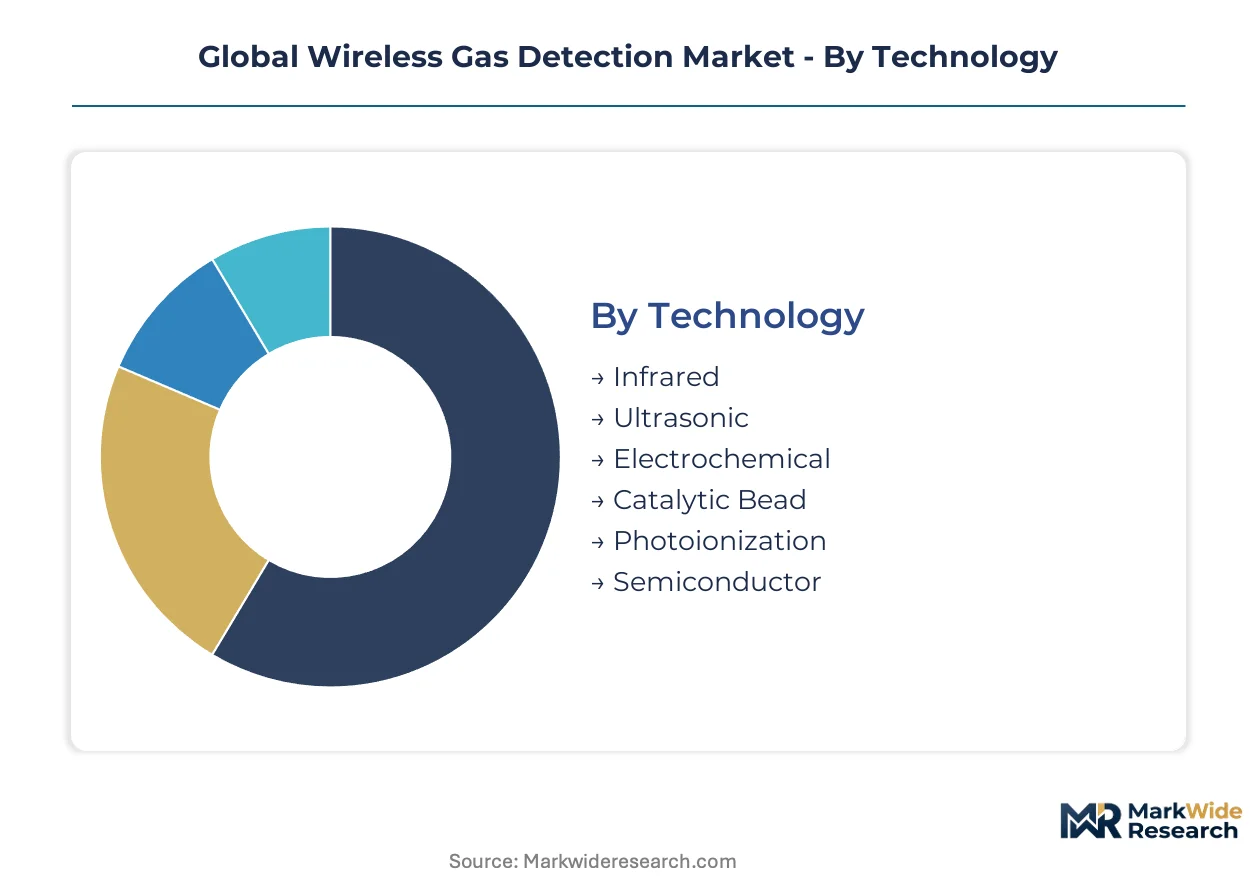
The global wireless gas detection market exhibits diverse operational requirements, driving a granular segmentation across various dimensions. Understanding these distinct segments allows stakeholders to tailor product development, market entry strategies, and regulatory compliance efforts effectively.
Technology:
Sensor technologies in wireless gas detection systems exhibit varying refresh rates and maintenance cycles. Newer electrochemical sensors offer frequent updates, while catalytic bead sensors often require more calibration over time.
- Infrared:This technology detects hydrocarbon gases by measuring the absorption of specific infrared wavelengths. Its reliability and resistance to poisoning make it essential for continuous monitoring in oil refineries and gas processing plants across Saudi Arabia.
- Electrochemical:These sensors react with target toxic gases to produce an electrical current proportional to gas concentration. They are widely deployed for hydrogen sulfide and carbon monoxide detection in chemical processing facilities throughout Europe.
- Ultrasonic:Ultrasonic sensors identify gas leaks by detecting the unique sound signature of escaping pressurized gas.
- Catalytic Bead:These sensors utilize a heated bead to oxidize combustible gases, measuring the resulting temperature change.
- Photoionization:Photoionization detectors (PIDs) use ultraviolet light to ionize volatile organic compounds (VOCs), enabling their detection.
- Semiconductor:Semiconductor sensors change electrical resistance in the presence of target gases, offering cost-effective detection for various applications.
Electrochemical sensors dominate the installed base. Infrared technology is where expansion concentrates for hydrocarbon detection.
Application:
Application segments for wireless gas detection systems vary significantly in their operational hazard profiles and regulatory oversight.
- Oil & Gas Extraction:This segment requires robust, intrinsically safe systems for continuous monitoring of methane and other flammable gases. Stricter US EPA fugitive emission standards compel significant investment in these systems.
- Chemical Processing Plants:These facilities demand precise detection of a wide array of toxic and flammable gases to ensure worker safety and environmental compliance. Europe's ATEX directives mandate certified systems in these environments.
- Confined Space Entry:This application focuses on portable and personal detectors for hazardous gases before and during worker entry into enclosed areas.
- Fire & Explosion Monitoring:Systems in this segment are integrated into broader safety protocols to provide early warning of combustible gas buildup.
- Environmental Surveillance:These deployments monitor ambient air quality and detect specific pollutants for regulatory reporting and public safety.
- Mining Operations:Wireless systems provide critical monitoring for methane and other hazardous gases in underground and surface mining environments.
Oil & Gas Extraction consistently generates the largest volume of demand. Confined Space Entry applications are gaining share fastest due to enhanced safety protocols.
End User:
Different end-user types exhibit distinct purchasing behaviors and service requirements for wireless gas detection solutions.
- Petrochemical Firms:These enterprises require extensive, facility-wide systems for continuous monitoring of flammable and toxic gases. New investments in the UAE drive substantial demand for these advanced solutions.
- Utility Providers:Municipal water and wastewater treatment plants increasingly adopt wireless systems to monitor hydrogen sulfide and chlorine in critical infrastructure. This sector represents a key growth area.
- Construction Contractors:These users primarily need portable and flexible gas detection units for temporary work sites and confined spaces.
- Hazardous Waste Handlers:This segment relies on robust detection systems to ensure worker safety during the handling and disposal of dangerous materials.
- Manufacturing Facilities:General manufacturing operations utilize wireless detectors for various gases, including refrigerants and combustion byproducts.
- Emergency Responders:First responders use portable gas detectors for immediate hazard assessment in incident management scenarios.
Petrochemical Firms represent the most mature customer type. Utility Providers are demonstrating significant new procurement interest.
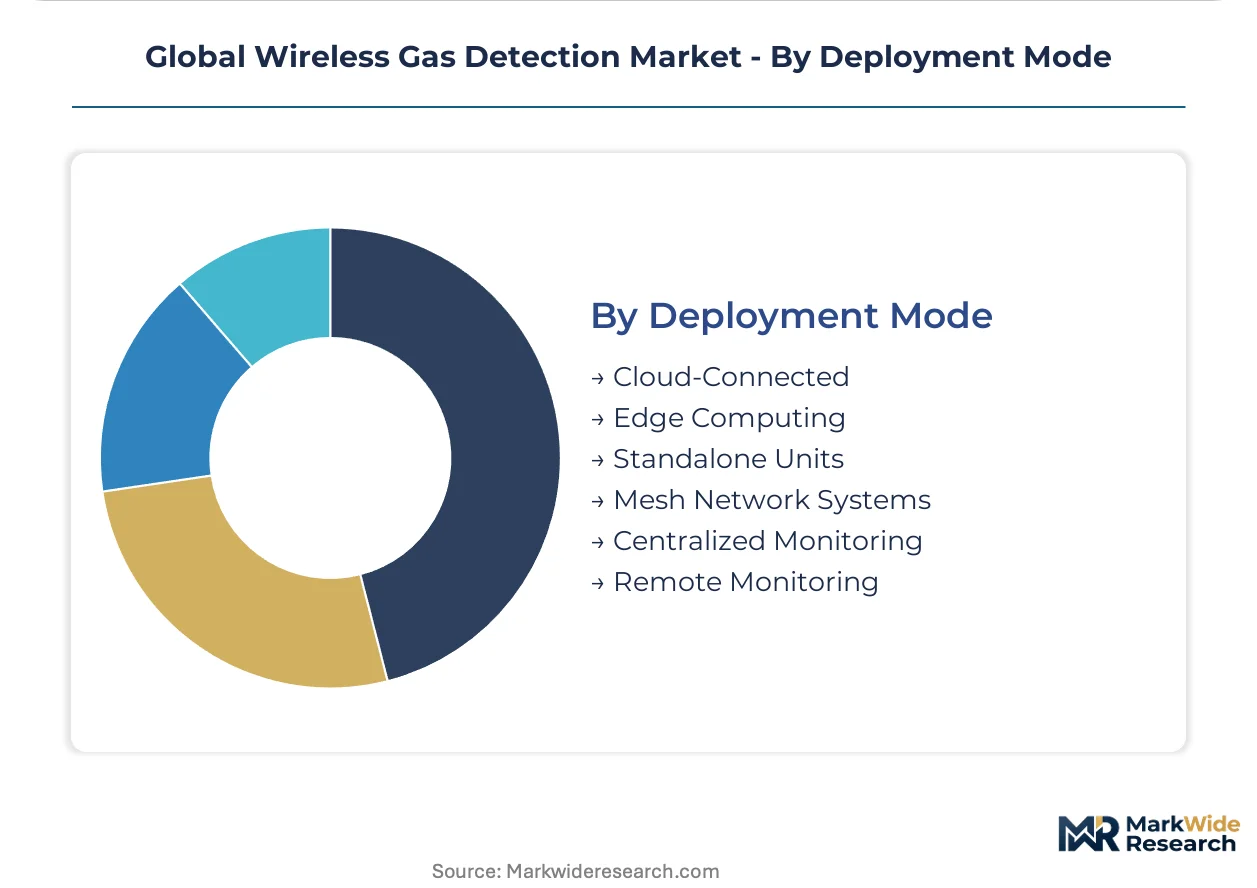
Deployment Mode:
The maturity of various deployment modes influences their integration complexity and data management capabilities.
- Cloud-Connected:These systems transmit gas detection data to remote cloud platforms for analytics, reporting, and predictive maintenance. This mode is reshaping competitive positioning by shifting profit pools towards services.
- Mesh Network Systems:Proprietary mesh networks provide reliable, long-range communication for sensor nodes across vast industrial sites. LoRaWAN protocols enhance system reliability for large-scale deployments like LNG terminals.
- Edge Computing:Edge devices process gas detection data locally, reducing latency and bandwidth requirements for critical alerts.
- Standalone Units:These independent detectors provide local alarms without central connectivity, often used for personal safety or basic spot monitoring.
- Centralized Monitoring:Data from multiple sensors converges at a single control room, enabling comprehensive oversight of an entire facility.
- Remote Monitoring:This mode allows for off-site observation and management of gas detection systems, particularly useful in hazardous or inaccessible areas.
Standalone Units constitute the traditional deployment mode. Cloud-Connected solutions reflect strategic investment in data-driven safety.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for wireless gas detection systems varies significantly across geographies; price sensitivity is higher in emerging industrial markets, while established regions prioritize advanced features and regulatory compliance. Buyers in regions with stringent safety mandates often accept higher capital outlays for sophisticated cloud-connected solutions. Conversely, operators in cost-conscious environments seek more economical, standalone units for basic monitoring needs.
United States
The United States market for wireless gas detection systems is driven by stringent US EPA fugitive emission standards and OSHA worker safety mandates. Investment is accelerating in oil refineries and chemical processing plants to monitor methane and volatile organic compounds. The Gulf Coast region, particularly around Houston, Texas, sees extensive deployment due to its concentration of petrochemical facilities.
Saudi Arabia
Significant capital expenditure on new petrochemical facilities and oil & gas extraction projects fuels demand in Saudi Arabia. The Saudi government's Vision 2030 initiatives emphasize industrial diversification, requiring advanced safety infrastructure. The Eastern Province, home to major Aramco operations and new industrial cities, represents a primary hub for system integration.
Germany
Germany's industrial sector, particularly chemical and pharmaceutical manufacturing, is a strong adopter of wireless gas detection systems, driven by Europe's ATEX directives. The country's focus on Industry 4.0 integrates these systems into broader digital factory platforms. The Rhine-Ruhr area, a dense industrial belt, consistently procures advanced electrochemical and infrared sensors.
China
China's market is expanding due to rapid industrialization and stricter environmental enforcement by the Ministry of Ecology and Environment (MEE). Demand is strong in chemical production and manufacturing sectors, aiming to reduce industrial accidents and pollution. The Yangtze River Delta region, with its vast industrial base, is a key area for new system installations.
United Arab Emirates
New investments in petrochemical facilities and the expansion of oil & gas infrastructure are driving demand in the United Arab Emirates. The UAE government's emphasis on industrial safety and environmental protection mandates continuous monitoring solutions. Abu Dhabi's industrial zones and Jebel Ali in Dubai are significant centers for wireless gas detection system deployment.
Global Wireless Gas Detection Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a dynamic competitive environment in the wireless gas detection market. This market structure features a mix of established industrial conglomerates and specialized technology providers. Strategic archetypes include diversified industrial technology leaders, niche safety equipment manufacturers, and software-centric service providers. Dominant competitive moves involve strategic partnerships for technology integration and portfolio diversification into recurring service models.
Within the diversified industrial technology leader archetype, Honeywell International and Siemens occupy strong positions, leveraging their extensive industrial software and automation platforms. MSA Safety exemplifies the specialized safety equipment manufacturer, maintaining its market standing through ruggedized hardware designed for harsh operational environments. These companies anchor the industry's evolution, often shaping technological standards and service delivery expectations for the broader market.
| Leading Market Players |
|---|
| Honeywell International |
| MSA Safety |
| Drägerwerk |
| Siemens |
| Yokogawa Electric Corporation |
| Crowcon Detection Instruments |
| Tyco Gas & Flame Detection |
| Emerson Electric |
| Detector Electronics Corporation |
| Others |
Cost & Logistics Intelligence
Sensor component manufacturing in East Asia, particularly China, concentrates upstream supply, directly influencing the cost structure and margin potential for downstream wireless gas detection system integrators.
Pricing Analysis
Cloud-connected monitoring services drive lifetime value, shifting the profit pool from initial hardware sales. Subscription-based models for data analytics and predictive maintenance define the dominant pricing structure. Certification levels, such as ATEX and IECEx, and sensor accuracy differentiate pricing, enabling premium tiers for specialized applications. Pricing pressure stems from commoditization of basic electrochemical sensors, particularly for general industrial use. Small to mid-sized industrial operators exhibit high price sensitivity, prioritizing upfront cost, while large petrochemical firms prioritize advanced features and compliance.
Supply Chain Analysis
Contract manufacturing for sensor components and electronic sub-assemblies primarily concentrates in China, forming the core of the supply chain. Raw material dependencies include specialized polymers for sensor housings and rare earth elements for certain advanced sensor types. Single-source vulnerability for proprietary sensor technologies represents a structural risk, particularly for high-performance infrared detectors. Distribution runs through a dual model, with direct sales channels serving large industrial clients and a network of system integrators supporting smaller deployments and specialized project needs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the increasing demand for specialized monitoring solutions in underpenetrated sectors like wastewater treatment.
For Market Incumbents:
Pre-empt commoditization of basic hardware by accelerating investment in AI-powered predictive analytics platforms. Acquire specialized software firms to integrate advanced data processing capabilities, countering the threat from pure-play software providers. Invest in R&D for extended battery life and miniaturization to reduce operational overhead for end-users. Reinforce global market access by proactively securing certifications like China's MEE standards for new product lines.
For New Entrants and Emerging Players:
Build out niche expertise in underpenetrated applications such as the municipal wastewater and utilities sector, where specific toxic gas monitoring needs are unmet. Target confined space entry applications, which are gaining share fastest due to enhanced safety protocols, with portable and user-friendly solutions. Offer Detection-as-a-Service (DaaS) models, bundling hardware with ongoing maintenance and data reporting, as a compelling go-to-market angle for mid-sized industrial clients.
For Investors and Strategic Acquirers:
Secondary-cycle assets sit with pure-play hardware manufacturers seeking to divest non-core segments. The market demonstrates long-term viability, underpinned by escalating environmental compliance and worker safety mandates. Target software-centric firms specializing in cloud analytics and data integration platforms, as these capture value from recurring revenue streams. A clear signal to watch is the harmonization of fragmented regional certification requirements, which would streamline market entry and product development.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire AI/Analytics Platforms | Enhances predictive maintenance capabilities, shifting market value towards proactive asset management for petrochemical firms. |
| Invest in Long-Life Battery R&D | Reduces operational burden and total cost of ownership for oil & gas extraction sites and remote facilities. |
| Expand DaaS Offerings | Captures recurring revenue streams and addresses the total cost of ownership concerns for utility providers. |
| Pursue Wastewater Sector Entry | Unlocks significant new demand for hydrogen sulfide and chlorine monitoring in municipal infrastructure. |
| Standardize Global Certifications | Streamlines product design and accelerates market access across diverse regulatory environments for vendors. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary regulatory filings anchors the qualitative findings. This involved discussions with plant managers, safety officers, and system integrators. Secondary data sources included US EPA reports, Europe's ATEX directives, and company financial statements, ensuring bottom-up and top-down triangulation of market insights.
The calibration approach involved developing a robust analytical framework to project market growth across the analysis window. Segmentation dimensions modeled included technology, application, end-user, deployment mode, and regional regulatory clusters. Compound annual growth rates were derived through a proprietary algorithm, incorporating forecast inputs such as planned petrochemical investment and anticipated regulatory enforcement trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized sensor developers or cloud platform providers would shift outcomes. Forecasts reflect assumptions regarding technological advancements and consistent regulatory enforcement. Quarterly review of new petrochemical facility investments and evolving environmental compliance mandates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Latin America Trace Detection Market
Detection and Regulation Devices
Hydrogen Detection Transmitters Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Constant Current Regulator Market
Detection and Regulation Devices
Temperature Modulation Devices Market
Detection and Regulation Devices
Global Gas Leak Detectors Market
Detection and Regulation Devices
Pyro Electric Infrared Detectors Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Duct Smoke Detectors Market
Detection and Regulation Devices
Temperature Detection Screen Market
Detection and Regulation Devices
Flooded Member Detection Equipment Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Registering Clock Driver (RCD) Market
Detection and Regulation Devices
Portable Radar Detectors Market
Detection and Regulation Devices
Global Portable Gas Detector Market
Detection and Regulation Devices
Pin and Sleeve Devices Market