
 Ultrasonic Thickness Gauge Market | 2026-2036
Ultrasonic Thickness Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Thickness Gauge Market Analytics
Germany's precision instrumentation cluster is reshaping competitive dynamics in ultrasonic thickness gauge supply. Olympus Corporation leverages its decades-long transducer expertise to dominate high-frequency applications above 10 MHz. DeFelsko Corporation anchors the handheld segment with ruggedized designs purpose-built for field corrosion surveys. Baker Hughes Company competes through integrated digital platforms that pair thickness data with predictive analytics.
An ultrasonic thickness gauge measures material wall thickness by transmitting high-frequency sound pulses through a substrate and calculating the time interval until echo return, typically operating between 0.5 MHz and 50 MHz depending on material density and required resolution. These instruments serve critical functions in corrosion monitoring, weld inspection, and structural integrity verification across metal, composite, and ceramic substrates. Piezoceramic transducer technology occupies the largest installed base due to its cost-efficiency and broad frequency range, while time-of-flight diffraction systems command premium positioning in subsea pipeline applications where defect sizing precision determines maintenance scheduling. Magnetostrictive sensors sustain niche adoption in high-temperature boiler tube monitoring where conventional piezoelectric elements degrade.
API 510 pressure vessel inspection codes and ASME B31.3 process piping standards mandate periodic thickness measurement intervals that directly sustain replacement demand cycles. OSHA process safety management regulations enforce documented mechanical integrity programs in covered facilities, embedding ultrasonic testing into compliance workflows. China's GB/T 11344 nondestructive testing standards and NMPA equipment registration requirements shape product certification pathways for market entry. Stakeholders must weigh sensor miniaturization roadmaps against the durability requirements of unmanned inspection platforms now penetrating offshore wind and subsea infrastructure markets.
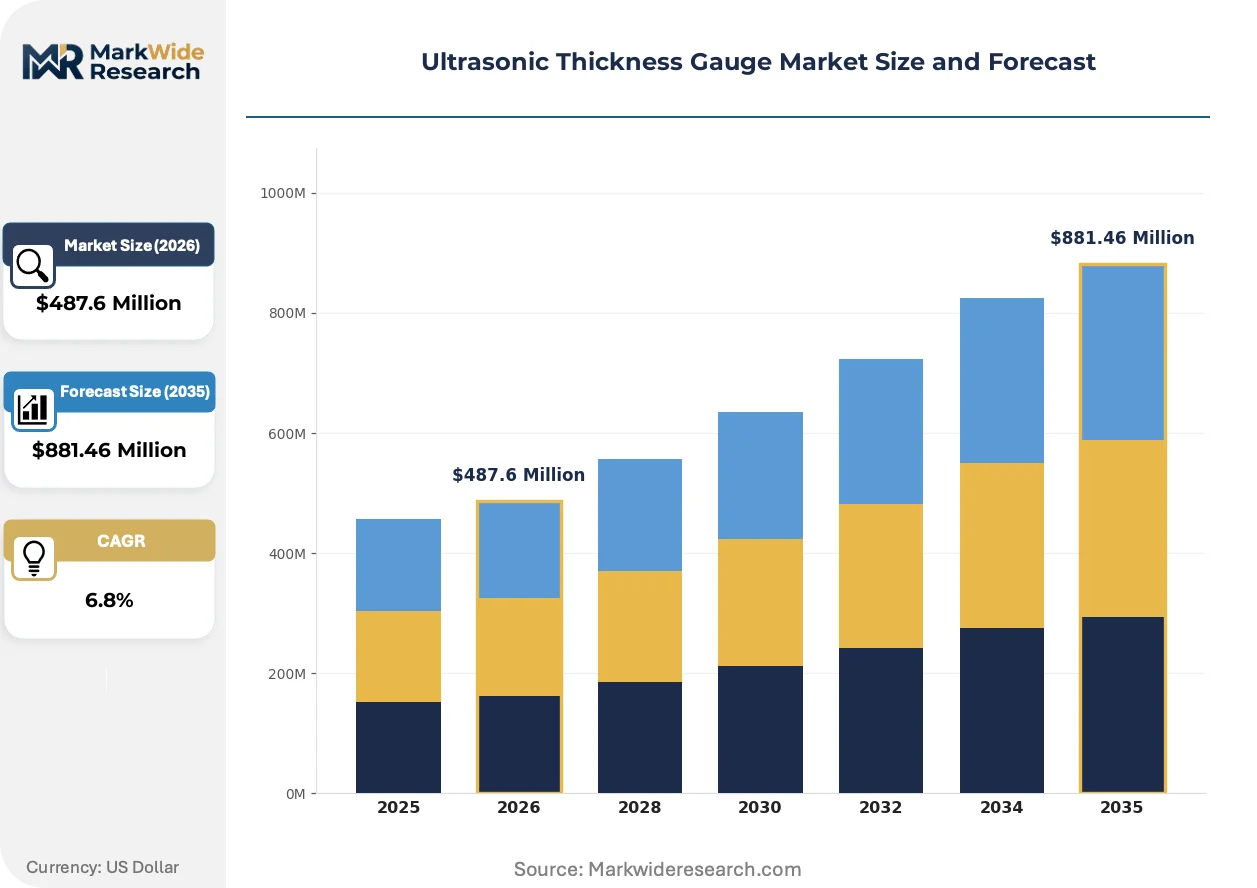
Market Dynamics
API 510 pressure vessel codes and ASME B31.3 process piping standards are compressing inspection intervals across North American refinery networks, forcing asset operators to embed continuous thickness monitoring into capital planning cycles rather than treating it as episodic maintenance.
Growth Catalysts
- Pipeline integrity mandates:FERC safety regulations require documented wall-thickness baselines for interstate natural gas transmission lines, creating recurring instrument replacement cycles.
- Offshore wind foundation inspection:Bureau of Ocean Energy Management lease stipulations mandate subsea structural surveys for monopile corrosion, opening new demand for time-of-flight diffraction systems rated to 300-meter depths.
- GB/T 11344 adoption:China's nondestructive testing standardization campaign is certifying domestic inspection contractors, expanding the qualified operator base for ultrasonic thickness protocols.
Market Restraints
- Piezoceramic supply concentration:High-purity lead zirconate titanate wafer production concentrates in Japanese and German specialty ceramic foundries, exposing gauge manufacturers to alloying element price volatility.
- Electromagnetic acoustic transducer substitution:EMAT systems eliminate couplant requirements in high-temperature boiler tube applications, eroding the addressable market for conventional contact-mode piezoelectric gauges above 400°C.
- CE marking friction:EU Machinery Directive conformity assessment timelines for multi-frequency portable units extend certification cycles by four to six months versus single-purpose industrial fixed installations.
Strategic Opportunities
- Unmanned underwater vehicle integration:Subsea inspection robotics manufacturers in Norway and the United Kingdom are sourcing miniaturized 25 MHz immersion probes for autonomous pipeline survey missions.
- Digital twin convergence:Thickness data streams from wireless-enabled gauges are feeding predictive corrosion models, creating recurring software subscription revenue alongside hardware sales.
- India petrochemical buildout:Reliance Industries and Indian Oil Corporation are expanding Gujarat and Maharashtra refinery capacity, requiring thousands of new inspection points under Petroleum and Natural Gas Regulatory Board technical standards.
Industry Challenges
- Phased array certification scarcity:ASNT Level III ultrasonic technicians with time-of-flight diffraction credentials command premium wages, constraining inspection contractor scaling.
- Legacy DCS integration complexity:Refinery operators running Honeywell TDC 3000 or Yokogawa CENTUM systems face protocol translation costs when connecting modern Ethernet-enabled thickness gauges to 1990s-era distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Thickness Gauge Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piezoceramic, Magnetostrictive, Capacitive, Laser End User: Aerospace, Energy, Manufacturing, Automotive Technology: Single Echo, Through Transmission, Dual Element, Time of Flight Application: Material Inspection, Quality Control, Pipeline Monitoring, Corrosion Assessment |
| Companies Covered | Olympus Corporation, Cygnus Instruments Ltd, Tritex NDT, Extech, NDT Systems Inc, DeFelsko Corporation, Baker Hughes Company, Sonatest Ltd, Elcometer Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Thickness Gauge Market Evolving Landscape
Wireless thickness monitoring arrays and artificial intelligence-enabled defect classification algorithms are displacing manual point-measurement workflows in continuous process industries, compressing the value capture toward data analytics platforms.
Phased array ultrasonic testing with full matrix capture acquisition is rendering obsolete single-element A-scan gauges in weld inspection applications where defect orientation varies. Pipeline construction contractors in the United States Gulf Coast corridor are specifying phased array protocols for new cross-country line construction, eliminating the need for radiographic backup inspection and reducing cycle time by half.
OSHA process safety management enforcement memoranda are tightening mechanical integrity documentation requirements for covered chemical facilities. Inspectors now demand timestamped thickness readings with GPS coordinates and operator identification, forcing gauge manufacturers to embed tamper-evident data logging as standard firmware rather than optional accessories. This shift most affects handheld unit suppliers serving contract inspection firms.
Buying committees at integrated oil companies are unbundling hardware procurement from calibration service contracts, pitting specialized NDE service providers against original equipment manufacturers for multi-year maintenance agreements. This pattern is most visible in the Rotterdam-Antwerp refining cluster, where Shell and BP facilities have consolidated ultrasonic testing contracts under third-party asset integrity managers rather than direct gauge vendor relationships.
Ultrasonic Thickness Gauge Market Segmentation
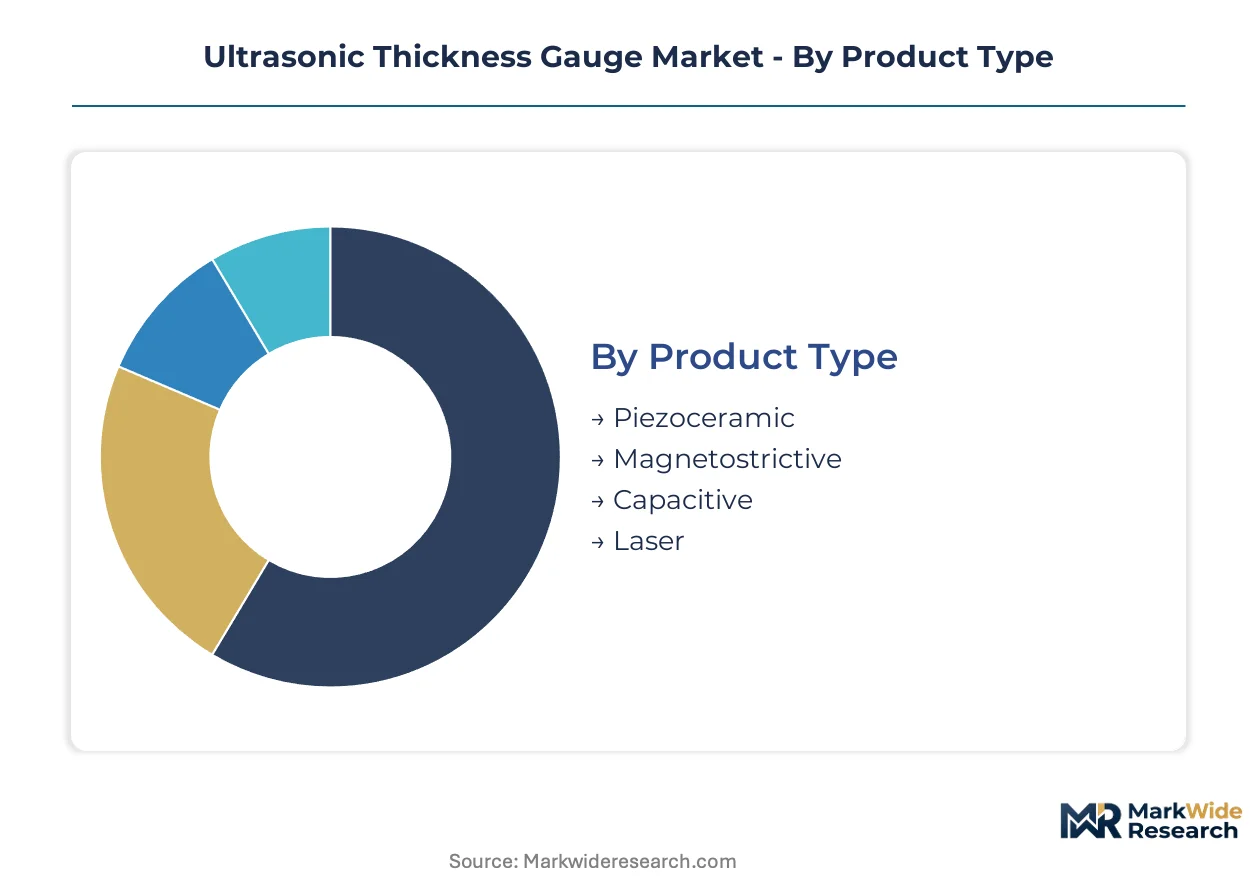
Ultrasonic thickness gauge procurement patterns diverge sharply between mature industrial verticals with established inspection protocols and emerging applications demanding specialized form factors. Technology selection hinges on material properties, access constraints, and regulatory documentation requirements rather than unit cost alone.
Product Type:
Mature piezoceramic architectures dominate installed bases, while emerging alternatives carve niches through temperature tolerance and couplant-free operation.
- Piezoceramic:Lead zirconate titanate transducers generate acoustic pulses across 0.5-50 MHz ranges with cost efficiency unmatched by alternative technologies. Refinery operators along the United States Gulf Coast specify these for routine pipeline wall-thickness surveys under API 510 intervals.
- Magnetostrictive:Ferromagnetic strip sensors convert magnetic field variations into elastic waves, eliminating direct contact requirements. These systems sustain continuous monitoring in boiler tube applications above 400°C where piezoelectric elements degrade.
- Capacitive:Micromachined membrane structures enable sub-millimeter probe dimensions for confined-space inspections.
- Laser:Optical interferometry techniques measure thickness without acoustic coupling, penetrating coatings that obstruct ultrasonic methods.
Piezoceramic retains volume leadership; laser holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive continuous process industries from discrete manufacturing with episodic inspection needs.
- Energy:Pipeline integrity mandates from FERC and ASME B31.3 codes compress inspection cycles across natural gas transmission and refinery networks. Operators embed fixed-installation gauges at critical corrosion monitoring locations.
- Aerospace:FAA airworthiness directives and OEM maintenance planning documents specify thickness verification intervals for turbine casings and structural elements. MRO facilities in Germany and France invest in phased array systems for defect sizing precision.
- Manufacturing:Quality control stations at metal forming and fabrication plants deploy handheld units for incoming material verification.
- Automotive:Battery enclosure manufacturers apply ultrasonic testing to validate weld integrity in electric vehicle chassis components.
Energy commands the premium pricing tier; automotive is climbing the fastest as electrification accelerates inspection point proliferation.
Technology:
Application complexity determines whether single-point measurement suffices or full waveform analysis becomes essential.
- Time of Flight:Precision timing of acoustic pulse transit enables sub-millimeter resolution in subsea pipeline surveys where defect sizing dictates maintenance scheduling. Norwegian UUV manufacturers specify 25 MHz immersion probes for autonomous missions to 300-meter depths.
- Dual Element:Separate transmitter-receiver configurations eliminate near-surface dead zones, penetrating thick castings and forgings with coarse grain structures. Foundries in India deploy these for petrochemical component qualification.
- Single Echo:Basic pulse-echo architectures serve routine corrosion monitoring with minimal operator training requirements.
- Through Transmission:Opposed transducer arrangements detect internal discontinuities by measuring signal attenuation rather than echo timing.
Dual Element sustains thickest-material penetration demand; Time of Flight is gaining share fastest in offshore automation.
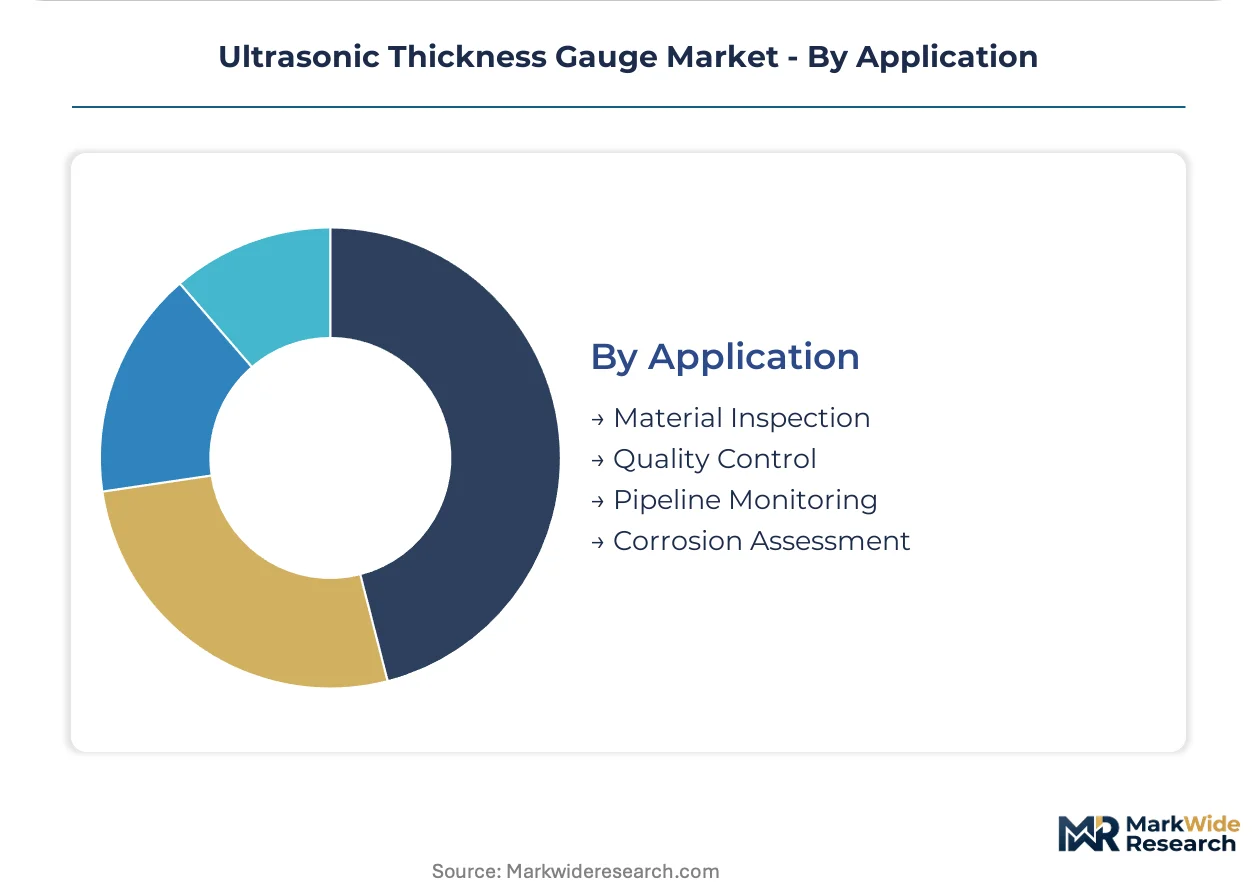
Application:
Customer type separation distinguishes compliance-driven scheduled inspection from proactive quality assurance integration.
- Pipeline Monitoring:Continuous wireless arrays feed digital twin corrosion models, converting thickness data into predictive maintenance schedules. Bureau of Ocean Energy Management lease stipulations mandate subsea structural surveys for offshore wind monopiles.
- Corrosion Assessment:Point-thickness measurements establish baseline wall conditions and calculate corrosion rates against API 510 retirement limits. Contract inspection firms in the Rotterdam-Antwerp cluster consolidate multi-site contracts under asset integrity managers.
- Material Inspection:Incoming verification ensures raw stock meets minimum thickness specifications before machining operations.
- Quality Control:In-process testing confirms weld penetration and heat-affected zone dimensions in fabricated assemblies.
Pipeline Monitoring retains the highest average selling prices; Corrosion Assessment is expanding most quickly through regulatory interval compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor anchors United States demand for continuous wall-thickness monitoring systems. FERC interstate pipeline regulations and API 510 vessel codes compress inspection cycles across the region's refinery networks.
United States
Petrochemical capacity expansions along the Texas and Louisiana Gulf Coast require thousands of new corrosion monitoring points. OSHA process safety management enforcement mandates documented mechanical integrity programs at covered chemical facilities. Houston-area contract inspection firms consolidate multi-site ultrasonic testing contracts under third-party asset integrity managers.
Germany
Precision instrumentation manufacturers in Baden-Württemberg and Bavaria supply high-frequency transducer technology for aerospace MRO applications. REACH chemical registration requirements and CE marking conformity assessments shape product certification pathways for EU market entry. Stuttgart's automotive supplier ecosystem applies ultrasonic testing to validate electric vehicle battery enclosure weld integrity.
China
State-owned refinery operators Sinopec and PetroChina expand NDT contractor certification under GB/T 11344 standardization campaigns. NMPA equipment registration requirements govern product approval timelines for imported gauges. Yangtze River Delta petrochemical complexes in Zhejiang and Jiangsu provinces drive demand for subsea-rated time-of-flight diffraction systems.
Norway
Subsea inspection robotics manufacturers source miniaturized immersion probes for autonomous pipeline survey missions to 300-meter depths. Bureau of Ocean Energy Management lease stipulations for North Sea offshore wind installations mandate monopile corrosion surveys. Stavanger and Bergen clusters specialize in unmanned underwater vehicle integration for subsea infrastructure monitoring.
India
Reliance Industries and Indian Oil Corporation expand Gujarat and Maharashtra refinery capacity under Petroleum and Natural Gas Regulatory Board technical standards. BIS certification requirements for imported testing equipment create compliance friction for foreign suppliers. Jamnagar and Vadodara industrial corridors require continuous thickness monitoring for new process piping installations.
Ultrasonic Thickness Gauge Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying transducer elements and signal processing modules. The vendor base stratifies across three tiers: multinational industrial conglomerates with predictive analytics platforms, mid-cap instrumentation houses with handheld portfolios, and regional fabricators serving price-sensitive inspection contractors. Two dominant competitive moves define current positioning: backward integration into piezoceramic wafer production to secure supply, and forward integration into calibration service contracts to capture recurring revenue streams.
Among Japanese and German precision component suppliers, Olympus Corporation and DeFelsko Corporation occupy distinct archetype positions—Olympus representing high-frequency transducer expertise above 10 MHz, DeFelsko anchoring ruggedized handheld designs for field corrosion surveys. Baker Hughes Company exemplifies the integrated platform tier, pairing thickness measurement hardware with digital infrastructure for asset integrity management.
| Leading Market Players |
|---|
| Olympus Corporation |
| Cygnus Instruments Ltd |
| Tritex NDT |
| Extech |
| NDT Systems Inc |
| DeFelsko Corporation |
| Baker Hughes Company |
| Sonatest Ltd |
| Elcometer Limited |
| Others |
Value Network & Pricing Analysis
Japanese and German specialty ceramic foundries concentrate high-purity lead zirconate titanate wafer production, anchoring margin capture upstream while gauge assemblers downstream compete on calibration service bundling. This concentration transfers pricing power to transducer substrate suppliers and forces hardware manufacturers toward recurring-revenue service contracts to defend profitability.
Pricing Analysis
API 510 and ASME B31.3 inspection codes dictate the pricing tier structure by mandating certified documentation packages that separate premium-calibrated units from economy handhelds. Three-tier pricing structure across premium phased-array systems, standard dual-element gauges, and economy single-echo units stratifies the market. Cost compression in the economy tier intensifies as Asian contract manufacturers scale piezoceramic probe output. Contract inspection firms exhibit highest price sensitivity; integrated oil companies prioritize certification pedigree over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for gauge manufacturers sourcing machined housings and printed circuit assemblies. Production concentrates in Japan, Germany, and China for transducer elements; Mexico and Vietnam for final assembly. Raw material dependencies include lead zirconate titanate ceramics, rare-earth magnetostrictive alloys, and high-frequency coaxial cabling. Single-source vulnerability persists for 25 MHz immersion probes rated to 300-meter subsea depths. Distribution runs through authorized NDT equipment distributors and direct OEM relationships with asset integrity managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from calibration certification and predictive analytics subscriptions expands faster than hardware unit sales, repositioning the market around recurring-revenue capture. Digital twin integration and automated defect classification software layers now drive margin expansion beyond transactional gauge procurement.
For Market Incumbents: Entrench position through backward integration into piezoceramic wafer production and captive calibration laboratory networks. Electromagnetic acoustic transducer substitution above 400°C threatens conventional piezoelectric gauge demand; defend by acquiring EMAT technology licenses. Certification investment in GB/T 11344 and NMPA pathways secures China market access against regional challengers.
For New Entrants and Emerging Players: Pursue unmanned underwater vehicle probe integration as the most penetrable white-space segment, where miniaturized 25 MHz immersion transducers face limited qualified suppliers. Target Norway and United Kingdom subsea robotics manufacturers with co-development partnerships. Bundle hardware with cloud-based thickness data platforms to differentiate from established handheld vendors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed NDT service contractors consolidating multi-site inspection contracts under asset integrity managers. Five-to-ten year viability hinges on software subscription attach rates outpacing hardware commoditization. Watch for Bureau of Ocean Energy Management lease stipulation expansion as the signal indicating offshore wind infrastructure inspection demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piezoceramic Production | Captive supply of lead zirconate titanate wafers insulates margin from Japanese and German foundry pricing power. |
| Calibration Service Contract Expansion | Multi-year maintenance agreements with Rotterdam-Antwerp refineries convert transactional sales into recurring revenue streams. |
| Digital Twin Platform Integration | Wireless thickness data feeds predictive corrosion models, creating software subscription revenue alongside hardware. |
| Unmanned Underwater Vehicle Probe Development | 25 MHz miniaturized immersion probes address Bureau of Ocean Energy Management mandated subsea structural surveys. |
| GB/T 11344 Certification Investment | NMPA registration pathways unlock Sinopec and PetroChina procurement channels for imported gauge suppliers. |
Research Methodology
A standing panel of asset integrity managers, NDT contractor operations directors, and refinery mechanical integrity engineers provided ongoing calibration against field inspection workflows. Primary interviews with ultrasonic technician training program administrators and piezoceramic transducer R&D heads combined with secondary validation from API 510 filing databases, ASME conference proceedings, and FERC pipeline safety enforcement records. Bottom-up unit demand estimates from petrochemical capacity expansion projects triangulated against top-down instrumentation spend data from integrated oil company capital expenditure disclosures.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling across product type, end-use vertical, technology architecture, and application workflow. CAGRs derived from regression analysis of historical replacement cycle compression against regulatory interval tightening. Forecast inputs incorporated Bureau of Ocean Energy Management lease stipulation adoption curves and GB/T 11344 contractor certification expansion rates.
Sensitivities concentrate around electromagnetic acoustic transducer substitution velocity in high-temperature boiler applications and phased array technician certification scarcity constraining inspection contractor scaling. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
LAMEA Semiconductor Metrology and Inspection Market
Test and Measurement
Uniaxial Tester Market
Test and Measurement
Fluorometers Market
Test and Measurement
Global Bench Scale Market
Test and Measurement
Laser Interferometer Market
Test and Measurement
LTE Testing Equipment Market
Test and Measurement
Electrical Test Equipment Market
Test and Measurement
Latin America Measurement and Test Equipment Market
Test and Measurement
EMC Testing Market
Test and Measurement
Liquid Immersion Cooling Fluid Compatibility Test Equipment Market
Test and Measurement
Asia-Pacific Nondestructive Testing Equipment Market
Test and Measurement
Radiation Tester Market
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
Global Nondestructive Testing Equipment Market