
 Pin and Sleeve Devices Market | 2026-2036
Pin and Sleeve Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pin and Sleeve Devices Market Intelligence
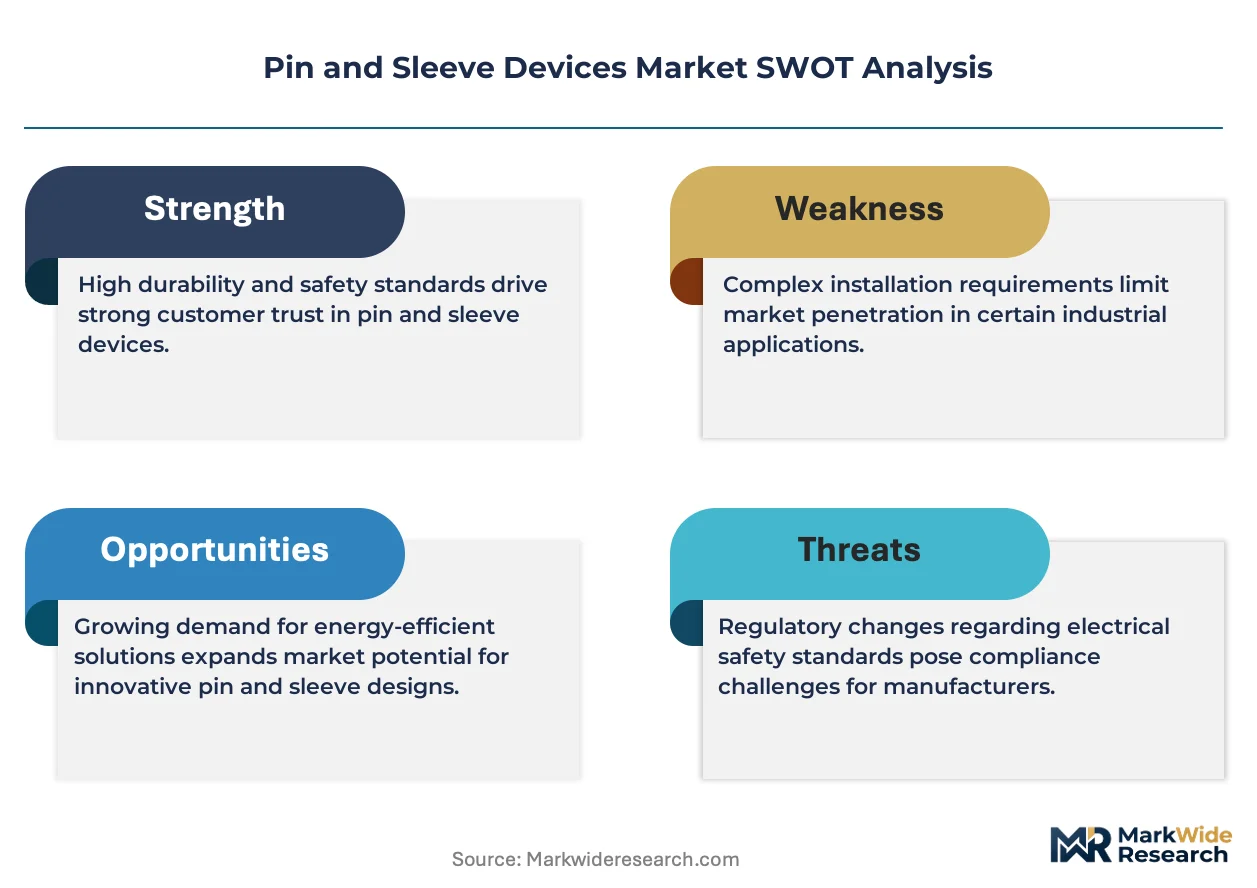
Modular power distribution architecture is tilting pin and sleeve device design toward interchangeable, tool-free configurations that slash installation time in field deployments. Eaton Corporation leverages extensive vertical integration across its electrical portfolio to control component quality from contact alloys to housings. Schneider Electric anchors its position through deep channel partnerships with electrical distributors across North America and Europe. Hubbell Incorporated specializes in severe-duty variants that command premium positioning in offshore and mining environments.
Pin and sleeve devices are mechanically keyed, color-coded electrical connectors built to IEC 60309 standards, rated from 16A to 125A and up to 1000V, designed to prevent mismating across voltage and frequency configurations in industrial temporary power applications. Heavy-Duty Connectors dominate value capture due to their irreplaceable role in high-amperage manufacturing and port operations where downtime costs dwarf hardware premiums. IP Rated technology leads growth trajectory as outdoor events and marine applications face escalating exposure to salt spray, dust ingress, and submersion risks that degrade standard connectors within months.
IEC 60309 governs dimensional and performance baselines globally, while UL 1686 and CSA C22.2 shape North American market access through distinct pin configurations and testing protocols. OSHA workplace safety mandates and NFPA 70 National Electrical Code provisions drive replacement cycles in US manufacturing facilities by mandating visible disconnect and ground-fault protection. Stakeholders must monitor evolving harmonization gaps between IEC and North American standards as modular construction and cross-border equipment leasing blur traditional regulatory boundaries.
Market Dynamics
Modular construction methods and cross-border equipment leasing are dissolving traditional regulatory boundaries, forcing manufacturers to engineer pin and sleeve devices that satisfy simultaneous IEC 60309, UL 1686, and CSA C22.2 certifications without hardware variation.
Growth Catalysts
- OSHA workplace safety mandates:US manufacturing facilities face mandatory replacement cycles driven by visible disconnect and ground-fault protection requirements. These provisions accelerate hardware turnover in heavy-industrial settings.
- Port electrification:Container terminals and ship-to-shore power systems generate concentrated demand for high-amperage connectors rated above 63A. Marine applications now specify IP67 as baseline ingress protection.
- Aluminum contact alloys:Advanced metallurgy reduces weight and improves conductivity in severe-duty variants. Mining and offshore operators specify these materials for corrosion resistance in salt-spray environments.
Market Restraints
- Copper price volatility:Contact material costs fluctuate with commodity markets, compressing margins on standard-duty products where buyers resist pass-through pricing.
- German supply concentration:MENNEKES Elektrotechnik GmbH & Co. KG anchors significant manufacturing capacity in a single geography, creating vulnerability to regional logistics disruptions or energy cost spikes.
- IEC-UL harmonization gaps:Dimensional and testing protocol misalignment forces redundant certification expenses, particularly burdening mid-cap manufacturers lacking dedicated compliance teams.
Strategic Opportunities
- India industrial corridor expansion:Dedicated freight corridors and smart city infrastructure projects under CEA guidelines create demand for standardized temporary power distribution in construction phases.
- Renewable energy integration:Solar farm commissioning and wind turbine maintenance require portable, tool-free connection systems that slash installation time in remote locations.
- EU Green Deal procurement standards:Public infrastructure tenders increasingly specify circular design criteria and extended producer responsibility, favoring suppliers with modular, repairable architectures.
Industry Challenges
- IEC 60309-2 certification timelines:Extended testing protocols for current-carrying capacity and mechanical endurance delay product launches, particularly for multi-voltage keyed variants.
- Legacy system integration:Industrial facilities operating pre-2000 electrical infrastructure require adapter configurations that increase BOM complexity and field failure risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pin and Sleeve Devices Market |
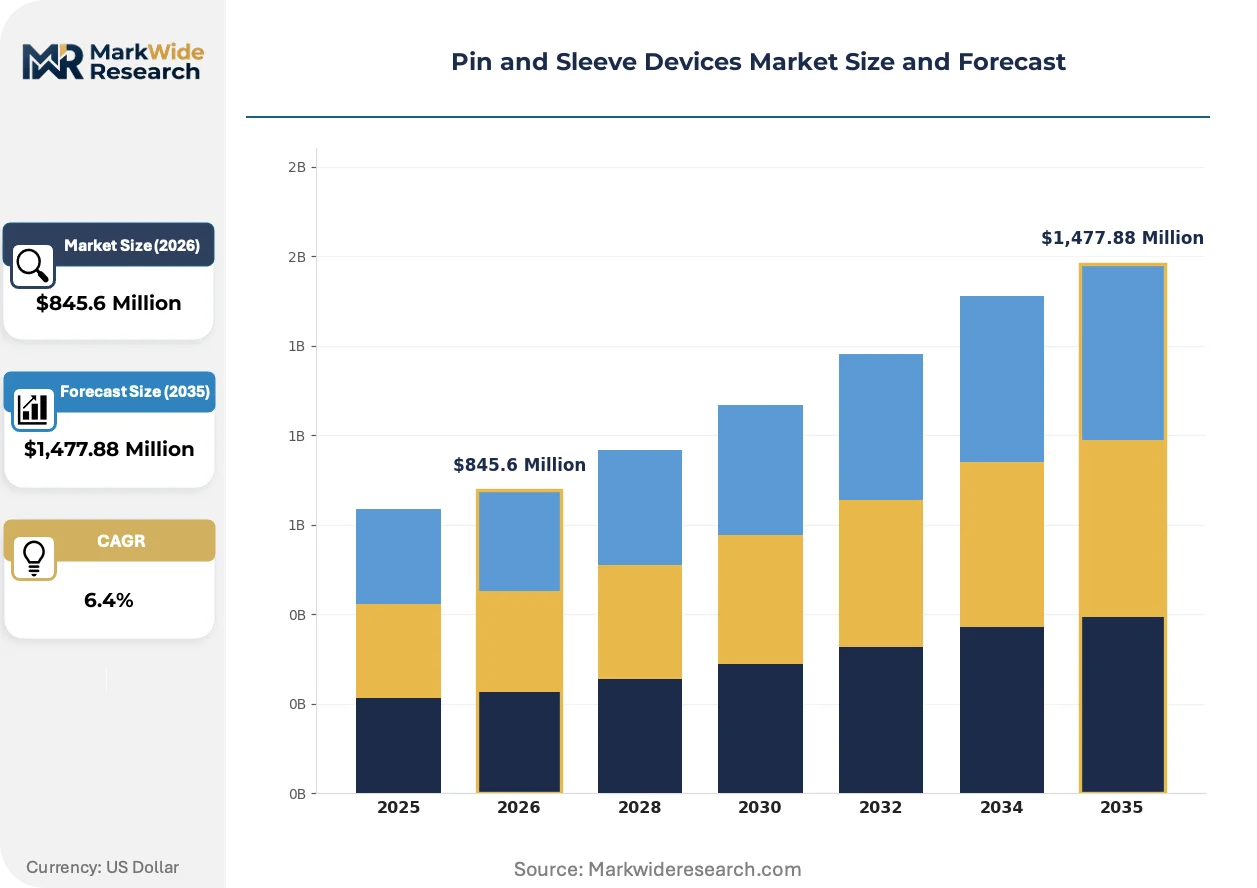
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,477.88 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Connectors, Industrial Plugs, Power Inlets, Locking Receptacles Application: Construction Sites, Outdoor Events, Manufacturing Facilities, Marine Applications End User: Event Organizers, Industrial Manufacturers, Electrical Contractors, Transportation Sector Technology: IP Rated, Non-IP Rated, Weather Resistant, Quick Connect |
| Companies Covered | ABB Ltd., Eaton Corporation, Schneider Electric, Emerson Electric, Amphenol Corporation, Meltric Corporation, Walther Electric, Hubbell Incorporated, MENNEKES Elektrotechnik GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pin and Sleeve Devices Market Strategic Shifts & Innovations
Smart connectivity features and predictive maintenance capabilities are migrating from adjacent electrical equipment categories into pin and sleeve device architectures, redefining value propositions beyond physical durability.
Integrated RFID and NFC tagging is digitizing asset tracking and inspection logging across rental equipment fleets. Construction and event management firms scan connector histories to verify test dates and duty cycles. This capability compresses equipment turnaround times and enables usage-based billing models previously impractical with passive hardware.
REACH substance restrictions and RoHS recast directives are phasing cadmium and hexavalent chromium from plating processes. European manufacturers reformulate contact surface treatments to maintain wear resistance under reduced coating thickness. Industrial buyers in Germany and France now specify compliance documentation as a procurement gate, displacing non-conforming Asian suppliers from premium tenders.
Equipment-as-a-service contracts are restructuring capital expenditure patterns in mining and oil & gas sectors. Rental fleet operators bundle connector replacement into comprehensive power distribution packages, shifting specification authority from project engineers to procurement departments. This concentration is visible most acutely in Australian and Canadian resource extraction regions where contractor consolidation has accelerated since 2022.
Pin and Sleeve Devices Market Segmentation
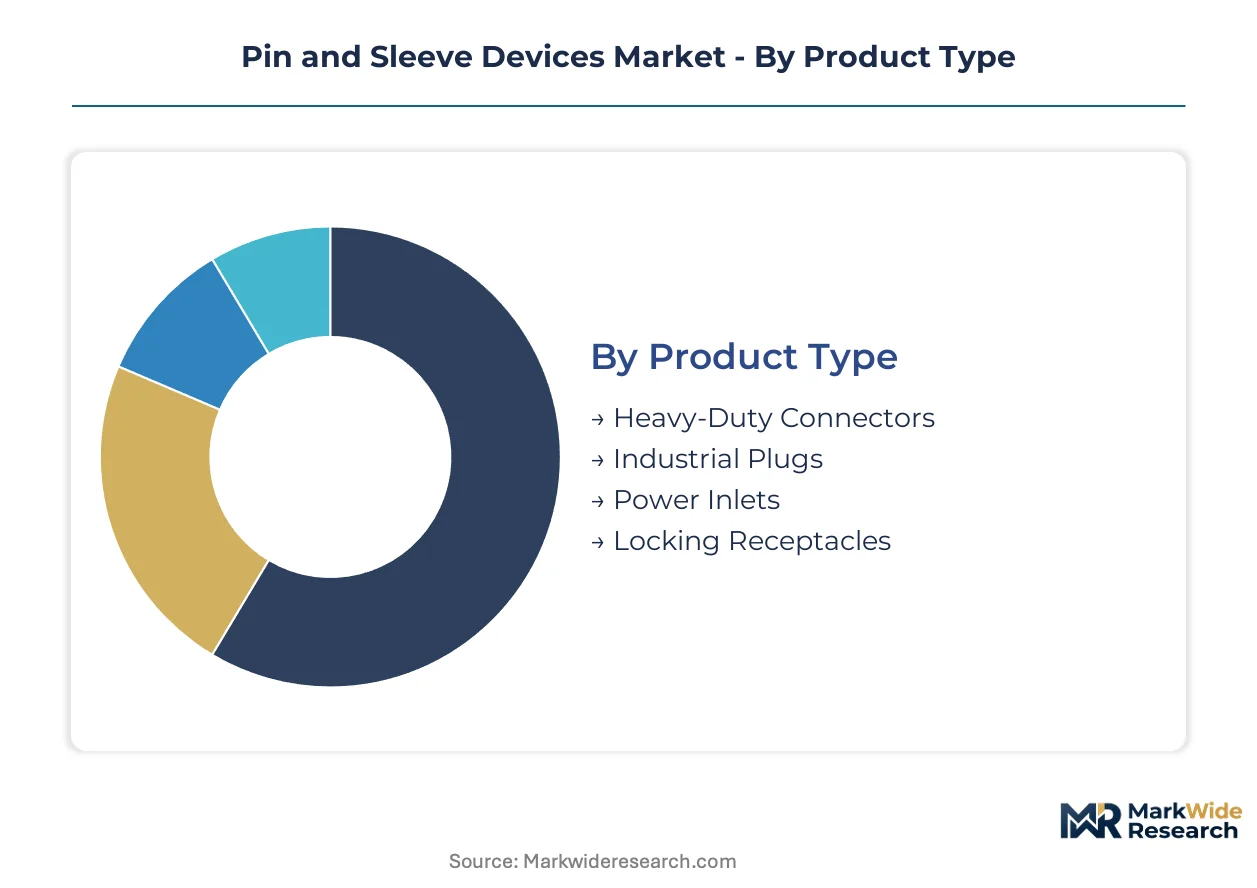
Pin and sleeve device procurement cycles vary dramatically across segments, with construction rental fleets turning inventory every 18-24 months while marine installations persist for 8-12 years. Understanding these replacement rhythms shapes inventory planning and warranty structuring for manufacturers serving mixed end-use portfolios.
Product Type:
Replacement velocity diverges sharply: construction-grade plugs cycle fastest due to physical damage, while heavy-duty connector systems in permanent industrial installations depreciate over decade-long horizons.
- Heavy-Duty Connectors:Rated 63A-125A with reinforced thermoplastic housings and silver-plated contact systems. Port terminals in Hamburg and Rotterdam specify these for ship-to-shore power, where salt spray corrosion mandates 5-year replacement schedules despite 15-year mechanical lifespans.
- Industrial Plugs:16A-32A configurations dominate temporary power distribution. German automotive plants standardize on these for production line reconfiguration, driving 30% annual churn in manufacturing procurement.
- Power Inlets:Panel-mounted receptacles for permanent installation. Data centers in Frankfurt specify these for generator hookups with 7-year depreciation cycles.
- Locking Receptacles:Twist-lock mechanisms prevent accidental disconnection. US oilfield service companies favor these for drilling rig power distribution.
Industrial plugs anchor the volume base while heavy-duty connectors gain share at the steepest rate.
Application:
Cost tier stratification separates premium marine specifications from commodity construction procurement, with outdoor events occupying a volatile middle band.
- Construction Sites:Temporary power distribution for equipment and lighting. UK infrastructure projects under the National Infrastructure Strategy drive standardized 32A distribution requirements.
- Outdoor Events:Festivals and sporting venues require rapid deployment capability. Munich's Oktoberfest generates concentrated seasonal demand for IP67-rated distribution boxes.
- Manufacturing Facilities:Permanent and semi-permanent industrial installations. Automotive plants in Stuttgart specify tool-free modular systems to minimize line downtime during reconfiguration.
- Marine Applications:Ship-to-shore power and offshore platforms. North Sea wind farms specify these for service vessel connections, with salt spray resistance commanding 3x construction-grade pricing.
Manufacturing facilities generate the steadiest procurement flow while marine applications expand most quickly on port electrification mandates.
End User:
Customer type determines specification authority, with electrical contractors controlling tactical purchasing and industrial manufacturers dictating long-term standards.
- Event Organizers:Rental-dependent procurement with seasonal concentration. Summer music festivals in France drive Q2-Q3 demand spikes for 16A distribution systems.
- Industrial Manufacturers:Standards-driven volume procurement. German automotive OEMs specify MENNEKES-compatible keying across supplier networks.
- Electrical Contractors:Project-based purchasing with price sensitivity. UK contractors favor IEC 60309-2 compliance for cross-border equipment compatibility.
- Transportation Sector:Rail depots and airport ground support equipment. Deutsche Bahn maintenance facilities standardize on quick-connect variants for rolling stock.
Industrial manufacturers anchor the volume base while transportation sector procurement climbs the fastest on infrastructure modernization.
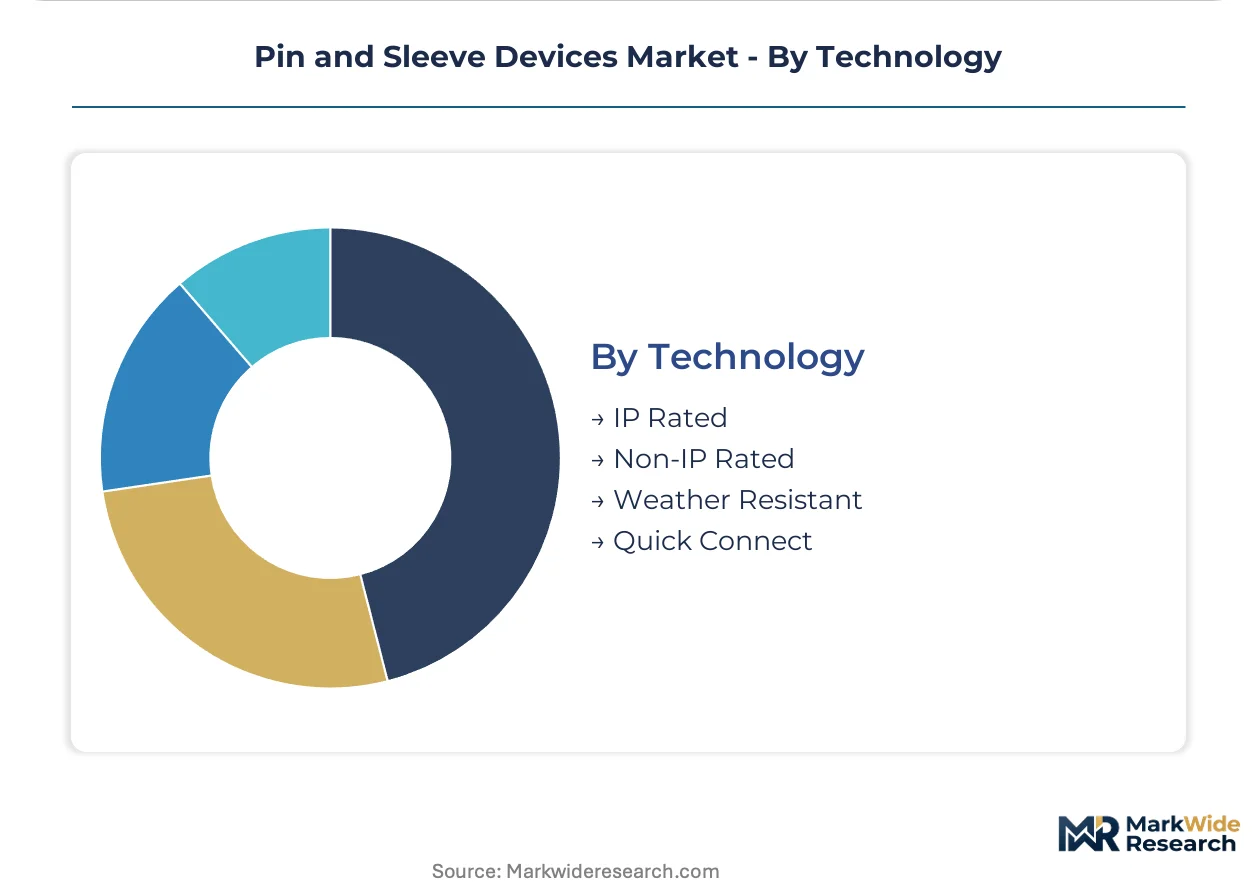
Technology:
IP rating tiering creates three distinct price bands, with ingress protection specifications now mandatory in premium tenders.
- IP Rated:Sealed against dust and water ingress per IEC 60529. IP67 variants dominate German offshore wind specifications.
- Non-IP Rated:Standard indoor installations with cost-sensitive positioning. Warehouse lighting in Poland favors these for protected environments.
- Weather Resistant:Intermediate protection for semi-exposed applications. Agricultural processing in Denmark specifies these for dairy facility washdown zones.
- Quick Connect:Tool-free installation mechanisms. Solar farm commissioning teams in Spain prioritize these for rapid array connection.
IP rated technology anchors the volume base while quick connect systems gain share at the steepest rate on renewable energy deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export pin and sleeve devices across European port networks and into North American industrial markets, with Hamburg-Rotterdam corridor traffic driving standardization pressure on IEC 60309-2 compliance documentation.
United States
OSHA workplace safety mandates accelerate replacement cycles in heavy manufacturing. The National Electrical Code provisions require visible disconnect and ground-fault protection in industrial facilities. Houston petrochemical complexes specify severe-duty connectors for maintenance turnaround operations.
Germany
Automotive OEM procurement standardizes on tool-free modular systems for production line reconfiguration. EU Green Deal procurement criteria favor circular design and extended producer responsibility. Stuttgart manufacturing clusters drive 30% annual churn in industrial plug procurement.
China
Dual carbon goals and port electrification programs expand demand for high-amperage ship-to-shore connectors. GB standards alignment with IEC 60309 facilitates export manufacturing. Yangtze River Delta port terminals specify IP67-rated distribution for container handling equipment.
India
Dedicated freight corridors and smart city infrastructure under CEA guidelines create standardized temporary power demand. BIS certification harmonization with IEC standards reduces import friction. Gujarat industrial corridors specify quick-connect systems for construction-phase electrification.
United Kingdom
National Infrastructure Strategy projects drive standardized 32A distribution requirements across construction sites. UKCA marking transition post-Brexit creates dual certification burdens for suppliers. Midlands manufacturing hubs specify MENNEKES-compatible keying for cross-border equipment compatibility.
Pin and Sleeve Devices Market Key Industry Players
On the supply side, the industry is moderately consolidated around electrical equipment conglomerates with captive distribution networks. Tiered competitive positioning separates premium severe-duty specialists from volume construction-grade suppliers. Three archetypes dominate: diversified electrical multinationals with backward integration into contact alloys; regional specialists with deep IEC certification expertise; and rental fleet operators bundling hardware into service contracts. Geographic expansion and portfolio diversification represent the dominant competitive vectors as manufacturers seek to offset copper price volatility through volume scale.
Among diversified electrical conglomerates, Eaton Corporation and Schneider Electric exemplify the integrated archetype with upstream control over component quality and channel partnerships across North America and Europe. MENNEKES Elektrotektrotechnik GmbH & Co. KG anchors the specialist tier with concentrated manufacturing capacity and technical authority in IEC 60309 standardization. Hubbell Incorporated occupies a position in the severe-duty segment where salt-spray resistance and mining applications command premium positioning.
| Leading Market Players |
|---|
| ABB Ltd. |
| Eaton Corporation |
| Schneider Electric |
| Emerson Electric |
| Amphenol Corporation |
| Meltric Corporation |
| Walther Electric |
| Hubbell Incorporated |
| MENNEKES Elektrotechnik GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
German contact alloy and thermoplastic housing suppliers anchor upstream concentration, concentrating margin capture in severe-duty connector tiers where salt-spray resistance and mechanical endurance justify 3x construction-grade premiums.
Pricing Analysis
Current-generation IP67-rated quick-connect systems command substantial premiums over legacy IP44 variants and prior-generation threaded housings, while next-generation smart-tagged connectors with RFID integration are testing value-based pricing models. Three-tier pricing structure across premium severe-duty, standard industrial, and economy construction levels dominates transactional flows, with certification grade and volume scale as primary differentiation drivers. Cost compression in economy construction tiers is intensifying because Asian suppliers without REACH compliance documentation are flooding spot markets. Electrical contractors exhibit highest price sensitivity, while marine operators purchasing through equipment-as-a-service contracts show least elasticity.
Supply Chain Analysis
Contract manufacturing for standard-duty housings concentrates in Chinese and Vietnamese electrical component foundries, while German and Czech Republic facilities retain captive production of high-amperage contact systems and precision keying mechanisms. Raw material flows draw from Chilean copper cathode, Chinese aluminum billet, and German engineering thermoplastic resin suppliers. Single-source vulnerability in IEC 60309-2 certification testing capacity creates bottleneck risk for multi-voltage product launches. Distribution runs through electrical distributor networks in North America and direct OEM relationships in European automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pin and sleeve devices sit at early-cycle expansion on port electrification mandates and renewable energy commissioning workflows, with IEC-UL harmonization pressure accelerating replacement demand across legacy industrial infrastructure.
For Market Incumbents: Build certification moat depth by securing simultaneous IEC 60309, UL 1686, and CSA C22.2 approvals for modular product architectures, defending against mid-cap Asian suppliers exploiting harmonization gaps. Channel control through electrical distributor exclusivity agreements anchors pricing power. Capacity addition in Indian industrial corridors captures CEA-guided infrastructure rollout demand. For New Entrants and Emerging Players: Quick-connect solar farm commissioning systems in Spain and Australian mining regions represent the most penetrable entry point, with tool-free installation value propositions displacing legacy threaded connectors. Marine aftermarket service contracts for North Sea wind farms offer second white-space target. Go-to-market through rental fleet operator partnerships bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward severe-duty specialists with captive salt-spray testing capabilities and circular design architectures qualifying for EU Green Deal procurement. Long-term viability over the analysis window hinges on modular repairability and extended producer responsibility compliance. Watch for BIS certification harmonization completion in India as inflection signal for import friction reduction.| Strategic Initiative | Industry Significance |
|---|---|
| IEC-UL-CSA Harmonization Investment | Simultaneous multi-standard certification unlocks cross-border equipment leasing demand in German port networks. |
| Smart Connectivity Integration | RFID and NFC tagging enables usage-based billing models for construction rental fleets in Munich and Rotterdam. |
| Aluminum Contact Alloy Transition | Advanced metallurgy reduces weight and improves conductivity for North Sea offshore wind service vessels. |
| India Manufacturing Footprint | CEA-guided freight corridor electrification creates localized supply advantage for Gujarat industrial projects. |
| Circular Design Architecture | Modular repairability qualifies suppliers for EU Green Deal public infrastructure tenders in Stuttgart automotive clusters. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC electrical equipment filings, and IEC standardization committee records. Primary interviews engaged plant engineers at automotive OEMs, procurement leads at port terminal operators, electrical contractor project managers, and aftermarket service heads at rental fleet operators. Secondary validation drew from OSHA enforcement databases, EU Green Deal procurement registries, and BIS certification harmonization notifications. Bottom-up demand modeling from end-use procurement cycles triangulates against top-down supply capacity assessments across German, Chinese, and Indian manufacturing hubs.
Forecast inputs span product type segmentation by amperage rating and IP tier, application segmentation across construction, marine, manufacturing, and outdoor events, and technology segmentation by quick-connect and smart-tagging adoption curves. CAGRs derive from replacement cycle velocity differentials and port electrification mandate implementation schedules. Industry-specific inputs include copper price volatility scenarios and IEC-UL harmonization timeline assumptions across the projection horizon.
Practitioners should monitor copper commodity futures, REACH substance restriction amendments, and BIS-IEC harmonization completion for early signals of margin compression or market access expansion. Quarterly review of port terminal electrification capex disclosures and CEA infrastructure tender awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Radiation Detection Device Market
Detection and Regulation Devices
Water Leak Detector Market
Detection and Regulation Devices
Digital Vacuum Regulators Market
Detection and Regulation Devices
Compliance Monitoring Devices Market
Detection and Regulation Devices
Global Inflation Device Market
Detection and Regulation Devices
Superconducting Detector Market
Detection and Regulation Devices
Hitoxic Gas Detector Market
Detection and Regulation Devices
Radiometric Detectors Market
Detection and Regulation Devices
Microwave Leakage Detector Market
Detection and Regulation Devices
Leak Detection Equipment Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Frequency Counter Market
Detection and Regulation Devices
Positive Temperature Coefficient (PTC) Thermistor Market
Detection and Regulation Devices
Pyro Electric Infrared Detectors Market
Detection and Regulation Devices
Electronic Article Surveillance Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market