
 Global Gas Detection System Market | 2026-2036
Global Gas Detection System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gas Detection System Market Foresight
Chemical plant instrumentation is restructuring demand patterns across the Global Gas Detection System Market as process safety budgets expand. Honeywell International Inc. leverages its distributed control system integration to bundle gas detection into broader automation contracts. Drägerwerk AG & Co KGaA anchors European industrial safety channels with specialized breathing apparatus and detection combinations. MSA Safety Incorporated competes through channel density in North American energy and construction verticals.
A gas detection system comprises sensor arrays, signal processing units, and alarm interfaces engineered to identify concentrations of toxic, combustible, or oxygen-deficient atmospheres, typically calibrated to parts-per-million sensitivity for hydrogen sulfide and lower explosive limit percentages for hydrocarbons. Fixed systems dominate capital expenditure in oilfield operations and chemical plants where continuous perimeter monitoring replaces manual survey routines, while wireless sensors represent the fastest-expanding technology segment as battery-powered mesh networks eliminate cabling costs in remote tank farms and temporary construction sites. Portable detectors sustain margin pools in mining operations and confined space entry applications where personal protective equipment mandates require individual unit ownership.
OSHA process safety management standards and EPA risk management plan requirements shape product specifications and replacement cycles for United States installations, while EU ATEX directives and IECEx certification schemes govern equipment approval for hazardous area deployment across European and Asia-Pacific export markets. The EU AI Act introduces emerging compliance dimensions for intelligent detection systems incorporating machine-learning-based alarm prioritization. Stakeholders must monitor regulatory divergence between regional certification bodies as wireless connectivity and cloud-based analytics complicate traditional equipment approval pathways.
Market Dynamics
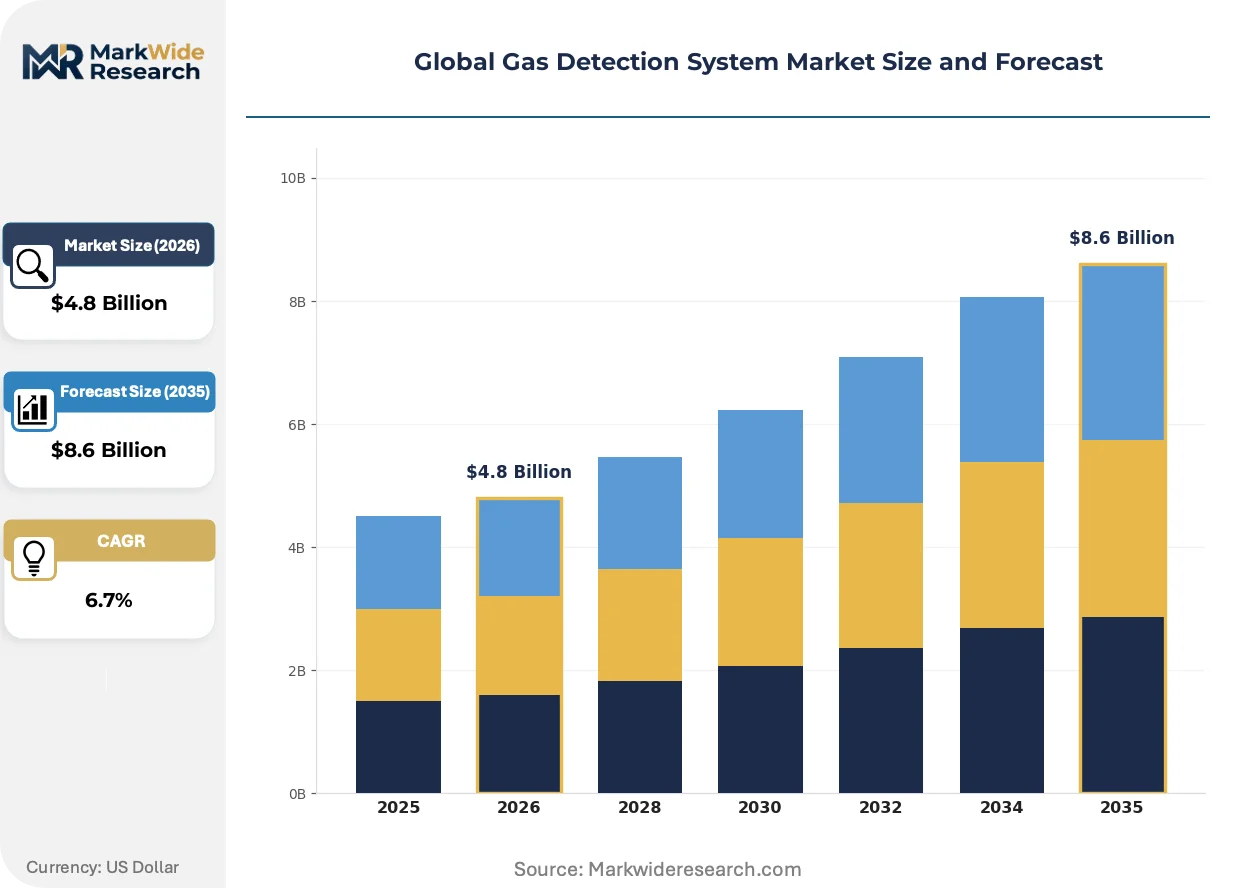
Wireless mesh architectures and cloud-native analytics are compressing replacement cycles for legacy fixed installations while forcing sensor manufacturers to recalibrate hardware margins against recurring software revenue streams.
Growth Catalysts
- OSHA Process Safety Management:United States chemical facilities face mandatory risk assessments for highly hazardous chemicals, driving continuous monitoring upgrades across Texas and Louisiana refining clusters.
- Battery-powered mesh networks:Wireless sensor deployments eliminate trenching and cabling costs in remote tank farms, accelerating adoption across Permian Basin oilfield operations.
- Hydrogen economy buildout:Electrolyzer installations and hydrogen pipelines in Germany and the Netherlands require specialized detection for odorless, highly flammable H2 leaks at low concentrations.
Market Restraints
- Palladium and platinum price volatility:Catalytic bead sensors depend on precious metal coatings, exposing manufacturers to South African and Russian supply concentration risks.
- EU ATEX certification timelines:Extended approval cycles for wireless devices with integrated batteries delay product launches by 12-18 months versus traditional wired equivalents.
- Electrochemical sensor drift:Calibration degradation in high-humidity environments forces frequent maintenance cycles that erode total cost-of-ownership advantages.
Strategic Opportunities
- India's industrial corridor expansion:Gujarat and Maharashtra petrochemical zones lack mature fixed-system penetration, creating first-mover advantages for integrated safety providers.
- EU AI Act compliance:Machine-learning-based alarm prioritization systems qualify as high-risk AI, mandating documentation standards that favor established vendors with regulatory affairs capabilities.
- Edge-to-cloud convergence:On-device inference combined with centralized analytics platforms enables predictive maintenance contracts that transform capital sales into recurring revenue.
Industry Challenges
- IECEx certification fragmentation:Divergent national interpretations of intrinsic safety standards force redundant testing for Australian, Brazilian, and Canadian hazardous area approvals.
- Legacy system integration:4-20mA analog outputs from 1990s-era installations resist digital retrofit without costly signal converters or full rip-and-replace programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gas Detection System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Systems, Wireless Sensors, Multi-gas Monitors, Single-gas Monitors Technology: Electrochemical, Infrared, Catalytic Bead, Semiconductor, Photoionization Detectors Application: Oilfield Operations, Chemical Plants, Mining Operations, Confined Space Entry, Fire Prevention End User: Energy Producers, Manufacturing Plants, Mining Contractors, Public Safety Agencies, Construction Firms |
| Companies Covered | Honeywell International Inc., Drägerwerk AG & Co KGaA, MSA Safety Incorporated, Emerson Electric Co., Industrial Scientific Corporation, Teledyne Technologies Incorporated, Riken Keiki, Crowcon Detection Instruments Ltd., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gas Detection System Market Shifts & Advancements
Photonic and solid-state sensing modalities are displacing electrochemical and catalytic technologies in high-value applications, while regulatory pressure on false alarm rates accelerates investment in multi-sensor fusion algorithms.
Photoacoustic spectroscopy is unifying methane detection capabilities across pipeline integrity and landfill monitoring applications. Midstream operators in the United States and Western Europe are piloting tunable diode laser systems for ppb-level sensitivity. This convergence is unifying previously separate product lines into single-platform architectures that compress vendor R&D spreads.
The EU AI Act imposes conformity assessment requirements on intelligent gas detection systems that employ machine learning for alarm validation. Industrial facilities must maintain technical documentation and human oversight protocols for automated safety decisions. German chemical plants and Dutch refining complexes are front-running compliance through early vendor partnerships.
Buyer consolidation among integrated energy majors is compressing vendor lists and demanding outcome-based service level agreements. Supermajors now specify uptime guarantees rather than equipment procurement, shifting risk to detection system providers. This restructuring is most advanced in the United States Gulf Coast and North Sea production basins where operator consolidation has concentrated purchasing power.
Global Gas Detection System Market Segmentation
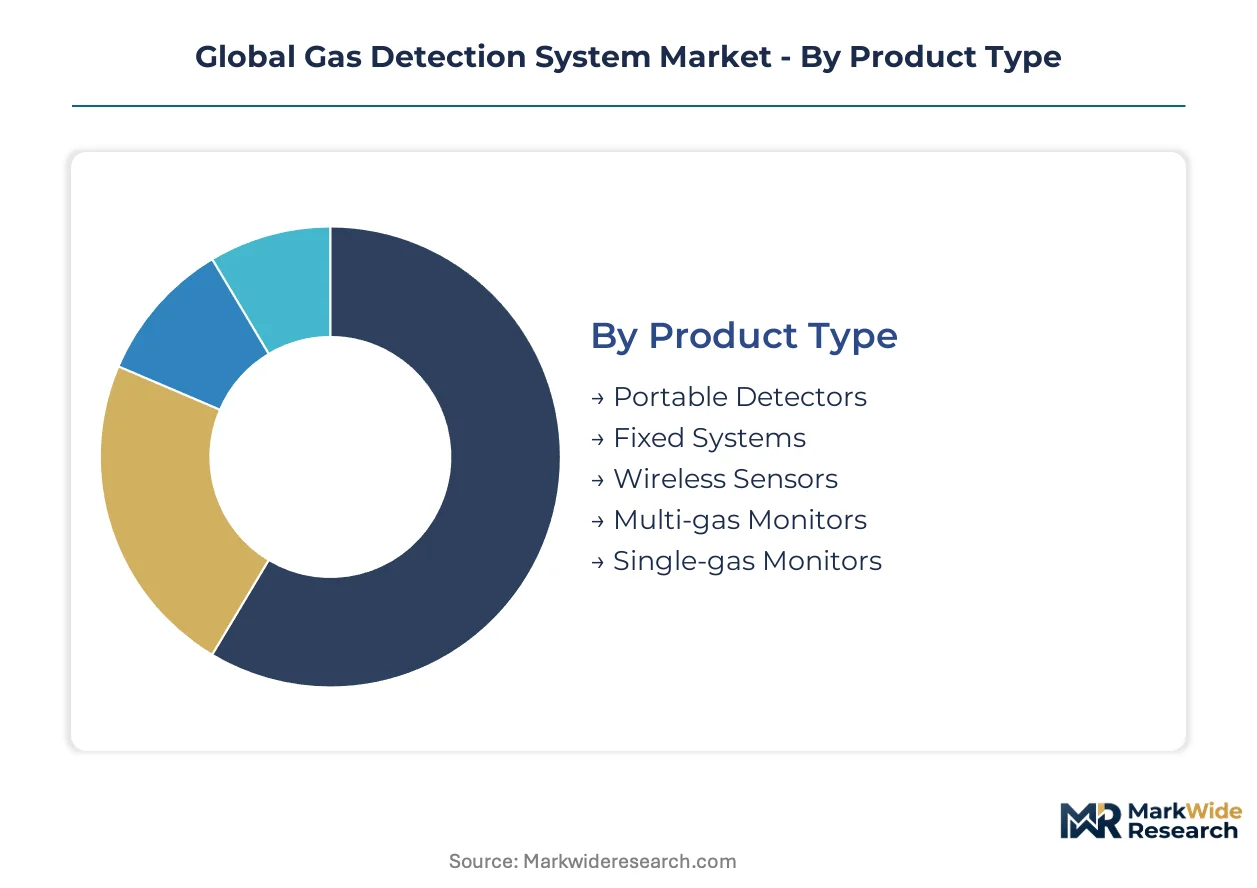
Gas detection procurement patterns diverge sharply between capital-intensive fixed installations and recurring portable device purchases. Understanding these segment boundaries clarifies where hardware margins concentrate versus where software and service revenue pools form.
Product Type:
Buyer budgets separate between facilities making multi-year capital commitments and operations requiring disposable personal units.
- Fixed Systems:Permanently installed sensor arrays with centralized control interfaces dominate chemical plant and refinery capital expenditure. United States Gulf Coast petrochemical corridor expansion sustains procurement cycles for perimeter monitoring networks.
- Portable Detectors:Handheld units with rechargeable power supplies serve confined space entry and maintenance turnarounds. Mining contractors in Australia and Canada mandate individual ownership per worker, creating recurring replacement demand.
- Wireless Sensors:Battery-powered mesh nodes eliminate cabling infrastructure in remote tank farms. Permian Basin oilfield operators deploy these for temporary wellpad monitoring.
- Multi-gas Monitors:Simultaneous detection of four to six gas species suits complex industrial environments.
- Single-gas Monitors:Dedicated hydrogen sulfide or carbon monoxide units serve utility and wastewater segments.
Volume sits with Fixed Systems; growth tilts toward Wireless Sensors.
Technology:
Sensor selection hinges on target gas chemistry, required sensitivity, and ambient interference tolerance.
- Infrared:Non-dispersive absorption spectroscopy measures hydrocarbon concentrations without oxygen dependence. German chemical plants favor these for solvent vapor monitoring under EU ATEX requirements.
- Electrochemical:Amperometric cells with liquid electrolytes detect toxic gases at parts-per-million thresholds. High-humidity degradation in Southeast Asian facilities accelerates replacement frequency.
- Catalytic Bead:Precious metal-coated filaments combust hydrocarbons to measure lower explosive limit percentages. Palladium price volatility from South African supply concentration threatens manufacturing cost stability.
- Photoionization Detectors:Ultraviolet lamp ionization captures volatile organic compounds at sub-ppm levels.
- Semiconductor:Metal oxide films respond to reducing gases through conductivity changes.
Electrochemical sensors dominate installed base; Infrared platforms are climbing the fastest on chemical plant upgrade cycles.
Application:
Regulatory exposure and incident liability shape instrumentation density across operational environments.
- Chemical Plants:Continuous monitoring of process zones for toxic releases and combustible vapor accumulation. OSHA process safety management mandates in Texas and Louisiana drive fixed system deployment.
- Oilfield Operations:Drilling rigs and production facilities require hydrogen sulfide detection at wellheads. North Sea platforms specify redundant sensor architectures under UK Health and Safety Executive guidelines.
- Mining Operations:Underground coal and hardrock extraction demands methane and carbon monoxide surveillance.
- Confined Space Entry:Pre-entry atmospheric testing protocols sustain portable detector procurement.
- Fire Prevention:Early smoke and combustion gas detection in warehousing and data centers.
Chemical Plants anchor revenue concentration; Confined Space Entry shows steepest expansion trajectory on construction safety enforcement.
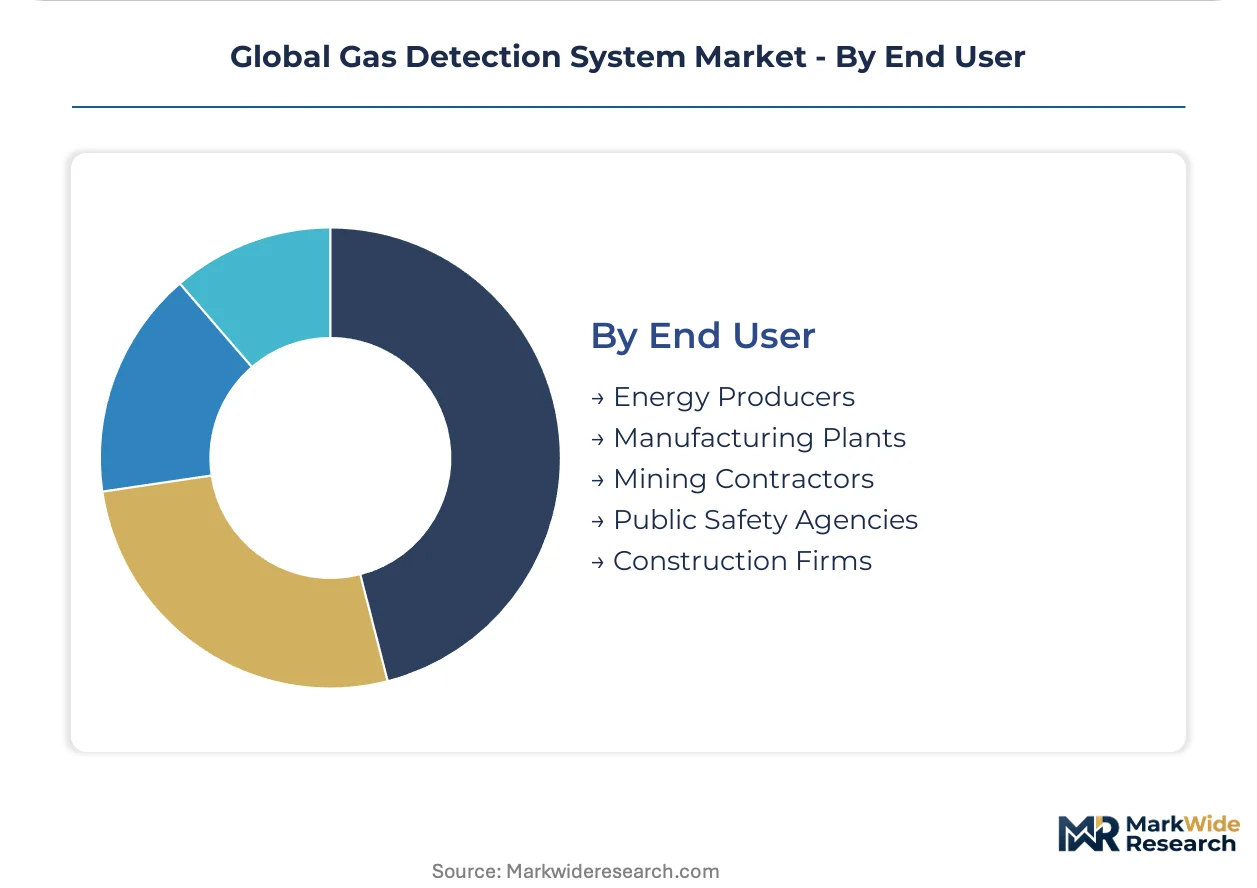
End User:
Procurement sophistication ranges from integrated safety management systems to spot-market equipment rental.
- Energy Producers:Integrated majors specify uptime-based service agreements rather than equipment purchase. Supermajor consolidation in the United States Gulf Coast compresses vendor lists.
- Manufacturing Plants:Automotive and electronics facilities deploy solvent vapor detection for worker protection. German automotive clusters under EU AI Act compliance timelines pilot machine-learning alarm validation.
- Mining Contractors:Project-based procurement favors rental and lease arrangements over capital ownership.
- Public Safety Agencies:Fire departments and emergency response units require ruggedized portable units.
- Construction Firms:Temporary site requirements drive wireless sensor adoption for excavation and tunneling.
Energy Producers command premium pricing; Manufacturing Plants are gaining share fastest on industrial automation integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones along the United States Gulf Coast petrochemical corridor concentrate fixed-system procurement through tax-advantaged infrastructure buildouts. These zones anchor capital deployment for continuous monitoring networks serving refinery expansion and LNG export terminal construction.
United States
Texas and Louisiana refining clusters drive fixed-system upgrades under OSHA process safety management mandates. EPA risk management plan requirements tighten compliance thresholds for toxic gas monitoring. The Houston Ship Channel and Lake Charles industrial zones sustain multi-year instrumentation cycles for hydrogen sulfide and hydrocarbon detection.
Germany
Electrolyzer installations and hydrogen pipeline networks in the Ruhr and Bavaria regions require specialized H2 leak detection at low concentrations. EU ATEX directives and the EU AI Act impose conformity assessments on machine-learning alarm systems. German chemical plants in Ludwigshafen and Leverkusen front-run compliance through early vendor partnerships.
China
Coal chemical complexes and refinery expansion in Ningxia and Shandong provinces sustain demand for catalytic bead and infrared sensor arrays. GB standards and MEE environmental enforcement tighten emission monitoring requirements. The Yangtze River Delta petrochemical belt concentrates procurement for integrated safety-automation systems.
India
Gujarat and Maharashtra petrochemical zones lack mature fixed-system penetration, creating first-mover opportunities for integrated safety providers. CEA electrical safety regulations and state-level industrial safety mandates accelerate formalization of gas monitoring protocols. The Dahej and Mundra special economic zones anchor greenfield plant construction with bundled detection system contracts.
Netherlands
Rotterdam port industrial complexes and hydrogen import terminal projects require redundant sensor architectures for odorless fuel leaks. EU ATEX certification timelines delay wireless device launches, favoring established vendors with regulatory affairs capabilities. The Port of Rotterdam and Chemelot chemical cluster drive specification of photoacoustic spectroscopy for pipeline integrity monitoring.
Global Gas Detection System Market Competitive Landscape
Top-tier vendors anchor premium-tier automation integration, while mid-scale specialists occupy technology-specific niches. The market structures around bundled safety-automation contracts, standalone instrument supply, and outcome-based service agreements. Three archetypes dominate: integrated industrial conglomerates with distributed control system platforms, dedicated safety technology houses with breathing apparatus combinations, and sensor-focused specialists with wireless mesh expertise. Competitive moves concentrate on vertical integration into software analytics and geographic expansion through local certification partnerships.
Among Germany-based safety technology houses, Drägerwerk AG & Co KGaA exemplifies the breathing apparatus and detection combination archetype. United States industrial conglomerates Honeywell International Inc. and Emerson Electric Co. occupy positions anchoring automation-integrated safety platforms. These three represent the tier commanding premium positioning through regulatory compliance depth and control system bundling capability.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Drägerwerk AG & Co KGaA |
| MSA Safety Incorporated |
| Emerson Electric Co. |
| Industrial Scientific Corporation |
| Teledyne Technologies Incorporated |
| Riken Keiki |
| Crowcon Detection Instruments Ltd. |
| Siemens AG |
| Others |
Supply & Pricing Matrix
Palladium spot price volatility on the London Metal Exchange cascades through catalytic bead sensor manufacturing into tiered pricing structures, with premium tiers absorbing precious metal cost spikes while economy segments face margin compression.
Pricing Analysis
Lead-time-driven pricing stratification separates expedited delivery premiums from spot inventory discounts across fixed system procurement. Three-tier pricing structure across premium, standard, and economy levels dominates, with ATEX/IECEx certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in the economy tier is intensifying because Chinese sensor manufacturers are expanding export capacity. Mining contractors in Australia exhibit highest price sensitivity, while United States Gulf Coast supermajors prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke patterns for spare sensor modules and calibration gases. Manufacturing concentrates in Germany, China, and the United States, with production drawing from South African palladium, Japanese semiconductor substrates, and specialty electrolytes from Belgium. Single-source vulnerability in catalytic bead coatings threatens continuity. Distribution runs through authorized service networks rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
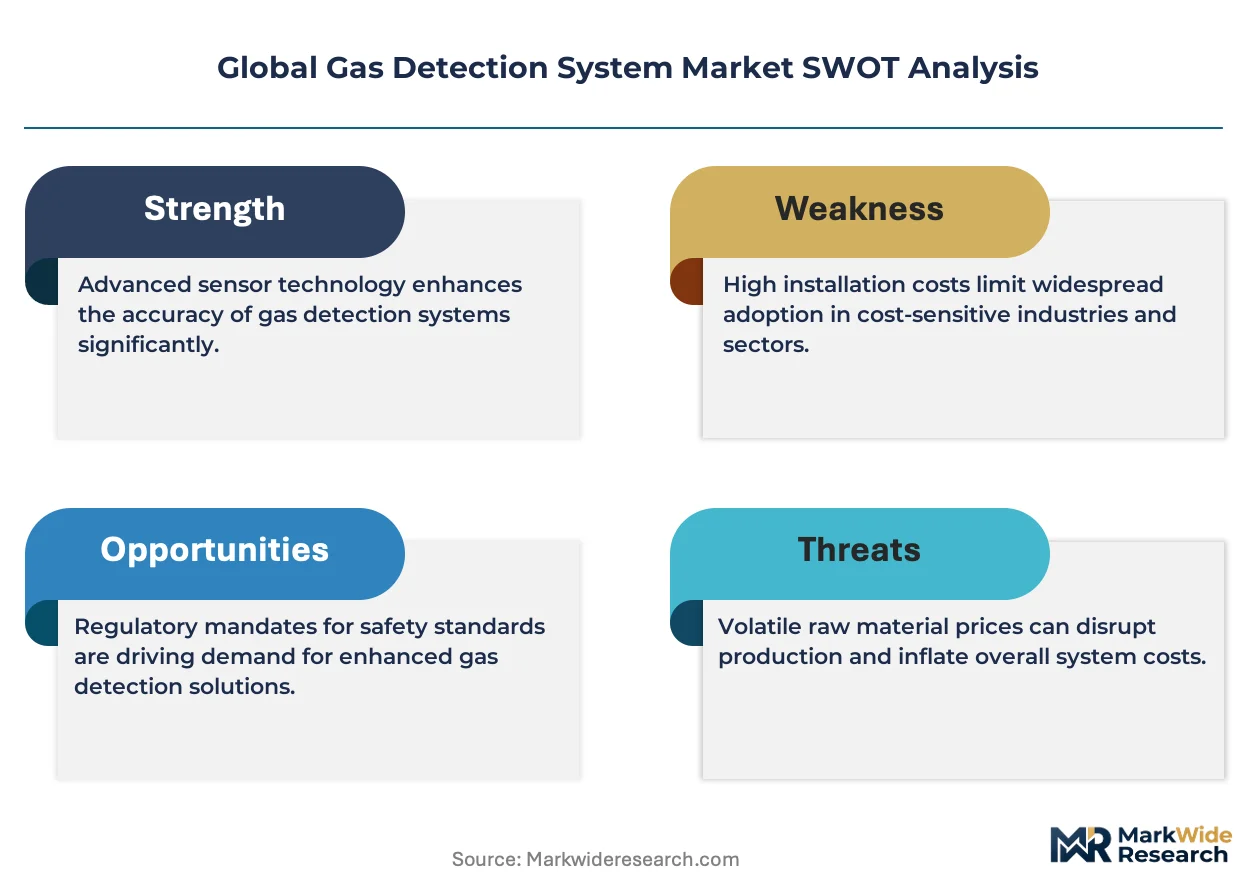
Analyst Recommendations
Precious metal coating capacity constraints prop pricing power for established vendors with captive supply relationships.
For Market Incumbents: Cement market position through backward integration into palladium recovery and refining operations, and through exclusive distribution partnerships with Permian Basin oilfield service companies. Solid-state sensor substitution threatens electrochemical installed base. Certification investment in EU AI Act compliance documentation centers on Ludwigshafen and Leverkusen anchor accounts. For New Entrants and Emerging Players: EU AI Act in Germany opens a window for machine-learning alarm validation specialists to capture retrofit demand from BASF and Bayer facilities. India's Gujarat petrochemical corridor lacks mature fixed-system penetration, creating first-mover advantages for wireless mesh specialists. Go-to-market through bundled safety-automation contracts with Indian EPC contractors avoids direct competition with Honeywell and Dräger channel density. For Investors and Strategic Acquirers: Distressed-cycle entries favor sensor-focused specialists with wireless mesh expertise in the Netherlands, where hydrogen economy buildout is accelerating detection procurement. Five-to-ten year viability hinges on photonic sensing platform transition. Monitor palladium price inflection as signal for catalytic bead manufacturer margin stress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precious Metal Recovery | Captive palladium supply from South African mining partnerships insulates Drägerwerk and Honeywell from LME price spikes. |
| EU AI Act Compliance Documentation | Technical file preparation for machine-learning alarm systems qualifies German chemical plants for early vendor preference. |
| Wireless Mesh Network Deployment | Battery-powered sensor elimination of trenching costs accelerates Permian Basin wellpad adoption. |
| Hydrogen Economy Detection Platform | Specialized H2 leak sensitivity at 4% LEL captures Rotterdam and Bavaria electrolyzer installation demand. |
| Outcome-Based Service Level Agreements | Uptime guarantees shift operational risk to vendors in United States Gulf Coast supermajor contracts. |
Research Methodology
Multi-period observation of OSHA enforcement actions, EU ATEX certification timelines, and palladium price movements anchored the trend analysis, supplemented by interviews with plant safety managers at Texas refineries, procurement leads at German chemical complexes, and aftermarket service heads at Singapore distribution hubs. Secondary validation drew from EPA risk management plan filings, IECEx equipment lists, SEC 10-K instrument revenue disclosures, and customs data on sensor array imports. Bottom-up channel checks and top-down industrial safety spending estimates were triangulated against fixed system installation permits.
Segment-weighting across product type, technology modality, application environment, and end-user procurement sophistication shaped the analytical framework. Deployment model splits between capital-intensive fixed installations and recurring portable purchases were modeled throughout the forecast period. CAGRs were derived from replacement cycle compression rates and hydrogen economy infrastructure buildout trajectories. Wireless sensor battery life improvements and photoacoustic spectroscopy adoption curves served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state sensing would alter the outlook if electrochemical sensor longevity improves beyond current degradation rates. Forecasts reflect documented assumptions on regulatory enforcement intensity and precious metal supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Underwater Signaling Devices Market
Detection and Regulation Devices
Semiconductor Leak Detectors Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Vapour Particle Barrier Market
Detection and Regulation Devices
Audio Signaling Devices Market
Detection and Regulation Devices
Voltage Detector Market
Detection and Regulation Devices
Handheld Optical Gas Imaging Camera Market
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market
Detection and Regulation Devices
Global Wireless Gas Detection Market
Detection and Regulation Devices
Radiometric Detectors Market
Detection and Regulation Devices
Middle East and Africa Trace Detection Market
Detection and Regulation Devices
Europe Trace Detection Market
Detection and Regulation Devices
Portable Metal Detectors Market
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market
Detection and Regulation Devices
Duct Smoke Detectors Market