
 Registering Clock Driver (RCD) Market | 2026-2036
Registering Clock Driver (RCD) Market Size, Share, and Industry Trends Forecast 2026-2036
Registering Clock Driver (RCD) Market Analytics
DDR5 memory interface migration is rewriting clock distribution architectures across server and high-performance computing platforms. Montage Technology dominates the China domestic supply chain for DDR5 RCDs through captive relationships with local memory module vendors. Texas Instruments sustains broad industrial and automotive clock driver portfolios that extend its reach beyond pure-play memory buffers. Renesas Electronics specializes in precision timing solutions for automotive ECUs, competing on AEC-Q100 qualification depth rather than raw data rate.
A Registering Clock Driver (RCD) is a buffer integrated circuit that regenerates and redistributes clock signals across multi-DIMM memory channels, typically operating at frequencies exceeding 4.8 GT/s with sub-100 femtosecond additive jitter budgets to maintain signal integrity in DDR5 subsystems. Its primary commercial purpose is to enable reliable parallel data transfer in server motherboards and enterprise storage arrays where clock skew between memory ranks would otherwise corrupt read-write operations. Crystal Oscillator-Based RCDs anchor the highest-margin tier of the product mix, serving hyperscale data centers where phase noise specifications are non-negotiable. MEMS-Based timing segments are gaining traction in automotive and industrial automation applications where vibration immunity and extended temperature ranges offset modest frequency precision trade-offs. PLL-Based architectures occupy the cost-optimized volume tier for consumer electronics and mid-range communication devices where programmable clock multiplication simplifies BOM consolidation.
FCC electromagnetic compatibility mandates shape RCD emission profiles for equipment sold into US communication infrastructure, while REACH substance restrictions in Europe constrain solder alloy and packaging material selections across the supply chain. China's GB standards for information technology equipment, administered by MIIT, impose additional jitter and eye-mask testing protocols that diverge from JEDEC baselines and create compliance segmentation. Stakeholders must monitor how DDR5-6400 and beyond specifications will tighten additive jitter requirements and whether domestic content rules in key geographies will force dual-qualified RCD sourcing strategies.
Market Dynamics
DDR5 memory interface migration is collapsing legacy clock distribution topologies as server OEMs abandon single-ended signaling for differential architectures that mandate registering clock drivers at every DIMM slot.
Growth Catalysts
- Hyperscale data center buildouts:Cloud operators in the United States are deploying DDR5-based servers at rack densities exceeding 128 DIMMs per chassis, multiplying RCD counts per motherboard.
- REACH substance restrictions:European environmental mandates are accelerating lead-free solder transitions that favor advanced packaging techniques compatible with high-pin-count RCD footprints.
- JEDEC specification ratification:The DDR5-6400 and beyond speed grades are tightening additive jitter budgets below 100 femtoseconds, mandating buffer regeneration that only RCD architectures can deliver.
Market Restraints
- Advanced substrate costs:Organic flip-chip ball grid array substrates for DDR5 RCDs consume 35-40% of packaged device cost, constraining margin expansion at volume price points.
- Foundry concentration:Taiwan-based semiconductor fabrication capacity for 40nm and below mixed-signal processes creates geographic supply vulnerability during seismic or geopolitical disruption.
- Silicon interposer alternatives:Active silicon interposers with integrated clock trees threaten discrete RCD displacement in highest-density server modules.
Strategic Opportunities
- Automotive edge computing:ADAS domain controllers in Germany and Japan are adopting DDR5 memory for sensor fusion workloads, opening RCD demand outside traditional server markets.
- India's PLI scheme:Production-linked incentives for electronics manufacturing are attracting memory module assembly that will cascade into localized RCD procurement.
- MIIT domestic content rules:China's GB standards for information technology equipment are creating dual-qualified sourcing requirements that favor captive supply chain development.
Industry Challenges
- Signal integrity simulation talent:DDR5 channel modeling requires expertise in 3D electromagnetic field solvers that remains concentrated among a handful of specialized engineering consultancies.
- AEC-Q100 automotive qualification timelines:The 12-18 month validation cycles for temperature grade 1 devices delay revenue realization from automotive design wins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Registering Clock Driver (RCD) Market |
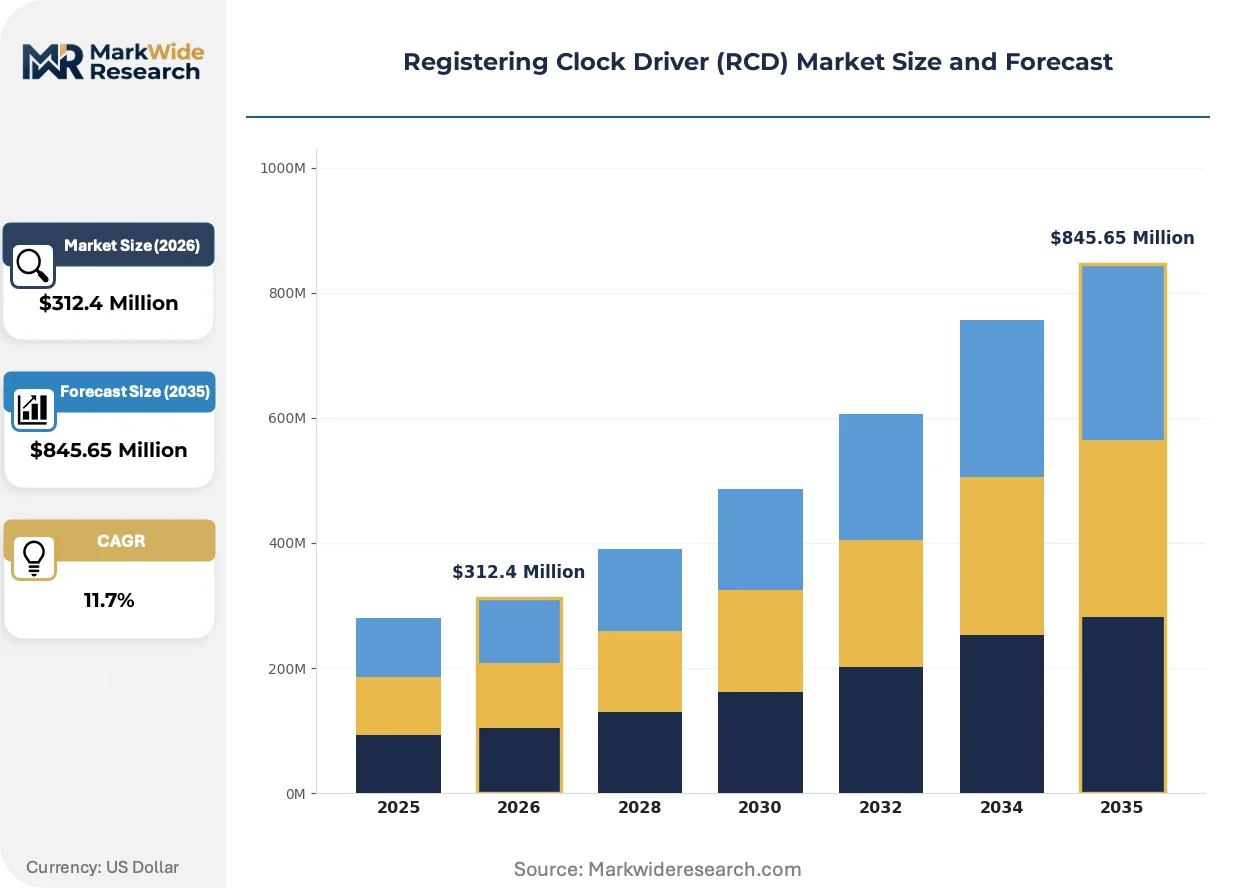
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Clock Drivers, Digital Clock Drivers, High-Speed Clock Drivers, Precision Clock Drivers Application: Consumer Electronics, Automotive Systems, Industrial Automation, Communication Devices End User: OEMs, Suppliers, Aftermarket Providers, Integrators Technology: Crystal Oscillator-Based, MEMS-Based, PLL-Based, Others |
| Companies Covered | Integrated Device Technology, STMicroelectronics, Montage Technology, Texas Instruments, Intel, Renesas Electronics, ON Semiconductor, Microchip Technology, Rambus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Registering Clock Driver (RCD) Market Evolving Landscape
Clock distribution architectures are fragmenting across three simultaneous vectors: silicon integration depth, regulatory compliance layering, and procurement model restructuring that favors direct foundry relationships over distributor channels.
Integrated voltage regulators within RCD packages are collapsing the traditional discrete power management IC companion market. Server motherboard designers at hyperscale operators are eliminating separate voltage regulator modules adjacent to DIMM slots, consolidating power delivery inside the buffer device itself. This integration is collapsing board area requirements by 15-20% while complicating thermal design rules.
China's MIIT-administered GB standards for information technology equipment are diverging from JEDEC baseline specifications on jitter measurement methodologies and eye-mask testing protocols. Module vendors serving the Chinese domestic market must maintain dual qualification streams that increase non-recurring engineering overhead. The divergence is most acute for DDR5-6400 speed grades where GB test fixtures impose stricter crosstalk penalties than international standards.
Memory module vendors are consolidating procurement relationships directly with semiconductor foundries, bypassing traditional distribution channels for high-volume RCD supply. This disintermediation compresses margin capture for authorized distributors while accelerating price discovery cycles. The shift is most visible among Taiwan-based module houses that maintain captive buffer design teams and negotiate wafer starts at foundry partners without intermediary markup.
Registering Clock Driver (RCD) Market Segmentation
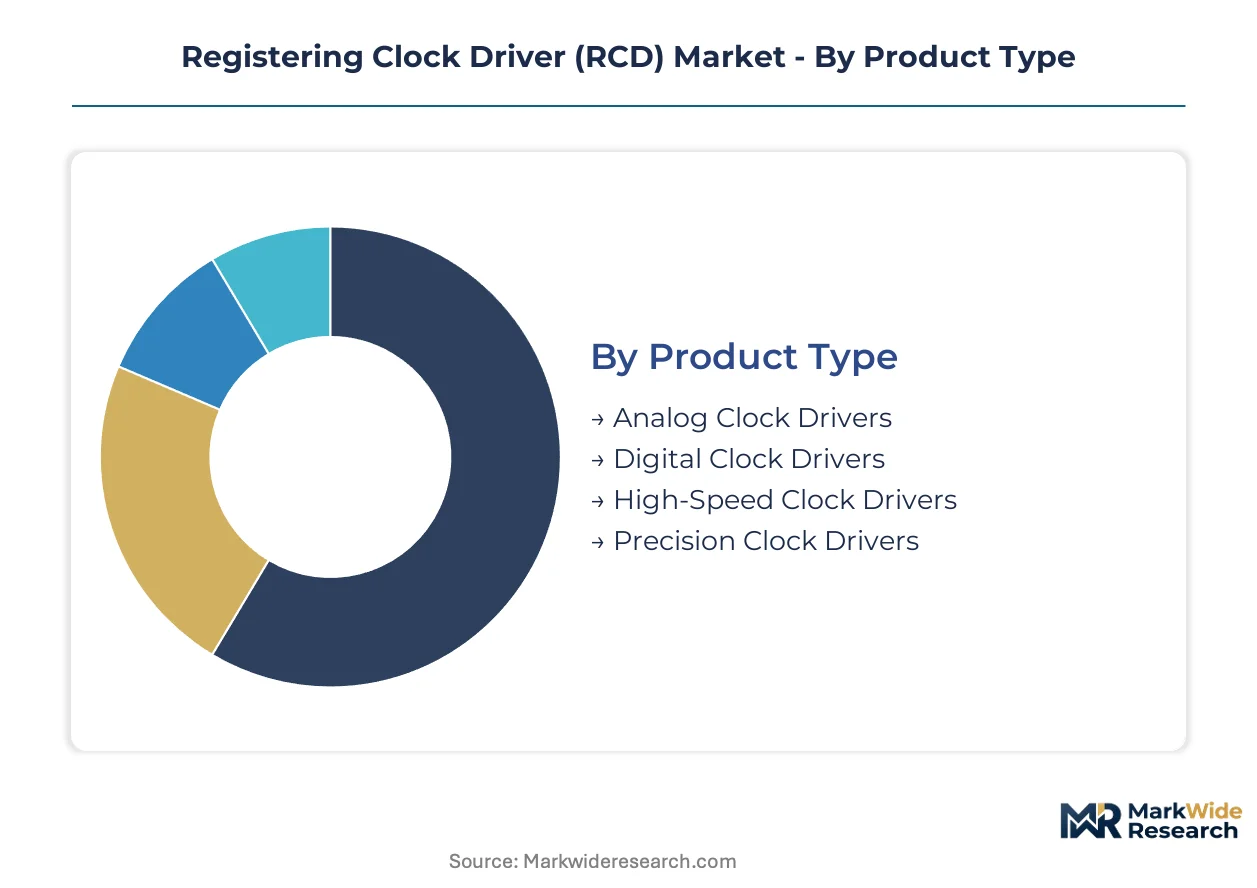
RCD procurement patterns fragment sharply across signal fidelity requirements and qualification timelines. Memory subsystem designers select buffer architectures based on jitter budgets, temperature grades, and compliance pathways that reshape vendor engagement models.
Product Type:
Digital Clock Drivers refresh at the fastest cadence as DDR5 speed grades advance, while Precision Clock Drivers sustain decade-long design cycles in aerospace and defense applications.
- Digital Clock Drivers:These devices implement programmable delay lines and skew compensation circuits for multi-rank memory configurations. Hyperscale operators in the United States specify these for DDR5-6400 server deployments where firmware-adjustable timing margins reduce motherboard respin costs.
- High-Speed Clock Drivers:Engineered for edge rates exceeding 10 Gbps with differential LVDS or CML output stages. Taiwan's semiconductor foundry cluster concentrates demand for these buffers in AI accelerator cards where signal integrity margins are thinnest.
- Analog Clock Drivers:Continuous-time architectures with minimal digital logic for lowest phase noise floors. Satellite communication ground stations specify these for reference clock distribution.
- Precision Clock Drivers:Stratum 3E and holdover-qualified devices with ovenized or temperature-compensated references. Telecom central offices in Germany and Japan maintain long procurement cycles for these mission-critical timing components.
Digital Clock Drivers dominate installed base. High-Speed Clock Drivers are where expansion concentrates.
Application:
Automotive Systems command the longest qualification timelines, while Consumer Electronics compress development cycles to under nine months for seasonal product launches.
- Automotive Systems:AEC-Q100 Grade 1 and Grade 0 devices with -40°C to 150°C operating ranges for ADAS domain controllers. Germany's KBA and Japan's METI shape validation requirements for DDR5-based sensor fusion platforms in premium vehicle programs.
- Communication Devices:5G baseband units and optical transport equipment requiring sub-100 femtosecond additive jitter. FCC Part 15 and ETSI EN 301 489 emission limits constrain clock distribution architectures for US and European infrastructure deployments.
- Industrial Automation:Isolated clock buffers with reinforced insulation ratings for programmable logic controller backplanes. Factory automation OEMs in Japan specify these for deterministic Ethernet timing.
- Consumer Electronics:Cost-optimized single-ended buffers for gaming consoles and high-end displays. Design wins track console refresh cycles with concentrated procurement from Taiwan-based module integrators.
Communication Devices anchor current revenue. Automotive Systems represent the steepest expansion trajectory as edge computing workloads migrate to vehicle platforms.
End User:
OEMs drive specification evolution through direct foundry engagement, while Aftermarket Providers extract value from legacy system sustainment with minimal NRE investment.
- OEMs:Server motherboard manufacturers and automotive tier-1s that co-develop RCD specifications with semiconductor vendors. Intel and AMD reference designs for DDR5 memory channels directly shape buffer feature roadmaps.
- Suppliers:Memory module vendors procuring RCDs for DIMM assembly. Taiwan's module houses negotiate wafer starts directly with foundry partners, bypassing distribution channels.
- Integrators:System builders consolidating clock distribution with power management and thermal solutions. Hyperscale operators in the United States favor this procurement model for rack-scale deployments.
- Aftermarket Providers:Service organizations sourcing form-fit-function replacements for legacy DDR3 and DDR4 systems. Demand concentrates in data center refurbishment programs.
OEMs dominate specification control. Suppliers capture volume scaling benefits.
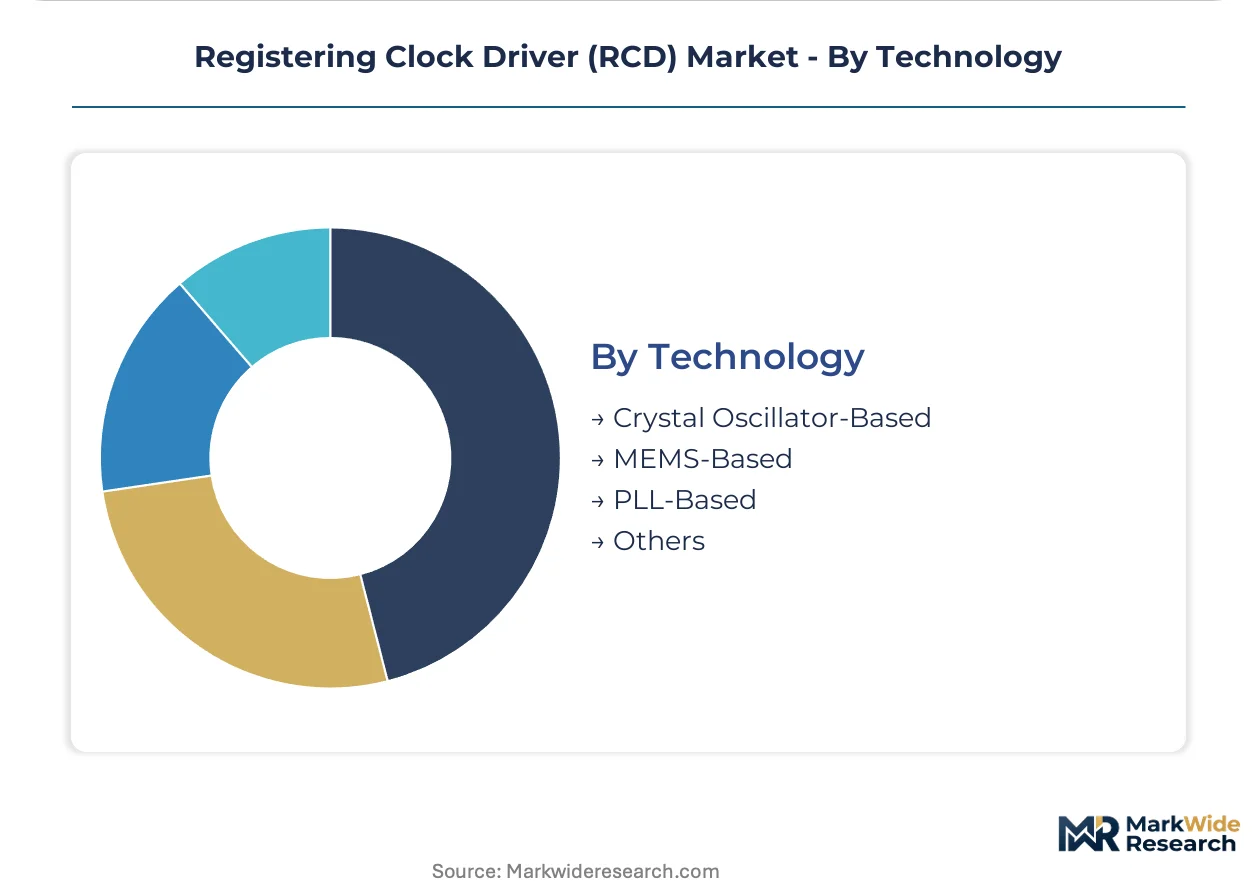
Technology:
Crystal Oscillator-Based architectures sustain premium pricing through phase noise performance, while PLL-Based solutions scale through silicon integration and programmable flexibility.
- Crystal Oscillator-Based:AT-cut and SC-cut quartz resonators with fractional-N synthesis for sub-50 femtosecond integrated jitter. Hyperscale data centers specify these for 400G and 800G optical transceiver timing.
- MEMS-Based:Silicon resonators with vibration immunity and shock resistance for automotive and industrial applications. Bosch and TDK MEMS foundries supply resonator die to RCD integrators.
- PLL-Based:All-digital PLL architectures with software-configurable multiplication ratios. Consumer electronics and mid-range communication devices favor these for BOM consolidation.
- Others:Direct digital synthesis and injection-locked oscillator topologies for specialized instrumentation and test equipment.
Crystal Oscillator-Based devices anchor the highest-margin tier. MEMS-Based timing is gaining share fastest in automotive qualification pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's semiconductor foundry cluster exports RCD die to memory module assemblers across the United States, China, and Germany, creating a trade-flow corridor that concentrates buffer supply within a single seismic zone.
United States
Hyperscale operators in Northern Virginia and Oregon deploy DDR5 servers at densities exceeding 128 DIMMs per chassis. FCC Part 15 electromagnetic compatibility mandates shape emission profiles for equipment sold into communication infrastructure. Silicon Valley engineering consultancies concentrate signal integrity simulation talent for 3D electromagnetic field solver development.
China
Domestic memory module vendors source RCDs through captive relationships with local buffer designers. MIIT-administered GB standards for information technology equipment impose jitter measurement methodologies that diverge from JEDEC baselines. Yangtze River Delta packaging houses maintain dual qualification streams for domestic and export markets.
Germany
Automotive tier-1s in Bavaria specify AEC-Q100 Grade 1 RCDs for ADAS domain controllers handling sensor fusion workloads. KBA validation requirements extend qualification timelines for temperature-critical devices. Stuttgart's precision timing engineering cluster serves telecom central offices with Stratum 3E holdover-qualified components.
Japan
METI shapes validation protocols for DDR5-based edge computing platforms in premium vehicle programs. Chubu region factory automation OEMs specify isolated clock buffers with reinforced insulation ratings for programmable logic controller backplanes. Nagoya's industrial electronics cluster drives deterministic Ethernet timing demand.
India
Production-linked incentive schemes for electronics manufacturing attract memory module assembly operations that cascade into localized RCD procurement. Karnataka and Tamil Nadu host emerging system integrators consolidating clock distribution with power management solutions. Chennai's contract manufacturing corridor negotiates directly with semiconductor foundries for high-volume buffer supply.
Registering Clock Driver (RCD) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Taiwan-based memory module houses negotiate wafer starts directly with foundry partners, bypassing distribution markups and compressing margin capture for intermediaries. The competitive landscape segments into captive supply chain operators, precision timing specialists, and diversified mixed-signal portfolio holders. Dominant competitive moves include backward integration into substrate manufacturing and strategic partnerships for automotive qualification acceleration.
Among diversified semiconductor portfolio companies, Texas Instruments and STMicroelectronics occupy positions exemplifying broad industrial and automotive clock driver reach. Montage Technology represents the captive supply chain archetype through China domestic buffer procurement relationships. Renesas Electronics sits within the precision timing tier, competing on AEC-Q100 qualification depth rather than raw data rate specifications.
| Leading Market Players |
|---|
| Integrated Device Technology |
| STMicroelectronics |
| Montage Technology |
| Texas Instruments |
| Intel |
| Renesas Electronics |
| ON Semiconductor |
| Microchip Technology |
| Rambus |
| Others |
Value Network & Pricing Analysis
Taiwan's Hsinchu Science Park concentrates 40nm and below mixed-signal foundry capacity for DDR5 RCDs, granting local buffer designers outsized leverage in price negotiations with memory module vendors across the United States and Germany. This geographic chokepoint compresses margins for downstream assemblers while sustaining premium pricing for jitter-qualified devices.
Pricing Analysis
DDR5-6400 generation RCDs command substantial premiums over legacy DDR4 buffers and early DDR5-4800 devices, while next-generation DDR5-8000 prototypes already price at stratospheric levels for hyperscale qualification samples. Three-tier pricing structure across crystal oscillator-based premium, MEMS-based mid-market, and PLL-based economy levels reflects certification grade and temperature range differentiation. Cost compression in the PLL tier is intensifying because consumer electronics buyers demand BOM consolidation at volume scale. Automotive OEMs exhibit lowest price sensitivity due to AEC-Q100 qualification barriers, while gaming console manufacturers drive hardest bargain on per-unit costs.
Supply Chain Analysis
US export-control restrictions on advanced semiconductor manufacturing equipment constrain mainland China's ability to develop indigenous RCD fabrication, perpetuating dependence on Taiwan and South Korean foundry output. Raw material dependencies center on AT-cut quartz substrates, organic flip-chip ball grid array laminates, and lead-free solder alloys compliant with REACH mandates. Single-source vulnerability concentrates in 300mm silicon wafer supply from Shin-Etsu and SUMCO. Distribution runs through direct foundry relationships that Taiwan-based memory module houses negotiate without distributor markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DDR5 interface fragmentation across server, automotive, and industrial edge computing creates specialized buffer niches that reward focused engineering investment over broad portfolio plays.
For Market Incumbents: Insulate market position by securing captive substrate supply through backward integration into organic flip-chip ball grid array manufacturing, countering the 35-40% cost concentration threatening margin stability. Accelerate AEC-Q100 Grade 0 qualification pipelines to defend against Renesas Electronics' timing expertise in automotive domain controllers. For New Entrants and Emerging Players: India's Karnataka and Tamil Nadu manufacturing corridors offer underpenetrated RCD demand as PLI-attracted memory module assembly cascades into localized buffer procurement. Target industrial automation OEMs in Japan's Chubu region with isolated clock buffers featuring reinforced insulation, leveraging shorter qualification cycles than automotive tier-1 mandates. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified semiconductor parents with neglected precision timing divisions lacking DDR5 roadmap investment. Five-to-ten-year viability hinges on MIIT domestic content rule expansion forcing dual-qualified sourcing strategies. Monitor Intel and AMD reference design specifications as inflection signals for buffer feature prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Acceleration | Shrinks AEC-Q100 Grade 1 validation from 18 months to 12 months for ADAS domain controller sockets. |
| Substrate Manufacturing Integration | Captures 35-40% of packaged device cost currently flowing to Japanese laminate suppliers. |
| Direct Foundry Partnership | Eliminates distributor margin capture for Taiwan-based memory module vendors negotiating wafer starts. |
| Dual-Standard Compliance Investment | Enables simultaneous JEDEC and MIIT GB qualification for China domestic market access. |
| Integrated Voltage Regulator Development | Collapses discrete PMIC companion market by 15-20% board area reduction for hyperscale operators. |
Research Methodology
Cross-validation between primary interviews with DDR5 memory subsystem architects and secondary analysis of JEDEC specification filings anchors the qualitative findings. Semiconductor vendor product managers, signal integrity engineering consultants, Taiwan-based module house procurement directors, and automotive tier-1 platform engineers contributed field intelligence. SEC 10-K disclosures, MIIT GB standard drafts, FCC Part 15 emission databases, and hyperscaler capex breakdowns provided secondary triangulation. Bottom-up die shipment estimates and top-down server motherboard build projections were reconciled.
Calibration against historical DDR3-to-DDR4 transition patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include buffer technology type, application end-use, temperature grade qualification, and regional regulatory compliance cluster. CAGRs were derived from slope-consistent growth trajectory fitting rather than endpoint anchoring. Forecast inputs incorporated Intel and AMD platform release cadences, foundry capacity expansion announcements, and REACH substance restriction phase-in schedules.
Macroeconomic conditions sit as an overlay; deviation in hyperscale data center construction cycles or Taiwan seismic risk realization would shift the trajectory. Forecasts reflect documented assumptions regarding JEDEC speed grade ratification timing and MIIT enforcement posture on domestic content rules. Material shifts in active silicon interposer adoption for highest-density server modules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Gas Detectors Market
Detection and Regulation Devices
Vapour Particle Barrier Market
Detection and Regulation Devices
Global Inflation Device Market
Detection and Regulation Devices
Latin America Trace Detection Market
Detection and Regulation Devices
Vacuum Leak Detectors Market
Detection and Regulation Devices
Pyro Electric Infrared Detectors Market
Detection and Regulation Devices
Underwater Signaling Devices Market
Detection and Regulation Devices
Ultra Low Dropout Regulator (LDO) Market
Detection and Regulation Devices
Flooded Member Detection Equipment Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Superconducting Detector Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market
Detection and Regulation Devices
Middle East and Africa Trace Detection Market
Detection and Regulation Devices
Limiter Diodes Market
Detection and Regulation Devices
Active Buzzer Market
Detection and Regulation Devices
Semiconductor Inspection System Market