
 Sewage Treatment Service Market | 2026-2036
Sewage Treatment Service Market Size, Share, and Industry Trends Forecast 2026-2036
Sewage Treatment Service Market Insights
Advanced tertiary treatment specifications is bifurcating the competitive landscape between premium technology providers and conventional operators. Veolia Water Technologies leverages its integrated design-build-operate platform across European municipal networks. SUEZ anchors its position through specialized anaerobic digestion and biogas recovery capabilities. Xylem differentiates via smart metering and digital twin integration for real-time process optimization.
Sewage treatment service encompasses the engineered removal of contaminants from wastewater streams through biological, chemical, and physical processes, typically achieving biochemical oxygen demand reduction below 20 mg/L and total suspended solids removal exceeding 85 percent before environmental discharge or reuse. Biological treatment commands the largest installed base due to lower operational expenditure for municipal flows, while membrane filtration represents the fastest-expanding segment as industrial buyers pursue zero-liquid-discharge compliance. Chemical treatment maintains stable margins in heavy-metal-laden effluent applications where precipitation and coagulation remain non-substitutable.
EPA effluent limitation guidelines and the EU Urban Wastewater Treatment Directive collectively mandate nutrient removal upgrades, directly expanding service contract values for tertiary-capable operators. BIS wastewater discharge standards in India and China's MEE surface-water quality classifications are accelerating outsourced treatment adoption where in-house compliance proves capital-intensive. Stakeholders must evaluate which delivery model—centralized infrastructure or decentralized mobile units—aligns with evolving enforcement patterns and capital availability cycles.
Market Dynamics
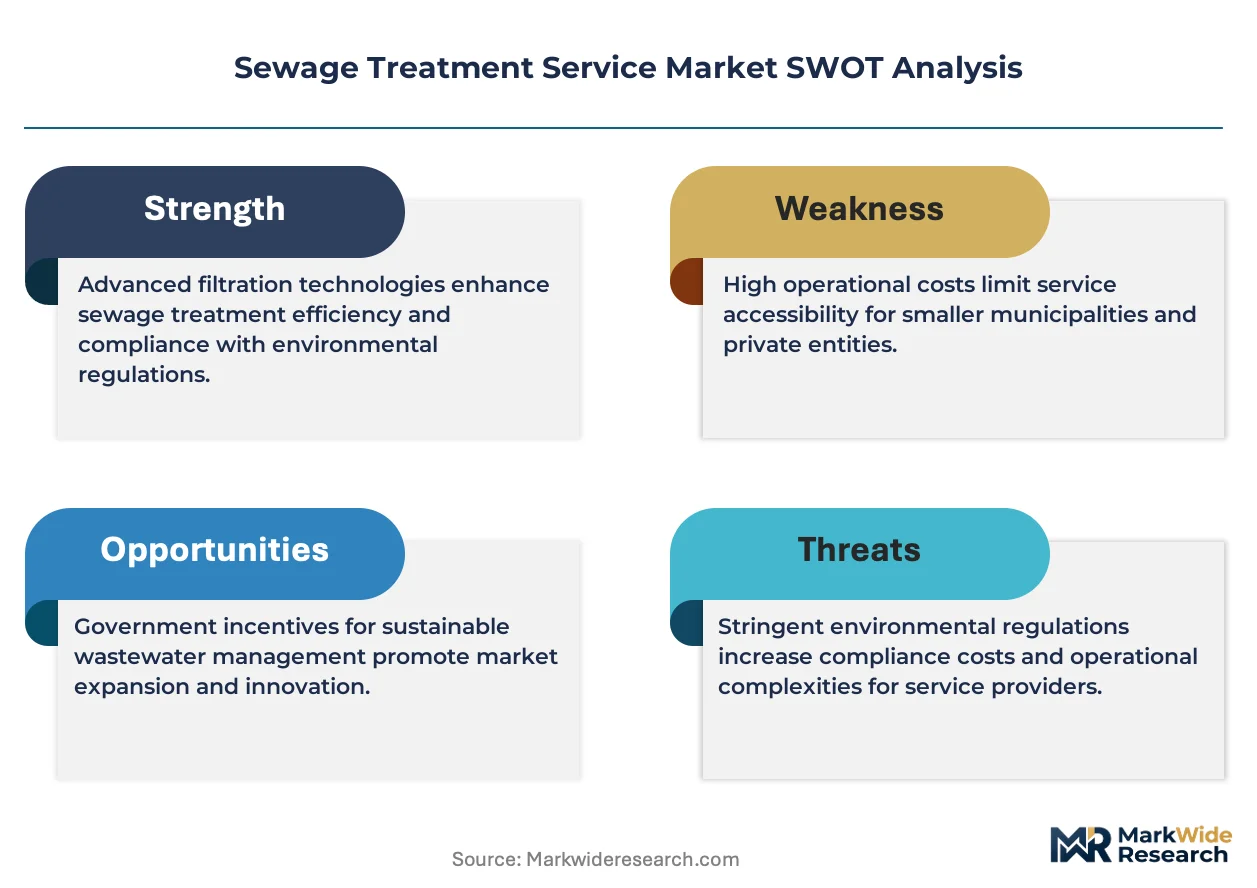
Tertiary nutrient removal mandates are compressing contract timelines for municipal operators while membrane bioreactor technology is reshaping capital deployment patterns across industrial clusters.
Growth Catalysts
- EU Urban Wastewater Treatment Directive nutrient limits:Municipal utilities across Germany, France, and Italy are accelerating service contract renewals to secure tertiary-capable operators for nitrogen and phosphorus removal compliance.
- Zero-liquid-discharge industrial mandates:Electronics and pharmaceutical manufacturing clusters in India and China are outsourcing treatment to specialized membrane filtration service providers.
- Anaerobic digestion with biogas capture:Food and beverage processors are retrofitting existing infrastructure to generate renewable energy credits under national decarbonization frameworks.
Market Restraints
- Specialized polymer and ceramic membrane supply concentration:Critical filtration components rely on a narrow supplier base concentrated in Germany and Japan, exposing operators to input cost volatility.
- Site-specific effluent variability:Textile and tannery effluent chemistry requires customized chemical precipitation protocols that resist standardization and economies of scale.
- Extended permitting timelines under EPA NPDES:New discharge permits for advanced treatment facilities face 18-24 month review cycles that delay revenue recognition for design-build-operate contracts.
Strategic Opportunities
- Decentralized mobile treatment units:Mining and oil-and-gas operations in remote Australian and Canadian jurisdictions are adopting containerized membrane systems to avoid fixed infrastructure commitments.
- Digital twin integration with predictive maintenance:Smart sensor networks combined with machine learning algorithms are enabling remote process optimization for distributed industrial clients.
- Water reuse mandates in water-stressed Middle Eastern economies:Saudi Arabia and UAE national water strategies are mandating treated effluent substitution for irrigation and industrial cooling applications.
Industry Challenges
- Cross-disciplinary engineering talent scarcity:Integration of biological process engineering with data science and automation expertise remains difficult to source in competitive labor markets.
- Legacy SCADA system interoperability:Municipal utilities operating decades-old control infrastructure face complex retrofit requirements to enable real-time monitoring and remote diagnostics.
- Extended operator certification timelines:State-level wastewater operator licensure programs create bottlenecks for scaling field service teams to match contract volume growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sewage Treatment Service Market |
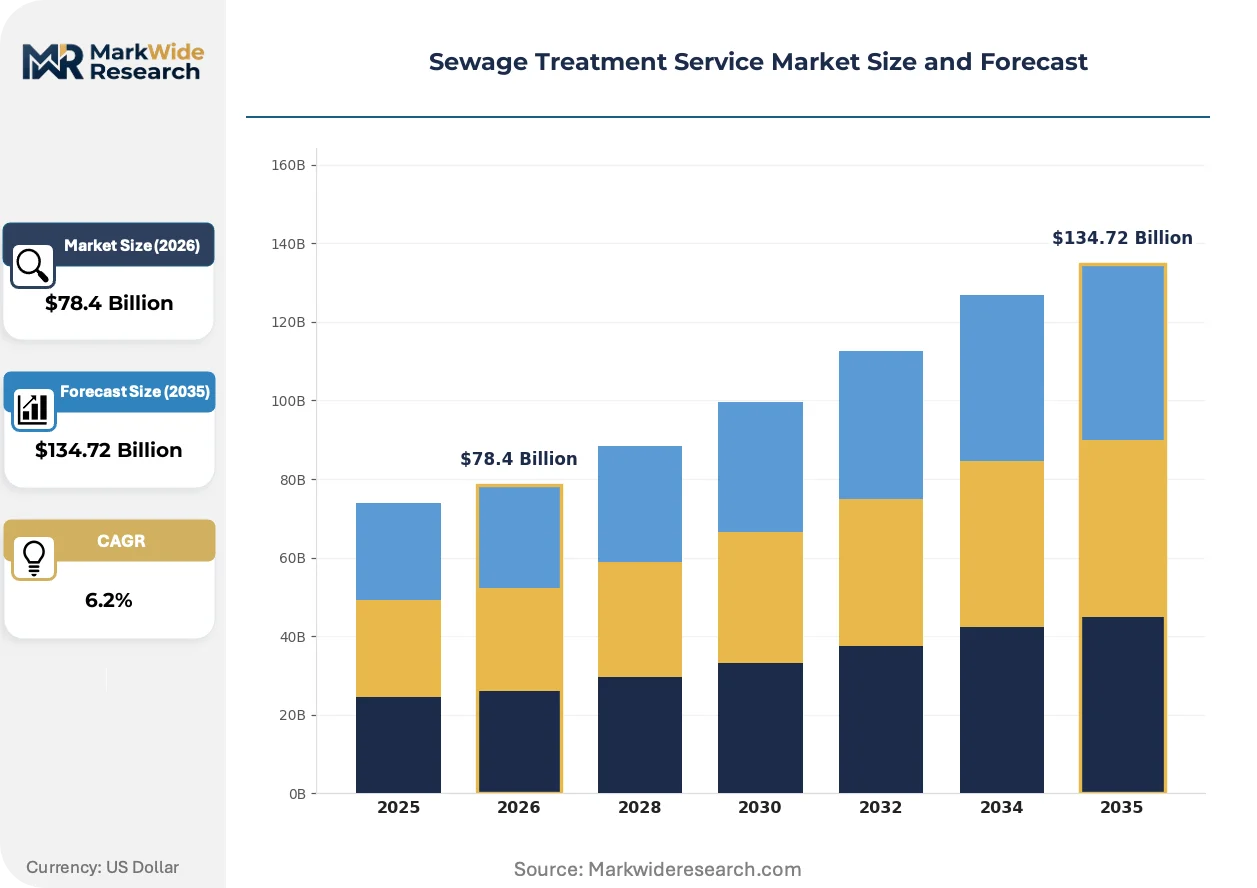
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Biological Treatment, Chemical Treatment, Physical Treatment, Sludge Management, Advanced Oxidation, Membrane Filtration Application: Municipal Wastewater, Industrial Effluents, Agricultural Runoff, Stormwater Management, Septic Systems, Landfill Leachate Client Type: Municipal Authorities, Industrial Facilities, Agricultural Enterprises, Property Developers, Waste Management Companies, Educational Institutions Delivery Model: Onsite Treatment, Offsite Treatment, Decentralized Systems, Centralized Systems, Mobile Units, Contractual Services |
| Companies Covered | Veolia Water Technologies, SUEZ, Xylem, Evoqua Water Technologies, Pentair, Kurita Water Industries, Ecolab, American Water, Thermax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sewage Treatment Service Market Trends and Innovations
Membrane aerated biofilm reactors are compressing footprint requirements while intensifying oxygen transfer efficiency, fundamentally altering how industrial buyers evaluate treatment infrastructure investments.
Membrane aerated biofilm reactor technology achieves simultaneous nitrification-denitrification in a single tank configuration through passive aeration via hollow-fiber membranes. Pharmaceutical and semiconductor manufacturers in Singapore and Ireland are specifying MABR-based service contracts for high-strength nitrogenous waste streams. This compact biological platform is displacing conventional activated sludge systems in land-constrained industrial zones where expansion space commands premium valuations.
EPA effluent limitation guidelines for PFAS are compelling municipal utilities to deploy granular activated carbon or ion exchange resin polishing trains as tertiary treatment extensions. The industrial consequence is a structural shift from biological-only service contracts toward multi-barrier treatment packages with higher operational expenditure profiles. Utilities in Michigan, North Carolina, and California are most affected, with several regional authorities issuing RFQs specifically requiring PFAS analytical capabilities and destruction verification protocols.
Performance-guaranteed service contracts are replacing traditional time-and-materials arrangements for industrial effluent management. Chemical and petrochemical processors are transferring operational risk to specialized operators through contracts tied to discharge compliance metrics rather than equipment uptime. This risk-transfer model is most visible in the US Gulf Coast and Rotterdam-Antwerp chemical clusters, where environmental liability exposure has intensified buyer preference for outsourced accountability.
Sewage Treatment Service Market Segmentation
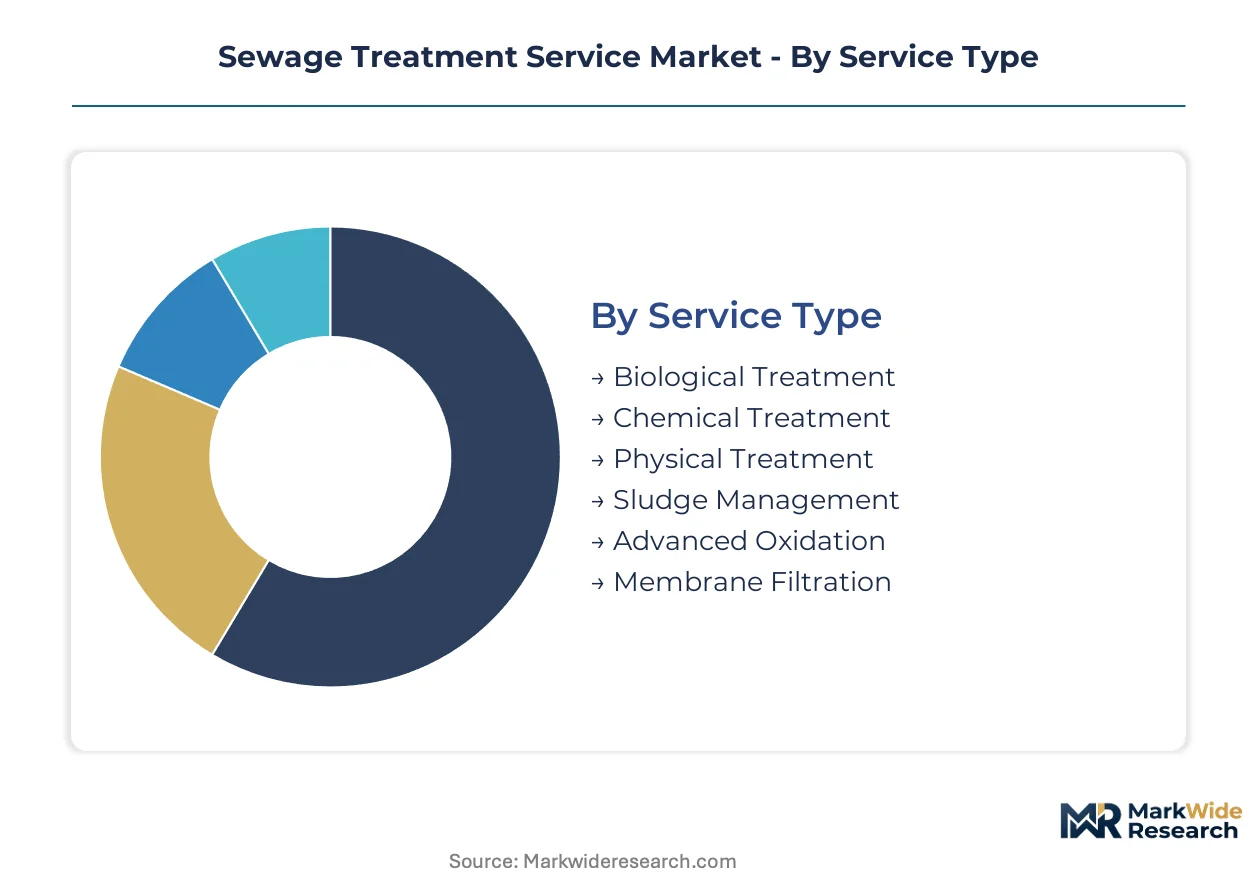
Segmentation in sewage treatment services determines how operators configure technology portfolios, price risk, and deploy capital across divergent regulatory and effluent chemistry requirements. Buyers select service tiers based on discharge permit stringency, site constraints, and liability transfer preferences rather than unit cost alone.
Service Type:
EPA effluent limitation guidelines and the EU Urban Wastewater Treatment Directive create tiered compliance obligations that directly map to service selection, with nutrient removal mandates favoring biological platforms and zero-liquid-discharge rules accelerating membrane adoption.
- Biological Treatment:Activated sludge and fixed-film processes dominate municipal flows due to lower energy intensity and operational simplicity. German and French utilities under EU nutrient limits are renewing service contracts to secure nitrification-denitrification upgrades for phosphorus compliance.
- Membrane Filtration:Ultrafiltration and reverse osmosis systems achieve dissolved solids rejection below 10 mg/L for electronics and pharmaceutical manufacturing. Industrial clusters in India and China are outsourcing membrane operations to avoid capital-intensive in-house installations under tightening BIS and MEE discharge standards.
- Chemical Treatment:Coagulation and precipitation protocols address heavy-metal-laden effluents from electroplating and mining operations.
- Physical Treatment:Screening, sedimentation, and flotation remove settleable solids and free-phase contaminants upstream of biological stages.
- Sludge Management:Dewatering, digestion, and disposal services handle residual biomass from primary and secondary treatment trains.
- Advanced Oxidation:Ozonation and UV-peroxide systems destroy refractory organics and emerging contaminants including PFAS.
Established volume favors biological treatment; emerging adoption favors membrane filtration.
Application:
Cost tier differentiation separates capital-intensive industrial effluent contracts from recurring municipal service fees.
- Municipal Wastewater:Combined sanitary and storm flows from urban populations require tertiary nutrient removal under EPA and EU mandates. Italian and Spanish utilities are accelerating tender processes for phosphorus-compliant operators.
- Industrial Effluents:High-strength, variable-chemistry waste streams from chemical, textile, and food processing demand customized treatment trains. Semiconductor fabs in Singapore and Ireland specify performance-guaranteed service contracts with discharge liability transfer.
- Agricultural Runoff:Nutrient-laden drainage from intensive livestock and crop operations faces emerging regulatory attention.
- Stormwater Management:First-flush contaminant capture and detention services address urban runoff quality requirements.
- Septic Systems:Decentralized residential wastewater servicing relies on periodic pumping and disposal contracts.
- Landfill Leachate:Age-variable organic strength and ammonia concentrations require adaptive treatment sequencing.
Contract value concentrates in industrial effluents; renewal frequency concentrates in municipal wastewater.
Client Type:
Customer type determines risk allocation, with municipal authorities favoring long-term concessions and industrial facilities preferring short-cycle performance contracts.
- Municipal Authorities:City and regional governments operate under public procurement frameworks with 15-25 year concession horizons. German municipalities are bundling tertiary upgrade requirements into renewed operating contracts.
- Industrial Facilities:Chemical, pharmaceutical, and electronics manufacturers seek outsourced accountability for discharge compliance. US Gulf Coast petrochemical processors are shifting from time-and-materials to outcome-based service agreements.
- Agricultural Enterprises:Large-scale livestock operations face emerging nutrient management obligations.
- Property Developers:Greenfield residential and commercial projects require packaged treatment for sewer connection deferrals.
- Waste Management Companies:Integrated solid waste operators require leachate and process water treatment services.
- Educational Institutions:Campus-scale systems serving universities and research facilities need specialized technical support.
Municipal authorities anchor contract duration; industrial facilities anchor technology innovation.
Delivery Model:
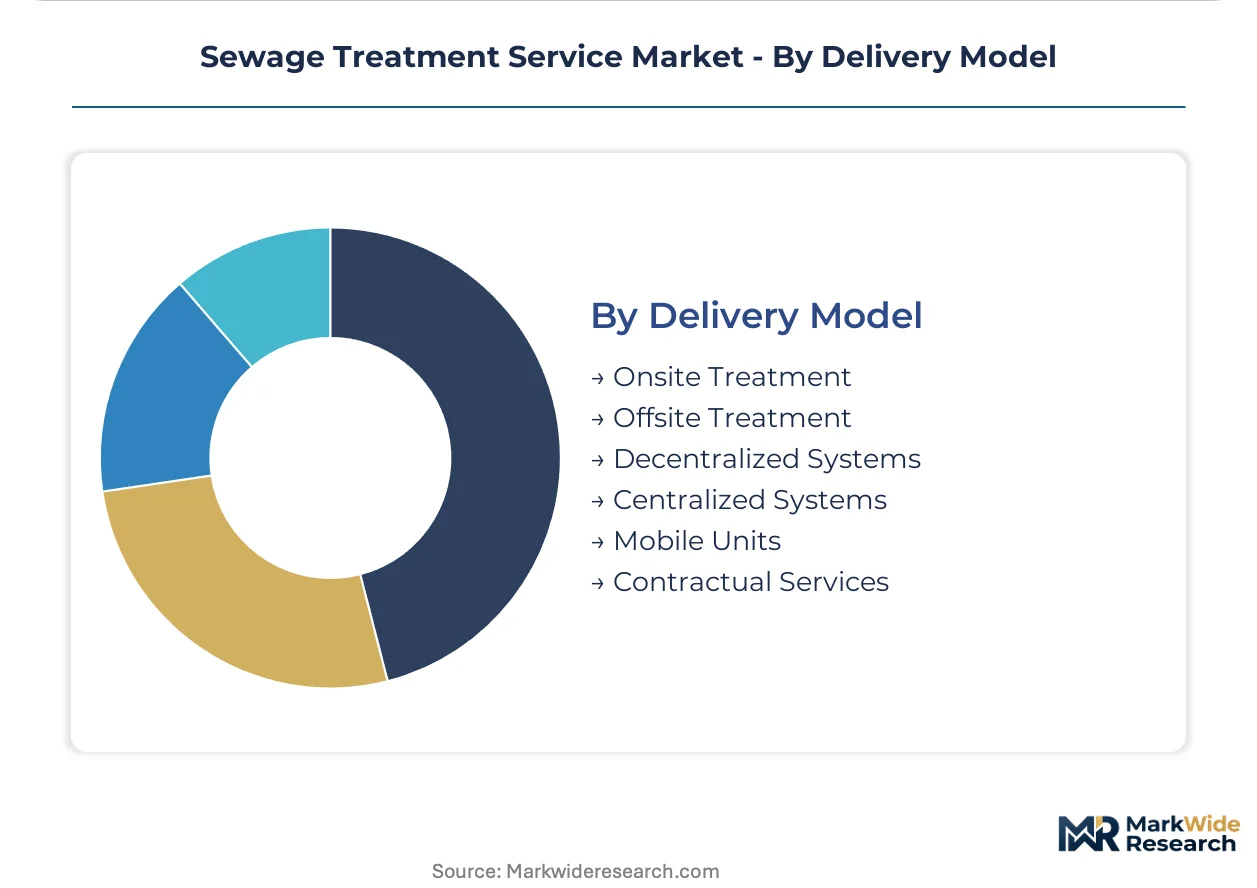
Supply concentration in specialized membrane and oxidation equipment favors centralized infrastructure in dense urban markets while remote extraction operations drive mobile unit adoption.
- Onsite Treatment:Dedicated facilities at industrial plants or institutions provide dedicated capacity with operational control. Pharmaceutical manufacturers in Switzerland and Germany maintain captive biological treatment with anaerobic digestion for biogas recovery.
- Offsite Treatment:Haulage to regional centralized plants suits variable-flow generators without land for dedicated infrastructure. Small and mid-scale food processors in the Netherlands rely on tanker collection to municipal tertiary facilities.
- Decentralized Systems:Cluster-scale packaged plants serve suburban developments and rural communities.
- Centralized Systems:Large urban treatment works achieve economies of scale for nutrient removal and energy recovery.
- Mobile Units:Containerized membrane systems deploy to remote mining and oil-and-gas sites in Western Australia and Alberta.
- Contractual Services:Design-build-operate arrangements transfer capital and operational risk to specialized operators.
Centralized systems dominate capital deployment; mobile units are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technology providers cluster in Germany, France, and Japan where membrane manufacturing and automation engineering concentrate, while service contract growth concentrates in India and China where tightening discharge standards outpace municipal capital budgets.
United States
Michigan, North Carolina, and California utilities face EPA effluent limitation guidelines for PFAS that mandate granular activated carbon or ion exchange resin polishing. The EPA NPDES permitting backlog stretches 18-24 months for advanced treatment facilities, delaying revenue recognition for design-build-operate contracts. Gulf Coast petrochemical processors in Texas and Louisiana are shifting from time-and-materials to outcome-based service agreements that transfer discharge liability.
Germany
Municipal utilities under EU Urban Wastewater Treatment Directive nutrient limits are accelerating contract renewals for nitrification-denitrification upgrades. The country's specialized polymer and ceramic membrane suppliers anchor critical filtration component production, though this concentration exposes operators to input cost volatility. Industrial clusters in the Ruhr and Bavaria are retrofitting anaerobic digestion infrastructure to generate renewable energy credits under national decarbonization frameworks.
China
Electronics and pharmaceutical manufacturing clusters in the Yangtze River Delta and Pearl River Delta are outsourcing membrane filtration operations to avoid capital-intensive in-house installations. MEE surface-water quality classifications are tightening faster than state-owned enterprise budgets can accommodate, accelerating private service contract adoption. Semiconductor fabs in Shanghai and Suzhou specify performance-guaranteed contracts with discharge liability transfer.
India
Textile processors in Gujarat and tannery operations in Tamil Nadu face BIS wastewater discharge standards that resist standardized chemical precipitation protocols due to site-specific effluent variability. Small and mid-scale food processors in Maharashtra rely on tanker collection to municipal tertiary facilities where land constraints prevent dedicated infrastructure. National discharge standard enforcement gaps are narrowing, forcing cluster-scale outsourcing decisions.
Australia
Mining operations in Western Australia and oil-and-gas developments in Queensland are adopting containerized membrane systems to avoid fixed infrastructure commitments in remote jurisdictions. Water-stressed conditions across the Murray-Darling basin are driving treated effluent substitution mandates for irrigation applications. Decentralized mobile treatment units are climbing fastest where conventional centralized systems prove economically unviable.
Sewage Treatment Service Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated design-build-operate platforms commanding premium contract values while regional operators compete on municipal renewal pricing. The market structure tilts toward consolidation at the technology-intensive tier and fragmentation at the service-delivery tier. Three archetypes dominate: multinational environmental services conglomerates with captive technology portfolios, specialized membrane and biological process engineering firms, and regional utilities with operating concessions. Competitive moves concentrate on strategic partnerships for technology licensing and geographic expansion through concession acquisitions.
Within the multinational services tier, Veolia Water Technologies and SUEZ occupy positions as archetypal integrated platform providers, while Xylem exemplifies the automation-forward specialist model. These three anchors span French, American, and Swedish origins respectively, representing the geographic dispersion of technology leadership across Western Europe and North America. Their collective positioning illustrates how service contract value migrates toward operators capable of bundling tertiary treatment compliance with digital infrastructure.
| Leading Market Players |
|---|
| Veolia Water Technologies |
| SUEZ |
| Xylem |
| Evoqua Water Technologies |
| Pentair |
| Kurita Water Industries |
| Ecolab |
| American Water |
| Thermax |
| Others |
Pricing and Supply Chain Analysis
Long-term design-build-operate contracts lock in membrane filtration supply access and price visibility for municipal utilities facing EU Urban Wastewater Treatment Directive compliance deadlines. These concession structures insulate operators from ceramic polymer cost volatility while committing buyers to fixed escalation clauses tied to energy indices.
Pricing Analysis
EPA effluent limitation guidelines dictate the pricing tier structure across municipal and industrial service contracts. Performance-guaranteed arrangements command premium positioning against time-and-materials baseline services, with liability transfer driving buyer willingness to pay. Cost compression in conventional biological treatment is intensifying because standardized activated sludge faces surplus regional capacity. Municipal authorities exhibit highest price sensitivity due to public procurement constraints, while semiconductor manufacturers prioritize discharge compliance over unit economics.
Supply Chain Analysis
Strategic stockpiling of hollow-fiber membrane modules prevails over just-in-time preferences given 12-18 week lead times from German and Japanese specialty manufacturers. Critical inputs draw from polyethersulfone polymer resin, precision ceramic substrates, and automated control valves. Single-source vulnerability concentrates in specialized membrane casting equipment where two suppliers dominate global output. Distribution runs through regional service hubs that position mobile treatment units for rapid deployment to remote mining and oil-and-gas sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward industrial facilities consolidating discharge liability through outcome-based contracts, fragmenting municipal authority negotiating leverage across fragmented regional utilities.
For Market Incumbents: Compound technology platform advantages by deepening captive membrane manufacturing capabilities and securing exclusive service concessions in German and French municipal networks. Emerging membrane bioreactor specialists threaten premium positioning unless incumbents accelerate digital twin integration for remote process optimization. For New Entrants and Emerging Players: Lead with decentralized mobile treatment units targeting Western Australian mining operations and Alberta oil-and-gas developments where fixed infrastructure economics fail. Containerized membrane systems represent the most penetrable delivery model for remote extraction clusters lacking centralized sewer access. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized membrane engineering firms with proven MABR deployment records. Long-term viability hinges on tertiary treatment capability depth rather than conventional biological scale. Watch EPA PFAS enforcement intensity across Michigan and North Carolina as inflection indicator for granular activated carbon polishing train demand.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Manufacturing Backward Integration | Captive polyethersulfone resin supply secures margin protection against German supplier concentration. |
| Digital Twin Platform Development | Machine learning algorithms enable real-time optimization for distributed industrial client portfolios. |
| MABR Technology Licensing Agreement | Singapore and Ireland pharmaceutical clusters specify compact nitrogenous waste treatment platforms. |
| Decentralized Mobile Unit Fleet Expansion | Containerized systems address remote Australian mining and Canadian oil-and-gas site requirements. |
| Anaerobic Digestion Biogas Recovery Partnership | Food and beverage processors generate renewable energy credits under national decarbonization frameworks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal utility procurement directors, industrial facility environmental compliance officers, membrane technology R&D leads, and regional service contract managers. Secondary validation drew from EPA NPDES permit databases, EU Urban Wastewater Treatment Directive implementation reports, BIS wastewater discharge notifications, and MEE surface-water quality classifications. Bottom-up service contract value aggregation was triangulated against top-down capital expenditure estimates across centralized infrastructure and mobile unit deployment categories.
Across the analysis window, volume and value outputs reflect segmentation modeling across service type, application, client category, and delivery model dimensions. CAGRs were derived from regression analysis of historical contract value trajectories and enforcement-driven upgrade cycles. Forecast inputs incorporated tertiary nutrient removal mandate timelines, zero-liquid-discharge industrial adoption curves, and membrane replacement cycle frequencies.
Forecasts assume regulatory continuity in EPA, EU, BIS, and MEE enforcement regimes; material policy shifts would require re-modeling contract value recognition timelines. Revision becomes warranted when PFAS limitation guideline expansion or ceramic membrane supply disruption crosses thresholds that alter capital deployment patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Global Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Global Biological Wastewater Treatment Market
Water and Wastewater Treatment
Global Water Recycle and Reuse Market
Water and Wastewater Treatment
US Wastewater Secondary Treatment Equipment Market
Water and Wastewater Treatment
Global Wastewater Diffused Aerator Market
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Electrocoagulation Market
Water and Wastewater Treatment
Global Vertical Sewage Pumps Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Water Aeration System Market
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market
Water and Wastewater Treatment
Mobile Wastewater Treatment Plant Market
Water and Wastewater Treatment
Agricultural Wastewater Treatment Market
Water and Wastewater Treatment
Packaged Wastewater Treatment Market
Water and Wastewater Treatment
Wastewater Clarifier Market