
 Global Smart Leak Detection Solutions for Water and Wastewater Industries Market | 2026-2036
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market Insights
Multi-source procurement of sensor hardware and analytics software is recalibrating how water utilities build leak detection networks. Xylem leverages its vertical integration across acoustic sensing and cloud analytics to control project margins from sensor deployment through software licensing. ABB competes through R&D intensity in fiber optic distributed sensing, while Schneider Electric anchors its position with IoT platform architectures that extend into predictive maintenance workflows.
Smart leak detection solutions for water and wastewater industries encompass sensor arrays, telemetry infrastructure, and analytics platforms that monitor pressure transients, acoustic signatures, and flow anomalies to pinpoint pipeline breaches before surface manifestation. These systems typically operate at sampling frequencies between 1 kHz and 100 kHz for acoustic methods, with cloud-based machine learning algorithms processing telemetry to reduce false-positive rates below five percent. Acoustic sensors occupy the largest installed base due to proven performance in metallic and plastic pipe materials, though fiber optic sensing represents the fastest-growing category as utilities deploy distributed temperature and strain monitoring across trunk mains exceeding ten kilometers. Machine learning technology sits at the center of margin pools, with vendors bundling algorithmic subscriptions that command recurring revenue streams distinct from hardware sales.
The EPA's Lead and Copper Rule revisions and the EU Green Deal's water efficiency mandates are forcing utilities to document non-revenue water reduction, directly accelerating procurement of validated leak detection systems. Japan's METI promotes smart water grid standards that align with ISO 24500 performance benchmarks, while China's MEE integrates pipeline monitoring into dual carbon accountability frameworks for municipal operators. Stakeholders must monitor how regulatory validation requirements for sensor accuracy reshape vendor qualification criteria and contract structures.
Market Dynamics
The convergence of acoustic sensing hardware with machine learning analytics is compressing deployment timelines for municipal leak detection networks, forcing utilities to restructure procurement around integrated platform vendors rather than component suppliers.
Growth Catalysts
- EU Green Deal water efficiency mandates:European utilities must document non-revenue water reduction, compelling validated leak detection procurement across Germany, France, and Italy.
- Japan METI smart water grid standards:Alignment with ISO 24500 performance benchmarks accelerates IoT-enabled monitoring adoption in Tokyo and Osaka metropolitan utilities.
- Acoustic sensor technology maturation:Proven performance in both metallic and plastic pipe materials expands addressable infrastructure across mixed-network municipalities.
Market Restraints
- Specialized sensor supply concentration:High-precision acoustic transducer manufacturing clusters in German and Japanese component suppliers, creating single-source vulnerability.
- Fiber optic installation cost structure:Distributed temperature sensing requires trenching and cable deployment that doubles upfront capital versus acoustic alternatives.
- EPA Lead and Copper Rule compliance timelines:Utility capital allocation priorities divert funding from proactive leak detection to mandated pipe replacement programs.
Strategic Opportunities
- China MEE dual carbon accountability:Municipal operators must integrate pipeline monitoring into emissions frameworks, creating new procurement mandates for smart grid vendors.
- Predictive maintenance workflow convergence:Utilities seek unified platforms combining leak detection with pressure management and asset health monitoring.
- Small and mid-sized utility underpenetration:Tier-two municipalities in Spain, Australia, and South Korea lack dedicated analytics teams, creating managed service openings.
Industry Challenges
- Machine learning model validation skill scarcity:Utilities struggle to recruit data scientists capable of tuning false-positive rates below regulatory thresholds.
- Legacy SCADA integration complexity:Decades-old telemetry infrastructure in Chicago, London, and Tokyo requires custom protocol bridges to modern cloud platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Leak Detection Solutions for Water and Wastewater Industries Market |
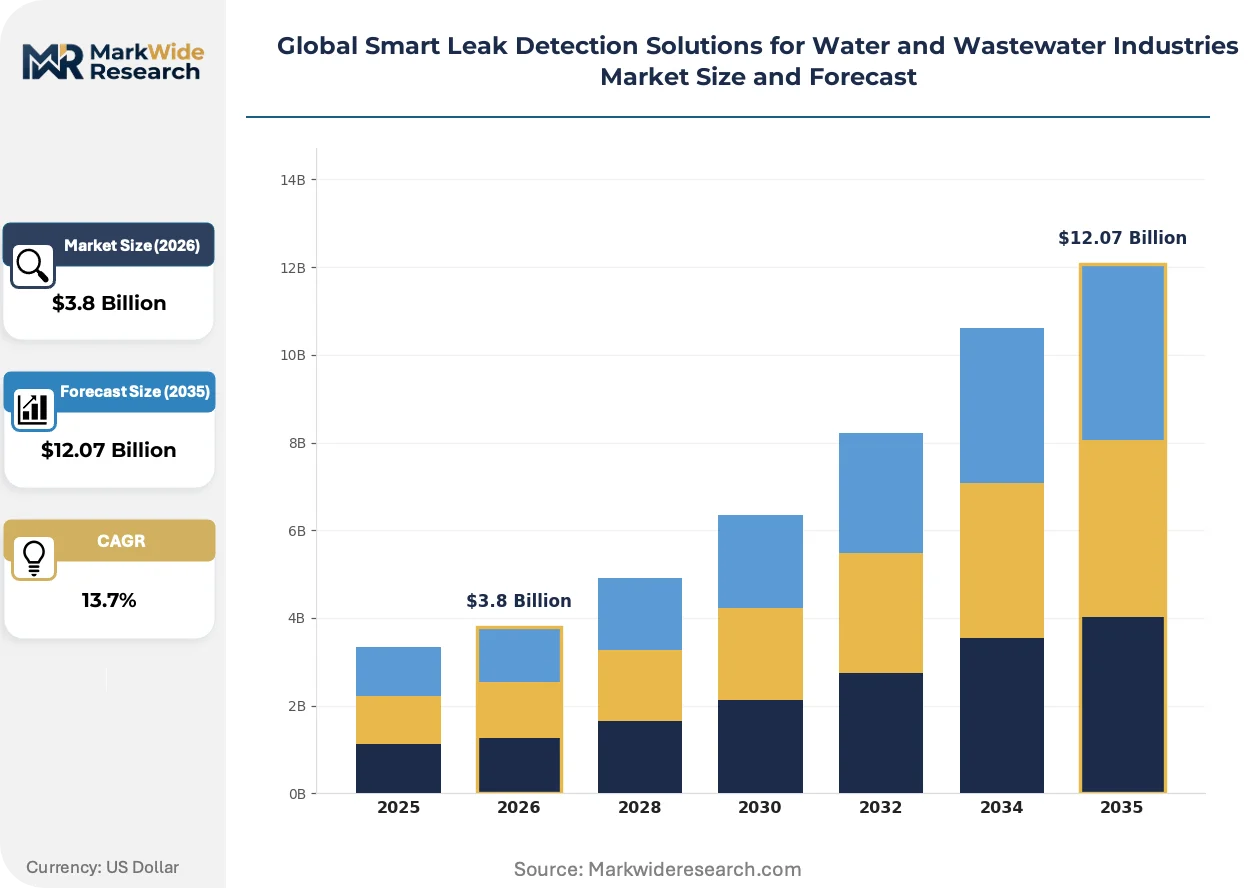
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Acoustic Sensors, Fiber Optic Sensors, Pressure Sensors Technology: IoT, Wireless, Cloud-Based, Machine Learning End User: Municipalities, Industrial Facilities, Residential Areas, Utilities Application: Leak Detection, Asset Monitoring, Flow Measurement, Water Quality Monitoring |
| Companies Covered | Honeywell International, ABB, Schneider Electric, Xylem, Atmos International, KROHNE Group, HWM-Water Ltd, Pure Technologies, AVEVA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market Trends and Innovations
Edge computing architectures and subscription-based analytics licensing are redrawing competitive boundaries between hardware manufacturers and software platforms.
Distributed acoustic sensing hardware is modularizing from fixed-node installations toward battery-powered, magnetically-mounted units that utilities deploy without pipe shutdown. German and Japanese water authorities pilot these rapid-deployment configurations for emergency response and construction-zone monitoring. This shift is modularizing project scopes, allowing procurement teams to separate permanent backbone infrastructure from temporary or expandable sensor arrays.
The EU Green Deal's water loss reduction targets are tightening validation requirements for sensor accuracy and calibration documentation. Utilities in the Netherlands and Denmark now require third-party certification of acoustic detection thresholds before contract award. Equipment vendors respond by pre-certifying hardware against ISO 24500 benchmarks and embedding self-diagnostic firmware that logs calibration drift.
Subscription pricing for algorithmic leak classification is displacing perpetual software licenses in municipal procurement. North American utilities favor operational expenditure models that align vendor payments with documented non-revenue water savings. This restructures vendor-customer relationships toward multi-year performance contracts with penalty clauses for false-negative rates.
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market Segmentation
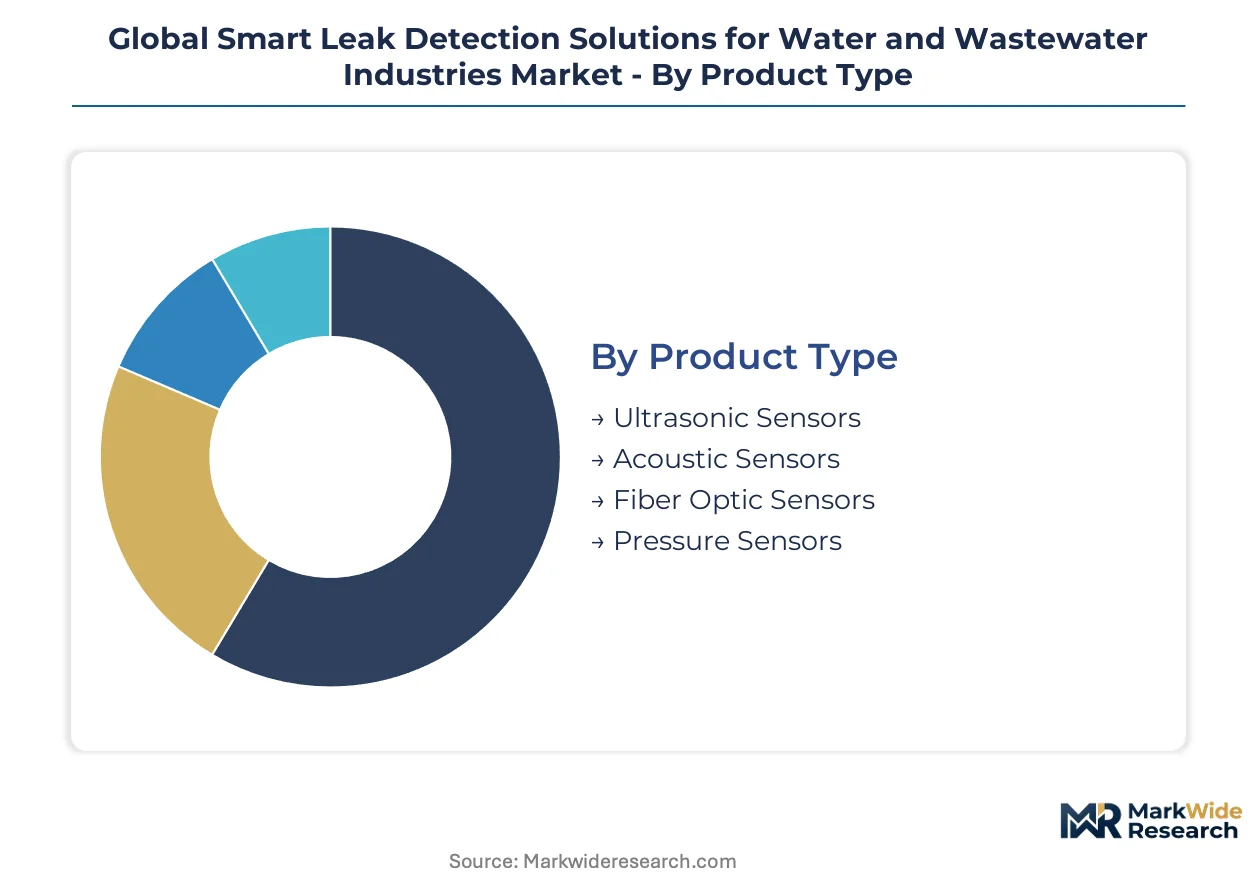
Capital allocation patterns across sensor hardware, analytics software, and telemetry infrastructure create distinct margin pools. Procurement teams structure vendor selection around installation complexity, data integration requirements, and recurring licensing models.
Product Type:
Capital intensity varies sharply across sensing modalities, with distributed fiber deployments demanding trenching and cable installation that multiplies upfront project costs versus surface-mounted alternatives.
- Acoustic Sensors:Piezoelectric transducers capture pressure wave signatures from pipe breaches at sampling frequencies between 1 kHz and 100 kHz. German and Japanese water authorities specify these for metallic and plastic distribution networks where proven detection thresholds reduce false-positive rates below regulatory limits.
- Fiber Optic Sensors:Distributed temperature and strain monitoring across trunk mains exceeding ten kilometers enables continuous coverage without discrete node installation. Deployment concentrates in Netherlands and Denmark where EU Green Deal water loss mandates justify premium infrastructure investment for non-revenue water documentation.
- Ultrasonic Sensors:Time-of-flight measurement systems transmit high-frequency pulses through pipe walls to detect wall thickness degradation and active leaks. Municipalities in Tokyo and Osaka deploy these for condition assessment of aging cast-iron networks.
- Pressure Sensors:Transient monitoring arrays identify pressure drops indicative of pipe breaches or illegal connections. These units integrate with existing SCADA infrastructure in Chicago and London where legacy telemetry protocols require custom bridging solutions.
Most installed capacity flows through acoustic sensor networks. Expansion is steepest in fiber optic sensing.
Technology:
Deployment architecture choices determine whether utilities build in-house analytics capability or outsource algorithmic processing to vendor cloud platforms.
- Machine Learning:Cloud-based classification algorithms process acoustic signatures and flow anomalies to pinpoint breach locations before surface manifestation. North American utilities negotiate multi-year performance contracts tying vendor payments to documented non-revenue water savings.
- IoT:Sensor-to-platform connectivity protocols enable real-time telemetry transmission from distributed node arrays. Japan's METI smart water grid standards mandate ISO 24500-aligned interoperability for Tokyo metropolitan procurement.
- Cloud-Based:Centralized data processing eliminates on-premise server infrastructure but introduces cybersecurity compliance requirements under EU GDPR and sector-specific critical infrastructure regulations.
- Wireless:Battery-powered, magnetically-mounted units permit rapid deployment without pipe shutdown for emergency response and construction-zone monitoring applications.
Subscription licensing now dominates machine learning procurement. IoT platform integration commands the steepest vendor margins.
End User:
Customer scale dictates whether procurement emphasizes integrated platform vendors or component suppliers capable of slotting into existing maintenance workflows.
- Municipalities:City water departments in Germany, France, and Italy face EU Green Deal mandates requiring validated leak detection procurement with third-party certification of acoustic detection thresholds before contract award.
- Utilities:Regional water authorities with dedicated engineering teams build multi-source procurement strategies separating sensor hardware from analytics software to maintain vendor pricing leverage.
- Industrial Facilities:Manufacturing and chemical processing plants deploy point-source monitoring around high-value process water loops where single leak events carry contamination liability.
- Residential Areas:Homeowner association and building-scale deployments concentrate in water-scarce regions where individual meter-level monitoring supports consumption-based billing reconciliation.
Municipal procurement absorbs the largest project volume. Industrial facility adoption is climbing the fastest as ESG disclosure requirements tighten.
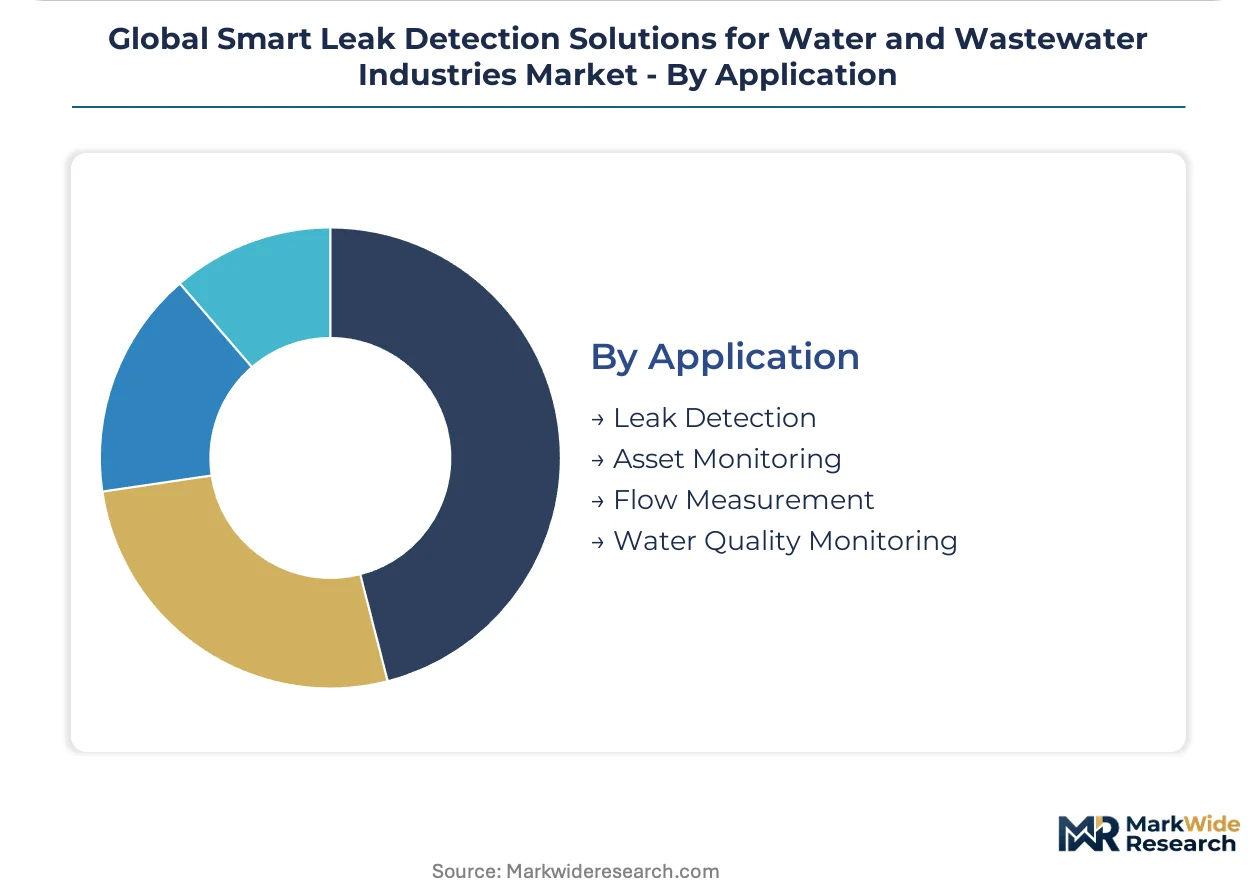
Application:
Functional scope determines whether deployments target reactive breach response or predictive infrastructure management spanning pressure, flow, and asset condition.
- Leak Detection:Core pipeline breach identification using acoustic, pressure, or fiber optic methods to reduce non-revenue water and document compliance with EPA Lead and Copper Rule revisions.
- Asset Monitoring:Continuous condition assessment of valves, pumps, and pipe segments to schedule preventive replacement before catastrophic failure.
- Flow Measurement:District metered area balancing and consumption verification supporting revenue protection and hydraulic model calibration.
- Water Quality Monitoring:Integration of contaminant sensors with leak detection arrays to identify intrusion events at negative pressure points.
Leak detection commands the dominant share of deployed sensors. Asset monitoring represents the fastest-climbing application as predictive maintenance workflows converge with pressure management platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement patterns as utilities migrate toward jurisdictions with clearer certification pathways and subsidized infrastructure programs. Cost-of-compliance gaps between mature markets and emerging adopters are accelerating technology transfer while fragmenting vendor qualification standards.
United States
EPA Lead and Copper Rule revisions are compelling municipal utilities to document non-revenue water reduction through validated leak detection systems. Chicago's century-old cast-iron network drives demand for SCADA-compatible pressure monitoring arrays. Metropolitan utilities across the Midwest prioritize rapid-deployment acoustic sensors for emergency response protocols.
Germany
Aging pipe infrastructure in the Ruhr and Rhine industrial corridors necessitates continuous trunk-main monitoring. EU Green Deal water efficiency mandates enforce third-party certification of acoustic detection thresholds before contract award. Bavarian water authorities pilot fiber optic distributed sensing across distribution networks exceeding ten kilometers.
Japan
METI smart water grid standards align procurement with ISO 24500 performance benchmarks. Tokyo and Osaka metropolitan utilities deploy ultrasonic time-of-flight systems for condition assessment of aging cast-iron networks. Kansai-region operators integrate IoT-enabled monitoring into predictive maintenance workflows.
China
MEE dual carbon accountability frameworks mandate pipeline monitoring integration for municipal emissions reporting. Yangtze River Delta utilities deploy machine learning-classified acoustic arrays to reduce water loss documentation. Pearl River Delta smart city pilots embed leak detection within broader urban water grid digitization.
Netherlands
EU Green Deal water loss reduction targets tighten validation requirements for sensor accuracy and calibration documentation. Dutch water authorities specify distributed temperature sensing for trunk mains serving the Randstad conurbation. Eindhoven-region utilities require self-diagnostic firmware logging calibration drift for regulatory audit trails.
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent analytics and managed service spaces. Market structure concentrates around integrated platform vendors capable of bundling hardware deployment with recurring software licensing. Three archetypes dominate: vertically integrated sensor-to-cloud providers, specialized fiber optic sensing laboratories, and IoT platform architects extending into predictive maintenance. Consolidation pressures favor M&A activity targeting analytics capabilities, while contract structures shift toward multi-year performance agreements with penalty clauses.
Among diversified industrial technology groups, Honeywell International and ABB exemplify scale-driven platform strategies spanning multiple sensing modalities. Xylem anchors the vertically integrated archetype with captive acoustic sensing production and cloud analytics licensing. Schneider Electric occupies the IoT-native position with architecture extending into utility workflow automation. Specialist operators including KROHNE Group and Atmos International represent regional precision-engineering traditions concentrated in German and UK industrial clusters.
| Leading Market Players |
|---|
| Honeywell International |
| ABB |
| Schneider Electric |
| Xylem |
| Atmos International |
| KROHNE Group |
| HWM-Water Ltd |
| Pure Technologies |
| AVEVA |
| Others |
Pricing and Supply Chain Analysis
Machine learning algorithm development talent clustering in California and Massachusetts creates labor-cost differentials that widen pricing-tier spreads between premium analytics subscriptions and basic sensor hardware.
Pricing Analysis
Distributor margins on acoustic sensor hardware compress project economics for small utilities while direct-to-utility SaaS licensing of leak classification algorithms captures recurring revenue streams. Pricing stratifies across premium-certified, standard-compliant, and economy-tier equipment levels based on ISO 24500 validation depth and telemetry integration complexity. Cost compression in economy-tier acoustic transducers is intensifying because Chinese component suppliers are scaling piezoelectric manufacturing capacity. Municipal water departments with constrained capital budgets exhibit highest price sensitivity, while industrial facilities prioritize detection accuracy over unit cost.
Supply Chain Analysis
China's MEE domestic-content mandates for smart grid infrastructure are reshaping sourcing patterns for telemetry hardware deployed in Yangtze River Delta utilities. High-precision acoustic transducer manufacturing concentrates in Germany and Japan, while cloud analytics platform development centers on US West Coast engineering clusters. The supply chain draws from piezoelectric ceramics, fiber optic cable, and edge-computing chipsets as critical inputs. Single-source vulnerability in German acoustic sensor component suppliers poses structural risk for European procurement timelines. Distribution runs through regional systems integrators who bundle sensor deployment with calibration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Procurement teams are shifting specification requirements toward third-party-certified detection thresholds that command pricing premiums.
For Market Incumbents: Anchor platform stickiness through backward integration into cloud analytics while pre-certifying hardware against evolving EU Green Deal validation protocols. Fiber optic sensing specialists threaten acoustic sensor incumbents in trunk-main applications. Capacity addition in edge-computing firmware development preserves margin control against software-native entrants. For New Entrants and Emerging Players: Battery-powered rapid-deployment sensor arrays offer a technology-first wedge into emergency-response procurement workflows. Small and mid-sized utilities in Spain and Australia represent the most penetrable customer segment. Managed service bundling of algorithmic tuning and false-positive rate optimization provides a differentiated go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among hardware-centric vendors lacking recurring software revenue streams. The five-to-ten-year viability window favors platform vendors with demonstrated utility workflow integration. Acquisition target archetype: fiber optic sensing laboratories with ISO 24500 certification track records. Watch for EPA enforcement intensity around non-revenue water documentation as an inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies acoustic sensing with predictive maintenance workflows for Tokyo metropolitan utilities. |
| Acquisition of Specialist Firm | Adds fiber optic distributed sensing capability to address EU Green Deal trunk-main mandates. |
| Geographic Expansion | Establishes local calibration facilities to meet Netherlands third-party certification requirements. |
| Product Launch | Introduces magnetically-mounted battery sensors for Chicago emergency-response protocols. |
| Strategic Partnership | Aligns IoT connectivity protocols with Japan METI smart water grid standards. |
Research Methodology
Bottom-up municipal utility deployment modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with water utility engineering directors, SCADA integration specialists, municipal procurement officers, and leak detection systems integrators combined with secondary validation against EPA regulatory filings, EU Green Deal implementation reports, Japan METI smart grid documentation, and ISO 24500 certification databases. Triangulation between utility capital expenditure surveys and vendor revenue disclosures anchors volume estimates.
Input-output matrices map sensor hardware unit economics against analytics software licensing terms across the projection horizon. Segmentation dimensions modeled include sensing modality, deployment architecture, end-user scale, and regional regulatory framework. CAGRs derive from utility capital budget growth rates and mandated leak detection procurement timelines. Industry-specific forecast inputs incorporate EU water loss reduction enforcement schedules and China MEE dual carbon accountability integration.
The model holds under stable regulatory enforcement intensity; deviation in EPA Lead and Copper Rule compliance timelines or EU Green Deal subsidy allocation would shift municipal capital prioritization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Ecological Wastewater Treatment Market
Water and Wastewater Treatment
Global Water Recycle and Reuse Market
Water and Wastewater Treatment
Wastewater Screening Equipment Market
Water and Wastewater Treatment
Sewage Treatment Service Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market
Water and Wastewater Treatment
Bio Filter Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Javelle Water Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Global Wastewater Diffused Aerator Market
Water and Wastewater Treatment
Sewage Pump Market
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
Tertiary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Packaged Wastewater Treatment Market
Water and Wastewater Treatment
Water Testing Meter Market