
 Global SCADA in Water and Wastewater Management Market | 2026-2036
Global SCADA in Water and Wastewater Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global SCADA in Water and Wastewater Management Market Foresight
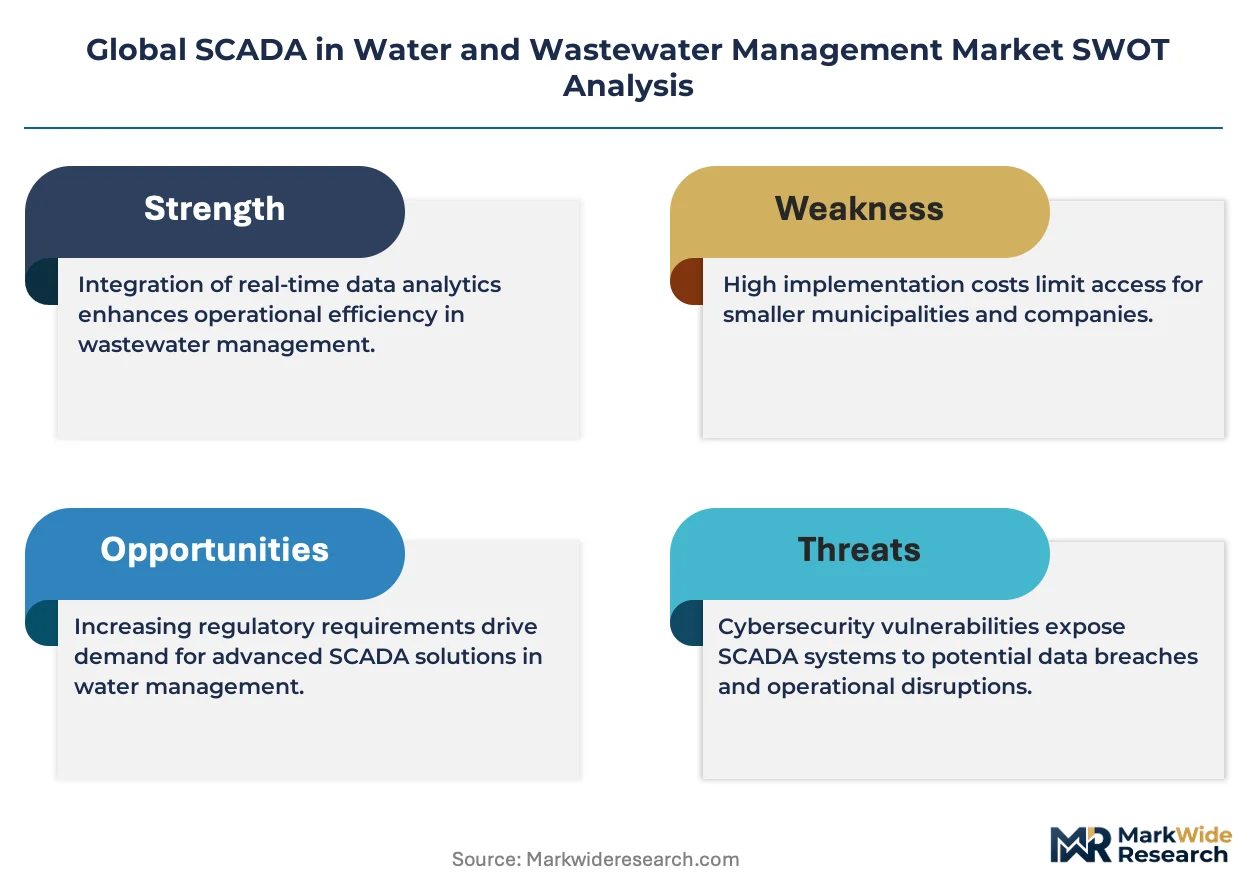
Legacy copper cabling in water treatment telemetry is shifting toward fiber-optic and wireless mesh architectures, cutting maintenance cycles and enabling edge-native sensor integration. Schneider Electric leverages its EcoStruxure platform to anchor European utility modernization programs with cyber-hardened RTU portfolios. Siemens sustains competitive density through deep domain expertise in membrane bioreactor SCADA coupling, while ABB dominates medium-voltage pump station automation with synchronized motor control algorithms.
SCADA in water and wastewater management denotes a layered control architecture comprising programmable logic controllers, remote terminal units with IP67 environmental sealing, and supervisory workstations that aggregate flow, pressure, and chemical composition data across distributed treatment assets. Its primary purpose is to enable real-time operational visibility, automated alarm escalation, and predictive maintenance scheduling across geographically dispersed hydraulic infrastructure. Supervisory Control Systems occupy the largest installed base due to their role as the central decision layer, though Analytics Platforms represent the fastest-expanding margin pool as utilities monetize operational data for capital planning. Cloud-Based deployment is gaining traction among mid-size municipal utilities seeking to defer capital expenditure, while On-Premises configurations persist at critical national water security facilities where air-gapped sovereignty remains non-negotiable.
The EPA mandates cybersecurity evaluation under its Water Sector Cybersecurity Initiative, while the EU Cyber Resilience Act imposes conformity obligations on networked control products entering European treatment facilities. India's CEA grid-connectivity standards for pumping stations and China's MEE real-time monitoring mandates for wastewater outfalls collectively expand the addressable regulatory surface for certified SCADA vendors. Stakeholders must weigh interoperability commitments against emerging zero-trust network segmentation requirements as OT-IT convergence accelerates threat exposure across legacy water infrastructure.
Market Dynamics
OT-IT convergence is compressing procurement cycles for water utilities as edge-native architectures displace legacy copper telemetry, forcing vendors to recertify hardened RTU portfolios under emergent zero-trust mandates.
Growth Catalysts
- EPA Water Sector Cybersecurity Initiative:Mandatory cybersecurity evaluations for treatment facilities are accelerating replacement of unpatched serial-based SCADA with IP-native architectures.
- India Smart Cities Mission:Integrated water command centers in urban corridors are mandating unified SCADA-IoT platforms for real-time hydraulic optimization.
- EU Urban Wastewater Treatment Directive revisions:Stricter effluent monitoring requirements are driving sensor density upgrades at municipal treatment plants.
Market Restraints
- Copper-to-fiber migration capex:Full telemetry infrastructure replacement at aging treatment plants requires capital allocation that smaller municipal utilities cannot access.
- Certified RTU supply concentration:IP67-sealed remote terminal units with IEC 62443-3-3 SL2 certification ship primarily from European foundries, creating geographic supply risk.
- Air-gapped sovereignty requirements:National water security facilities in China, Saudi Arabia, and Israel mandate on-premises architectures that exclude cloud-based OPEX models.
Strategic Opportunities
- Vietnam Mekong Delta leakage networks:Underpenetrated municipal utilities are deploying wireless mesh SCADA for non-revenue water reduction without fiber trenching.
- Digital twin convergence:SCADA-integrated hydraulic modeling is enabling predictive maintenance contracts that monetize operational data for capital planning.
- EU Cyber Resilience Act conformity:Networked control products with pre-certified CE marking gain accelerated procurement pathways across European treatment facilities.
Industry Challenges
- IEC 62443-4-2 certification timelines:Component-level security certification for edge devices extends vendor product launch cycles by 14-18 months.
- OT-IT skill bifurcation:Water utilities face acute scarcity of engineers conversant in both Modbus protocol stacks and zero-trust network segmentation.
- Legacy protocol integration:DNP3 and IEC 60870-5-104 assets in 1990s-era pump stations require costly protocol gateways for cloud telemetry backhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global SCADA in Water and Wastewater Management Market |
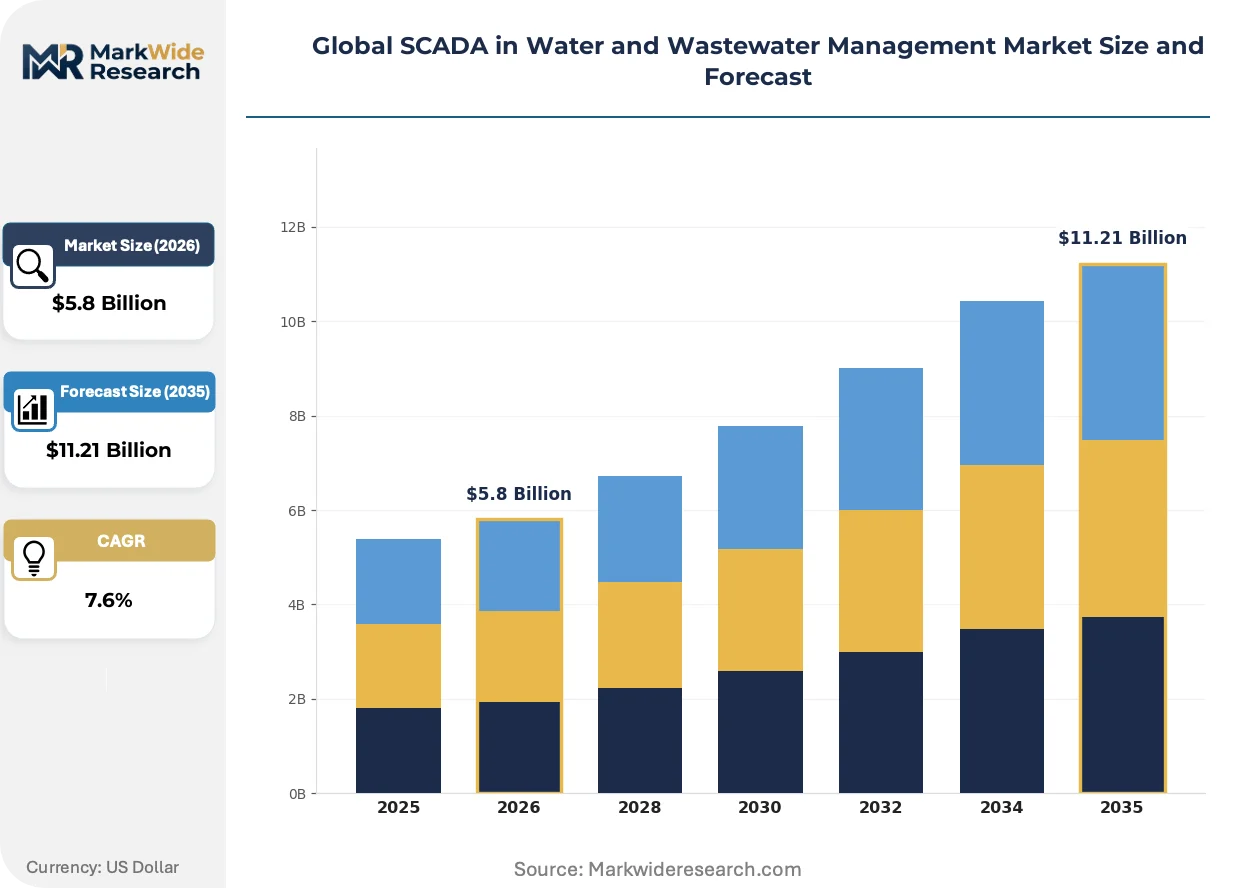
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.21 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Supervisory Control Systems, Data Acquisition Modules, Communication Interfaces, Remote Terminal Units, Human Machine Interface, Analytics Platforms Deployment Mode: Cloud-Based, On-Premises, Hybrid, Edge Computing Application: Water Quality Monitoring, Wastewater Treatment, Pipeline Management, Flood Control, Irrigation Management, Reservoir Management End User: Municipal Utilities, Industrial Facilities, Agricultural Operations, Environmental Agencies |
| Companies Covered | Schneider Electric, Siemens, ABB, Rockwell Automation, Honeywell International, Emerson Electric, Yokogawa Electric Corporation, Mitsubishi Electric, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global SCADA in Water and Wastewater Management Market Shifts & Advancements
Edge-native sensor architectures are collapsing the traditional three-tier SCADA hierarchy, compressing decision latency from minutes to milliseconds while exposing legacy RTU vendors to disintermediation.
Unified SCADA-IoT platforms are unifying telemetry, control, and analytics layers into single software-defined stacks. Mid-size utilities in Brazil and Thailand are adopting these architectures fastest, bypassing capital-intensive PLC retrofits. The structural consequence is unifying hardware procurement with SaaS subscription models, eroding traditional RTU margin pools.
REACH restrictions on per- and polyfluoroalkyl substances are forcing sensor manufacturers to reformulate waterproof housings and cable sheathing. Industrial consequence includes accelerated validation cycles for IP-rated field devices. Water quality monitoring OEMs serving EU utilities are responding fastest, with some shifting supply chains to fluorine-free polymer suppliers ahead of 2026 enforcement windows.
Performance-based service contracting is displacing capital sale models for SCADA deployments. System integrators in Australia's Murray-Darling basin are piloting availability-guarantee contracts where vendor compensation ties to leakage reduction metrics. This shift is most visible in water-stressed geographies where municipal OPEX budgets exceed capital appropriations.
Global SCADA in Water and Wastewater Management Market Segmentation
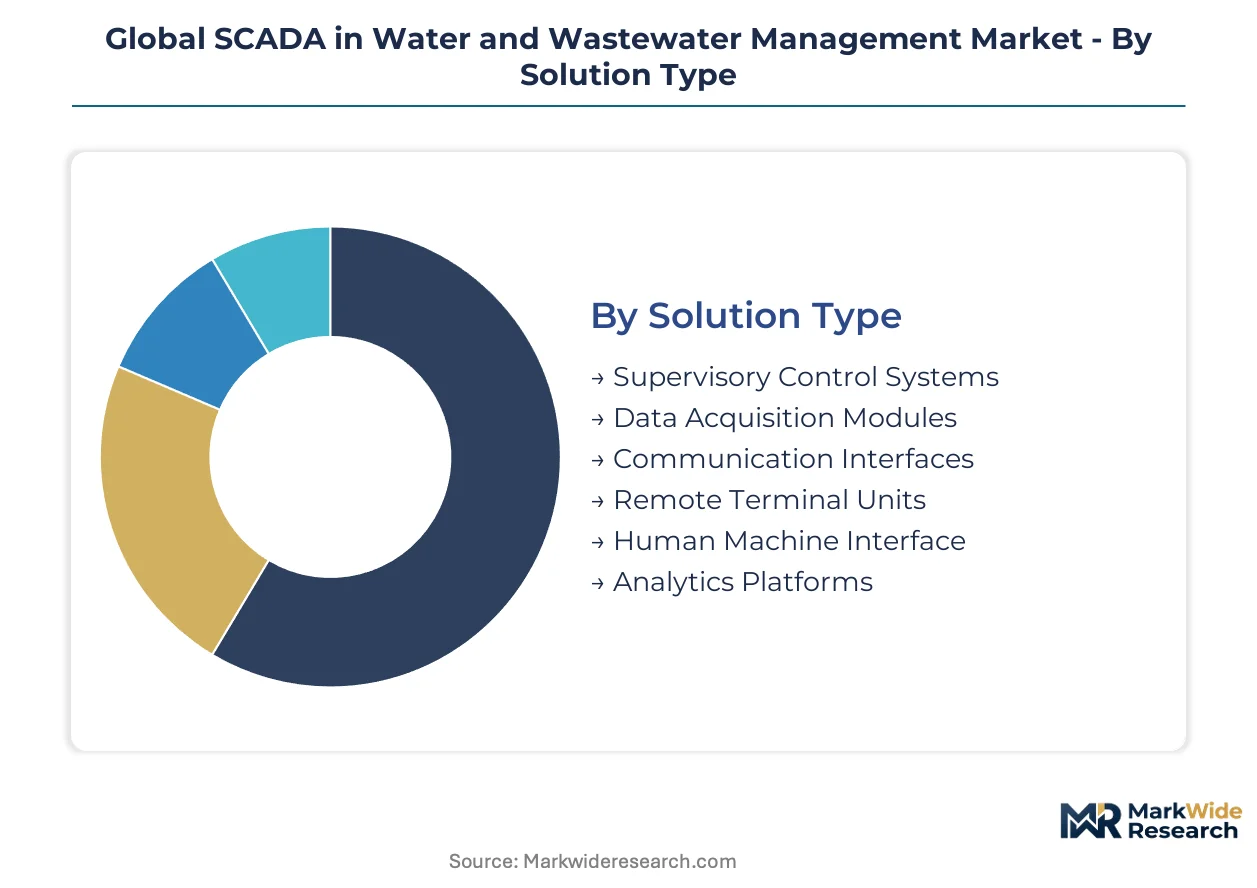
SCADA procurement patterns diverge sharply across deployment modes and end-user sophistication, with capital availability dictating architecture choices from fiber-backbone command centers to solar-powered edge nodes. Solution type selection correlates directly with telemetry density requirements and cybersecurity certification obligations.
Solution Type:
Capital intensity peaks at the control layer, where redundant server infrastructure and cyber-hardened RTU portfolios absorb the majority of utility automation budgets.
- Supervisory Control Systems:Centralized decision platforms aggregate real-time telemetry from distributed PLCs and RTUs across treatment assets. Municipal utilities in Germany and Japan prioritize these systems for multi-site hydraulic optimization under national water security mandates.
- Analytics Platforms:Machine learning pipelines transform operational data into predictive maintenance schedules and capital planning scenarios. Demand concentrates among Australia's water-stressed utilities monetizing leakage reduction through performance-based service contracts.
- Data Acquisition Modules:Signal conditioning hardware bridges analog sensors to digital control networks.
- Communication Interfaces:Protocol gateways enable legacy DNP3 assets to interface with IP-native architectures.
- Remote Terminal Units:IP67-sealed field devices with IEC 62443 certification command premium pricing from European foundries.
- Human Machine Interface:Operator workstations with alarm escalation workflows remain standard at treatment facilities.
Most installed capacity flows through Supervisory Control Systems. Expansion is steepest in Analytics Platforms.
Deployment Mode:
Operational technology teams weigh sovereignty requirements against total cost of ownership, with air-gapped mandates constraining cloud adoption at critical infrastructure sites.
- On-Premises:Dedicated server infrastructure with physical network segmentation satisfies national water security protocols. China's MEE real-time monitoring mandates and Saudi Arabia's critical facility standards exclude external connectivity.
- Cloud-Based:SaaS delivery models defer capital expenditure for mid-size municipal utilities. Brazilian and Thai utilities adopt these fastest, bypassing legacy PLC retrofits through subscription telemetry platforms.
- Hybrid:Split architectures process sensitive control logic locally while pushing analytics workloads to managed infrastructure.
- Edge Computing:Millisecond-latency decision making at sensor nodes collapses traditional three-tier hierarchies.
On-Premises retains dominance at national security facilities. Cloud-Based is climbing the fastest among capital-constrained municipalities.
Application:
Regulatory enforcement intensity varies by application, with effluent discharge standards driving sensor density upgrades faster than irrigation efficiency mandates.
- Wastewater Treatment:Membrane bioreactor automation and chemical dosing control demand precise flow and composition telemetry. EU Urban Wastewater Treatment Directive revisions are accelerating compliance-driven system upgrades across Dutch and Spanish facilities.
- Water Quality Monitoring:Multi-parameter sensor networks track pH, turbidity, and contaminant thresholds in distribution systems. EPA Clean Water Act enforcement is expanding certified SCADA procurement at US municipal plants.
- Pipeline Management:Pressure transient monitoring and leak detection algorithms reduce non-revenue water.
- Flood Control:Real-time rainfall-runoff modeling integrates weather radar with hydraulic infrastructure.
- Irrigation Management:Soil moisture telemetry optimizes agricultural water allocation in water-stressed regions.
- Reservoir Management:Bathymetric and inflow forecasting supports dam safety compliance.
Wastewater Treatment commands the largest installed base. Water Quality Monitoring is gaining share fastest under tightening discharge standards.
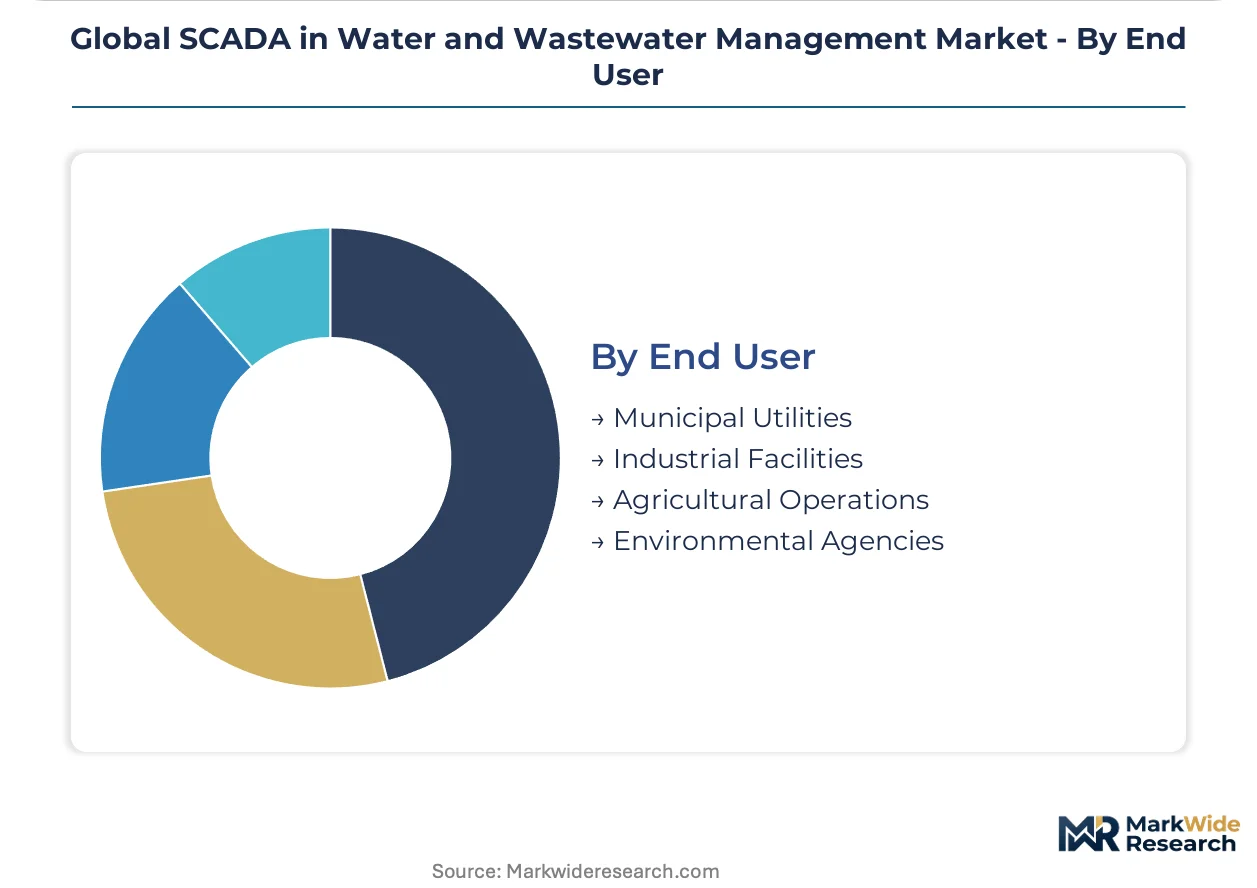
End User:
Procurement sophistication separates municipal utilities with dedicated automation teams from agricultural operators prioritizing plug-and-play field kits.
- Municipal Utilities:Urban water authorities deploy unified SCADA-IoT architectures across treatment, distribution, and collection networks. India's Smart Cities Mission corridors mandate integrated command centers with real-time hydraulic dashboards.
- Industrial Facilities:Food and beverage processors with captive water treatment prioritize batch control integration and audit trail compliance.
- Agricultural Operations:Cooperative irrigation districts adopt solar-powered wireless mesh nodes for remote valve automation.
- Environmental Agencies:Regulatory monitoring stations require tamper-evident data logging for enforcement documentation.
Municipal Utilities account for the dominant share of deployed systems. Industrial Facilities are expanding most quickly as ESG disclosure requirements tighten water stewardship obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor anchors European SCADA modernization for water utilities, with municipal operators replacing legacy copper telemetry under EU cybersecurity mandates. The regional pattern shows concentrated investment in industrialized river basins where aging infrastructure meets stringent discharge compliance.
United States
EPA Water Sector Cybersecurity Initiative evaluations are accelerating IP-native SCADA procurement across Great Lakes municipal utilities. Chicago and Milwaukee metropolitan water districts deploy unified command centers integrating real-time leak detection with chemical dosing automation. The Ohio River Valley treatment corridor shows fastest upgrade velocity as legacy DNP3 assets reach end-of-life.
China
MEE real-time monitoring mandates for wastewater outfalls are expanding certified SCADA deployment across Yangtze River Delta treatment clusters. Shanghai and Jiangsu province utilities integrate edge-native sensor architectures for millisecond-latency chemical composition tracking. National water security protocols enforce air-gapped on-premises configurations at critical reservoir management facilities.
India
Smart Cities Mission corridors in Maharashtra and Karnataka mandate integrated water command centers with SCADA-IoT unified architectures. Mumbai and Bangalore municipal corporations deploy wireless mesh telemetry for non-revenue water reduction in distribution networks. CEA grid-connectivity standards for pumping stations are accelerating certified RTU procurement from European suppliers.
Australia
Murray-Darling basin water utilities pioneer performance-based SCADA service contracts tied to leakage reduction metrics. Sydney and Melbourne metropolitan operators adopt analytics platforms for predictive maintenance scheduling across membrane bioreactor assets. TGA-aligned cybersecurity frameworks are shaping procurement specifications for treatment facility automation upgrades.
Brazil
São Paulo state water utility Sabesp expands cloud-based SCADA deployment to defer capital expenditure on legacy PLC retrofits. Mid-size municipal operators in Minas Gerais adopt SaaS telemetry platforms bypassing fiber trenching requirements. ANVISA-processed industrial facilities integrate batch control SCADA for captive wastewater treatment compliance.
Global SCADA in Water and Wastewater Management Market Competitive Landscape
Strategic partnerships dominate the current landscape as OT-IT convergence forces technology stack consolidation. The vendor base organizes around three tiers: diversified industrial conglomerates with cyber-hardened portfolios, specialized water domain integrators, and edge-native software challengers eroding traditional RTU margins. Two competitive moves define positioning: M&A activity targeting analytics platform capabilities, and vertical integration into sensor manufacturing to secure supply chains against REACH compliance disruptions.
Among European-headquartered industrial conglomerates, Schneider Electric, Siemens, and ABB exemplify distinct archetype strategies. Schneider Electric represents the platform-ecosystem approach through its EcoStruxure architecture. Siemens occupies the deep domain specialization position with membrane bioreactor coupling expertise. ABB anchors the medium-voltage automation segment with synchronized motor control algorithms. These three entities collectively shape certification standards and procurement specifications across municipal utility segments.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens |
| ABB |
| Rockwell Automation |
| Honeywell International |
| Emerson Electric |
| Yokogawa Electric Corporation |
| Mitsubishi Electric |
| General Electric |
| Others |
Supply & Pricing Matrix
Municipal utility mandates for IEC 62443-3-3 SL2 certification are compressing supplier qualification timelines and forcing foundry capacity allocation toward cyber-hardened RTU portfolios, which in turn concentrates pricing power among European semiconductor fabricators serving water infrastructure OEMs.
Pricing Analysis
Input-cost pass-through from fluorine-free polymer reformulation under REACH restrictions is intensifying price pressure across IP67-sealed sensor housings. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels stratifies procurement budgets, with certification grade and volume scale as primary differentiation drivers. Cost compression in the economy tier reflects substitution pressure from cloud-native SaaS telemetry platforms. Mid-size municipal utilities in Southeast Asia exhibit highest price sensitivity, while national water security facilities in China and Saudi Arabia prioritize sovereignty-compliant sourcing over unit economics.
Supply Chain Analysis
Reverse-logistics flows for RTU refurbishment and remanufacturing are expanding as European utilities extend asset life cycles under circular economy procurement rules. Manufacturing concentrates in Germany, France, and Taiwan for cyber-hardened control hardware, with raw material dependencies spanning fluorine-free polymers, industrial-grade silicon, and rare-earth magnet components for motor synchronization. Single-source vulnerability around IEC 62443-certified foundry capacity creates geographic concentration risk. Distribution runs through system integrator channels with long-term service contracts, bypassing direct OEM relationships for municipal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on the shift from capital hardware sales toward subscription telemetry services, enabled by cloud-native architectures that collapse traditional three-tier SCADA hierarchies and reduce field deployment costs.
For Market Incumbents: Lock in certification moats by accelerating IEC 62443-4-2 component-level accreditation ahead of competitor timelines, while capturing aftermarket service revenue through predictive maintenance contracts. Edge-native software challengers threaten traditional RTU margin pools; vertical integration into sensor manufacturing secures supply chain control against REACH compliance disruptions.
For New Entrants and Emerging Players: Wireless mesh telemetry protocols offer a technology-first wedge into Vietnam's Mekong Delta leakage networks and Brazil's capital-constrained mid-size utilities. The most penetrable white space sits in solar-powered edge nodes for agricultural irrigation districts. A SaaS-first go-to-market bypasses fiber trenching capital requirements and accelerates utility adoption cycles.
For Investors and Strategic Acquirers: Asymmetric upside sits with analytics platform specialists possessing hydraulic modeling IP and recurring revenue visibility. Long-term viability favors vendors with demonstrated OT-IT convergence execution across the analysis window. Acquisition targets should demonstrate pre-certified CE marking pathways under the EU Cyber Resilience Act. Monitor IEC 62443 certification backlog durations as an inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Acceleration | Pre-certified IEC 62443-3-3 SL2 RTUs unlock expedited procurement at EU municipal utilities under Cyber Resilience Act timelines. |
| Platform Integration | Unified SCADA-IoT architectures collapse traditional three-tier hierarchies and displace legacy PLC retrofit spending. |
| Strategic Partnership | System integrator alliances with membrane bioreactor OEMs embed control software into wastewater treatment equipment specifications. |
| Acquisition of Specialist Firm | Analytics platform capabilities enable predictive maintenance contracts that monetize operational data for capital planning. |
| Geographic Expansion | Wireless mesh deployments in Southeast Asian leakage networks bypass fiber trenching requirements and capture non-revenue water reduction budgets. |
Research Methodology
Multiple input streams — structured interviews with municipal utility automation directors, SCADA system integrators, and cybersecurity certification auditors, alongside secondary validation from EPA enforcement databases, EU Urban Wastewater Treatment Directive implementation reports, and customs trade flows for industrial control hardware — were reconciled through bottom-up and top-down triangulation.
Historical deployment trajectories across municipal, industrial, and agricultural end-use segments were cross-referenced against panel input from utility procurement officers to model adoption curves. The analytical framework spans solution type, deployment mode, application, and end-user sophistication dimensions throughout the forecast period. CAGRs were derived from segmented penetration modeling calibrated to regulatory mandate enforcement schedules and capital expenditure cycles.
The model holds under continued OT-IT convergence and sustained regulatory enforcement; deviation in certification timeline delays or sovereign air-gap policy reversals would shift vendor competitive positioning. Forecasts reflect documented assumptions regarding technology substitution rates and procurement budget availability. Practitioners should monitor IEC 62443-4-2 accreditation backlogs and REACH fluoropolymer restriction implementation for early signals of supply constraint or cost acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Ecological Wastewater Treatment Market
Water and Wastewater Treatment
Electrocoagulation Market
Water and Wastewater Treatment
Aeration Pads Market
Water and Wastewater Treatment
Water Aeration System Market
Water and Wastewater Treatment
Mobile Wastewater Treatment Plant Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market
Water and Wastewater Treatment
United States Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Sewage Pump Market
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Wastewater Screening Equipment Market
Water and Wastewater Treatment
Global Vertical Sewage Pumps Market
Water and Wastewater Treatment
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Bio Filter Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market
Water and Wastewater Treatment
Commercial Atmospheric Water Generator Market