
 Global Volumetric Cup Fillers Market | 2026-2036
Global Volumetric Cup Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Volumetric Cup Fillers Market Intelligence
REACH compliance is pivoting European equipment procurement toward stainless-steel construction and clean-in-place architectures. IMA Group leverages its Italian manufacturing base to supply certified rotary systems across EU food plants. All-Fill Inc. anchors North American demand with servo-controlled precision lines for spice and powder applications. Spee-Dee Packaging Machinery Inc. competes through specialized cup designs that minimize product giveaway in high-speed cereal operations.
Volumetric cup fillers are precision dispensing machines that measure free-flowing granular, powder, or pellet products into rigid containers using rotating or linear cup assemblies with calibrated cavity volumes, typically achieving fill accuracies within one to two percent of target weight. These systems serve primary packaging lines where consistent dose uniformity and throughput speed determine line efficiency and material yield. Rotary cup configurations occupy the largest installed base due to their mechanical simplicity and proven reliability in 24-hour food production cycles. Electronic technology segments are expanding fastest as programmable logic controllers and servo motor drives replace pneumatic indexing for changeover flexibility and data logging compliance. Piston-assisted cup systems capture premium margin pools in pharmaceutical applications where dust containment and cross-batch cleaning validation are mandatory.
FDA food-contact substance regulations, EU MDR machinery safety directives, and India's BIS electrical standards collectively shape equipment certification requirements and cross-border market access for filler OEMs. The EU F-Gas Regulation additionally pressures pneumatic system designs as manufacturers phase out compressed air actuators in favor of electric alternatives. Stakeholders must monitor evolving national hygiene codes and energy efficiency labeling schemes to align capital expenditure with emerging compliance thresholds.
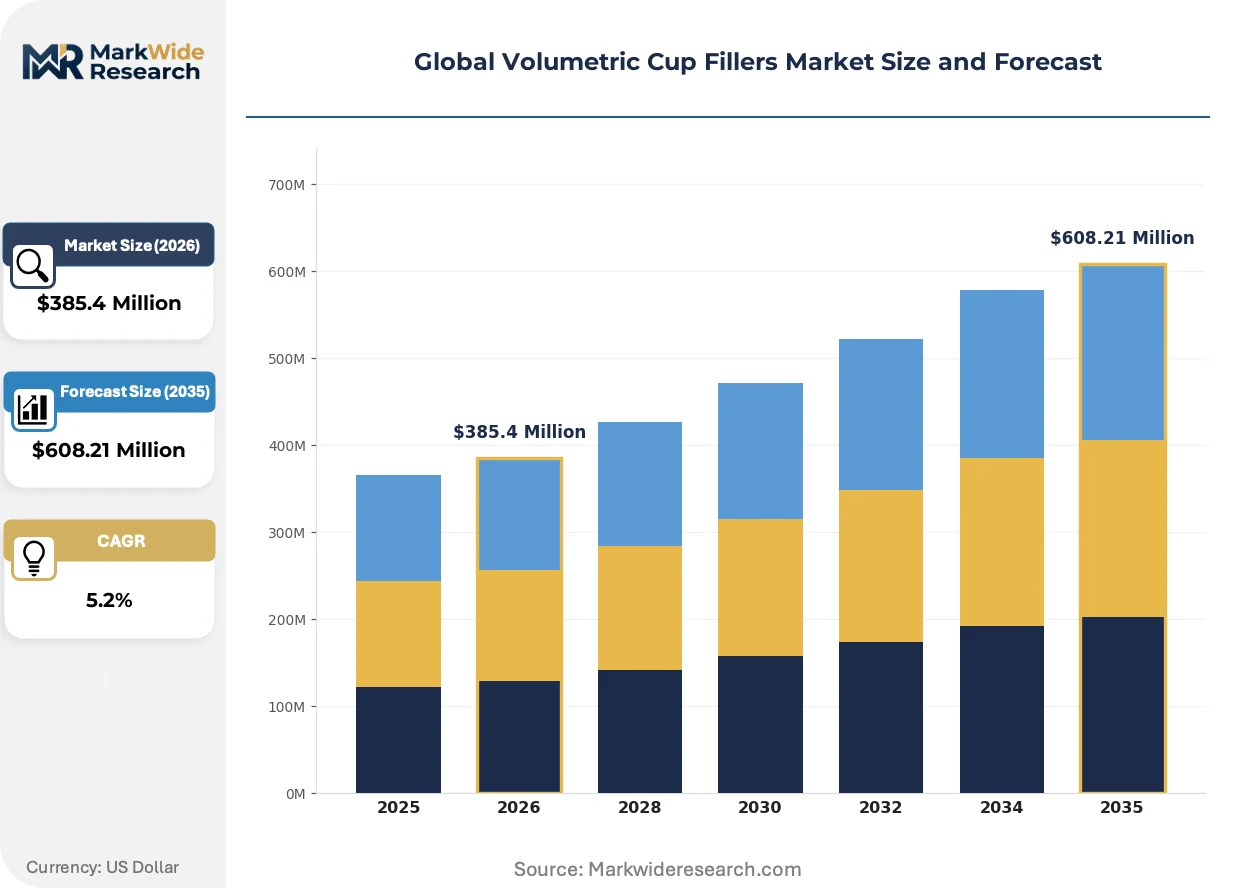
Market Dynamics
Mechanical-to-electric actuator conversion is compressing installed-base economics across food and pharmaceutical packaging corridors, forcing OEMs to reprice service contracts and accelerate retrofit program development.
Growth Catalysts
- Servo motor adoption:Programmable indexing systems reduce changeover downtime from hours to minutes in multi-SKU spice operations. European food-contact regulations now explicitly favor electric drives over pneumatic alternatives in cleanroom-rated lines.
- India's PLI scheme for food processing:Capital subsidies for automated packaging infrastructure are accelerating cup filler procurement in Mumbai-Pune and Gujarat industrial belts. Domestic equipment assemblers are qualifying for tiered incentive thresholds.
- REACH stainless-steel mandates:Chemical safety compliance is disqualifying carbon-steel constructions from EU pharmaceutical tenders. Italian and German OEMs are capturing replacement cycles through pre-certified 316L architectures.
Market Restraints
- Stainless-steel input volatility:Nickel price swings distort quoting timelines for 316L cup assemblies. Smaller fabricators in India and Brazil lack hedging mechanisms to absorb alloy cost spikes.
- Pneumatic component obsolescence:EU F-Gas Regulation phase-out timelines strand compressed-air inventory across installed bases. Retrofit economics favor full replacement over partial upgrade paths.
- Clean-in-place validation complexity:Pharmaceutical batch records require documented residue elimination protocols. Cup cavity geometries with dead zones fail FDA validation, limiting design flexibility.
Strategic Opportunities
- Pharmaceutical dust containment convergence:Integration of vacuum-assisted cup systems with isolator technology addresses potent compound handling. German and Swiss packaging corridors are specifying combined systems for oncology tablet lines.
- Brazilian cereal automation:São Paulo state food safety inspectors are mandating enclosed filling environments for breakfast grain operations. Servo-driven rotary systems with integrated metal detection represent greenfield specification.
- CE-MDR dual certification bundling:Machinery safety and medical device directives now overlap for pharmaceutical filler deployments. OEMs offering unified conformity assessment reduce buyer procurement cycle friction.
Industry Challenges
- Servo commissioning expertise scarcity:Mechanical technicians lack PLC programming proficiency for electronic system startup. Training lags behind equipment shipment volumes in India and Brazil.
- Legacy mechanical spare parts:Pneumatic indexer manufacturers are discontinuing component lines faster than end-of-service predictions. Food plants with 15-year-old rotary systems face unsupported downtime risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Volumetric Cup Fillers Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary, Inline, Gravity, Piston, Servo, Vacuum Technology: Mechanical, Pneumatic, Electronic, Automated, Manual, Semi-automated Application: Food Processing, Beverage Bottling, Cosmetics Production, Pharmaceutical Packaging, Chemical Filling, Personal Care End User: Contract Manufacturers, Packaging Firms, Filler Manufacturers, Food & Drink Companies, Pharma Producers, Cosmetic Brands |
| Companies Covered | IMA Group, All-Fill Inc., Spee-Dee Packaging Machinery Inc., AMS Filling Systems, Frain Industries, Inline Filling Systems, Yeaman Machine Technologies Inc., Mespack SL, AVS Pack Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Volumetric Cup Fillers Market Strategic Shifts & Innovations
Actuator electrification is rewriting equipment lifecycle economics while regulatory chemistry mandates reshape material specifications. Data logging requirements are embedding traceability hardware as standard rather than optional configuration.
Brushless servo motor systems with integrated torque feedback are expanding into high-speed cereal and snack packaging lines. Brazilian and Indian food processors are specifying these drives for 400+ cup-per-minute rotary configurations. The technology is expanding into mid-market price tiers previously served by mechanical indexing, compressing pneumatic system residual values.
EU F-Gas Regulation phase-out schedules are accelerating electric actuator adoption in cleanroom pharmaceutical environments. Compressed-air system carbon footprint disclosures now factor into German and Dutch capital expenditure approval workflows. Pneumatic cup filler OEMs are repositioning remaining inventory toward non-EU markets with deferred environmental compliance timelines.
Outcome-based service contracting is displacing traditional time-and-materials maintenance in North American spice and powder operations. Buyers are demanding guaranteed uptime percentages with penalty clauses for unplanned stoppages. This procurement recalibration concentrates service revenue among OEMs with remote diagnostics infrastructure and regional parts depots.
Global Volumetric Cup Fillers Market Segmentation
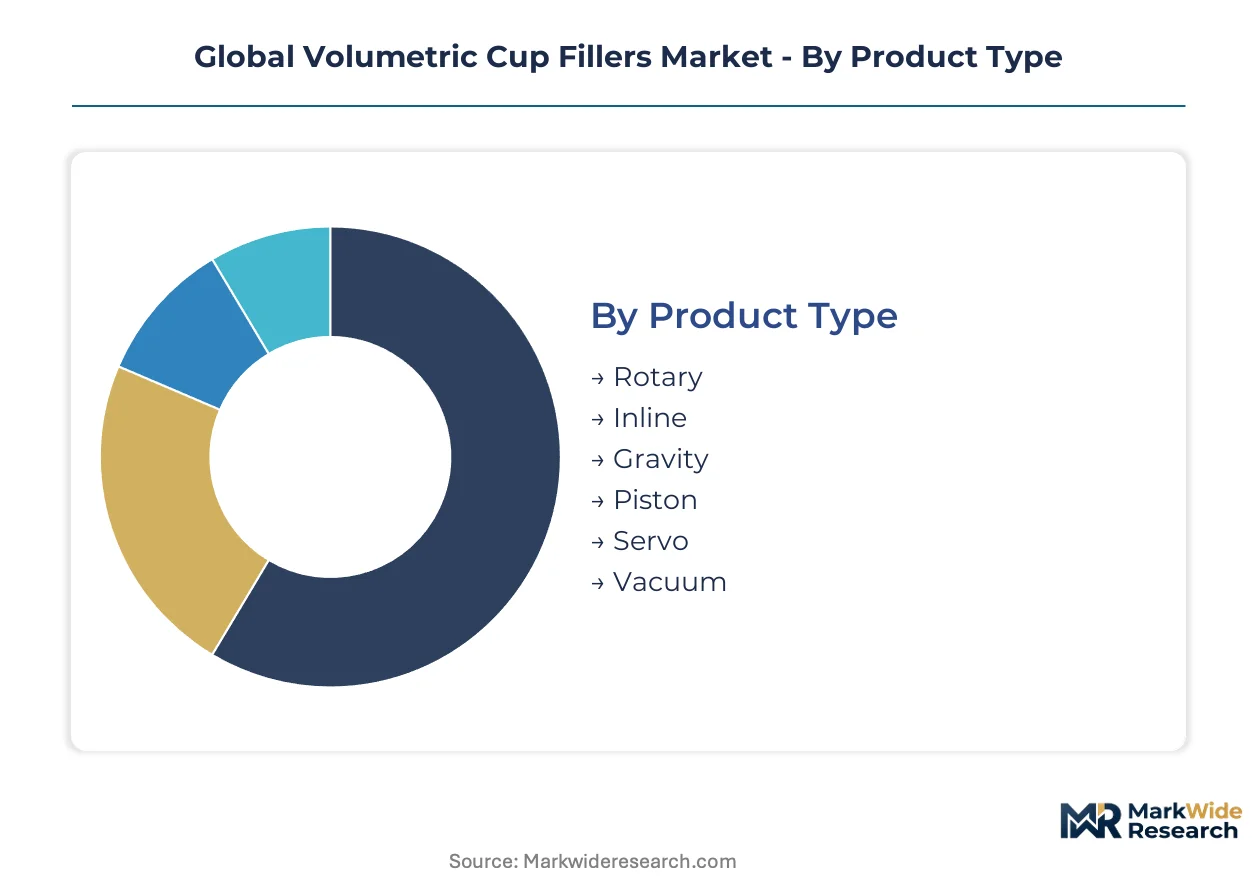
Volumetric cup filler procurement decisions hinge on certification alignment, throughput requirements, and changeover flexibility. Segmentation reveals where regulatory burdens concentrate and which configurations command premium positioning across food, pharmaceutical, and chemical corridors.
Product Type:
REACH and FDA validation requirements map unevenly across mechanical architectures, with stainless-steel rotary systems facing the heaviest documentation burdens for pharmaceutical tenders.
- Rotary:Circular turret configurations with 8-24 stations achieve 400+ fills per minute in cereal and snack operations. German and Brazilian food processors specify these for 24-hour production cycles where mechanical simplicity reduces downtime risk.
- Servo:Brushless motor drives with programmable indexing replace pneumatic actuators for sub-minute changeovers. Mumbai pharmaceutical corridors are specifying these for multi-SKU tablet lines where batch records require electronic data logging.
- Inline:Linear cup arrangements suit space-constrained packaging halls with lower throughput requirements.
- Gravity:Free-flow discharge mechanisms handle coarse granular products without mechanical agitation.
- Piston:Assisted compression systems capture dust-prone pharmaceutical powders requiring isolator integration.
- Vacuum:Negative-pressure cup cavities address potent compound containment in oncology packaging suites.
Rotary sits at the top of the volume ranking, with Servo climbing the fastest.
Technology:
Cost tiers separate capital-intensive electronic installations from maintenance-heavy mechanical legacy bases, with pneumatic systems stranded in a contracting middle band.
- Electronic:PLC-controlled servo architectures with torque feedback and recipe storage command premium pricing in cleanroom-rated lines. EU F-Gas Regulation is disqualifying compressed-air alternatives from new pharmaceutical tenders.
- Mechanical:Cam-driven indexing with fixed stroke lengths dominates installed-base economics in mature spice processing corridors. Indian contract manufacturers retain these for single-SKU operations where changeover frequency remains low.
- Pneumatic:Compressed-air actuators face component obsolescence as OEMs discontinue indexer lines.
- Automated:Fully integrated lines with upstream feeding and downstream capping reduce labor touchpoints.
- Semi-automated:Operator-assisted loading suits batch-scale cosmetic and personal care operations.
- Manual:Hand-cranked cup assemblies persist in artisanal food and micro-batch chemical applications.
Electronic captures the steepest expansion trajectory, while Mechanical retains the largest installed base.
Application:
Application segmentation tracks hygiene mandate intensity, with pharmaceutical and food processing corridors facing the strictest residue elimination protocols.
- Food Processing:Spice, cereal, and powder operations in São Paulo and Gujarat industrial belts specify servo rotary systems for enclosed filling environments. Brazil's state-level food safety inspectors are mandating metal detection integration.
- Pharmaceutical Packaging:Tablet and capsule lines in Mumbai-Pune and Rhine-Ruhr clusters require 316L construction, clean-in-place validation, and batch record traceability.
- Beverage Bottling:Granular drink mix operations favor gravity and inline configurations.
- Chemical Filling:Industrial powder and pellet handling prioritizes explosion-rated electrical enclosures.
- Cosmetics Production:Color powder and talc operations specify dust containment for operator exposure limits.
- Personal Care:Bath salt and detergent pod filling runs at lower speeds with semi-automated loading.
Food Processing leads absolute unit demand, with Pharmaceutical Packaging expanding most quickly.
End User:
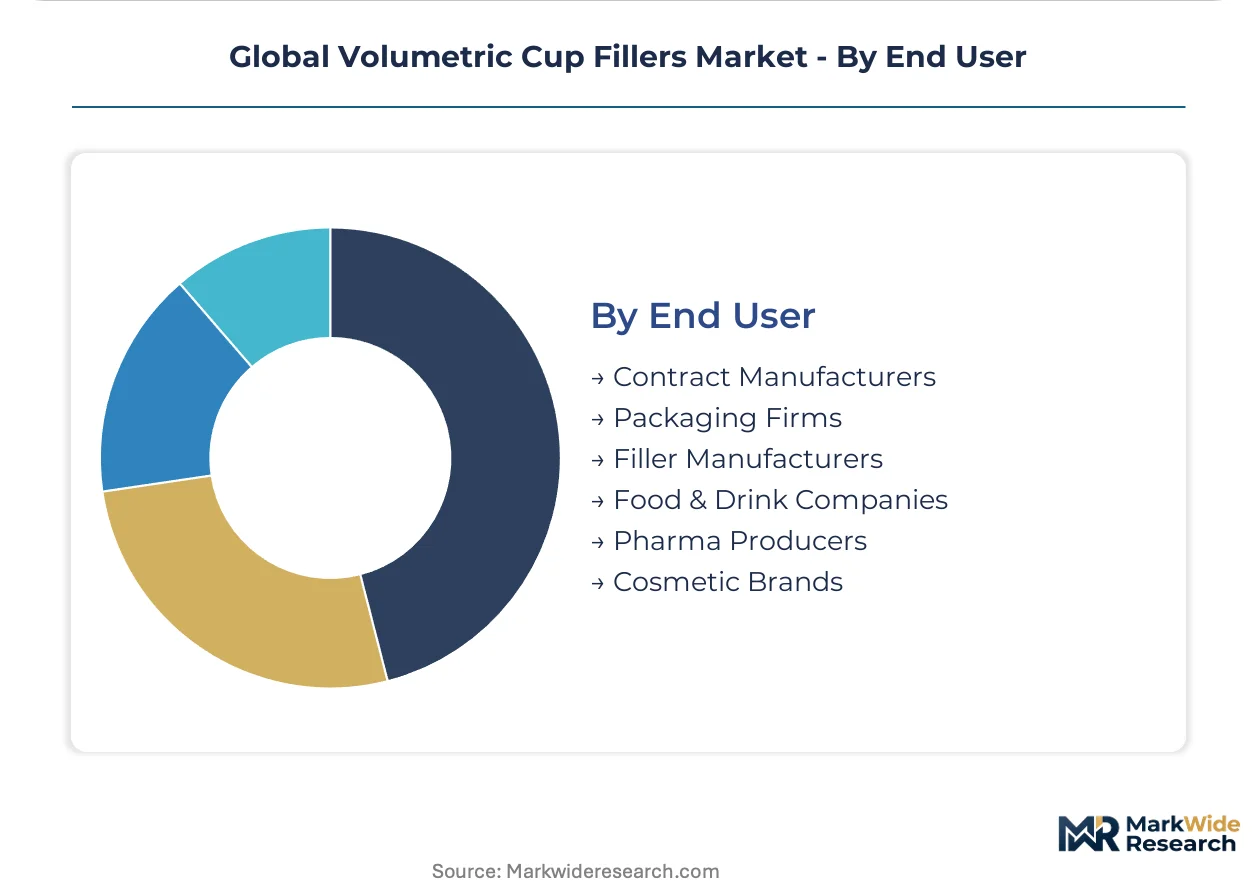
Customer type determines procurement authority concentration, with contract manufacturers consolidating specification influence across multiple brand portfolios.
- Contract Manufacturers:Multi-client packaging operations in India and Brazil aggregate demand for flexible servo systems. These buyers prioritize changeover speed over single-purpose throughput.
- Pharma Producers:Integrated pharmaceutical manufacturers in Germany and Switzerland specify combined cup filler-isolator systems for potent compound handling.
- Packaging Firms:Dedicated co-packers serving regional food brands favor mid-speed rotary configurations.
- Food & Drink Companies:Cereal and spice brand owners specify integrated lines with upstream metal detection.
- Filler Manufacturers:OEMs building complete packaging lines source cup modules for system integration.
- Cosmetic Brands:Beauty and personal care companies with captive production specify semi-automated units for color powder batching.
Contract Manufacturers sit at the top of the volume ranking, with Pharma Producers climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment engineering talent pools in Germany, Italy, and Switzerland anchor European precision manufacturing for pharmaceutical-grade cup filler systems. Indian and Brazilian technical workforces are scaling automated packaging infrastructure under national incentive programs. These workforce concentrations shape regional procurement patterns and technology adoption trajectories.
Germany
Rhine-Ruhr industrial clusters demand servo-driven rotary systems for 24-hour cereal and spice operations. REACH compliance mandates stainless-steel 316L construction, disqualifying carbon-steel alternatives from pharmaceutical tenders. Bavarian packaging OEMs supply certified equipment across EU food plants with integrated clean-in-place validation.
India
Mumbai-Pune pharmaceutical corridors specify electronic cup fillers with PLC-controlled data logging for batch record compliance. The PLI scheme for food processing delivers capital subsidies accelerating procurement in Gujarat industrial belts. Domestic equipment assemblers qualify for tiered incentive thresholds while scaling servo system production.
Brazil
São Paulo state food safety inspectors mandate enclosed filling environments for breakfast grain operations. ANVISA pharmaceutical regulations drive demand for dust containment systems in tablet packaging suites. Servo-driven rotary configurations with integrated metal detection dominate greenfield cereal automation projects.
United States
Spice and powder processors in Midwest packaging hubs specify servo-controlled precision lines for multi-SKU flexibility. FDA food-contact substance regulations shape equipment certification requirements for cross-border market access. Outcome-based service contracting with guaranteed uptime percentages displaces traditional maintenance models.
Switzerland
Swissmedic pharmaceutical standards require combined cup filler-isolator systems for potent compound handling. Basel and Zurich packaging corridors specify vacuum-assisted cup technology for oncology tablet lines. German and Swiss OEMs capture premium margin pools through CE-MDR dual certification bundling.
Global Volumetric Cup Fillers Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the volumetric cup filler supply base. Italian and German diversified industrial groups leverage integrated manufacturing footprints to bundle machinery safety certifications. Pure-play specialists concentrate on servo-driven electronic architectures for pharmaceutical cleanroom applications. Tiered competitive dynamics separate premium-certified system integrators from mid-market fabricators serving single-SKU food operations. Strategic moves concentrate on retrofit program development for pneumatic installed bases and geographic expansion into PLI-subsidized Indian corridors.
Within the diversified machinery tier, IMA Group represents integrated European manufacturing capabilities spanning rotary and servo configurations. All-Fill Inc. and Spee-Dee Packaging Machinery Inc. exemplify North American specialization in precision dosing systems for granular and powder applications. These three anchors demonstrate how geographic origin and organizational structure map to distinct service models across food and pharmaceutical end markets.
| Leading Market Players |
|---|
| IMA Group |
| All-Fill Inc. |
| Spee-Dee Packaging Machinery Inc. |
| AMS Filling Systems |
| Frain Industries |
| Inline Filling Systems |
| Yeaman Machine Technologies Inc. |
| Mespack SL |
| AVS Pack Tech |
| Others |
Cost & Logistics Intelligence
REACH stainless-steel mandates from European pharmaceutical buyers are forcing fabricators to absorb nickel alloy volatility or lose tender eligibility, compressing margin buffers across 316L cup assembly suppliers. This specification-driven procurement pressure concentrates pricing power with Italian and German OEMs holding pre-certified architectures, while Indian and Brazilian fabricators face quoting timeline distortions from unhedged raw material exposure.
Pricing Analysis
Bundled outcome-based service contracts now command premium positioning over unbundled equipment-only transactions across North American spice operations. Three-tier pricing structure across premium certified, standard compliant, and economy mechanical tiers reflects divergence in data logging capability and clean-in-place validation depth. Pricing pressure stems from servo system commoditization as brushless motor costs decline and mid-market electronic configurations displace pneumatic alternatives. Contract manufacturers in India and Brazil exhibit highest price sensitivity due to PLI scheme capital subsidy dependency, while Swiss and German pharma producers prioritize CE-MDR dual certification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Italian and German precision machining clusters for pharmaceutical-grade 316L cup turret assemblies. Component sourcing draws from Chinese rare-earth magnet suppliers for servo motors, Indian stainless-steel rolling mills for 316L sheet stock, and German PLC controller manufacturers for electronic system brains. Supply chain risk centers on nickel price volatility transmitted through alloy surcharges without hedging mechanisms at smaller fabricators. Distribution runs through OEM direct sales for pharmaceutical cleanroom lines and regional equipment distributors for food processing retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU regulatory compliance premiums and Indian PLI-subsidized production cost bases, with stainless-steel specification differentials creating divergent margin pools across identical mechanical architectures.
For Market Incumbents: Deepen captive 316L machining capacity in Italian and German manufacturing footprints to defend against Asian fabricators qualifying for REACH-equivalent certifications. Accelerate retrofit program development for stranded pneumatic installed bases before component obsolescence triggers unsupported downtime claims. Certification investment in CE-MDR dual assessment bundling creates switching costs for pharmaceutical procurement committees.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in servo rotary systems for Brazilian cereal automation offers white-space entry below IMA Group and All-Fill Inc. positioning. Target São Paulo state food safety inspector mandates for enclosed filling environments as the most penetrable regulatory-driven replacement cycle. Pursue private-label supply relationships with domestic Indian equipment assemblers qualifying for PLI tiered incentives rather than direct OEM competition.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap servo system specialists holding pharmaceutical cleanroom references but lacking geographic diversification. Five-to-ten year viability hinges on electronic actuator penetration rates overtaking mechanical legacy depreciation schedules. Watch for ANVISA and FSSAI regulatory harmonization signals as inflection indicators for cross-regional equipment standardization plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Retrofit Program Development | Captures stranded pneumatic installed base value before component obsolescence accelerates. |
| CE-MDR Dual Certification Bundling | Reduces procurement cycle friction for German and Swiss pharmaceutical packaging corridors. |
| Backward Integration into 316L Machining | Insulates margin from nickel alloy surcharge volatility in cup turret production. |
| Geographic Expansion into PLI-Subsidized India | Leverages capital subsidies accelerating automated packaging infrastructure procurement. |
| Outcome-Based Service Contracting | Aligns revenue with guaranteed uptime percentages demanded by North American spice processors. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary field engagement with plant engineers, OEM procurement teams, aftermarket service heads, and food safety compliance officers against secondary validation through EU F-Gas Regulation filings, FDA food-contact substance registrations, BIS electrical standard certifications, and SEC equipment manufacturer disclosures. Bottom-up installation tracking across Mumbai-Pune, Rhine-Ruhr, and São Paulo industrial corridors triangulated against top-down OEM shipment aggregation.
Segment-weighting distributed analytical emphasis across rotary, servo, and inline product architectures; electronic, mechanical, and pneumatic technology tiers; and food processing, pharmaceutical packaging, and chemical filling application corridors. CAGRs derived from equipment replacement cycle modeling, regulatory phase-out timeline alignment, and national incentive program disbursement schedules across the projection horizon. Forecast inputs incorporated nickel alloy price trajectory assumptions and servo motor cost decline curves.
Caveats apply where EU F-Gas Regulation enforcement intensity or PLI scheme renewal decisions could materially shift the outlook. Forecasts reflect documented assumptions about regulatory harmonization timelines and raw material price stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Global Blow Molding Machine Market
Packaging Machinery
Foil Embossing Machine Market
Packaging Machinery
Vial Filling and Capping Machines Market
Packaging Machinery
Cartridge Filling System Market
Packaging Machinery
Aseptic Filling Machines Market
Packaging Machinery
Capsule Filling Machines Market
Packaging Machinery
Wraparound Case Packers Market
Packaging Machinery
Kraft Paper Machines Market
Packaging Machinery
Oil Packing Machine Market
Packaging Machinery
Case Packing Machines Market
Packaging Machinery
Side Load Case Packing Machines Market
Packaging Machinery
Plastic Extruding Equipment Market
Packaging Machinery
Twist Tie Machines Market
Packaging Machinery
Pouch Packaging Machine Market
Packaging Machinery
Carton Folding and Gluing Machine Market