
 Cartridge Filling System Market | 2026-2036
Cartridge Filling System Market Size, Share, and Industry Trends Forecast 2026-2036
Cartridge Filling System Market Analytics
Aftermarket service revenue is fragmenting across the cartridge filling system landscape as OEMs and third-party providers compete for calibration contracts and spare parts. Syntegon Technology GmbH leverages its installed base in Europe to sustain long-term service agreements. IMA Group anchors its position through integrated line solutions spanning filling, capping, and labeling. Marchesini Group specializes in high-speed rotary fillers for biopharmaceutical applications, occupying a distinct tier in sterile processing.
A cartridge filling system is precision equipment designed to dispense liquid, semi-solid, or powder formulations into pre-formed cartridges with dosing accuracy typically within plus or minus one percent, employing servo-driven piston mechanisms or peristaltic pumps under laminar airflow conditions. Its primary purpose is to ensure sterile, aseptic, or clean-fill processing for injectable drugs, cosmetics, and food-grade products where contamination control and dose uniformity are critical. Automated fillers command the dominant share of capital expenditure as pharmaceutical manufacturers pursue line speeds exceeding 600 units per minute, while custom systems capture the fastest-growing margin pool by addressing cell and gene therapy formats with flexible batch sizes. Piston fillers lead in viscous biologic applications where shear-sensitive proteins require gentle displacement, and vacuum fillers gain traction in cosmetic fragrance packaging to prevent oxidation and bubble formation.
FDA enforces current Good Manufacturing Practice requirements under 21 CFR Parts 210 and 211, mandating validated cleaning protocols and electronic batch records that shape equipment specification decisions for US-bound production. EMA oversees compliance with EU GMP Annex 1 on sterile medicinal products, driving demand for isolator-integrated filling lines and single-use fluid path technologies across European manufacturing sites. ISO 13485 quality management standards for medical devices influence design documentation and risk management for systems producing combination drug-device products. Stakeholders must weigh total cost of ownership against regulatory pathway complexity when selecting between standardized platforms and bespoke configurations.
Market Dynamics
EU GMP Annex 1 revisions are compressing equipment replacement cycles as pharmaceutical manufacturers face mandatory isolator integration and single-use fluid path mandates, forcing capital redeployment toward validated aseptic processing architectures.
Growth Catalysts
- Biologics pipeline expansion:Cell and gene therapy formats require flexible batch processing that standard rotary fillers cannot accommodate. Contract manufacturing organizations in Switzerland and Germany are commissioning modular piston systems to handle shear-sensitive proteins.
- FDA 21 CFR Part 11:Electronic batch record mandates drive replacement of legacy mechanical fillers with servo-driven platforms capable of automated data integrity logging. US-based sterile injectables producers face audit pressure to upgrade.
- Peristaltic pump advancement:Improved tubing materials enable gentle handling of high-viscosity biologics without piston shear. This technology is displacing traditional displacement methods in cosmetic fragrance applications where oxidation prevention matters.
Market Restraints
- Stainless steel supply concentration:Pharmaceutical-grade 316L stainless sourcing clusters in German and Italian mill networks. Tariff volatility and energy cost spikes at these production nodes transmit directly to equipment lead times.
- Isolator integration complexity:EU GMP Annex 1's 2023 revision mandates physical separation between operators and sterile zones. Retrofitting existing cleanrooms with restricted access barrier systems requires facility downtime that manufacturers resist.
- Pre-filled syringe substitution:Drug-device combination products in diabetes and auto-immune categories increasingly bypass cartridges entirely. This format shift constrains addressable volume in chronic disease therapeutic segments.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's tightening sterile facility inspections and PLI scheme incentives for active pharmaceutical ingredient production create demand for import-substituting filling equipment with local service support.
- Continuous processing convergence:Integration of real-time release testing with inline weighing and machine vision is digitizing quality assurance workflows. Early adopters in Swiss biologics manufacturing are compressing batch release timelines.
- Cosmetic fragrance premiumization:Vacuum filler technology prevents bubble formation and oxidation in high-value perfume cartridges. French and Italian luxury houses are specifying these systems for limited-edition launches.
Industry Challenges
- Mechatronics talent scarcity:Servo-driven piston mechanisms require cross-functional expertise spanning fluid dynamics, software validation, and sterile engineering. German equipment builders report 14-month recruitment cycles for commissioning specialists.
- Legacy system integration friction:Brownfield pharmaceutical sites operate mechanical fillers with 20-plus year service lives. Replacing these with automated platforms demands line reconfiguration that disrupts validated production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cartridge Filling System Market |
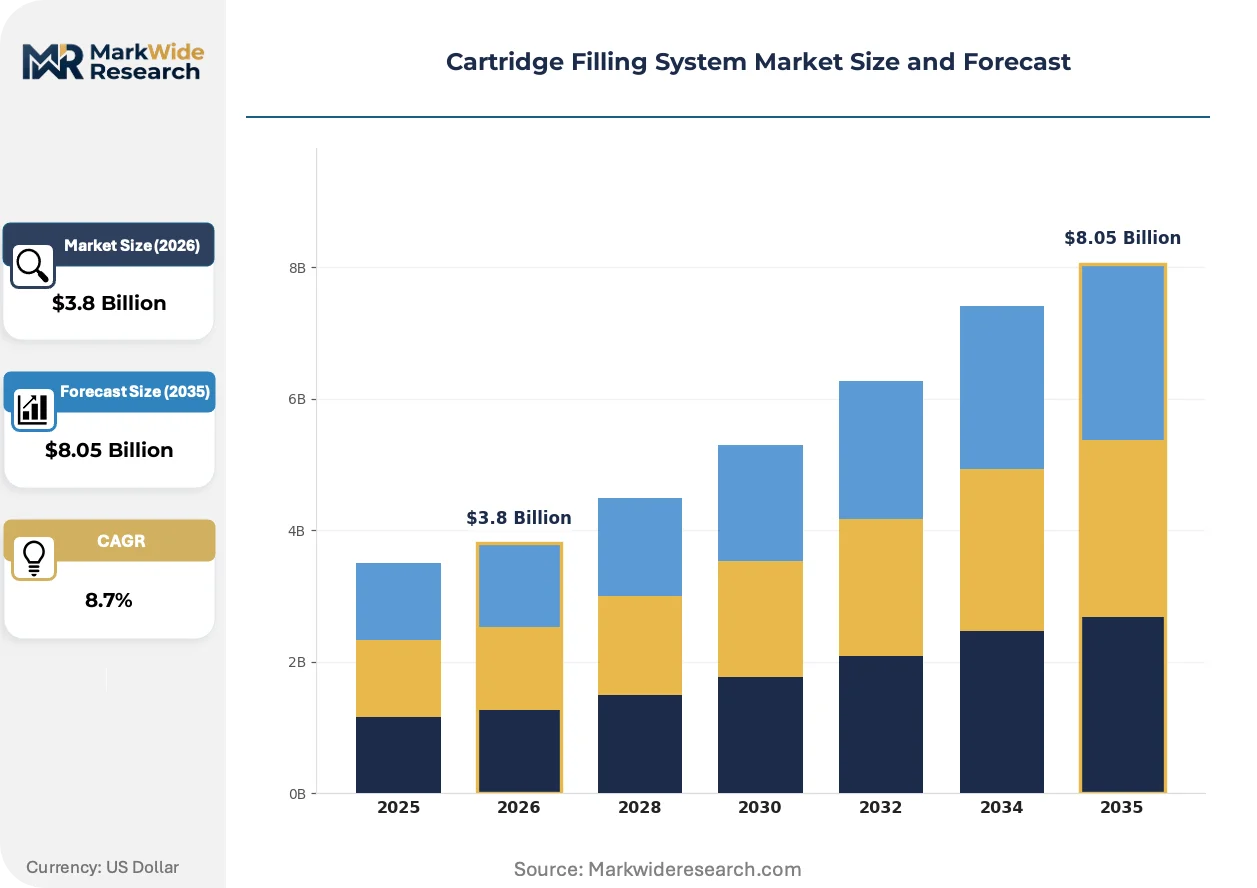
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Fillers, Semi-Automated Fillers, Manual Fillers, Custom Systems End User: Pharmaceutical Companies, Cosmetics Manufacturers, Food & Beverage Producers, Contract Packers Filling Technology: Piston Fillers, Vacuum Fillers, Gravity Fillers, Pressure Fillers Container Type: Glass Bottles, Plastic Cartridges, Aluminium Canisters, Bag-in-Box Solutions |
| Companies Covered | Syntegon Technology GmbH, IMA Group, Dara Pharmaceutical Packaging, Filamatic, Coesia, ProSys Servo Filling Systems, Marchesini Group, Bosch Packaging Technology, Romaco Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cartridge Filling System Market Evolving Landscape
Machine learning algorithms are penetrating process control architectures, enabling predictive maintenance and real-time dosing correction that reduces rejected units during format changeovers.
Inline spectroscopic inspection is digitizing quality assurance by replacing offline sampling with continuous verification of fill weight and particulate contamination. Biopharmaceutical contract manufacturers in Germany and Switzerland are piloting these systems to compress batch release documentation. The technology is compressing the traditional separation between production and quality control functions.
EMA's updated EU GMP Annex 1 imposes stricter environmental monitoring and contamination control requirements on sterile medicinal product manufacturing. European facilities must implement isolator-integrated filling lines or demonstrate equivalent contamination control through risk assessment. High-speed rotary filler deployments in Italian and French pharmaceutical plants are accelerating to meet these compliance deadlines.
Service contract unbundling is fragmenting aftermarket relationships as end-users seek specialized calibration providers independent of original equipment manufacturers. Pharmaceutical procurement teams in the United States are disaggregating spare parts, preventive maintenance, and validation support into separate vendor relationships. This pattern is most visible among mid-scale generic injectables producers optimizing total cost of ownership across mixed equipment fleets.
Cartridge Filling System Market Segmentation
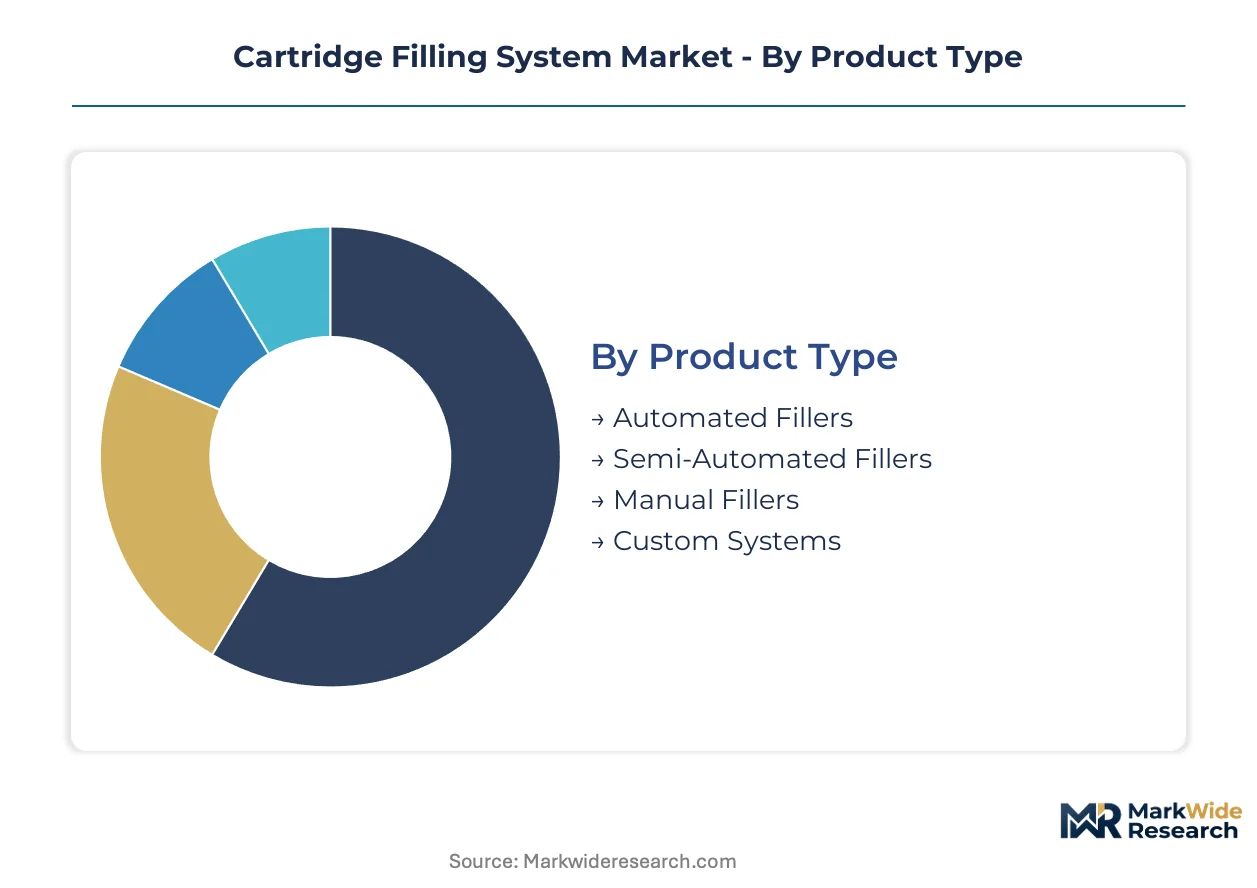
Segmentation in cartridge filling systems reveals distinct capital deployment cycles across equipment tiers. Pharmaceutical procurement teams prioritize cycle-time compression in high-volume sterile lines while cosmetic and food applications tolerate longer amortization periods on semi-automated platforms.
Product Type:
Cycle times vary dramatically across automation tiers, with fully automated platforms turning over every 5-7 years under FDA audit pressure while manual systems persist for 15-plus years in emerging manufacturing bases.
- Automated Fillers:Servo-driven platforms integrate electronic batch recording and isolator-ready architectures for aseptic processing. Demand concentrates at sterile injectables facilities in Germany and Switzerland where EMA's Annex 1 revisions compress replacement timelines.
- Custom Systems:Modular piston configurations accommodate cell and gene therapy batch formats with flexible changeover protocols. Swiss contract manufacturing organizations commission these for shear-sensitive protein handling where standard rotary fillers fail.
- Semi-Automated Fillers:Hybrid platforms bridge mechanical reliability with selective automation for mid-scale generic producers.
- Manual Fillers:Benchtop displacement units serve pilot-scale biologics development and compounding pharmacy operations.
Automated fillers anchor the volume base while custom systems gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive pharmaceutical validation requirements from cosmetic and food-grade specifications where equipment expenditure concentrates at lower price points.
- Pharmaceutical Companies:Sterile injectables producers demand 21 CFR Part 11 compliant data integrity architectures with isolator integration. FDA audit frequency in the United States drives replacement of legacy mechanical fillers with servo-driven platforms.
- Contract Packers:Multi-format flexibility requirements prioritize rapid changeover capability across mixed product portfolios. German and Italian third-party fillers specify modular lines to accommodate cosmetic fragrance and food-grade contracts simultaneously.
- Cosmetics Manufacturers:Vacuum filler specifications dominate high-value perfume cartridge production for oxidation prevention.
- Food & Beverage Producers:Clean-fill standards without sterile validation requirements enable longer equipment depreciation schedules.
Pharmaceutical companies anchor the volume base while contract packers gain share at the steepest rate.
Filling Technology:
Application-specific fluid dynamics determine technology selection, with shear-sensitive biologics demanding gentle displacement while cosmetic formulations prioritize oxidation control.
- Piston Fillers:Positive displacement mechanisms handle viscous biologics with dosing accuracy within plus or minus one percent. German biopharmaceutical manufacturing clusters specify these for monoclonal antibody production where protein integrity preservation overrides speed considerations.
- Vacuum Fillers:Sub-atmospheric filling prevents bubble formation and oxidation in oxygen-sensitive formulations. French and Italian luxury fragrance houses deploy these for limited-edition perfume cartridge launches where product integrity commands premium positioning.
- Gravity Fillers:Passive flow systems serve low-viscosity liquid applications with minimal mechanical complexity.
- Pressure Fillers:Forced displacement accommodates high-viscosity semi-solids in topical pharmaceutical preparations.
Piston fillers anchor the volume base while vacuum fillers gain share at the steepest rate.
Container Type:
Material compatibility requirements with sterilization protocols create distinct specification tiers across glass, plastic, and metal substrates.
- Glass Bottles:Borosilicate and treated soda-lime formulations provide inert surfaces for parenteral drug stability. Swiss and German sterile injectables facilities specify Type I borosilicate for biologics requiring thermal shock resistance during autoclave sterilization.
- Plastic Cartridges:Cyclic olefin polymer and polypropylene formats reduce breakage risk in self-injection devices. United States diabetes therapeutic producers specify these for pen-injector compatibility where patient handling durability matters.
- Aluminium Canisters:Barrier properties suit pressurized and light-sensitive formulations in cosmetic and pharmaceutical aerosols.
- Bag-in-Box Solutions:Flexible containment reduces shipping volume for bulk liquid food and beverage concentrates.
Glass bottles anchor the volume base while plastic cartridges gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across procurement contexts. German and Swiss pharmaceutical buyers absorb premium equipment costs for regulatory compliance, while Indian and Brazilian manufacturers prioritize total cost of ownership and local service availability.
Germany
Sterile injectables producers in Baden-Württemberg and Bavaria drive demand for isolator-integrated filling lines. EU GMP Annex 1 revisions mandate physical separation between operators and sterile zones, accelerating capital redeployment. The Stuttgart precision engineering cluster houses servo-driven piston system specialists serving monoclonal antibody manufacturing.
Switzerland
Contract manufacturing organizations in Basel and Zurich commission modular systems for cell and gene therapy batches. Swissmedic oversight of combination drug-device products enforces ISO 13485 documentation standards. The Basel biopharma corridor concentrates demand for flexible changeover protocols handling shear-sensitive proteins.
United States
FDA audit pressure on sterile injectables facilities drives replacement of legacy mechanical fillers with 21 CFR Part 11 compliant platforms. The Boston-Cambridge biotech cluster and New Jersey pharmaceutical corridor dominate capital deployment. Electronic batch record mandates compress replacement cycles for servo-driven architectures.
India
CDSCO's tightening sterile facility inspections and PLI scheme incentives for active pharmaceutical ingredient production create demand for import-substituting equipment. Maharashtra and Gujarat pharmaceutical manufacturing zones prioritize local calibration support and spare parts availability. Domestic contract manufacturers seek mid-tier automation bridging manual and fully automated platforms.
Italy
Cosmetic fragrance and pharmaceutical packaging equipment demand concentrates in Emilia-Romagna and Lombardy. High-speed rotary filler deployments accelerate to meet EU GMP Annex 1 compliance deadlines. Bologna-area manufacturers supply vacuum filler technology to French and Italian luxury houses for limited-edition perfume launches.
Cartridge Filling System Market Competitive Landscape
Capability concentration sits with precision engineering specialists; scale advantage sits with diversified packaging machinery conglomerates. The market structures around three tiers: European precision fabricators with sterile processing expertise, integrated line solution providers spanning filling-to-labeling workflows, and regional specialists serving cost-sensitive emerging markets. Consolidation pressure operates through technology licensing partnerships and selective geographic expansion rather than horizontal mergers.
Within the European precision tier, Syntegon Technology GmbH and Marchesini Group exemplify divergent strategic positions. Syntegon leverages its installed base to sustain long-term service agreements across German and Swiss pharmaceutical corridors. Marchesini occupies a distinct position in high-speed rotary applications for biopharmaceutical processing. IMA Group represents the integrated-line archetype, anchoring competitive positioning through spanning architectures that consolidate filling, capping, and labeling workflows for pharmaceutical manufacturers seeking single-source accountability.
| Leading Market Players |
|---|
| Syntegon Technology GmbH |
| IMA Group |
| Dara Pharmaceutical Packaging |
| Filamatic |
| Coesia |
| ProSys Servo Filling Systems |
| Marchesini Group |
| Bosch Packaging Technology |
| Romaco Group |
| Others |
Value Network & Pricing Analysis
Overcapacity in European precision engineering clusters is compressing margins for servo-driven piston system builders, forcing suppliers to bundle long-term calibration contracts with equipment sales while buyers in India and Brazil exploit this softness to negotiate extended payment terms.
Pricing Analysis
Aftermarket service revenue tiers—spanning spare parts, preventive maintenance, and validation support—drive lifetime value capture for original equipment manufacturers. Three-tier pricing structure across premium isolator-integrated lines, standard rotary platforms, and economy semi-automated units separates FDA-validated pharmaceutical specifications from cosmetic-grade alternatives. Pricing pressure stems from unbundling trends as procurement teams disaggregate service contracts to specialized third-party calibrators. Generic injectables producers in emerging manufacturing bases exhibit highest price sensitivity, while Swiss and German biologics manufacturers absorb premium costs for Annex 1 compliance.
Supply Chain Analysis
Export-control restrictions on precision motion-control components limit flows of servo motors and linear encoders to certain manufacturing destinations. Pharmaceutical-grade 316L stainless steel sourcing clusters in German and Italian mill networks, with cyclo-olefin polymer cartridges and peristaltic pump tubing as critical dependencies. Tariff exposure on European steel inputs creates lead time volatility that transmits to equipment delivery schedules. Distribution runs through direct OEM sales for large pharmaceutical accounts and specialized distributors serving mid-scale contract packers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pharmaceutical procurement teams as service contract unbundling fragments traditional OEM relationships, with mid-scale generic producers consolidating vendor selection authority across mixed equipment fleets.
For Market Incumbents: Harden installed-base defenses by converting episodic spare parts sales into multi-year calibration subscriptions with Swiss and German biopharmaceutical corridors. Deepen backward integration into precision machining capabilities to reduce exposure to 316L stainless supply concentration in Italian mill networks. Pre-filled syringe substitution in diabetes therapeutics threatens cartridge addressable volume; counter with flexible format-changeover architectures that accommodate both container types.
For New Entrants and Emerging Players: Build out localized service capabilities in Maharashtra and Gujarat pharmaceutical zones where CDSCO inspection tightening creates demand for import-substituting equipment with domestic calibration support. Target contract packers seeking rapid changeover flexibility across mixed cosmetic and food-grade portfolios. Lead with modular piston configurations for cell and gene therapy batches where standard rotary fillers fail.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision fabricators with captive service networks in sterile processing corridors. Five-to-ten-year viability favors equipment builders with isolator-integration expertise as EU GMP Annex 1 revisions compress replacement cycles. Target acquisition archetype: European mid-cap specialists with ISO 13485 documentation capabilities and established Swissmedic relationships. Watch for inflection in brownfield retrofit momentum as FDA audit pressure accelerates legacy mechanical filler replacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Integration Partnership | EMA Annex 1 compliance deadlines in Italian and French facilities drive demand for physical separation architectures. |
| Service Contract Bundling | Long-term calibration agreements with Syntegon and Marchesini installed bases defend against third-party unbundling. |
| Modular Platform Development | Flexible batch handling for Swiss CMOs processing shear-sensitive proteins captures cell and gene therapy expansion. |
| Regional Manufacturing Footprint | Local assembly in Maharashtra reduces lead times for CDSCO-inspected facilities under PLI scheme incentives. |
| Peristaltic Pump Technology Licensing | Gentle high-viscosity handling displaces piston methods in cosmetic fragrance applications for French luxury houses. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with sterile injectables production managers, pharmaceutical procurement directors, contract manufacturing organization executives, and precision equipment aftermarket service heads. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA EU GMP Annex 1 revision texts, ISO 13485 certification registries, and German mechanical engineering association trade statistics. Bottom-up equipment shipment data was triangulated against top-down pharmaceutical capital expenditure disclosures.
Calibration across the analysis window employed segmented growth modeling by automation tier, filling technology, end-user vertical, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and pipeline-stage biologics capacity expansion announcements. Forecast inputs incorporated EU GMP Annex 1 compliance deadline phasing, FDA audit frequency patterns, and stainless steel input cost trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese precision equipment builders or sudden tariff escalations on European steel would shift outcomes. Material shifts in FDA data integrity enforcement intensity or EMA isolator mandate implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Stick Pack Packaging Machine Market
Packaging Machinery
Europe Blow Molding Machine Market
Packaging Machinery
Paper Napkins Converting Machines Market
Packaging Machinery
Vacuum Sealing Machine Market
Packaging Machinery
Bundling Machine Market
Packaging Machinery
Form-Fill-Seal Equipment Market
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Lidding Machines Market
Packaging Machinery
Barcode Labeller Machine Market
Packaging Machinery
Plastic Extrusion Equipment Market
Packaging Machinery
Rotary Sealers Market
Packaging Machinery
Air Cushion Machine Market
Packaging Machinery
Side Load Case Packing Machines Market
Packaging Machinery
Straw Machine Market
Packaging Machinery
Tray Sealing Machines Market
Packaging Machinery
Poly Bagging Machines Market