
 Foil Embossing Machine Market | 2026-2036
Foil Embossing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Foil Embossing Machine Market Foresight
Cosmetics and premium spirits packaging is shifting toward high-tactile embellishment as brands chase unboxing-driven consumer engagement. BOBST leverages its rotary platform dominance to anchor supply relationships with multinational beauty houses. Heidelberg competes through service network density across European print hubs. KURZ differentiates via captive foil supply that reduces job changeover waste for converters.
A foil embossing machine applies heat and pressure to transfer metallic or pigment foil onto substrates while simultaneously raising a relief pattern, typically operating between 100°C and 200°C with pressure calibrated to substrate caliper and foil adhesion chemistry. Flat bed systems occupy the legacy installed base for short-run craft and stationery work, while rotary configurations lead throughput economics in folding carton and label environments. Hybrid architectures are gaining traction where job lot sizes fragment and changeover speed determines margin capture.
CE marking governs machine safety and electromagnetic compatibility across European deployments, while OSHA lockout-tagout standards shape guarding and access panel design for US installations. The EU Green Deal's packaging waste directives are pressuring converters toward recyclable foil substrates and reduced job waste, altering machine specification priorities. Stakeholders must monitor how ECHA substance restrictions on perfluorinated compounds reshape foil chemistry portfolios and retrofit requirements across installed equipment fleets.
Market Dynamics
The foil embossing machine market pivots on REACH compliance pressures from ECHA, which are forcing converters to requalify foil chemistries and retrofit thermal management systems across installed European fleets.
Growth Catalysts
- EU Green Deal packaging directives:Mandates for recyclable substrates accelerate demand for machines compatible with biodegradable foils and lower-temperature transfer processes.
- Luxury cosmetics unboxing economics:Premium beauty houses in Germany and France are specifying tactile embellishment to drive social media shareability and shelf differentiation.
- Rotary platform throughput advantages:Folding carton converters facing job fragmentation are prioritizing changeover speed over legacy flat-bed flexibility.
Market Restraints
- Perfluorinated compound substitution costs:ECHA substance restrictions on PFAS chemistries force foil reformulation and machine recalibration, raising converter operating expenses.
- Precision engineering supply concentration:Critical servo drive and thermal control components cluster in southern German industrial zones, creating geographic vulnerability.
- Digital print embellishment convergence:Inkjet metallic deposition and laser micro-structuring threaten foil transfer volumes in short-run label applications.
Strategic Opportunities
- Indian pharmaceutical packaging expansion:CDSCO serialization mandates and rising domestic drug manufacturing create demand for tamper-evident embossed cartons.
- Hybrid architecture penetration:Converters serving fragmented lot sizes benefit from machines combining rotary speed with flat-bed die flexibility.
- US IRA clean manufacturing incentives:Domestic packaging equipment purchasers qualify for credits when deploying energy-efficient thermal recovery systems.
Industry Challenges
- Mechatronics technician scarcity:Servo calibration and thermal profiling expertise concentrates in aging workforces across European machine tool regions.
- CE marking timeline compression:Evolving electromagnetic compatibility standards delay new machine introductions by 4-6 months for third-party certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foil Embossing Machine Market |
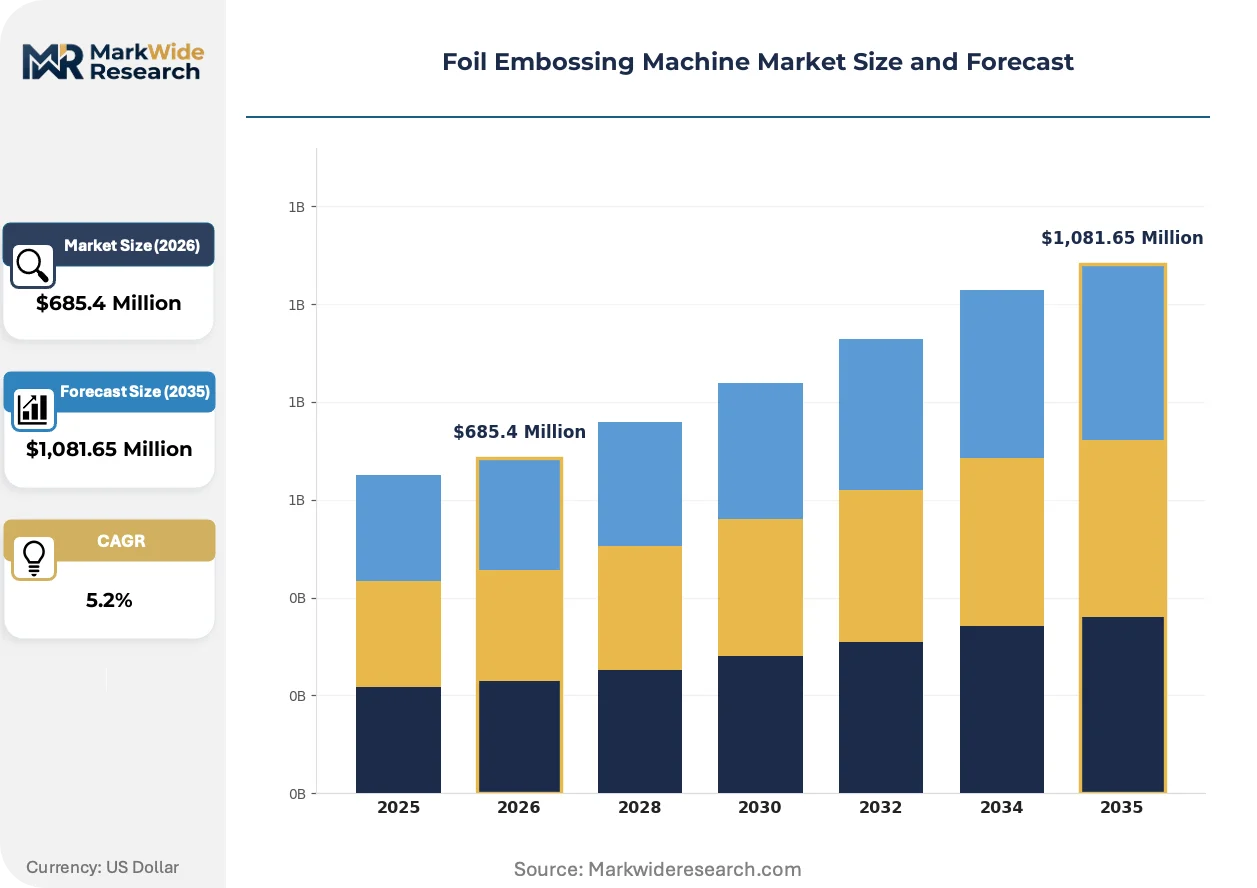
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Flat Bed, Rotary, Hybrid, Cylinder Industry Vertical: Packaging, Publishing, Label Printing, Decorations Application: Book Covers, Greeting Cards, Product Packaging, Stationery Automation Level: Manual, Semi-Automatic, Fully Automatic, CNC Controlled |
| Companies Covered | BOBST, Heidelberg, Komori Corporation, Gietz, Koenig and Bauer, KURZ, Masterwork Machinery, IIJIMA MFG., Grafisk Maskinfabrik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foil Embossing Machine Market Shifts & Advancements
Active thermal management and chemistry adaptation dominate equipment evolution as converters navigate regulatory tightening and substrate diversification. Machine architecture decisions increasingly hinge on job-size economics rather than maximum throughput.
Induction heating modules are consolidating control over foil transfer temperature precision, replacing resistive elements in mid-range rotary systems. Premium cosmetics converters in Germany and Switzerland are specifying these modules to reduce thermal drift during extended runs. The technology is consolidating supplier relationships around firms with captive metallurgy expertise.
REACH Annex XVII restrictions on perfluorinated compounds are compelling foil manufacturers to reformulate release coatings and adhesives. Converters must validate new chemistries through machine trials, extending job setup cycles. The folding carton segment across Benelux and northern France is responding by pooling qualification costs through industry consortia.
Converter procurement patterns now emphasize total cost of ownership over capital expenditure, with service network density weighted heavily in vendor selection. Beauty and spirits packaging houses are unbundling maintenance contracts from equipment purchases, creating aftermarket revenue concentration. This shift is most pronounced in Germany, where precision engineering vendors compete on technician response time rather than machine price alone.
Foil Embossing Machine Market Segmentation
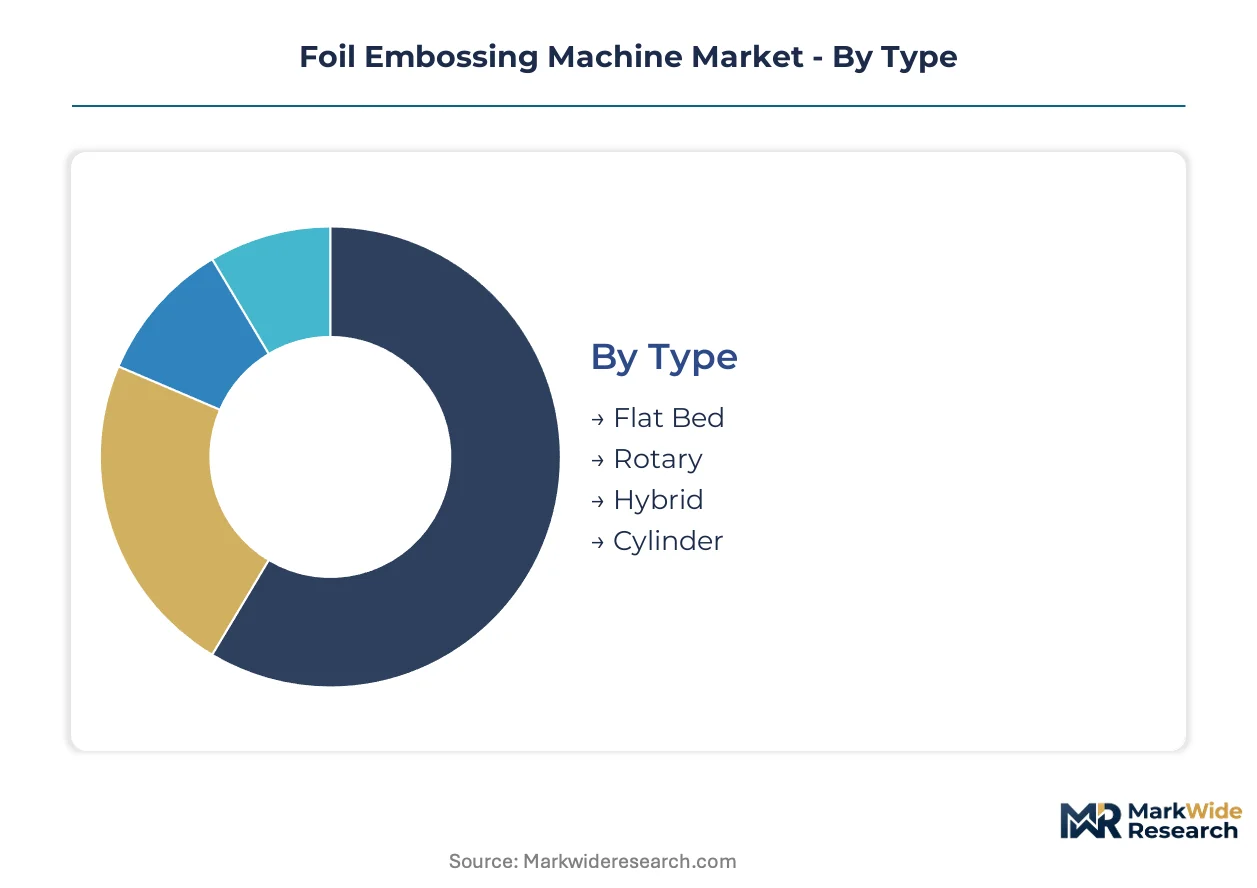
Converters select foil embossing equipment based on run-length economics, substrate versatility, and regulatory compliance requirements. Segmentation reveals how technology choices diverge between high-volume folding carton producers and short-run craft specialists.
Type:
Capital intensity and changeover frequency determine architecture selection for converters balancing throughput against job fragmentation.
- Rotary:Continuous web-fed operation employs engraved cylinders to sustain speeds exceeding 10,000 impressions per hour. German folding carton producers serving L'Oréal and Beiersdorf specify rotary systems for lipstick and spirits packaging where 50,000+ unit runs justify cylinder engraving costs. REACH-compliant thermal management modules are becoming standard specifications.
- Hybrid:Configurations combine rotary speed with quick-change flat-bed stations for lot sizes below 5,000 units. Swiss converters serving fragmented luxury watch packaging demand these systems to avoid cylinder inventory for seasonal designs. The architecture commands 40-60% capital premiums over pure rotary equivalents.
- Flat Bed:Platen-based systems dominate craft stationery and limited-edition book production where die flexibility outweighs speed.
- Cylinder:Dedicated engraved-cylinder configurations serve dedicated high-volume contracts with minimal design turnover.
Rotary leads on scale; hybrid leads on momentum.
Industry Vertical:
End-use specifications diverge sharply between regulated pharmaceutical applications and discretionary luxury goods.
- Packaging:Folding carton and rigid box producers account for the dominant equipment installed base. French cosmetics houses specify tactile embossing for shelf differentiation in Sephora and Douglas retail environments. EU Green Deal directives are forcing substrate transitions toward biodegradable films compatible with modified thermal profiles.
- Label Printing:Self-adhesive and wet-glue label converters face digital embellishment displacement in short-run applications. Pressure-sensitive wine and spirits labels in Bordeaux and Champagne regions sustain foil demand despite inkjet metallic alternatives.
- Publishing:Coffee-table and limited-edition book publishers in Milan and London maintain flat-bed capacity for cover embellishment.
- Decorations:Wallcovering and interior panel producers in northern Italy employ wide-format cylinder systems for architectural applications.
Packaging dominates absolute volumes; label printing faces the steepest technology substitution pressure.
Application:
Surface area and relief depth requirements determine press specification and foil consumption rates.
- Product Packaging:Folding cartons for fragrances and skincare demand multi-level embossing with registered foil transfer across 300-600 micron board. German precision engineering clusters supply servo-controlled pressure systems achieving ±0.05mm registration tolerance for premium beauty houses.
- Greeting Cards:Seasonal volume spikes and design variety favor semi-automatic flat-bed configurations with rapid die changeover. UK and US specialty card publishers operate equipment fleets averaging 15-20 years age.
- Book Covers:Leather and cloth-bound editions require deep relief capabilities and substrate-specific pressure calibration.
- Stationery:Business cards and correspondence papers sustain small-format flat-bed demand in craft-oriented segments.
Product packaging commands the steepest expansion trajectory; greeting cards represent the most replacement-dependent segment.
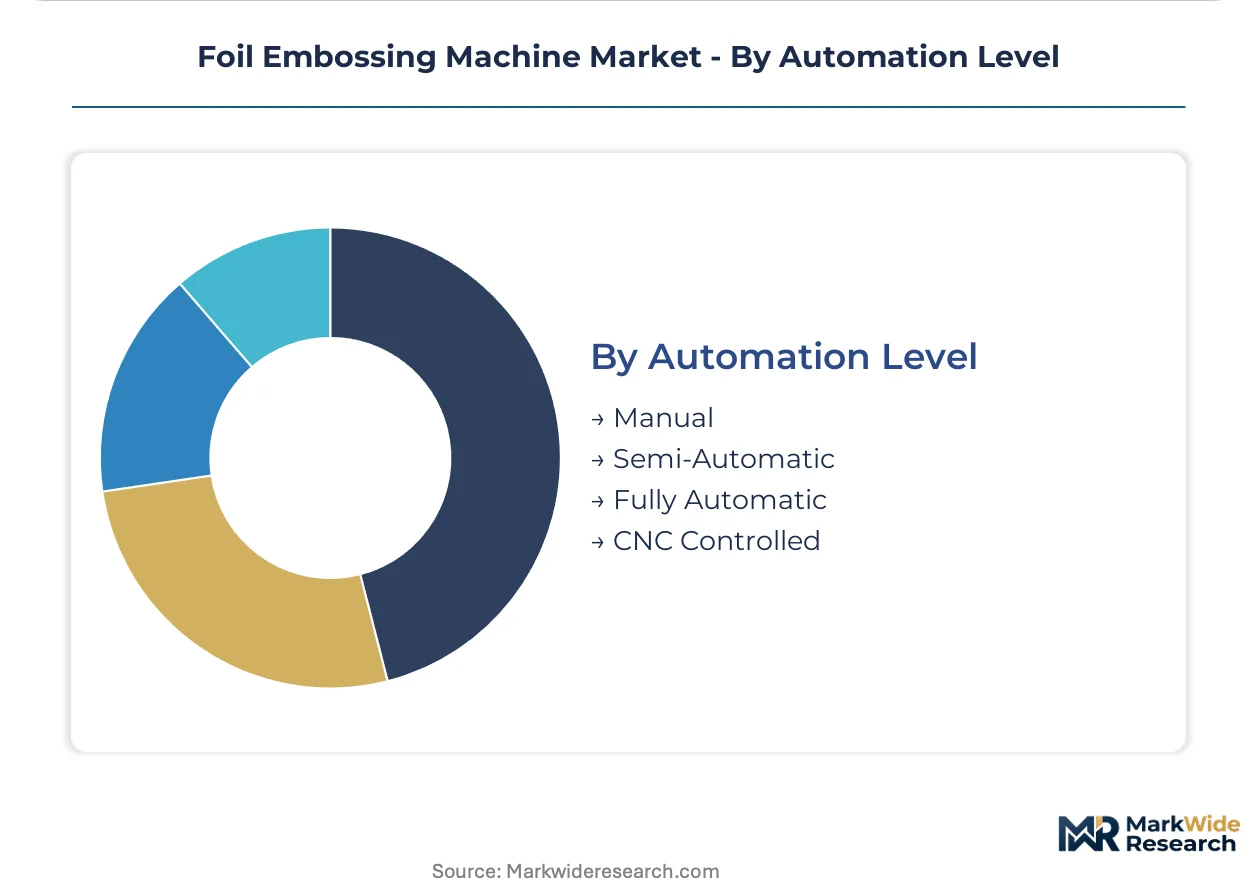
Automation Level:
Labor availability and quality consistency requirements drive investment in servo-controlled systems.
- Fully Automatic:Closed-loop registration and foil tension control enable unattended operation across extended runs. Benelux converters serving Unilever and Procter & Gamble specify these systems to minimize operator intervention and waste generation.
- CNC Controlled:Programmable servo positioning allows rapid job recall and digital die storage for converters serving fragmented lot sizes. Austrian and Swiss equipment vendors lead integration of CNC architectures with MES systems.
- Semi-Automatic:Operator-assisted loading and registration adjustment persists in short-run craft applications.
- Manual:Hand-fed platen systems survive in artisanal production and developing market micro-enterprises.
Fully automatic leads on scale; CNC controlled gains share fastest among mid-cap converters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting foil embossing equipment procurement toward jurisdictions with clearer compliance pathways and established precision engineering ecosystems. Converters in high-standard markets absorb REACH recertification costs while emerging pharmaceutical packaging hubs exploit regulatory clarity to capture contract manufacturing migration.
Germany
Precision engineering clusters in Baden-Württemberg and Bavaria supply servo-controlled thermal management systems to folding carton converters serving L'Oréal and Beiersdorf. ECHA REACH Annex XVII enforcement is forcing foil chemistry requalification across installed equipment fleets. Stuttgart-area machine builders are consolidating supplier relationships around induction heating module specialists with captive metallurgy expertise.
France
Premium cosmetics houses in the Île-de-France region specify multi-level embossing for Sephora and Douglas retail differentiation. ANSM pharmaceutical packaging standards drive tamper-evident carton specifications for dermo-cosmetic lines. The Champagne and Bordeaux wine label corridors sustain rotary foil demand despite digital embellishment encroachment in shorter runs.
Switzerland
Luxury watch packaging converters in the Jura Arc demand hybrid architectures combining rotary speed with flat-bed die flexibility for fragmented seasonal designs. Swissmedic medical device labeling requirements extend foil embossing into pharmaceutical secondary packaging. Zürich and Geneva precision component suppliers dominate thermal control subsystem exports across Central Europe.
India
CDSCO serialization mandates and rising domestic drug manufacturing are expanding demand for tamper-evident embossed cartons in Maharashtra and Gujarat. The country's national pharmaceutical regulator is tightening traceability requirements that favor mechanical over digital embellishment for authentication. Ahmedabad and Mumbai packaging corridors are importing European rotary platforms to serve contract manufacturing growth.
United States
OSHA lockout-tagout standards shape guarding and access panel design for folding carton installations in Wisconsin and Illinois packaging corridors. IRA clean manufacturing incentives qualify domestic purchasers for credits when deploying energy-efficient thermal recovery systems. Chicago-area converters are retrofitting legacy fleets to meet EPA-adjacent state emissions standards for volatile foil adhesive chemistries.
Foil Embossing Machine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with rotary platform dominance concentrating among Swiss and German engineering houses while Asian fabricators capture mid-cap CNC-controlled demand. The vendor base organizes around three strategic archetypes: precision engineering specialists with captive foil supply, scale-oriented rotary platform builders, and hybrid architecture innovators serving fragmented lot sizes. Competitive moves center on M&A-driven thermal management technology consolidation and geographic expansion through service network density rather than price-based positioning.
Within the precision engineering tier, BOBST and Heidelberg exemplify the rotary platform archetype anchored in European packaging hubs. KURZ occupies a distinct position through backward integration into foil manufacturing that reduces converter job changeover waste. Among Asian fabricators, Masterwork Machinery and IIJIMA MFG. represent the CNC-controlled mid-cap segment where programmable servo positioning and MES integration determine vendor selection.
| Leading Market Players |
|---|
| BOBST |
| Heidelberg |
| Komori Corporation |
| Gietz |
| Koenig and Bauer |
| KURZ |
| Masterwork Machinery |
| IIJIMA MFG. |
| Grafisk Maskinfabrik |
| Others |
Supply & Pricing Matrix
Induction heating module adoption across mid-range rotary systems is compressing thermal management costs while consolidating supplier relationships around German and Swiss metallurgy specialists with captive coil production capabilities. This technology shift simultaneously reduces converter operating expenses and concentrates procurement leverage among precision engineering clusters in Baden-Württemberg and Bavaria.
Pricing Analysis
Distributor margins of 12-18% on European rotary platforms compress to 6-9% for direct OEM relationships with volume converters. Pricing stratifies across premium induction-heated systems, standard resistive-element configurations, and economy-grade flat-bed alternatives, with differentiation anchored in CE marking tier and servo registration precision. Cost compression in standard rotary tiers intensifies as Asian CNC-controlled alternatives penetrate mid-cap converter procurement. Brand-conscious cosmetics houses in Germany and France exhibit lowest price sensitivity, while Indian pharmaceutical packaging startups prioritize capital efficiency over thermal precision specifications.
Supply Chain Analysis
CE marking and REACH Annex XVII compliance certification gates access to European converter procurement, filtering out non-compliant thermal control subsystems. Component supply concentrates in Germany, Switzerland, and Japan, with servo drives drawing from Stuttgart-area precision motor manufacturers and engraved cylinders sourcing from Jura Arc toolmaking specialists. Single-source vulnerability persists for induction heating coils with specialized ferrite cores. Distribution runs through regional equipment distributors with certified technician networks rather than direct manufacturer sales in fragmented lot-size segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA substance restrictions on perfluorinated compounds drive recurring equipment retrofit demand across installed European fleets.
For Market Incumbents: To counter digital embellishment displacement in short-run label applications, BOBST and Heidelberg should anchor rotary platform upgrades with REACH-compliant thermal management modules and deepen backward integration into foil chemistry qualification services. Certification investment in next-generation induction heating architectures represents the critical defensive lever against Asian CNC-controlled alternatives. For New Entrants and Emerging Players: Capture white-space opportunity in Indian pharmaceutical packaging corridors where CDSCO serialization mandates expand tamper-evident carton demand faster than domestic equipment supply. Hybrid architecture penetration among Swiss luxury watch packaging converters offers second entry vector. Lead go-to-market through regional distributor partnerships with existing MES integration capabilities rather than direct sales force buildout. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap CNC-controlled equipment fabricators with programmable servo positioning and nascent MES connectivity. Long-term viability over the next decade hinges on thermal management technology consolidation and service network density rather than manufacturing scale alone. The signal to watch is ECHA expansion of PFAS restrictions into additional foil coating categories, which would accelerate retrofit demand across installed fleets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foil Chemistry | KURZ's captive foil supply reduces converter waste and locks in recurring chemistry requalification revenue. |
| Induction Heating Module Adoption | German precision engineering clusters consolidate supplier relationships around metallurgy specialists with coil expertise. |
| Hybrid Architecture Development | Swiss converters serving fragmented luxury watch packaging demand quick-change flat-bed stations for seasonal designs. |
| Service Network Density Expansion | Heidelberg competes on technician response time across European print hubs rather than equipment price alone. |
| Indian Market Entry Partnerships | Ahmedabad and Mumbai packaging corridors import European rotary platforms to serve CDSCO-mandated serialization growth. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with folding carton converters, precision engineering procurement leads, thermal control subsystem suppliers, and aftermarket service heads with secondary validation against customs equipment import records, ECHA regulatory filings, and SEC disclosures from publicly traded packaging machinery vendors. Bottom-up equipment shipment tallies triangulated against top-down converter capital expenditure surveys across Germany, France, Switzerland, India, and the United States.
Historical reference periods anchored the forecast window to pre-pandemic baseline capacity utilization and post-REACH implementation equipment retrofit cycles. Segmentation modeling spanned machine architecture type, automation level, end-use vertical, and regional regulatory cluster, with CAGRs derived from installed base turnover rates and net new capacity requirements. Foil chemistry transition timelines and ECHA substance restriction enforcement patterns served as industry-specific forecast inputs.
PFAS regulatory expansion, digital embellishment substitution velocity, and precision engineering technician availability are the dominant revision risks to modeled equipment demand. Forecasts reflect documented assumptions regarding converter compliance cost absorption and hybrid architecture adoption elasticity. A model refresh is warranted upon material change in ECHA Annex XVII amendment schedules or CDSCO serialization mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Wraparound Case Packers Market
Packaging Machinery
Tube Filling Machine Market
Packaging Machinery
Paper Slitting Machine Market
Packaging Machinery
Global Wrapping Machine Market
Packaging Machinery
Precision Dispensing Machine Market
Packaging Machinery
Volumetric Boom Filling Machine Market
Packaging Machinery
Shrink Label Machine Market
Packaging Machinery
Metal Banding Machine Market
Packaging Machinery
Laminating Machines Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Pulp Molding Machines Market
Packaging Machinery
Pillow Packing Machine Market
Packaging Machinery
Vertical Injection Molding Machine Market
Packaging Machinery
Straw Machine Market
Packaging Machinery
Orbital Wrapping Machine Market
Packaging Machinery
Vial Filling and Capping Machines Market