
 Glass Cosmetic Bottle Market | 2026-2036
Glass Cosmetic Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Cosmetic Bottle Market Foresight
ISO 15378 certification for primary packaging materials is collapsing the supplier base as smaller molders exit the qualification cycle. Gerresheimer AG leverages captive pharmaceutical-grade glass expertise to dominate premium fragrance contracts. Stoelzle Glass Group anchors European volume through its Austrian and French furnace networks. VERESCENCE differentiates via proprietary lightweighting technology that reduces wall thickness without compromising drop resistance.
Glass cosmetic bottles are rigid primary containers fabricated from soda-lime silica or borosilicate formulations, typically ranging from 15 ml to 200 ml nominal capacity, formed through blow-and-blow or press-and-blow processes, and engineered to provide inert barrier protection against oxygen ingress and UV degradation for volatile fragrance compounds and oxidation-sensitive skincare actives. Perfume bottles command the highest unit value segment due to sculptural complexity and decorative overcapacity, while serum bottles represent the fastest-expanding volume pool as facial treatment formats proliferate across luxury and masstige tiers. Flint glass sustains dominant share in color cosmetics where product visibility drives purchase conversion, though amber glass competes aggressively in botanical skincare positioning.
EMA stability testing guidelines, REACH chemical registration requirements, and France's AGEC anti-waste law collectively tighten material traceability and recyclability thresholds for glass cosmetic packaging placed on European markets. ECHA substance restrictions on heavy metal colorants in decorative coatings directly reformulate supplier enamel portfolios and extend qualification timelines. Stakeholders must monitor evolving extended producer responsibility fee structures and lightweighting mandates as these mechanisms determine competitive viability across mid-volume fragrance and skincare contract segments.
Market Dynamics
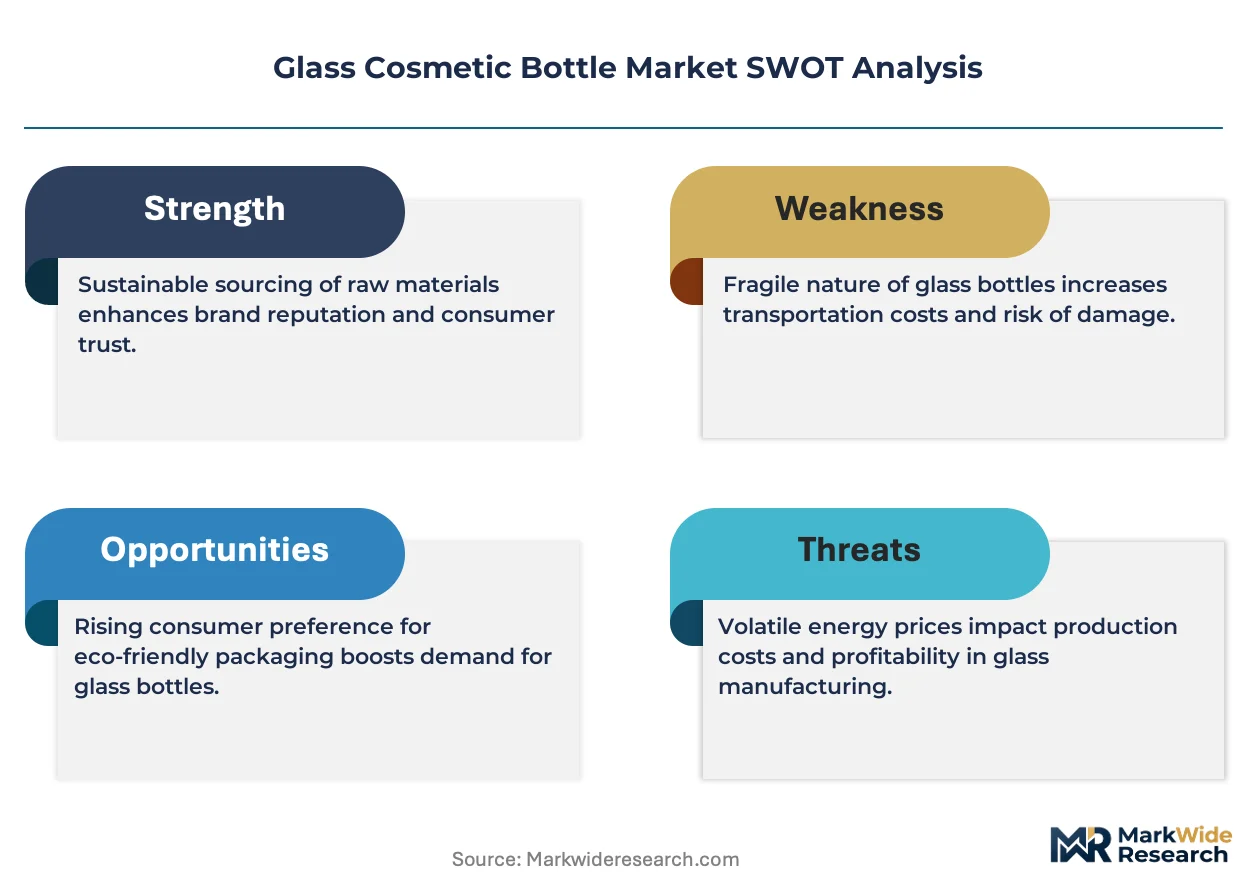
Extended producer responsibility mandates across France and Germany are forcing brand owners to internalize end-of-life glass costs, compressing margins for non-refillable formats while rewarding lightweighting investments and post-consumer recycled content adoption.
Growth Catalysts
- EU Green Deal packaging targets:Mandatory recyclability thresholds for cosmetic packaging placed on European markets accelerate conversion from mixed-material formats to monomaterial glass.
- Serum bottle proliferation:Facial treatment actives requiring oxygen and UV barrier protection drive unit volume expansion across luxury and masstige skincare tiers.
- France's AGEC anti-waste law:Bans on single-use promotional samples push fragrance houses toward durable, refillable glass formats with higher per-unit value capture.
Market Restraints
- Furnace energy intensity:Natural gas dependency in soda-lime glass melting exposes molders to input cost volatility exceeding 30% of manufacturing overhead.
- ISO 15378 certification barriers:Pharmaceutical-grade qualification timelines exceeding 18 months exclude smaller molders from premium fragrance and skincare contracts.
- Aluminum and PET substitution:Lightweight, shatter-resistant formats penetrate travel retail and direct-to-consumer channels where handling durability outweighs premium perception.
Strategic Opportunities
- Lightweighting technology convergence:Proprietary thin-wall forming processes combined with surface strengthening treatments enable material reduction without drop-test failure.
- Germany's skincare manufacturing belt:Concentrated contract manufacturing demand in Bavaria and North Rhine-Westphalia creates captive offtake for regional furnace networks.
- Decorative coating reformulation:ECHA heavy metal restrictions on enamel colorants open premium positioning for mineral-derived, compliance-ready pigment systems.
Industry Challenges
- Drop-test engineering expertise:Wall thickness reduction targets collide with distribution handling standards, requiring specialized finite element modeling talent scarce in traditional glass operations.
- Multi-format furnace scheduling:Campaign changeovers between flint, amber, and custom color runs erode asset utilization rates below continuous-output benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Cosmetic Bottle Market |
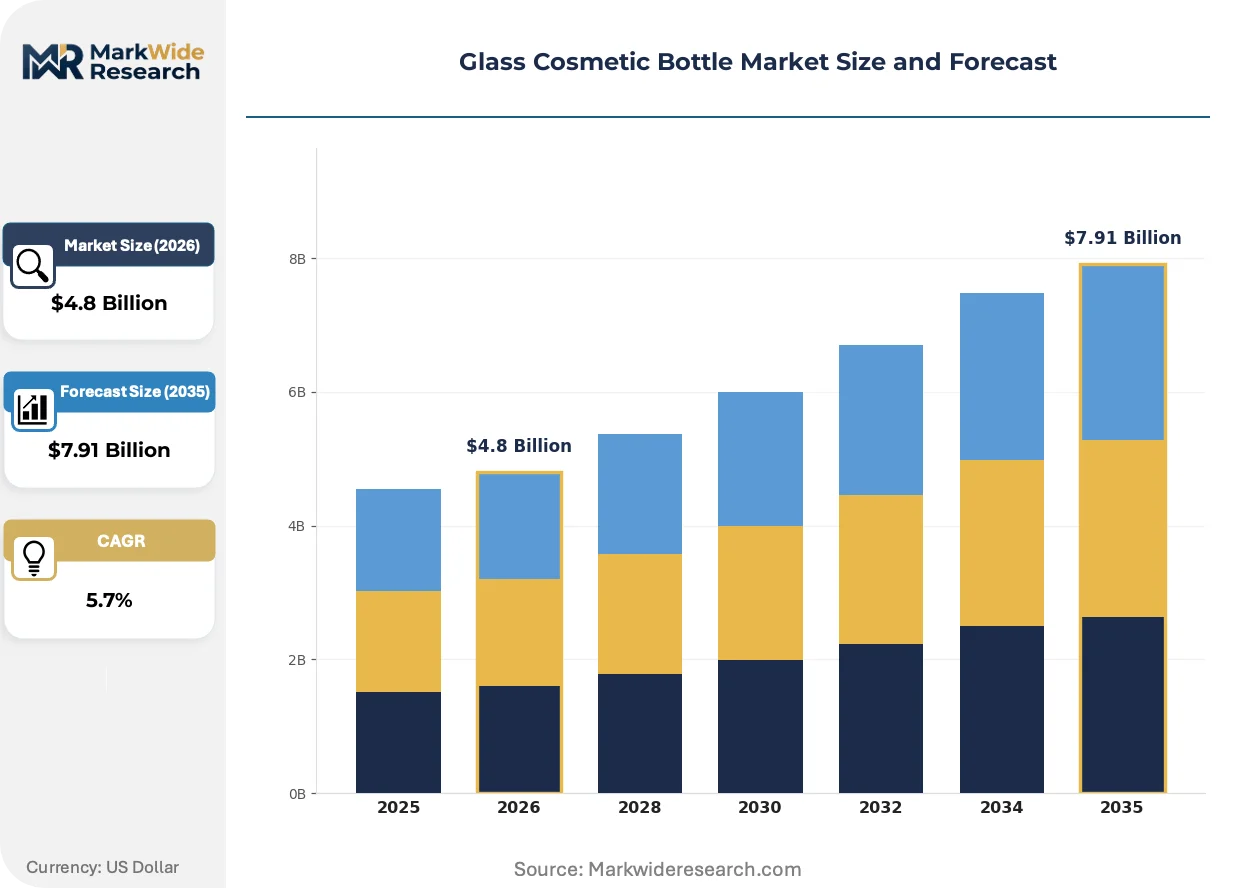
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Perfume Bottles, Lotion Bottles, Serum Bottles, Eye Cream Bottles, Foundation Bottles Material Type: Flint Glass, Amber Glass, Green Glass, Cobalt Blue Glass, Frosted Glass Application: Skincare, Fragrance, Hair Care, Nail Care, Makeup End User: Luxury Brands, Mass Market Brands, Boutiques, Spas, Online Retailers |
| Companies Covered | Gerresheimer AG, Stoelzle Glass Group, VERESCENCE, Groupe Pochet, Bormioli Luigi, Coverpla, PGP Glass, Heinz-Glas, Zignago Vetro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Cosmetic Bottle Market Shifts & Advancements
Glass cosmetic packaging is undergoing functional reinvention as sustainability mandates and actives protection requirements reshape material specifications, forming methods, and supplier qualification criteria across European markets.
Lightweighting technology is decomposing the traditional trade-off between material reduction and mechanical durability. VERESCENCE and Stoelzle Glass Group deploy proprietary thin-wall forming with ion-exchange surface strengthening to achieve 15-20% weight reduction in 50ml serum formats. Premium skincare houses in France's perfume corridor adopt these specifications for refillable lines, compressing per-unit material costs while maintaining luxury heft perception.
France's AGEC anti-waste law and Germany's extended producer responsibility fee structures tighten material traceability thresholds for glass cosmetic packaging. ECHA substance restrictions on cadmium and lead-based decorative coatings force reformulation of supplier enamel portfolios, extending qualification timelines. Fragrance houses respond by consolidating supplier bases toward vertically integrated molders with captive analytical laboratories.
Direct-to-consumer channel expansion fragments procurement lot sizes while compressing lead time requirements. Masstige skincare brands bypass traditional distributor networks, placing 5,000-10,000 unit orders with 6-week turnaround demands. This pattern concentrates in Germany's e-commerce fulfillment hubs, where regional molders with digital printing capabilities capture contract manufacturing volumes previously routed through Asian suppliers.
Glass Cosmetic Bottle Market Segmentation
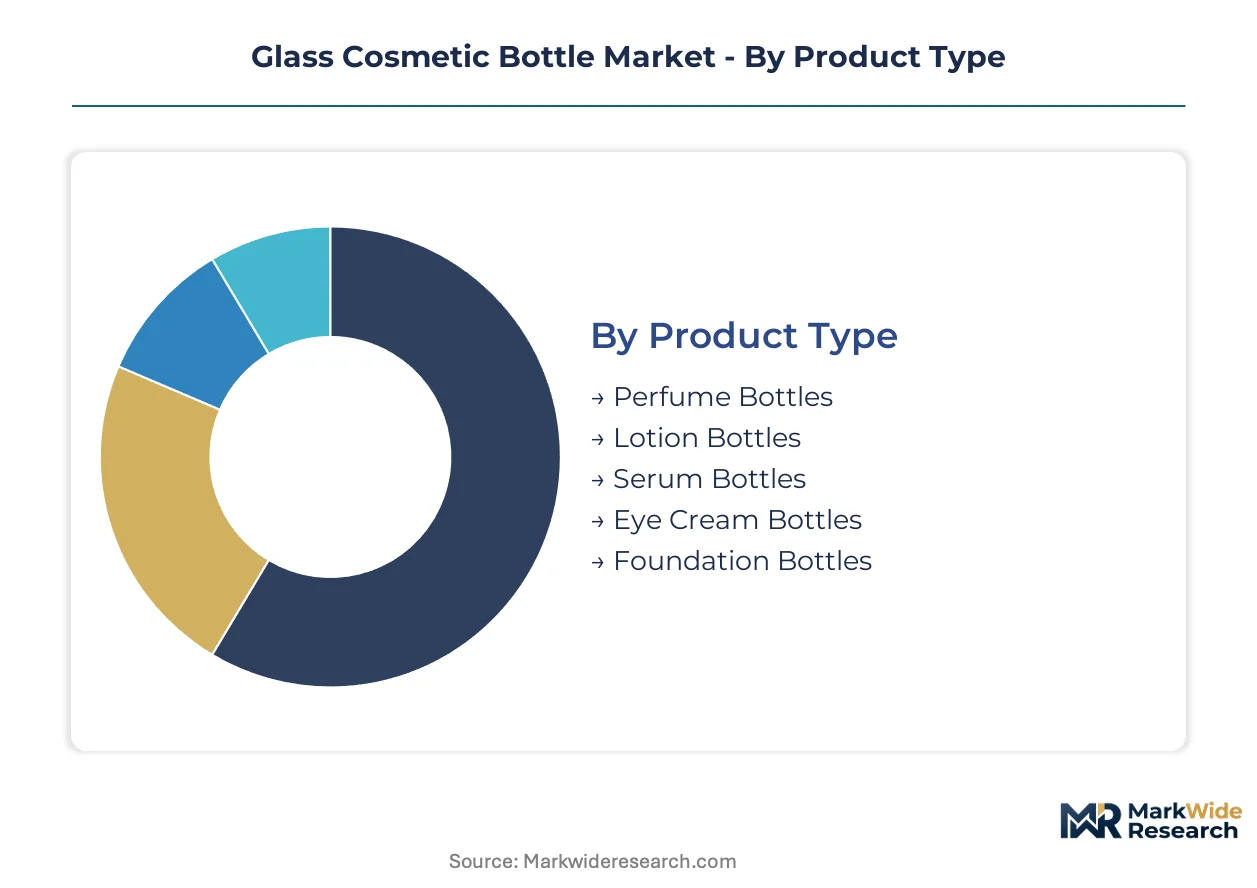
Glass cosmetic bottle segmentation reveals how premium positioning, barrier requirements, and channel economics fragment procurement patterns across European markets. Understanding these divisions exposes where molders capture value and where brand owners face substitution pressure.
Product Type:
Perfume bottles command the highest unit margins due to decorative complexity and sculptural differentiation, while serum bottles concentrate volume growth from actives protection demands.
- Perfume Bottles:Sculptural forms with heavy-wall construction and applied decorative elements dominate France's perfume corridor. AGEC anti-waste law bans on single-use samples push houses toward refillable, high-value formats that amortize glass costs across multiple purchase cycles.
- Serum Bottles:Small nominal capacities from 15ml to 50ml with UV-blocking tints or amber glass formulations protect oxidation-sensitive facial actives. Germany's skincare manufacturing belt drives fastest volume expansion as contract manufacturers scale facial treatment lines.
- Lotion Bottles:Mid-volume formats with pump-compatible neck finishes serve body care and hand cream applications across masstige tiers.
- Eye Cream Bottles:Compact 15ml-30ml jars and tubes with wide-mouth access target precision dispensing for delicate periorbital formulations.
- Foundation Bottles:Flint glass dominates for color visibility, with pump or dropper closures matching fluid viscosity requirements.
Perfume bottles hold installed capacity. Serum bottles are rotating up the share rankings.
Material Type:
Material selection traces directly to product protection needs and sustainability positioning, with flint glass anchoring volume and specialty tints capturing premium markup.
- Flint Glass:Soda-lime silica formulations with high optical clarity dominate color cosmetics where purchase conversion depends on visible product tone. France and Germany together concentrate flint furnace capacity serving cosmetic contract manufacturers.
- Amber Glass:Iron-sulfur colorants block UV transmission below 450nm, protecting retinol and vitamin C actives in botanical skincare positioning. German natural cosmetics brands specify amber for shelf-life extension claims.
- Green Glass:Chromium-based tints offer intermediate UV protection with distinctive shelf presence for heritage fragrance houses.
- Cobalt Blue Glass:Premium positioning for Mediterranean and marine-themed skincare lines commands 15-20% price premium over flint equivalents.
- Frosted Glass:Acid-etched or sandblasted surfaces diffuse light and obscure fill-level variation, popular in minimalist luxury packaging from Scandinavian-influenced brands.
Flint glass maintains volume dominance. Amber glass is climbing the fastest on clean beauty specification.
Application:
Application segmentation aligns with barrier requirements and dosage precision, concentrating procurement among specialized molders with format-specific tooling libraries.
- Skincare:Oxygen and UV barrier demands drive borosilicate and amber glass adoption for retinol, vitamin C, and peptide formulations. German contract manufacturers consolidate volumes for private-label facial treatment launches.
- Fragrance:Volatile compound containment requires inert glass surfaces and tight closure tolerances; sculptural complexity justifies captive mold fabrication for luxury houses.
- Hair Care:Larger nominal capacities from 100ml to 200ml with flip-top or disc-cap closures serve salon and retail channels.
- Nail Care:Small cylindrical bottles with brush-integrated caps dominate solvent-based polish packaging.
- Makeup:Foundation and liquid color products split between flint glass visibility and airless pump systems for sensitive formulations.
Fragrance commands per-unit value. Skincare is expanding most quickly on serum format proliferation.
End User:
End-user segmentation fragments order patterns, with luxury brands demanding customization and mass-market players prioritizing furnace efficiency and scale economics.
- Luxury Brands:Bespoke mold development, limited color runs, and applied decorative elements require 12-18 month qualification cycles. French fragrance houses consolidate supplier bases toward vertically integrated molders with captive analytical laboratories.
- Mass Market Brands:High-volume, standardized formats with digital printing decoration compress lead times and per-unit costs through continuous furnace scheduling.
- Boutiques:Small lot sizes of 5,000-10,000 units with 6-week turnaround demands favor regional European molders over Asian suppliers.
- Spas:Professional-size formats with pump dispensers target treatment room consumption and retail resale.
- Online Retailers:Direct-to-consumer fulfillment prioritizes shatter-resistant packaging and compact dimensional weight for shipping economics.
Luxury brands anchor customization capacity. Online retailers are rotating up the share rankings on e-commerce channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's AGEC anti-waste law and Germany's extended producer responsibility frameworks are redrawing procurement geography across European glass cosmetic packaging. National sustainability mandates now determine where brand owners source refillable formats and lightweighted containers.
France
Grasse perfume manufacturers and Paris luxury houses drive demand for sculptural, refillable bottles. ANSM material traceability requirements extend qualification timelines for decorative coatings. The perfume corridor from Grasse to Paris concentrates captive mold fabrication and applied decoration capacity for heritage fragrance brands.
Germany
Bavarian and North Rhine-Westphalia contract manufacturers scale serum bottle volumes for facial treatment lines. Extended producer responsibility fee structures reward post-consumer recycled glass adoption. The skincare manufacturing belt around Munich and Düsseldorf anchors regional furnace networks serving private-label launches.
Italy
Murano glassmaking heritage and Lombard cosmetic contract manufacturers sustain decorative bottle demand. REACH chemical registration requirements tighten enamel pigment sourcing for luxury positioning. The Veneto-Lombardy corridor specializes in artisanal finishing techniques for masstige fragrance launches.
Spain
Barcelona-based natural cosmetics brands specify amber glass for botanical skincare shelf-life claims. ECHA substance restrictions on heavy metal colorants reformulate supplier portfolios. Catalonia's packaging cluster develops lightweighted formats for Mediterranean export markets.
United Kingdom
London direct-to-consumer skincare brands fragment lot sizes while compressing lead times. CSRD sustainability disclosure requirements elevate material traceability demands. The Southeast England logistics corridor concentrates e-commerce fulfillment volumes requiring shatter-resistant packaging specifications.
Glass Cosmetic Bottle Market Competitive Landscape
Listed leaders compete with private specialists across furnace scale and qualification depth. The supplier base consolidates around three tiers: multinational glass groups with captive pharmaceutical expertise, mid-cap regional molders with digital decoration capabilities, and artisanal fabricators serving limited luxury runs. Strategic moves concentrate on lightweighting technology licensing and backward integration into raw material processing.
Among European glass groups, Gerresheimer AG and Stoelzle Glass Group exemplify the qualification-heavy tier where pharmaceutical-grade certification opens premium fragrance contracts. VERESCENCE occupies a position within the innovation-driven segment, representing proprietary thin-wall forming approaches that reduce material intensity without mechanical compromise. These three entities anchor the competitive structure through distinct capability configurations rather than scale alone.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Stoelzle Glass Group |
| VERESCENCE |
| Groupe Pochet |
| Bormioli Luigi |
| Coverpla |
| PGP Glass |
| Heinz-Glas |
| Zignago Vetro |
| Others |
Supply & Pricing Matrix
ISO 15378 pharmaceutical-grade certification gates both supplier qualification and price differentiation simultaneously, compressing the qualified molder base while stratifying contract values across premium fragrance and mid-volume skincare tiers. Brand owners face extended producer responsibility fee structures that internalize end-of-life costs, forcing trade-offs between lightweighting investments and decorative complexity premiums.
Pricing Analysis
Certification level creates the primary spread between ISO 15378-qualified pharmaceutical-grade molders and general cosmetic suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects qualification depth, furnace campaign flexibility, and captive decoration capabilities. Cost compression in mid-volume serum formats is intensifying because masstige brands consolidate volumes toward regional European molders with digital printing. Mass-market contract manufacturers exhibit highest price sensitivity, while luxury fragrance houses prioritize sculptural differentiation over per-unit cost.
Supply Chain Analysis
Strategic stockpiling of soda-lime silica raw materials dominates over just-in-time preferences given natural gas price volatility and furnace campaign rigidity. Supply concentrates in France, Germany, and Austria where regional furnace networks serve perfume corridor and skincare manufacturing belt demand. Raw material dependencies draw from silica sand deposits, heavy fuel oil or natural gas for melting energy, and mineral-derived colorants for amber and cobalt tints. Single-source vulnerability runs through concentrated borosilicate specialty glass supply for oxidation-sensitive actives. Distribution runs through contract manufacturing clusters in Bavaria and North Rhine-Westphalia, with secondary routing via Grasse-to-Paris logistics corridors for finished fragrance assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal packaging mandates and AGEC anti-waste law enforcement are accelerating format conversion toward refillable glass, creating a high-growth disruption window for qualified molders with lightweighting capabilities.
For Market Incumbents: Secure captive pharmaceutical-grade certification depth to defend premium fragrance contracts against emerging regional specialists. Deepen backward integration into raw material processing to buffer soda-lime silica cost volatility. Expand furnace capacity in Germany's skincare manufacturing belt to capture contract manufacturing volume consolidation.
For New Entrants and Emerging Players: Differentiate on proprietary thin-wall forming with ion-exchange surface strengthening to capture lightweighting specification demand from masstige skincare brands. Target boutique direct-to-consumer brands in Southeast England and Catalonia with sub-10,000 unit lot capabilities and six-week turnaround positioning. Pursue digital decoration partnerships to bypass traditional applied enamel qualification timelines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade furnace networks as ISO 15378 qualification timelines extend. Acquisition targets should emphasize mid-cap regional molders with captive analytical laboratories and existing amber glass campaign experience. The signal to watch is ECHA substance restriction expansion beyond cadmium and lead into broader decorative coating portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting Technology Licensing | Proprietary thin-wall forming enables material reduction without drop-test failure for serum formats. |
| Backward Integration into Raw Material Processing | Captive silica sand beneficiation buffers natural gas price volatility exposure in furnace operations. |
| Digital Decoration Capability Expansion | Direct-to-consumer channel fragmentation favors regional molders with compressed lead time positioning. |
| Refillable Format Development Partnerships | AGEC anti-waste law compliance drives durable, high-value bottle specifications across French fragrance houses. |
| Post-Consumer Recycled Glass Supply Agreements | Germany's extended producer responsibility fee structures reward recycled content adoption in skincare tiers. |
Research Methodology
Operator-level perspectives from furnace operations managers, brand owner packaging procurement leads, contract manufacturing supply planners, and decorative coating formulators anchored the qualitative base. Primary interview data combined with secondary validation from ECHA substance restriction filings, EU Green Deal implementation guidance, ANSM material traceability requirements, and extended producer responsibility fee schedules across France and Germany. Bottom-up volume modeling triangulated against top-down market sizing from furnace capacity utilization and campaign scheduling data.
Sensitivity analysis framed volume and value outputs across product type, material tint, application barrier requirements, end-user tier, and regional regulatory cluster segmentation. CAGRs derived from trend extrapolation of serum format proliferation, lightweighting adoption curves, and refillable line conversion rates across the analysis window. Industry-specific forecast inputs incorporated natural gas price scenario modeling and ISO 15378 qualification pipeline visibility.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or alternative material substitution acceleration would require recalibration. Forecasts reflect documented assumptions regarding furnace energy efficiency improvement trajectories and ECHA decorative coating restriction implementation scope. Revision becomes warranted when aluminum or PET substitution rates in direct-to-consumer channels cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market
Cosmetic Packaging
Fragrance Packaging Market
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
Crimp Neck Serum Bottles Market
Cosmetic Packaging
Cosmetic Bottles Packaging Market
Cosmetic Packaging
Middle East and Africa Personal Care Packaging Market
Cosmetic Packaging
Global Eye Cosmetic Packaging Market
Cosmetic Packaging
North America Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic and Toiletry Containers Market
Cosmetic Packaging
Lip Care Packaging Market
Cosmetic Packaging
Middle East and Africa Cosmetic Packaging Market
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Plastic Cosmetic Packaging Market
Cosmetic Packaging
Global Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Tubes Market
Cosmetic Packaging
Asia Pacific Personal Care Packaging Market