
 Carton Folding and Gluing Machine Market | 2026-2036
Carton Folding and Gluing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Carton Folding and Gluing Machine Market Outlook
Remote diagnostics and predictive maintenance subscriptions is rebalancing how OEMs capture lifetime value from installed equipment. Bobst leverages its cloud-connected service architecture to secure multi-year contracts with large converters. Heidelberg anchors its competitiveness through deep software integration across press-to-finisher workflows. Koenig & Bauer specializes in high-speed folder-gluer configurations for pharmaceutical-grade cartons, occupying a premium tier in validated packaging environments.
A carton folding and gluing machine mechanically converts die-cut paperboard blanks into finished folded cartons through sequential pre-breaking, folding, and adhesive bonding operations, typically processing 50,000 to 400,000 units per hour depending on format complexity and automation level. These systems serve primary and secondary packaging functions across consumer goods supply chains where shelf-ready presentation and structural integrity determine brand protection outcomes. Automatic configurations now dominate capital expenditure plans among multinational converters seeking labor reduction and throughput consistency, while servo technology is displacing electromechanical and pneumatic alternatives in new installations due to precision registration and energy efficiency advantages. The food and beverage end-user segment sustains the largest installed base though pharmaceutical applications generate superior margin pools through validation requirements and changeover flexibility demands.
FDA validation protocols for pharmaceutical packaging equipment shape machine design requirements in the United States, while CE marking under the EU Machinery Directive governs market access across European member states. China's GB standards and SAMR technical regulations impose additional conformity assessment burdens for imported equipment. REACH compliance on adhesive chemistries and emerging EU packaging waste regulations are redirecting R&D investment toward water-based bonding systems and substrate compatibility testing. Stakeholders must monitor how extended producer responsibility frameworks and substrate lightweighting trends will redefine machine specification criteria and service contract structures.
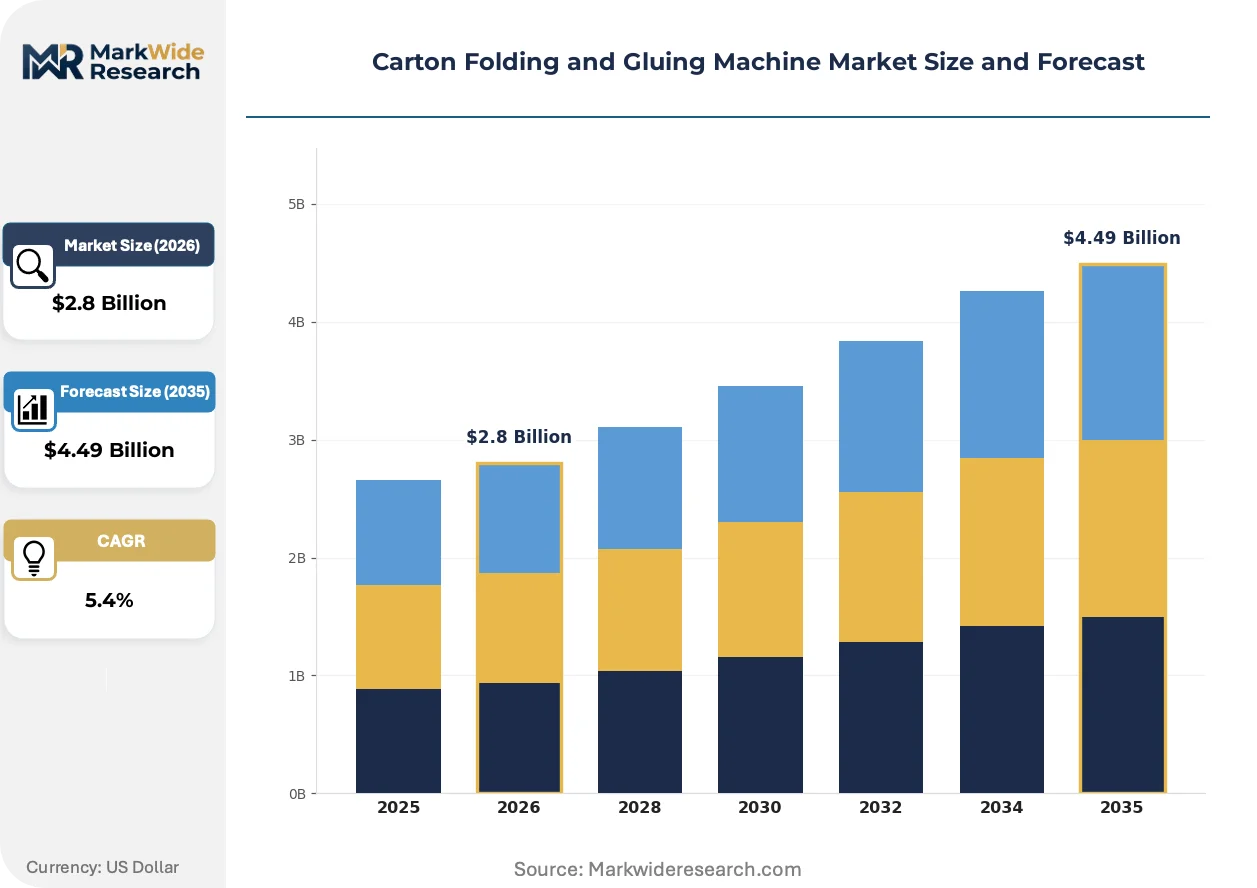
Market Dynamics
Servo-driven automation is compressing electromechanical and pneumatic system share across folding carton production lines as converters prioritize registration precision and energy efficiency in high-throughput environments.
Growth Catalysts
- EU serialization mandates:Pharmaceutical packaging lines in Germany and France are expanding validated machine fleets to comply with the EU Falsified Medicines Directive and emerging traceability requirements.
- Food-grade carton demand:Beverage and ready-meal brands are specifying high-speed folder-gluer configurations with quick-changeover capabilities to accommodate SKU proliferation.
- Water-based adhesive chemistry:REACH compliance pressures on solvent-based bonding systems are redirecting R&D investment toward aqueous formulations compatible with existing machine architectures.
Market Restraints
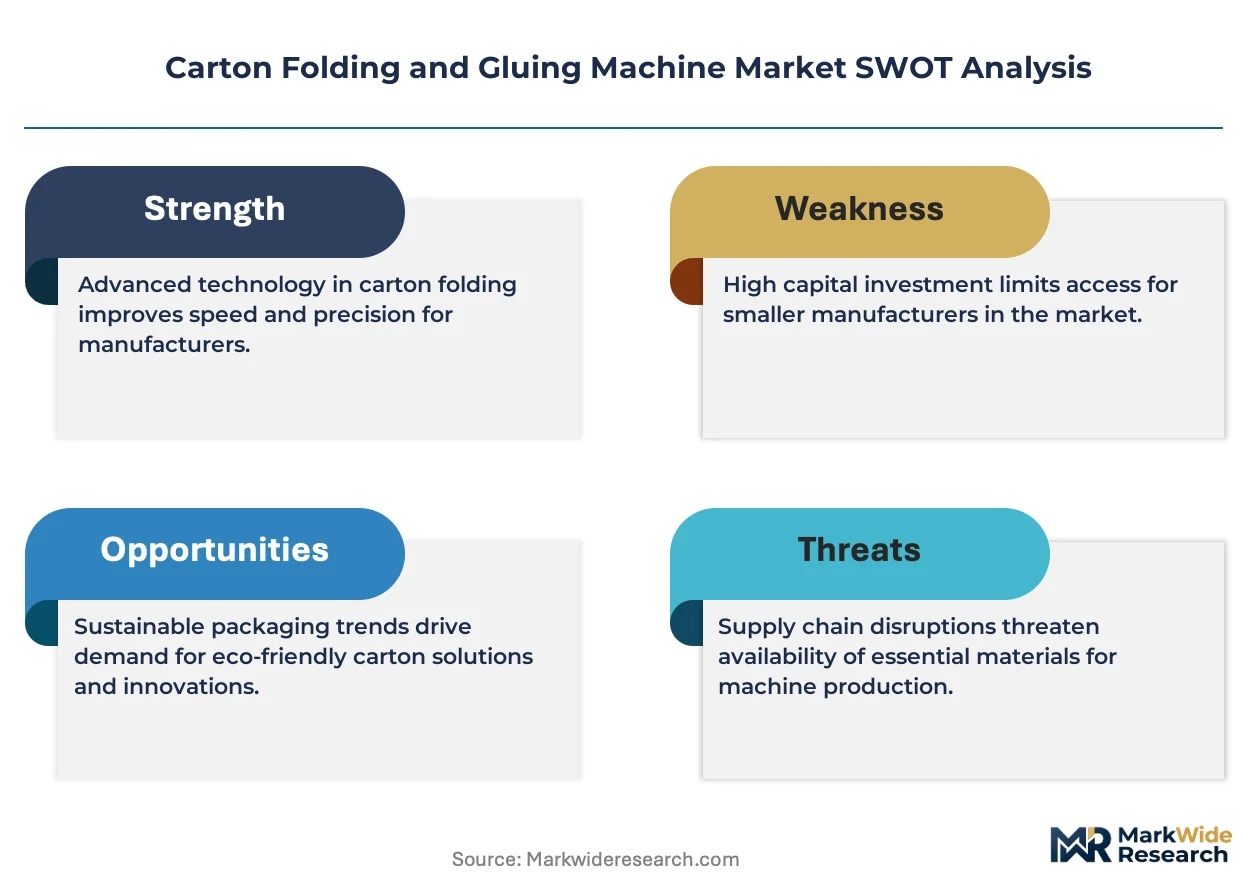
- Steel and aluminum input volatility:Precision-machined components and frame assemblies face cost pressure from commodity price swings affecting OEM margins.
- Technical talent scarcity:Servo programming and mechatronics expertise concentrates in southern Germany and Swiss manufacturing clusters, limiting expansion flexibility elsewhere.
- Extended validation timelines:FDA 21 CFR Part 11 compliance for pharmaceutical-grade installations stretches commissioning cycles and defers revenue recognition.
Strategic Opportunities
- India packaging conversion:Domestic folding carton capacity is consolidating near Mumbai and Ahmedabad, creating demand for mid-speed automatic configurations with localized service support.
- Recyclable substrate compatibility:Machine OEMs can capture premium positioning by certifying systems for lightweighted and fiber-based barrier boards ahead of EU packaging waste regulations.
- Predictive maintenance subscriptions:Cloud-connected diagnostics architectures enable recurring revenue streams and multi-year service contracts with large multinational converters.
Industry Challenges
- Legacy system integration friction:Brownfield plants struggle to retrofit servo-driven folder-gluers into existing press-to-finisher workflows without custom engineering.
- Cross-functional skill gaps:Maintenance teams lack combined mechanical-electrical-software competencies required for troubleshooting integrated automation stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carton Folding and Gluing Machine Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Custom End User: Food & Beverage, Personal Care, Pharmaceuticals, Consumer Electronics Technology: Electromechanical, Pneumatic, Servo, Hydraulic Application: Packaging, Assembly, Sealing, Labeling |
| Companies Covered | Bobst, Heidelberg, Koenig & Bauer, Fujian Zhongtai, Duran Machinery, Mitsubishi, KBA-Kammann, Anhui Gude Machinery Manufacturing, B&R Moll, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carton Folding and Gluing Machine Market Strategic Shifts
Digital connectivity and substrate diversification are redefining machine specification criteria as converters balance throughput targets against sustainability compliance and serialization traceability.
Servo motor architectures with integrated motion controllers are overtaking pneumatic actuation in new installations across high-volume pharmaceutical and cosmetics packaging plants. These systems deliver sub-millimeter registration accuracy at speeds exceeding 300,000 cartons hourly. The shift is compressing demand for legacy electromechanical configurations and repositioning energy efficiency as a procurement criterion.
REACH restrictions on adhesive chemistries are forcing reformulation of bonding systems toward water-based and hot-melt alternatives with lower volatile organic compound profiles. Machine builders must validate glue application hardware for modified viscosity and setting characteristics. Pharmaceutical-grade installations in the EU and United States are prioritizing substrate-adhesive-machine compatibility testing to preempt regulatory rejection.
Converters are unbundling after-sales service from capital equipment purchases and negotiating standalone predictive maintenance agreements with performance guarantees. This procurement model shift transfers uptime risk to OEMs and rewards vendors with established cloud infrastructure. The pattern is most pronounced among multinational consumer goods companies with centralized packaging engineering functions in Germany and the United States.
Carton Folding and Gluing Machine Market Segmentation
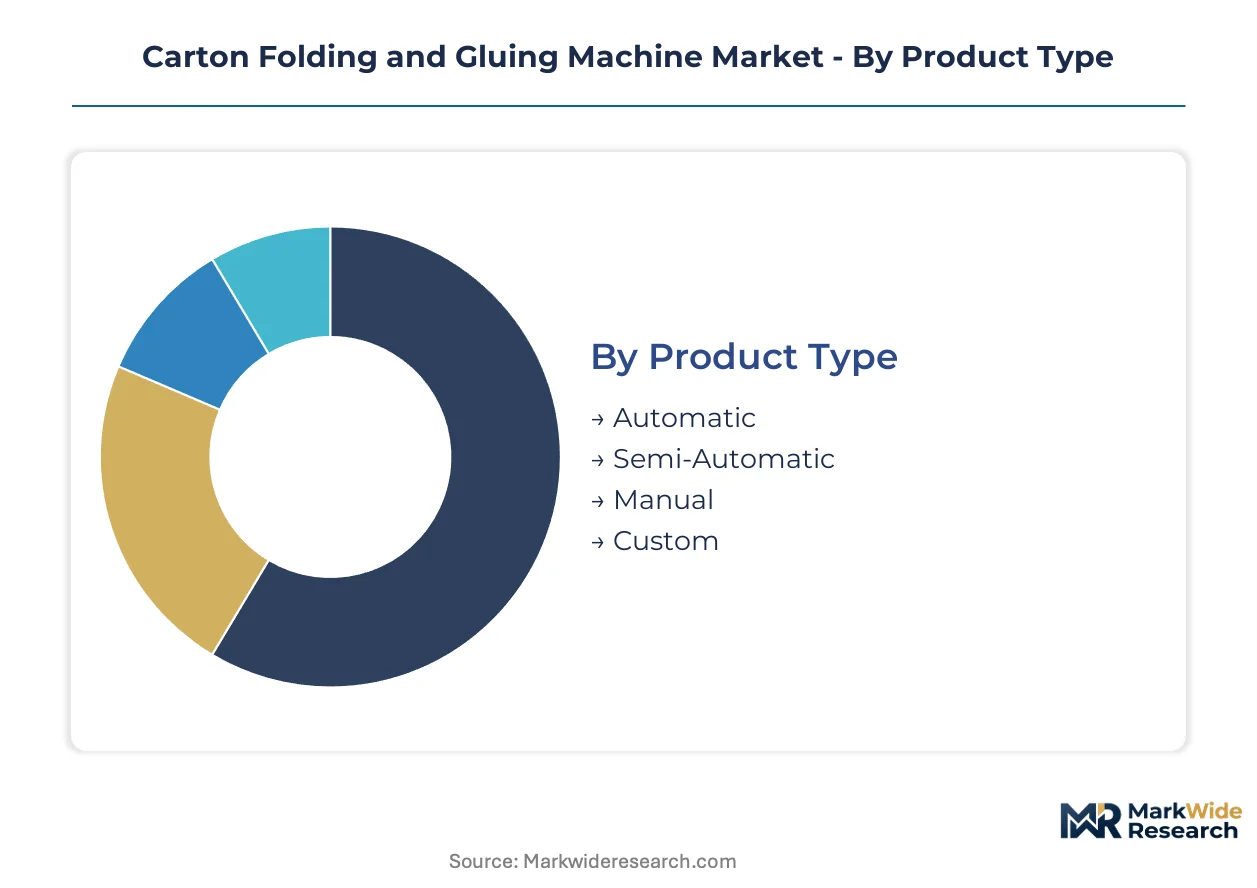
Segmentation in carton folding and gluing machines reveals how procurement priorities diverge between high-volume converters and specialized packaging operations. Equipment specifications vary sharply across pharmaceutical validation requirements versus food-grade throughput demands.
Product Type:
Supply concentration in automatic systems is reshaping how OEMs allocate engineering resources and service infrastructure.
- Automatic:Servo-driven architectures process 300,000-plus units hourly with integrated vision inspection and automatic changeover. Pharmaceutical converters in Germany and the United States specify these for validated lines under FDA and EU serialization mandates.
- Semi-Automatic:Hybrid configurations blend manual loading stations with automated folding sequences, serving mid-tier converters in India and Southeast Asia where labor costs offset capital intensity. Demand clusters near Mumbai and Ahmedabad packaging corridors.
- Manual:Entry-level benchtop units target artisanal producers and short-run specialty carton operations with minimal throughput requirements.
- Custom:Engineered-to-order systems accommodate non-standard board grades, window patching integrations, or unique structural formats for luxury cosmetics and spirits packaging.
Automatic configurations absorb the bulk of installed capacity; custom systems are expanding most quickly among premium brand owners.
End User:
Margin structures across end-use segments determine how aggressively OEMs pursue validation certifications and regional service footprints.
- Food & Beverage:The largest installed base serves ready-meal, dairy, and beverage cartons requiring moisture resistance and high-speed format flexibility. Quick-changeover capabilities dominate procurement criteria as SKU proliferation accelerates.
- Pharmaceuticals:Generates superior margin pools through FDA 21 CFR Part 11 and EU Falsified Medicines Directive compliance requirements. Serialization-ready folder-gluers with full batch traceability command premium positioning.
- Personal Care:Cosmetic and skincare brands specify systems with delicate handling for embossed or metallized boards, often requiring inline quality inspection.
- Consumer Electronics:Anti-static specifications and precision folding for retail-ready presentation drive specifications for smartphone and accessory packaging.
Food & Beverage retains the deepest installed base; Pharmaceuticals climbs the fastest on regulatory investment cycles.
Technology:
Energy efficiency and registration precision are compressing legacy technology shares as converters recalculate total cost of ownership.
- Servo:Integrated motion controllers deliver sub-millimeter accuracy at 400,000 units hourly while cutting energy consumption versus pneumatic alternatives. Electrification mandates in the EU and China's dual carbon goals accelerate displacement of legacy systems.
- Pneumatic:Compressed-air actuation persists in legacy installations and cost-sensitive markets though maintenance intensity and energy penalties erode competitiveness.
- Electromechanical:Cam-driven mechanisms dominate older fleets; brownfield retrofit friction limits replacement demand despite inferior flexibility.
- Hydraulic:Heavy-duty configurations for thick board grades and specialty structural applications retain niche positioning in industrial packaging segments.
Servo architectures command the majority of new capital expenditure; electromechanical systems are losing share fastest to electrification mandates.
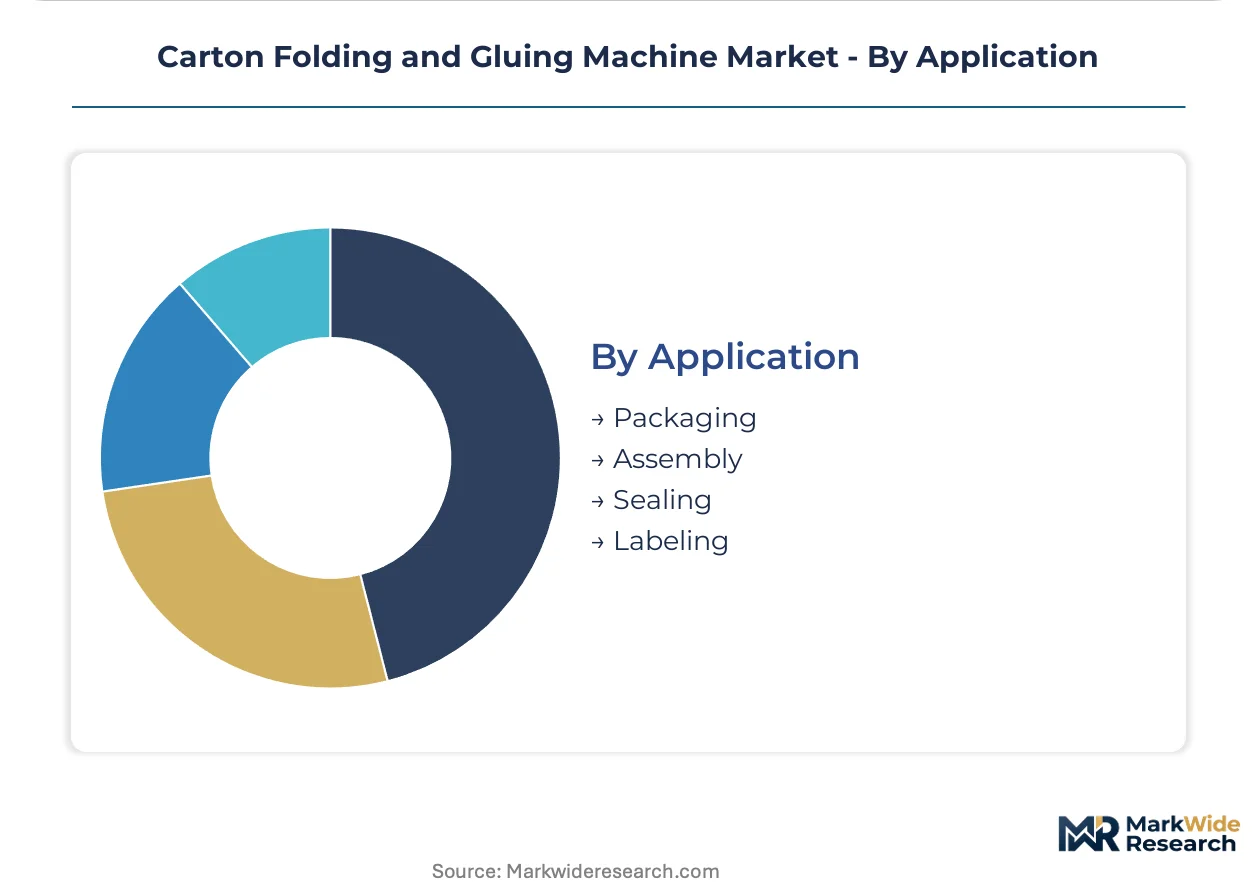
Application:
Workflow integration requirements determine how folder-gluer specifications cascade upstream to press and downstream to case packing decisions.
- Packaging:Primary and secondary carton conversion represents the core application, with shelf-ready presentation and structural integrity determining brand protection outcomes across consumer goods supply chains.
- Assembly:Multi-point gluing for complex carton geometries including crash-lock bottoms and auto-erect features serves e-commerce and retail display applications.
- Sealing:Tamper-evident and security sealing configurations address pharmaceutical and high-value consumer goods requirements with validated adhesive application.
- Labeling:Inline carton labeling with serialization and variable data printing integrates traceability directly into folding-gluing workflows.
Packaging commands the dominant share of machine deployments; labeling is gaining share fastest on serialization compliance deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, China, and the United States dominate machine production capacity, while consumption spreads across pharmaceutical hubs in Switzerland and food-processing corridors in India. This geographic split shapes how OEMs configure service networks and validation support.
Germany
Pharmaceutical serialization mandates under the EU Falsified Medicines Directive are accelerating validated folder-gluer deployments. CE marking requirements under the EU Machinery Directive govern all new installations. The southern manufacturing cluster around Bobst's Swiss-German operations and Heidelberg's Wiesloch headquarters concentrates high-precision servo system development.
China
Domestic folding carton converters are consolidating capacity near Shanghai and Guangzhou to serve e-commerce and beverage packaging demand. GB standards and SAMR technical regulations impose conformity assessment burdens on imported European equipment. The Yangtze River Delta hosts the densest concentration of mid-speed automatic machine installations serving export-oriented consumer goods manufacturers.
United States
FDA 21 CFR Part 11 validation protocols stretch commissioning cycles for pharmaceutical-grade installations. Serialization requirements for track-and-trace compliance are expanding machine fleets across New Jersey and North Carolina packaging corridors. Chicago and Milwaukee industrial zones sustain legacy electromechanical system maintenance demand alongside greenfield servo adoption.
India
Domestic capacity consolidation near Mumbai and Ahmedabad is creating demand for mid-speed automatic configurations with localized service support. BIS certification requirements and DGFT import regulations shape equipment procurement timelines. The Gujarat pharmaceutical packaging belt is prioritizing quick-changeover capabilities to accommodate SKU proliferation in generic drug exports.
Switzerland
Swissmedic pharmaceutical regulations and proximity to German OEMs position the Basel-Zurich corridor as a validation technology testbed. Precision engineering clusters in Winterthur and St. Gallen supply servo motion control components to folder-gluer manufacturers. The country's dual role as regulator and supplier creates feedback loops between compliance requirements and machine design specifications.
Carton Folding and Gluing Machine Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the carton folding and gluing machine market. European and Japanese incumbents dominate premium-tier validated systems, while Chinese and Indian fabricators capture mid-speed automatic demand through price-competitive positioning. Three archetypes define competitive structure: integrated press-to-finisher workflow specialists, standalone folder-gluer pure-plays, and diversified packaging machinery conglomerates. Consolidation through regional distributor acquisitions and technology licensing partnerships represents the dominant competitive moves as OEMs seek to anchor recurring service revenue.
Within the integrated workflow tier, Bobst and Heidelberg exemplify vendors competing through software-anchored ecosystem control. Koenig & Bauer occupies a position among pharmaceutical-grade specialists serving validated packaging environments. Among Asia-Pacific fabricators, Fujian Zhongtai and Anhui Gude Machinery Manufacturing represent the scale-driven segment addressing cost-sensitive converters in emerging markets. These companies anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Bobst |
| Heidelberg |
| Koenig & Bauer |
| Fujian Zhongtai |
| Duran Machinery |
| Mitsubishi |
| KBA-Kammann |
| Anhui Gude Machinery Manufacturing |
| B&R Moll |
| Others |
Value Chain & Pricing Dynamics
Steel and aluminum input volatility cascades through precision-machined frame assemblies to compress OEM margins, with servo motor costs from Swiss-German engineering clusters ultimately stratifying final equipment pricing across premium pharmaceutical-grade and mid-speed automatic tiers.
Pricing Analysis
Margin tightening in standard automatic configurations reflects steel price swings and electromechanical legacy displacement. Three-tier pricing structure across premium validated, standard automatic, and economy semi-automatic levels separates FDA-certified pharmaceutical systems from food-grade throughput machines. Certification level under EU Machinery Directive and FDA 21 CFR Part 11 commands substantial premia. Cost-down pressure on mid-speed segments accelerates because Chinese fabricators anchor price-competitive positioning. Emerging market converters in India exhibit highest price sensitivity; multinational pharmaceutical packaging operations in Germany and Switzerland demonstrate lowest.
Supply Chain Analysis
Freight cost differentials between European precision component sources and Asian final assembly sites redistribute competitive advantage. Supply concentrates in Germany, Switzerland, and China for servo motion controllers, precision-machined frames, and final system integration respectively. Raw material dependencies span high-grade steel alloys, aluminum extrusions, and rare-earth servo magnets. Single-source vulnerability concentrates in Swiss-German servo controller supply. Distribution runs through OEM-direct sales for pharmaceutical validators and regional distributor networks for mid-speed automatic configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo-driven automation is displacing pneumatic and electromechanical legacy across folding carton production, compressing technology-transition windows for stakeholders to recalibrate positioning.
For Market Incumbents: Lock in recurring service revenue through predictive maintenance subscriptions anchored by cloud-connected diagnostics architectures. Defend against Chinese mid-speed fabricators by deepening pharmaceutical validation certifications under FDA and EU Falsified Medicines Directive requirements. Prioritize vertical integration into servo motion controller supply through partnerships with Swiss-German engineering clusters. For New Entrants and Emerging Players: EU Falsified Medicines Directive serialization mandates in Germany and France open a window for specialized validators lacking incumbent service infrastructure. Target India's domestic capacity consolidation near Mumbai and Ahmedabad with localized mid-speed automatic configurations. Pursue white-space in recyclable substrate compatibility testing ahead of EU packaging waste regulations. Lead with after-sales service bundling to differentiate from price-driven Chinese competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-light designers with pharmaceutical validation expertise in Switzerland and southern Germany. Long-term viability hinges on software-anchored ecosystem control rather than hardware manufacturing scale. Monitor servo controller supply concentration as inflection indicator for margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Launch | Cloud-connected diagnostics architectures secure multi-year contracts with multinational converters in Germany. |
| Pharmaceutical Validation Certification | FDA 21 CFR Part 11 and EU Falsified Medicines Directive compliance commands premium positioning in serialized packaging. |
| Recyclable Substrate Compatibility Program | Water-based adhesive validation ahead of EU packaging waste regulations captures sustainability-driven procurement shifts. |
| Regional Service Network Expansion | Localized technical support in India and Southeast Asia defends market share against Chinese fabricators. |
| Servo System Backward Integration | Upstream control over motion controller supply mitigates Swiss-German single-source vulnerability and cost volatility. |
Study Parameters
Multi-period observation of installed machine fleet composition, technology substitution rates, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with maintenance directors at folding carton converters, OEM product managers, pharmaceutical packaging engineers, and aftermarket service heads. Secondary validation drew from EU Machinery Directive implementation records, FDA 510(k) and 21 CFR Part 11 guidance documents, SAMR technical regulation filings, and trade flow data for precision machinery. Bottom-up equipment deployment estimates triangulated against top-down packaging production capacity assessments.
Segment-weighting across product type, end user, technology, and application dimensions shaped the analytical framework. Modeled variables included servo adoption curves, pharmaceutical serialization compliance deadlines, and substrate lightweighting trajectories. CAGRs derived from equipment replacement cycles, brownfield retrofit elasticity, and greenfield capacity expansion patterns across the projection horizon. Industry-specific inputs incorporated REACH adhesive chemistry restrictions and extended producer responsibility framework evolution.
The model assumes a particular technology adoption path; alternative pathways for pneumatic system persistence or electromechanical retrofit viability would alter the outlook. Forecasts reflect assumptions about regulatory enforcement intensity, commodity price stabilization, and cross-border equipment certification reciprocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Global Volumetric Cup Fillers Market
Packaging Machinery
Orbital Wrapping Machine Market
Packaging Machinery
Thermal Film Laminating Machines Market
Packaging Machinery
Cup Filling Machine Market
Packaging Machinery
Global Blow Fill Seal Equipment Market
Packaging Machinery
Volumetric Filling Machines Market
Packaging Machinery
Glue Machine Market
Packaging Machinery
Hand-Held Capping Machines Market
Packaging Machinery
Automatic Liquid Filling Machines Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Stick Pack Packaging Machine Market
Packaging Machinery
Vertical Bagging Machine Market
Packaging Machinery
Capsule Filling Machines Market
Packaging Machinery
Tray Sealing Machines Market
Packaging Machinery
Cutter-Box Packaging Market
Packaging Machinery
Folding Gluing Machines Market