
 Case Packing Machines Market | 2026-2036
Case Packing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Case Packing Machines Market Outlook
Contract packagers is unwinding share toward in-house food and beverage producers seeking line integration. Schneider Packaging Equipment Company, Inc. leverages modular platform designs to serve mid-sized bottlers. Douglas Machine Inc. anchors its position in dairy and frozen food case packing through stainless-steel washdown architectures. Mpac Group plc competes on pharmaceutical validation protocols, differentiating its machines for cleanroom deployment.
Case packing machines mechanically erect, load, and seal corrugated containers around primary or secondary product arrays, typically operating at 10-120 cases per minute depending on product stability and collation pattern. Their core purpose is to bridge the gap between flexible primary packaging formats and rigid palletized distribution loads. Robotic case packers now capture the fastest expansion within product type segments as articulated arms handle irregular shapes and mixed-SKU trays that fixed mechanical systems cannot accommodate. Servo motor technology leads the technology dimension for precision and changeover speed, while pneumatic systems persist in cost-sensitive emerging markets where compressed air infrastructure already exists.
FDA cGMP and EU MDR impose validation documentation and traceability requirements that elevate machine qualification costs for pharmaceutical end users. OSHA lockout/tagout standards and EU Machinery Directive 2006/42/EC mandate interlocked guarding and risk assessments that shape design priorities for manufacturers exporting across jurisdictions. Stakeholders must weigh total cost of ownership against throughput flexibility as labor availability tightens and SKU proliferation accelerates.
Market Dynamics
Pharmaceutical serialization mandates under EU MDR and FDA track-and-trace rules are forcing case packing machine architectures toward integrated vision systems and database connectivity, compressing design cycles and elevating qualification costs for suppliers.
Growth Catalysts
- EU MDR Serialization Mandates:Pharmaceutical manufacturers in Germany and France must deploy automated case packing lines with aggregation capabilities to meet unit-level traceability requirements by statutory deadlines.
- Servo Motor Adoption:Food and beverage producers across the United States are retrofitting pneumatic lines with servo-driven systems to achieve sub-second changeovers and reduced compressed air dependency.
- Labor Shortages in Processing Hubs:Meat and dairy processors in China's coastal provinces face acute operator scarcity, accelerating capital deployment toward robotic case packing cells.
Market Restraints
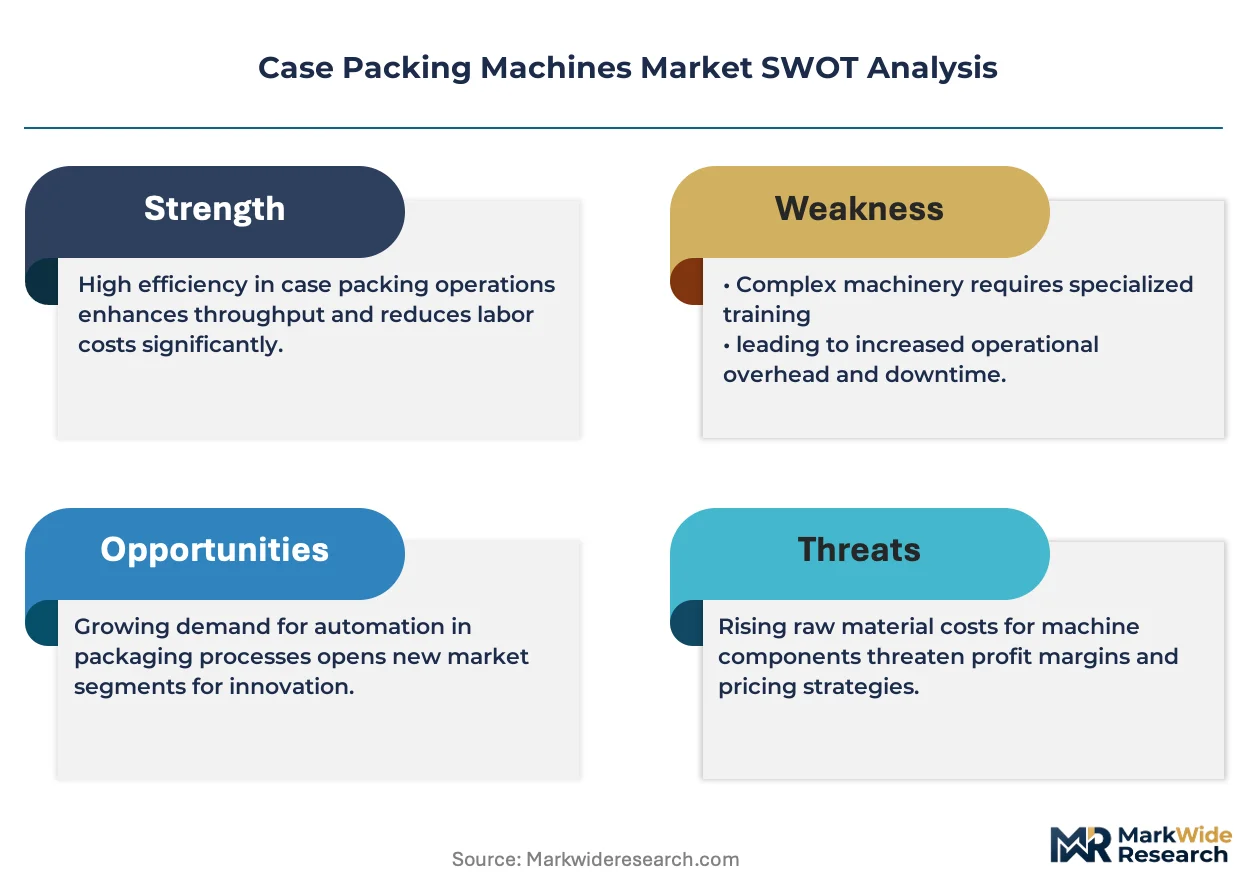
- Stainless Steel Input Volatility:Grade 304 and 316 stainless steel price swings directly compress margins for manufacturers building washdown architectures for dairy and frozen food applications.
- Validation Documentation Burden:FDA cGMP qualification protocols impose 12-18 month machine acceptance timelines that deter mid-sized pharmaceutical buyers from greenfield investments.
- Compressed Air Infrastructure Lock-In:Emerging market facilities in Brazil and Mexico retain pneumatic case packers due to sunk capital in air compressor networks, slowing servo conversion.
Strategic Opportunities
- Contract Packaging Pivot:Third-party logistics providers in India are installing modular case packing lines to capture SKU proliferation from e-commerce grocery platforms.
- Cleanroom Deployment Protocols:EU MDR Annex I requirements for aseptic processing create demand for HEPA-integrated case packing systems in sterile injectables manufacturing.
- Retrofit Servo Kits:Technology suppliers are developing drop-in servo actuation packages that upgrade legacy mechanical case packers without full line replacement.
Industry Challenges
- Controls Integration Complexity:Pharmaceutical manufacturers struggle to synchronize case packing machine PLCs with centralized MES and serialization databases.
- Multi-Craft Maintenance Shortage:Facilities lack technicians cross-trained in mechanical, electrical, and software troubleshooting for hybrid robotic-mechanical systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Case Packing Machines Market |
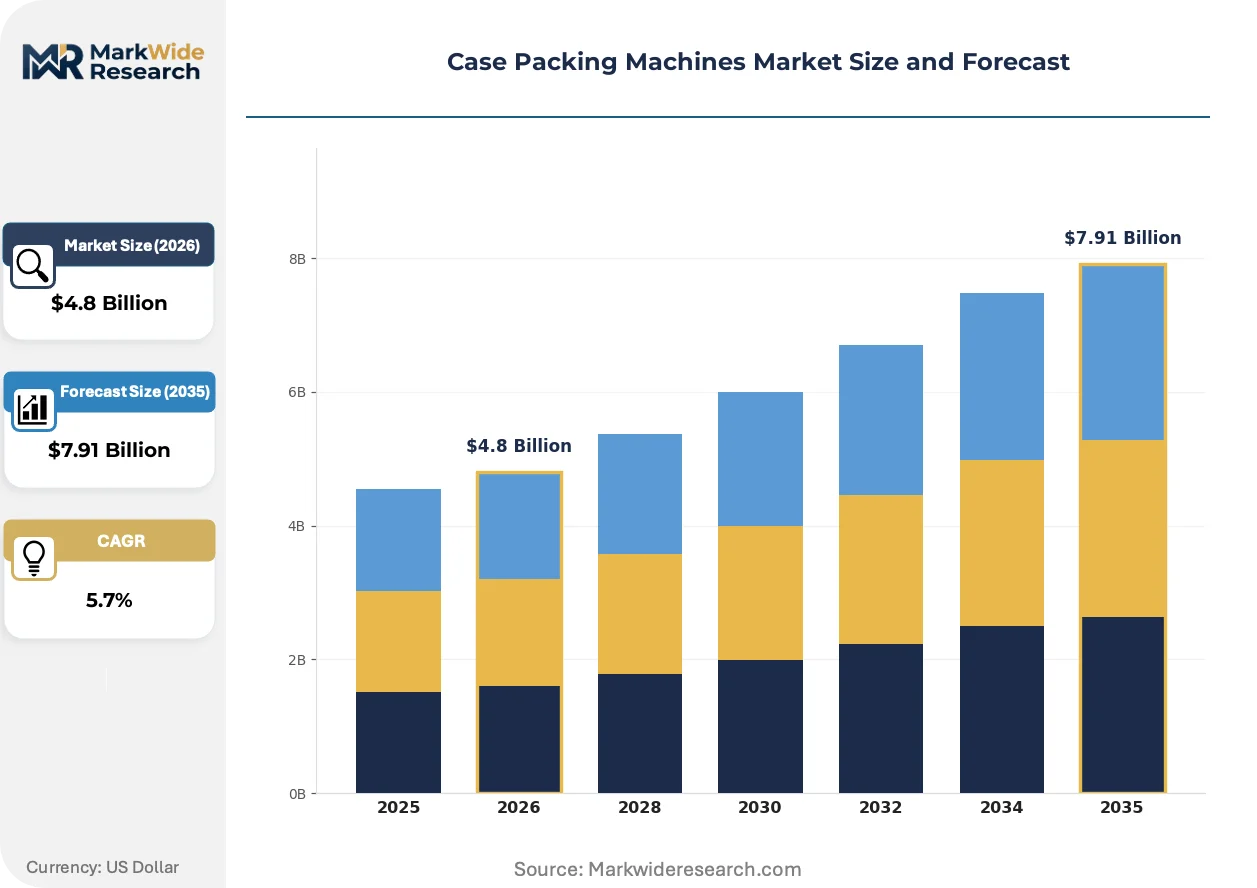
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Case Packers, Vertical Case Packers, Robotic Case Packers, Automated Case Packers Application: Beverages, Food, Pharmaceuticals, Personal Care End User: Food Manufacturers, Beverage Producers, Pharmaceutical Companies, Cosmetic Firms Technology: Servo Motor Technology, Pneumatic Technology, Mechanical Technology, Hybrid Technology |
| Companies Covered | Schneider Packaging Equipment Company, Inc., Douglas Machine Inc., Fallas Automation, Econocorp, Mpac Group plc, ADCO Manufacturing, Combi Packaging System, LLC, JOCHAMP, Tekpak Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Case Packing Machines Market Strategic Shifts
Articulated robotic arms are penetrating case packing applications previously reserved for fixed mechanical systems, driven by SKU proliferation and irregular primary package geometries that defy traditional collation patterns.
Servo motor technology is supplanting pneumatic actuation in high-speed beverage and dairy lines. Bottlers in Germany and the United States are specifying servo-driven case erectors and loaders to eliminate compressed air consumption and enable programmable motion profiles. This transition is compressing the installed base of pneumatic machines into commodity segments while elevating servo suppliers into premium positioning.
EU MDR Article 10 and FDA 21 CFR Part 11 are mandating electronic records and audit trails for pharmaceutical packaging equipment. Machine builders must now embed barcode verification cameras and database connectivity as standard rather than optional features. Cleanroom-deployable case packers with IQ/OQ/PQ documentation packages command pricing premiums in sterile processing facilities.
Food and beverage producers are unbundling after-sales service contracts from initial equipment purchases, treating maintenance as a separate procurement category. Large multinational CPGs in China and the United States now negotiate multi-site service agreements with third-party automation integrators rather than OEM service departments. This disintermediation pressures traditional suppliers to restructure revenue models around performance guarantees rather than spare parts markups.
Case Packing Machines Market Segmentation
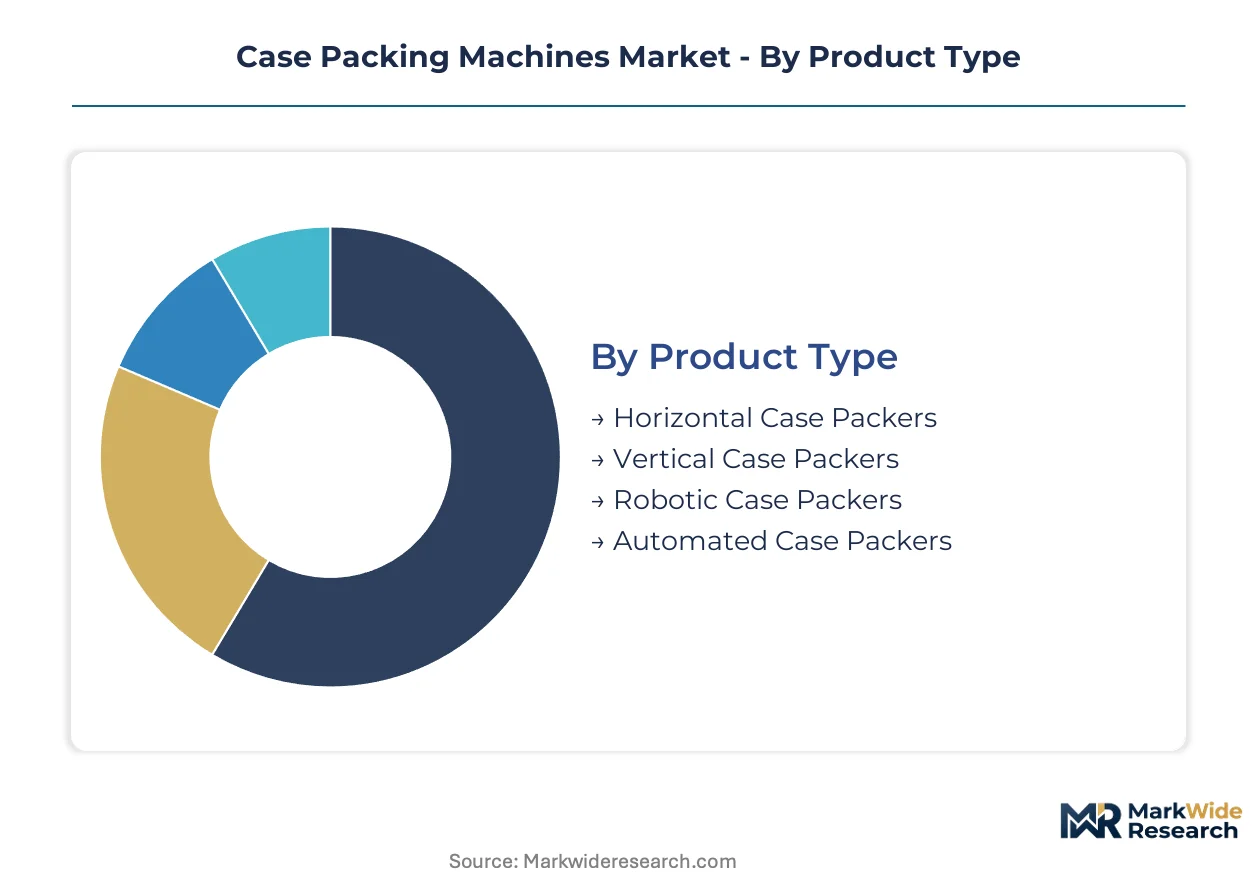
Segmentation in case packing machines reveals how equipment specifications align with regulatory pressures, product fragility, and line speed requirements across discrete manufacturing environments. Distinct margin profiles emerge where validation documentation, washdown architectures, or robotic flexibility command pricing premiums.
Product Type:
Margin pools concentrate in robotic and automated systems where integration complexity and software content elevate pricing power above mechanical alternatives.
- Robotic Case Packers:Articulated arm configurations with vision-guided pick-and-place accommodate irregular geometries and mixed-SKU trays that fixed mechanical systems cannot process. Demand from pharmaceutical cleanrooms and e-commerce fulfillment centers in Germany and the United States drives specification toward IP65-rated enclosures and sub-millimeter repeatability.
- Automated Case Packers:Integrated lines combining case erection, loading, and sealing with centralized controls dominate high-volume beverage operations. Chinese dairy processors deploy these systems to offset coastal labor shortages while maintaining throughput above 100 cases per minute.
- Horizontal Case Packers:Side-loading configurations handle stable rectangular products in gravity-fed arrangements common to bottled water and shelf-stable food.
- Vertical Case Packers:Top-loading architectures suit fragile or nested products where compression forces must be minimized.
Automated case packers hold installed capacity. Robotic case packers are rotating up the share rankings.
Application:
Application segmentation tracks how regulatory intensity and product stability requirements fragment equipment specifications across consumer industries.
- Pharmaceuticals:Serialization mandates under FDA track-and-trace rules and EU MDR impose aggregation-capable architectures with vision verification and database connectivity. Machine qualification timelines of 12-18 months elevate total cost of ownership while restricting supplier pools to validated vendors.
- Food:Washdown-compatible stainless-steel construction and rapid changeover capability dominate specifications for frozen and refrigerated products. Grade 304 and 316 input volatility directly compress margins for manufacturers serving dairy and ready-meal segments.
- Beverages:High-speed carbonated and still water lines prioritize servo-driven precision over mechanical indexing to achieve sub-second format changes.
- Personal Care:Cosmetic and hygiene product lines emphasize gentle handling for irregular primary packages with decorative finishes.
Food applications hold installed capacity. Pharmaceuticals is gaining share fastest.
End User:
End user structure reflects divergent procurement capabilities between multinational CPGs with centralized engineering teams and mid-sized operators prioritizing modularity.
- Pharmaceutical Companies:Serialization compliance and cleanroom deployment requirements drive specification toward IQ/OQ/PQ documentation packages and HEPA-integrated systems. EU MDR Annex I aseptic processing mandates create demand premiums for sterile injectables manufacturing.
- Food Manufacturers:SKU proliferation and private-label volatility push mid-sized processors toward modular platforms with rapid reconfiguration. Contract packaging unwinding toward in-house operations concentrates investment in integrated lines.
- Beverage Producers:Retrofit activity dominates as established bottlers convert pneumatic legacy equipment to servo actuation for energy efficiency.
- Cosmetic Firms:Premium positioning and batch flexibility requirements favor compact robotic cells over continuous-motion mechanical systems.
Food manufacturers hold installed capacity. Pharmaceutical companies is climbing the fastest.
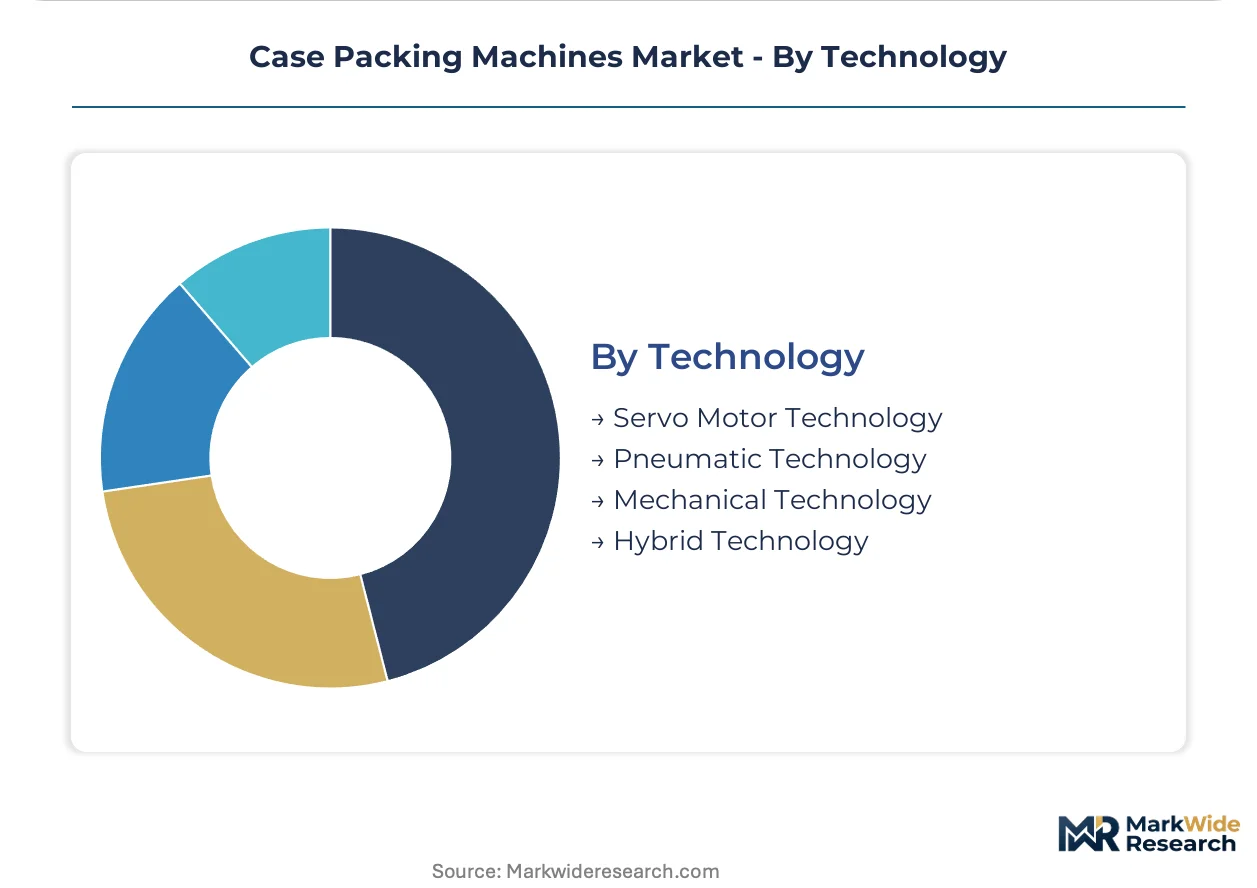
Technology:
Technology segmentation captures the displacement curve as precision motion control supplants compressed air infrastructure in premium applications.
- Servo Motor Technology:Programmable motion profiles enable sub-second changeovers and eliminate compressed air dependency. German and United States beverage producers specify servo-driven case erectors and loaders to reduce operating costs and improve precision.
- Hybrid Technology:Combinations of servo axes with pneumatic clamping or vacuum generation balance capital efficiency with performance in mid-speed applications. Emerging market facilities in Brazil leverage existing compressor infrastructure while upgrading critical motion axes.
- Pneumatic Technology:Compressed air actuation persists in cost-sensitive emerging markets where sunk capital in compressor networks slows conversion.
- Mechanical Technology:Fixed cam and linkage systems occupy commodity segments where format stability and low acquisition cost outweigh flexibility requirements.
Pneumatic technology holds installed capacity. Servo motor technology is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in European case packing machinery distribution, while the Yangtze River Delta's manufacturing density anchors Chinese production capacity for export markets.
United States
Meat and dairy processors across Wisconsin and California deploy robotic case packing cells to offset acute operator scarcity in processing hubs. FDA 21 CFR Part 11 mandates electronic records and audit trails for pharmaceutical packaging equipment, compressing supplier qualification timelines. Chicago's automation corridor concentrates servo-driven retrofit activity as beverage bottlers eliminate compressed air dependency.
Germany
Bavarian pharmaceutical manufacturers expand automated lines with aggregation capabilities to meet EU MDR unit-level traceability deadlines. The EU Machinery Directive 2006/42/EC mandates interlocked guarding and risk assessments that shape exporter design priorities. Stuttgart's industrial automation cluster anchors servo motor technology development for sub-second changeover specifications.
China
Coastal dairy processors in Jiangsu and Zhejiang provinces accelerate capital deployment toward robotic cells amid acute labor shortages. SAMR's national food safety standards elevate washdown architecture requirements for frozen food applications. The Pearl River Delta's electronics manufacturing base supplies vision system components for serialization-integrated machines.
India
Third-party logistics providers in Maharashtra install modular case packing lines to capture SKU proliferation from e-commerce grocery platforms. FSSAI's packaging material regulations shape stainless steel specification standards for food contact applications. Gujarat's pharmaceutical manufacturing belt drives demand for IQ/OQ/PQ documentation packages in sterile processing facilities.
Brazil
Food processors in São Paulo retain pneumatic case packers due to sunk capital in existing compressor networks, slowing servo conversion timelines. ANVISA's pharmaceutical manufacturing standards impose validation documentation burdens comparable to FDA protocols. The Campinas technology corridor concentrates hybrid technology adoption balancing capital efficiency with performance upgrades.
Case Packing Machines Market Competitive Environment
Listed leaders compete with private specialists across validation documentation capabilities and service contract structures. The vendor base stratifies into three tiers: multinational OEMs with pharmaceutical qualification expertise, regional fabricators serving food and beverage retrofits, and emerging robotic integrators capturing e-commerce fulfillment demand. Consolidation pressure concentrates among mid-sized players lacking modular platform architectures. Dominant competitive moves include backward integration into servo drive manufacturing and multi-site service agreement disintermediation of traditional OEM service departments.
Within the pharmaceutical validation tier, Mpac Group plc and Schneider Packaging Equipment Company, Inc. exemplify archetypes emphasizing IQ/OQ/PQ documentation packages and cleanroom deployment protocols. Among stainless-steel washdown specialists, Douglas Machine Inc. occupies a position reflecting dairy and frozen food architecture concentration. These three anchors represent divergent strategic positioning across regulatory intensity segments rather than overlapping capability claims.
| Leading Market Players |
|---|
| Schneider Packaging Equipment Company, Inc. |
| Douglas Machine Inc. |
| Fallas Automation |
| Econocorp |
| Mpac Group plc |
| ADCO Manufacturing |
| Combi Packaging System, LLC |
| JOCHAMP |
| Tekpak Automation |
| Others |
Value Chain & Pricing Dynamics
FDA cGMP and EU MDR qualification protocols gate both supplier entry and price differentiation in pharmaceutical case packing tiers, compressing vendor pools while elevating documentation premiums. Machine builders must absorb validation engineering costs upfront, feeding through to three-tier pricing structures that separate validated cleanroom systems from standard food-grade architectures.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with multinational CPGs extracting 15-25% effective price reductions on multi-site fleet orders. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales bundling intensity. Price differentiation hinges on IQ/OQ/PQ documentation completeness and stainless-steel grade specification. Pricing pressure stems from stainless steel input volatility in washdown architectures, with Grade 304 and 316 swings compressing margins for dairy equipment specialists. Mid-sized food processors exhibit highest price sensitivity due to capital constraint, while pharmaceutical serialization mandates render large buyers relatively inelastic on compliance-critical features.
Supply Chain Analysis
Germany, China, and the United States anchor precision motion control and stainless-steel fabrication for case packing machinery. Component sourcing draws from Taiwan for servo drives, Japan for precision bearings, and domestic foundries for washdown-grade enclosures. Single-source vulnerability concentrates in high-torque servo motor supply chains where two Asian producers dominate global capacity. Distribution runs through regional automation integrators who bundle installation with third-party service contracts, disintermediating traditional OEM aftermarket revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects as modular machine architectures enable software-defined reconfiguration, with interoperability between case packers and centralized MES systems becoming the decisive ecosystem battleground.
For Market Incumbents: Fortify validation documentation capabilities to defend pharmaceutical tier positioning against emerging robotic integrators. Backward integration into servo drive manufacturing reduces exposure to Asian supply concentration while capturing margin pools in precision motion control. Prioritize multi-site service agreement structures that counter third-party automation integrator disintermediation.
For New Entrants and Emerging Players: Differentiate on retrofit servo kit deployment for legacy pneumatic installations in Brazil and Mexico, where compressed air infrastructure lock-in slows incumbent conversion. Target contract packaging pivot opportunities in Indian third-party logistics, where e-commerce SKU proliferation outruns existing equipment flexibility. Pursue cleanroom deployment protocols for sterile injectables as the most penetrable pharmaceutical sub-segment lacking validated vendor density.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across servo motor technology lines as precision motion control R&D demands escalate. Five-to-ten-year viability favors platform-anchored specialists with modular architectures over fixed-mechanical commodity producers. Acquisition target archetype: mid-sized robotic integrators with pharmaceutical qualification expertise but limited geographic footprint. Signal to monitor: FDA enforcement intensity on 21 CFR Part 11 audit trail completeness as demand inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Retrofit Servo Kit Development | Enables pneumatic-to-servo conversion without full line replacement, capturing locked-in emerging market installed base. |
| IQ/OQ/PQ Documentation Packaging | Accelerates pharmaceutical machine acceptance timelines, differentiating suppliers under FDA and EU MDR mandates. |
| Multi-Site Service Agreement Restructuring | Counteracts third-party integrator disintermediation by bundling performance guarantees with spare parts supply. |
| Backward Integration into Servo Drives | Reduces supply chain vulnerability to Asian concentration while capturing precision motion control margin pools. |
| Cleanroom Deployment Protocol Investment | Captures EU MDR Annex I aseptic processing premiums in sterile injectables manufacturing expansion. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association machinery shipment data, and stainless steel price indices. Primary interviews engaged packaging line engineers at dairy processors, pharmaceutical manufacturing directors, aftermarket service heads at automation integrators, and procurement leads at beverage bottlers. Secondary validation drew from FDA warning letter databases, EU MDR technical documentation guidance, SEC equipment manufacturer filings, and VDMA machinery production statistics. Bottom-up equipment unit economics triangulate against top-down industry value chain estimates.
Segmentation dimensions modeled span product type, application, end user, and technology across the analysis window. Servo motor adoption curves, pharmaceutical serialization compliance deadlines, and labor shortage intensity by processing hub geography inform growth trajectory assumptions. CAGRs derive from equipment replacement cycle analysis and greenfield capacity expansion announcements. Stainless steel input cost pass-through elasticity and validation documentation burden effects shape margin projection sensitivity.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement intensity and labor scarcity in developed market processing hubs; material deviation would warrant model refresh. Recalibration cycles align with material shifts in EU MDR implementation timelines, FDA inspection priority changes, and servo motor supply chain reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Tubular Form Fill and Seal Machines Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Hand-Held Capping Machines Market
Packaging Machinery
Robotic Carton Loading Machine Market
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Bakery Packaging Machine Market
Packaging Machinery
Lid Applicator Machine Market
Packaging Machinery
Shrink Wrapping Machines Market
Packaging Machinery
Cup Fill and Seal Machine Market
Packaging Machinery
Sack Filling Machine Market
Packaging Machinery
Carton Erecting Machinery Market
Packaging Machinery
Metal Banding Machine Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Global Film Coating Machine Market
Packaging Machinery
Volumetric Boom Filling Machine Market