
 Oil Packing Machine Market | 2026-2036
Oil Packing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Packing Machine Market Analytics
The EU Green Deal's packaging sustainability targets are shifting demand toward machines compatible with mono-material pouches and reduced plastic formats. GEA Group leverages its hygienic design heritage to anchor premium positions in aseptic oil filling lines across European dairy-oil copackers. Nichrome Packaging Solutions competes on cost-engineered auger systems for regional edible oil brands in South Asia. Tetra Laval Group dominates aseptic carton formats for cooking oil retail packs through its integrated processing-packaging platforms.
An oil packing machine is an automated or semi-automated industrial system that meters, fills, seals, and labels containers with liquid or viscous oil products, typically achieving fill accuracies within plus or minus one percent and handling viscosities from light vegetable oils to heavy lubricant grades. Piston fillers command the largest installed base due to their precision with high-viscosity edible and industrial oils, while pump fillers represent the fastest-growing category as chemical processors adopt positive-displacement systems for aggressive lubricant formulations. Pouch packaging is expanding share fastest among packaging types, driven by flexible film cost advantages and e-commerce logistics efficiency, though bottles retain the deepest margin pools in branded edible oil segments where optical clarity and shelf differentiation command premium positioning.
The US FDA enforces food-contact material compliance and sanitary design standards that dictate stainless steel construction and clean-in-place capability for edible oil packing equipment sold into food-grade applications. REACH and EU F-Gas Regulation constrain sealant and refrigerant choices in European-built machines, pushing manufacturers toward mechanical sealing alternatives. China's SAMR implements national food safety standards that require traceability coding on all packaged cooking oil, directly driving integrated vision and laser-marking module demand. Buyers must weigh regional certification burdens against modular upgrade paths when specifying cross-border production footprints.
Market Dynamics
The EU Green Deal's packaging sustainability mandates are compressing demand timelines for mono-material-compatible filling systems, forcing packagers to retire multi-layer pouch lines ahead of depreciation schedules.
Growth Catalysts
- India's SAMR traceability mandate:National food safety standards now require laser-marked coding on all packaged cooking oil, directly pulling integrated vision systems into bottling corridors.
- Nitrogen flushing protocols:Oxidation-resistant sealing is converging with stainless steel piston architectures as edible oil processors in Southeast Asia automate to meet retail traceability requirements.
- Aseptic carton expansion:Dairy-oil copackers across European processing hubs are retrofitting lines for extended-shelf-life formats, anchoring demand for hygienic-design filling equipment.
Market Restraints
- Stainless steel input volatility:Grade 316L sheet pricing swings directly compress margin pools for European and Indian equipment fabricators locked into fixed-price contracts.
- REACH chemical constraints:Sealant formulation restrictions under ECHA oversight are forcing mechanical redesign cycles that extend qualification timelines by eight to fourteen months.
- Positive-displacement pump saturation:Aggressive lubricant processors in North American chemical corridors have largely converted to pump fillers, capping greenfield expansion for incumbent piston architectures.
Strategic Opportunities
- Flexible film logistics:Pouch packaging formats are capturing e-commerce channel preference in Southeast Asian retail networks, opening white space for cost-engineered auger systems.
- EU F-Gas refrigerant phase-down:Mechanical sealing alternatives are receiving engineering priority as European OEMs redesign climate-controlled filling environments ahead of compliance deadlines.
- Retrofit automation kits:Mid-scale edible oil brands in South Asia are modularizing legacy lines with vision and nitrogen modules rather than full line replacement.
Industry Challenges
- Clean-in-place validation:FDA sanitary design standards for food-grade applications require documented protocol verification that extends commissioning timelines and strains field service capacity.
- Cross-border certification stacking:Equipment specified for multi-country footprints must simultaneously satisfy FDA, REACH, and SAMR requirements, multiplying documentation burden without revenue uplift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Packing Machine Market |
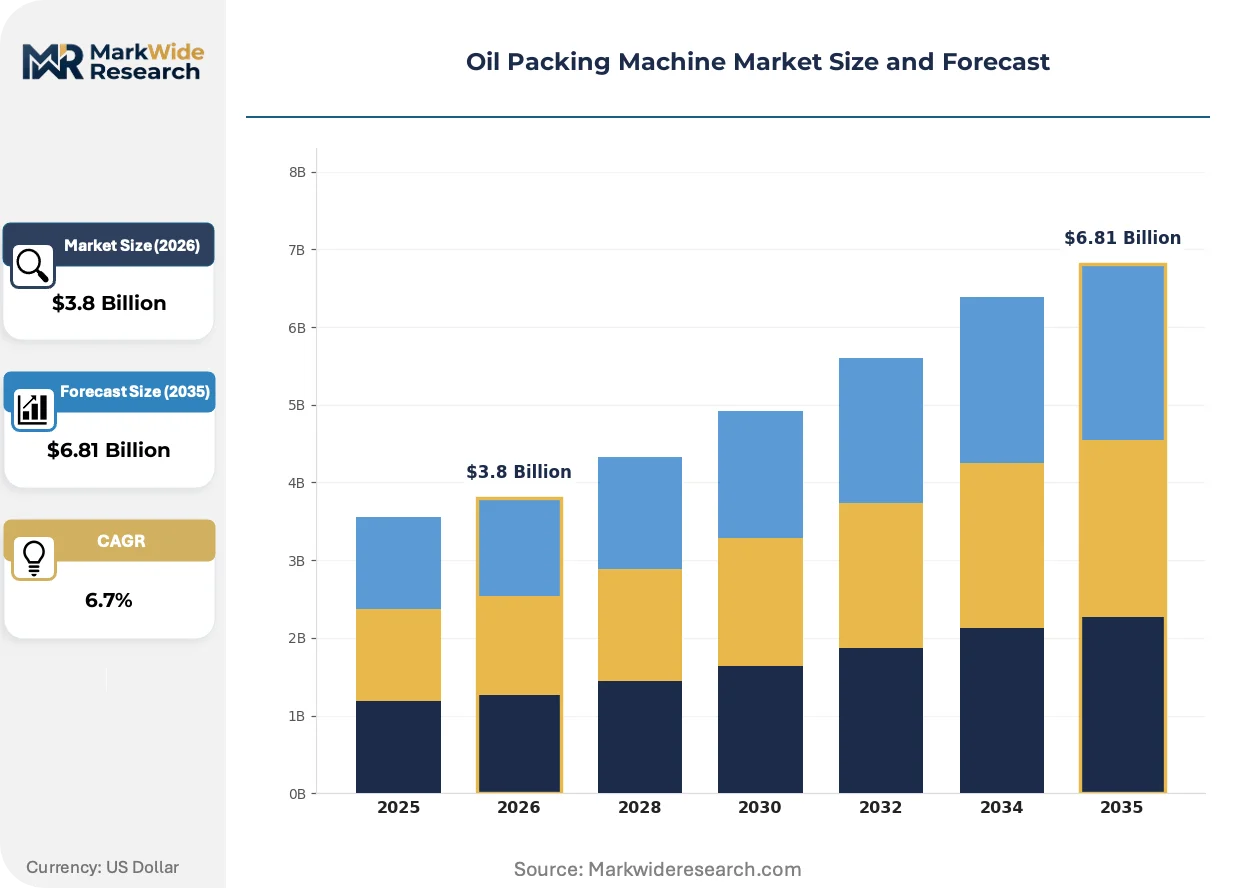
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piston Fillers, Auger Fillers, Gravity Fillers, Pump Fillers Packaging Type: Bottles, Pouches, Cans, Jars End User: Food Industry, Cosmetic Industry, Chemical Industry, Pharmaceutical Sector Sales Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Niverplast B.V., Turpack Packaging Machinery, GEA Group, Nichrome Packaging Solutions, Gemseal, KHS Group, SIG Combibloc Group Ltd., Tetra Laval Group, Syntegon Technology GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Packing Machine Market Evolving Landscape
Automation architectures are fragmenting between precision-oriented aseptic systems and cost-optimized flexible lines, with equipment specification increasingly tied to channel strategy rather than product viscosity alone.
Machine vision is converging with laser-marking modules to form integrated traceability stacks that eliminate separate coding stations. Edible oil processors in India and Southeast Asia are adopting these combined units under regulatory pressure from SAMR and evolving national food safety mandates. The convergence is compressing floor space requirements and reducing integration complexity for mid-scale bottling operations.
REACH and the EU F-Gas Regulation are constraining refrigerant and sealant chemistries in European-built equipment, pushing manufacturers toward dry mechanical seals and ambient-temperature filling protocols. Chemical processors are absorbing redesign costs for aggressive lubricant lines, while edible oil packagers face compressed qualification windows as 2025 compliance deadlines approach. The regulatory pressure is most acute in dairy-oil copacking facilities where aseptic requirements intersect with climate control.
Service unbundling is fragmenting traditional turnkey contracts into separate hardware, software, and maintenance streams. Large edible oil refiners in India are procuring filling equipment without bundled after-sales agreements, instead negotiating direct spare-part supply with component manufacturers. The disintermediation is visible in South Asian procurement patterns where packagers seek to decouple capital expenditure from long-term service lock-in.
Oil Packing Machine Market Segmentation
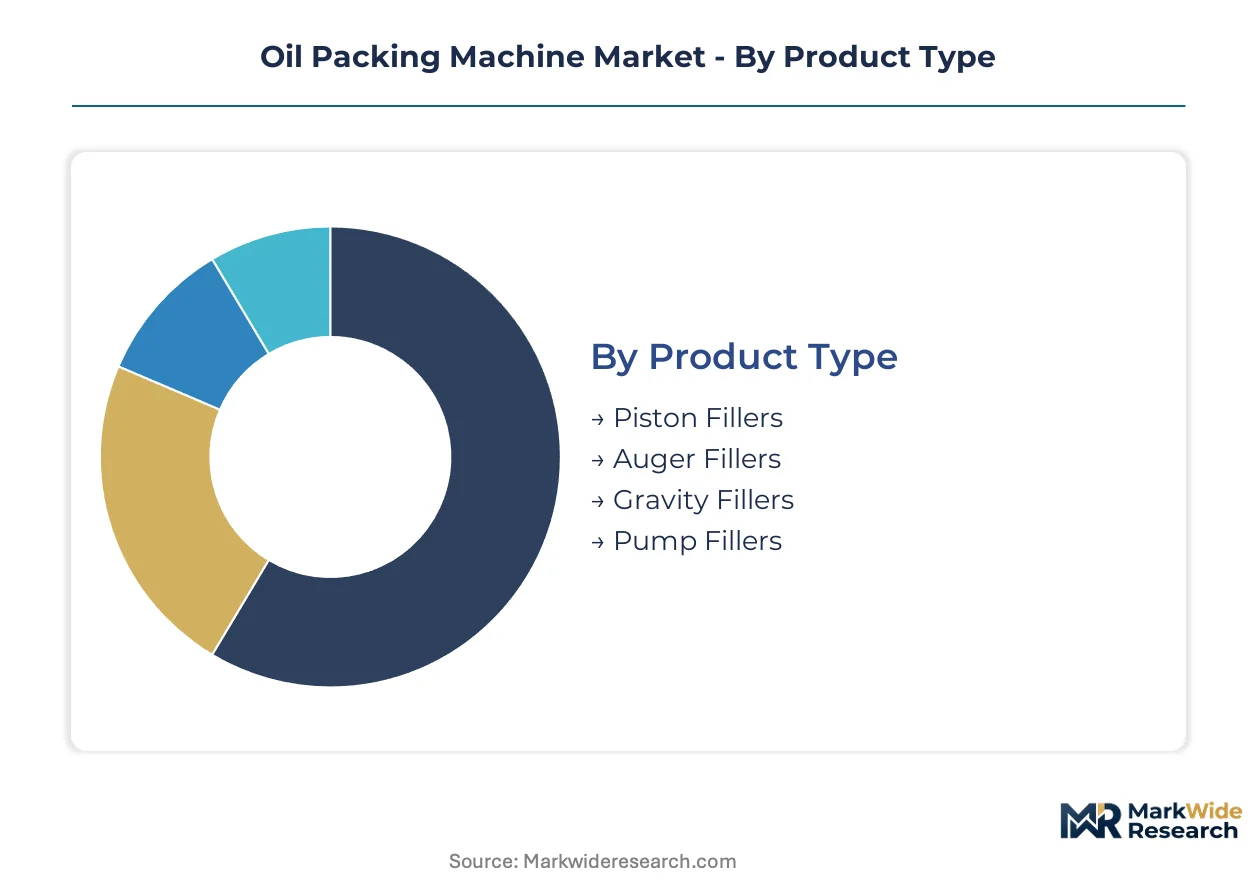
Oil packing machine procurement patterns diverge sharply between integrated refinery operations and standalone packaging facilities. Equipment specification now tracks channel strategy more closely than product viscosity, forcing manufacturers to architect modular platforms that span multiple output formats.
Product Type:
Standalone piston architectures dominate high-viscosity edible oil corridors, while embedded pump systems penetrate chemical processing lines with aggressive lubricant formulations.
- Piston Fillers:Positive-displacement pistons meter high-viscosity oils within plus or minus one percent accuracy. India's refining corridors anchor installed base expansion as packagers automate under SAMR traceability mandates. Stainless steel 316L construction with integrated nitrogen flushing captures preference for oxidation-sensitive edible oils.
- Pump Fillers:Positive-displacement rotary and gear pumps handle aggressive chemical formulations without seal degradation. North American lubricant processors drive category momentum as facilities convert from legacy gravity systems. REACH-constrained sealant chemistries accelerate mechanical seal adoption in European-built equipment.
- Auger Fillers:Screw-feed mechanisms excel at viscous semi-solids and paste-like oil products. Regional edible oil brands in South Asia specify cost-engineered auger systems for mid-scale pouch operations.
- Gravity Fillers:Atmospheric-pressure filling suits low-viscosity light vegetable oils with minimal foam generation. Small-batch artisanal processors retain gravity installations where capital constraints limit automation investment.
Volume placements concentrate in piston architectures; the faster expansion belongs to pump fillers.
Packaging Type:
Cost tier stratification separates premium optical clarity formats from logistics-optimized flexible films.
- Bottles:PET and glass containers command deepest margin pools in branded edible oil segments. Southeast Asian retail networks sustain bottle demand where shelf differentiation justifies premium positioning. Optical clarity requirements drive integrated vision system specification for defect detection.
- Pouches:Multi-layer and mono-material flexible films capture e-commerce channel preference. India's mid-scale packagers retrofit legacy lines with pouch-compatible sealing modules rather than full replacement. EU Green Deal sustainability timelines accelerate mono-material format conversion ahead of multi-layer depreciation schedules.
- Cans:Metal containers serve industrial lubricant and chemical oil segments requiring impact resistance. Automotive service channel procurement sustains tinplate and aluminum can demand.
- Jars:Wide-mouth glass and plastic jars target cosmetic oil and premium culinary segments. Cosmetic industry packagers specify jar formats for facial oil and serum applications.
Revenue concentration pools in bottle formats; pouch packaging climbs the fastest as logistics efficiency reshapes channel economics.
End User:
Application severity determines sanitary design intensity and regulatory compliance burden.
- Food Industry:Edible oil processors face FDA sanitary design standards and clean-in-place validation requirements. India's SAMR laser-marking mandate pulls integrated vision systems into food-grade bottling corridors. Nitrogen flushing protocols converge with stainless steel construction for oxidation-resistant sealing.
- Chemical Industry:Aggressive lubricant and industrial oil processors specify positive-displacement pumps with mechanical seals. REACH and EU F-Gas Regulation constrain refrigerant choices in climate-controlled filling environments.
- Cosmetic Industry:Facial oils and serum packagers require aseptic filling lines with hygienic design heritage. Extended-shelf-life formats drive dairy-oil copacker retrofit demand across European processing hubs.
- Pharmaceutical Sector:Excipient and API oil filling demands validated containment and batch documentation. Pharmaceutical-grade equipment carries premium positioning against food-industry baseline specifications.
Installed base dominance sits with food industry applications; pharmaceutical sector specification carries steepest expansion trajectory.
Sales Channel:
Customer scale and technical sophistication determine direct versus intermediated procurement patterns.
- Direct Sales:Large edible oil refiners negotiate equipment specification directly with OEM engineering teams. Indian refiners increasingly unbundle hardware from after-sales agreements, sourcing spare parts from component manufacturers.
- Distributors:Regional equipment distributors serve mid-scale packagers requiring local commissioning and field service support. Southeast Asian markets sustain distributor networks for cost-engineered auger and gravity systems.
- Online Sales:E-commerce platforms capture small-batch processor procurement for standardized filling modules. Modular automation kits for vision and nitrogen integration list through industrial equipment marketplaces.
- Retail:Limited applicability for capital equipment; residual channel presence in consumable spare parts and maintenance components.
Transaction value concentrates in direct sales; distributor channels gain share fastest among mid-scale regional packagers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's edible oil refining corridor anchors South Asian equipment procurement as packagers automate bottling lines under evolving traceability mandates.
United States
Midwestern lubricant processors drive positive-displacement pump adoption for aggressive chemical formulations. FDA sanitary design standards dictate stainless steel construction and clean-in-place capability for food-grade applications. Houston's petrochemical corridor concentrates industrial oil filling equipment demand from downstream chemical operations.
Germany
Dairy-oil copackers across Bavaria retrofit lines for extended-shelf-life aseptic formats. REACH chemical constraints and EU F-Gas Regulation push manufacturers toward mechanical sealing alternatives and dry seal designs. Stuttgart's machinery engineering cluster supplies hygienic-design filling equipment to European processing hubs.
India
Edible oil refiners in Gujarat and Maharashtra expand automated bottling capacity under SAMR traceability mandates requiring laser-marked coding. FSSAI food safety standards converge with national packaging regulations to pull integrated vision systems into bottling corridors. The Mumbai-Pune industrial belt concentrates stainless steel piston filler demand for oxidation-resistant sealing protocols.
China
Coastal refining provinces adopt nitrogen flushing modules as packagers upgrade for retail traceability requirements. SAMR national food safety standards mandate traceability coding on all packaged cooking oil, driving laser-marking module integration. The Yangtze River Delta manufacturing cluster produces cost-engineered auger systems for regional edible oil brands.
Southeast Asia
Thai and Vietnamese packagers capture e-commerce channel preference with flexible film pouch formats. Evolving national food safety mandates across ASEAN markets accelerate automated bottling investment. Bangkok's packaging machinery distributors serve mid-scale regional brands with modular automation kits for legacy line retrofit.
Oil Packing Machine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across hygienic design intensity and regulatory compliance depth. The vendor base stratifies between aseptic-system specialists serving dairy-oil copackers and cost-engineered fabricators targeting South Asian pouch operations. Three archetypes dominate: integrated processing-packaging platforms, stainless steel precision fabricators, and flexible-film logistics specialists. Competitive moves concentrate on modular upgrade path development and geographic certification stacking for multi-country footprints.
Within the integrated platform tier, Tetra Laval Group and GEA Group exemplify divergent strategic positions—one anchoring aseptic carton dominance through dairy-oil copacker relationships, the other leveraging hygienic design heritage across European extended-shelf-life retrofits. Among precision fabrication specialists, Nichrome Packaging Solutions occupies a position representing cost-engineered auger system supply for South Asian regional brands. These three companies illustrate how equipment specification increasingly tracks channel strategy rather than product viscosity alone, with each archetype defending margin position through regulatory compliance depth or logistics efficiency optimization.
| Leading Market Players |
|---|
| Niverplast B.V. |
| Turpack Packaging Machinery |
| GEA Group |
| Nichrome Packaging Solutions |
| Gemseal |
| KHS Group |
| SIG Combibloc Group Ltd. |
| Tetra Laval Group |
| Syntegon Technology GmbH |
| Others |
Value Network & Pricing Analysis
Captive in-house production of Grade 316L stainless steel components anchors supply positions for European and Indian fabricators while insulating premium-tier OEMs from commodity sheet volatility. This vertical integration choice concentrates pricing power with hygienic-design specialists serving dairy-oil copackers, while cost-engineered fabricators compete on modular upgrade paths without captive metallurgy.
Pricing Analysis
Throughput-based value anchoring dominates equipment procurement as edible oil refiners calculate total cost of ownership across fill accuracy, uptime guarantees, and nitrogen integration. Three-tier pricing structure across premium, standard, and economy levels separates aseptic-system specialists from regional auger fabricators and unbundled automation kit suppliers. Cost compression in mid-scale piston architectures intensifies as Indian packagers procure hardware without bundled after-sales agreements. Price sensitivity concentrates among South Asian regional brands specifying retrofit kits; least sensitivity sits with European dairy-oil copackers prioritizing hygienic design heritage.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale refiner demand from Gujarat and Maharashtra while distributor networks serve Southeast Asian mid-scale packagers through Bangkok-based machinery traders. Component sourcing concentrates in Germany, China, and India for precision pumps, laser-marking modules, and stainless steel fabrication. Supply chain risk hinges on single-source vulnerability for Grade 316L sheet from European mills facing energy cost volatility. Distribution runs through integrated processing-packaging platforms for aseptic carton formats and standalone precision fabricators for piston architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cost-of-compliance story centers on REACH chemical constraints and EU F-Gas Regulation phase-downs, which erect eight-to-fourteen-month qualification barriers that filter out undercapitalized entrants lacking mechanical redesign capabilities.
For Market Incumbents: Hedge stainless steel input exposure through long-term offtake agreements with Grade 316L mills rather than spot-market exposure. Accelerate mechanical seal R&D to preempt REACH-driven redesign cycles. Capacity addition in India's Mumbai-Pune belt captures SAMR-mandated automation demand before regional fabricators consolidate retrofit expertise. For New Entrants and Emerging Players: The premium-to-economy price-point gap in aseptic carton equipment creates white space for flexible-film logistics specialists targeting Southeast Asian e-commerce channels. Mid-scale pouch operations in Thailand and Vietnam represent the most penetrable segment. Go-to-market angle: modular nitrogen-flushing retrofits compatible with legacy gravity lines. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated processing-packaging platforms seeking hygienic design depth. Long-term viability favors OEMs with certification stacking capabilities across FDA, REACH, and SAMR requirements. Signal to watch: unbundling of hardware and after-sales agreements among Indian refiners, which may compress service revenue multiples for pure-play fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Component Production | Captive Grade 316L supply insulates margin pools from European energy-driven sheet volatility. |
| Mechanical Seal R&D Investment | REACH-compliant dry seal designs preempt ECHA-mandated redesign cycles for climate-controlled filling. |
| Modular Automation Kit Development | Vision and nitrogen modules capture Indian mid-scale retrofit demand under SAMR traceability mandates. |
| ASEAN Distributor Network Expansion | Bangkok-based channels access Thai and Vietnamese packagers adopting flexible film for e-commerce logistics. |
| Multi-Country Certification Stacking | Simultaneous FDA, REACH, and SAMR compliance defends premium positioning in cross-border production footprints. |
Research Methodology
Trade association filings, customs export records, and equipment registration databases formed the secondary backbone for market sizing and competitive positioning. Primary interviews with plant engineers at edible oil refiners, procurement leads at dairy-oil copackers, aftermarket service heads at distributor networks, and regulatory affairs specialists at OEMs validated technical specifications and compliance burden estimates. Bottom-up and top-down triangulation cross-checked unit shipment data against capital expenditure disclosures.
Bottom-up modeling tracked individual line installations across piston, pump, and auger architectures while top-down analysis calibrated against regional food processing investment flows. Segmentation dimensions spanned filling technology type, packaging format, end-use industry severity, and channel procurement pattern. CAGRs were derived from regression analysis of historical automation adoption curves against regulatory mandate timelines. Forecast inputs included SAMR traceability implementation pace and EU F-Gas refrigerant phase-down schedules.
Inputs from OEM technical documentation and national food safety regulator filings were available through the study window; gaps in real-time stainless steel pricing data introduce uncertainty bands around margin compression estimates. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and retrofit versus replacement preference shifts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Granule Filling Machine Market
Packaging Machinery
Plastic Vacuum Forming Machinery Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Lidding Machines Market
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Global Food and Beverage Packaging Machinery Market
Packaging Machinery
Global Blow Fill Seal Equipment Market
Packaging Machinery
Cup Filling Machine Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
Pouch Packaging Machine Market
Packaging Machinery
Tea Packing Machine Market
Packaging Machinery
Food Powder Packaging Machine Market