
 Side Load Case Packing Machines Market | 2026-2036
Side Load Case Packing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Side Load Case Packing Machines Market Analytics
The EU Machinery Directive is rebalancing the cost-of-entry calculus for side load case packing equipment sold into European manufacturing operations. Bosch Packaging Technology leverages its vertical integration into control systems to sustain premium positioning across pharmaceutical and dairy installations. Douglas Machine Inc. anchors its competitive stance through specialized expertise in washdown-rated machinery for food processing environments. Massman Automation Designs competes on engineering flexibility, offering customized lane configurations that navigate the tighter safety and interoperability standards now mandated across multiple jurisdictions.
Side load case packing machines are automated or semi-automated systems engineered to erect, load, and seal corrugated cases from the side orientation, typically operating at speeds from 10 to 70 cases per minute with servo-driven or mechanical indexing mechanisms. These systems serve primary industrial functions in secondary packaging operations where product collation, case formation, and sealed discharge must integrate with upstream filling and downstream palletizing lines. Automatic configurations lead installed base volume due to labor cost pressures and throughput requirements in high-volume beverage bottling, while robotic variants represent the fastest-growing technology segment as articulated arm and delta robot architectures displace fixed mechanical lanes in changeover-intensive operations. Hybrid technology installations, combining pneumatic actuation with electrical servo control, concentrate margin pools where end users demand energy efficiency without sacrificing the force characteristics of compressed air for heavy-gauge case handling.
FDA cGMP standards govern pharmaceutical installations in the United States, requiring validated cleaning protocols and material traceability that elevate equipment specification complexity. The EU Machinery Directive, enforced through notified bodies in Germany and other member states, mandates risk assessment documentation and CE conformity that shapes product development cycles for equipment builders targeting European sales. China's GB standards and SAMR oversight impose additional certification layers for imported machinery. Stakeholders must monitor how divergent safety and data integrity requirements across these jurisdictions influence platform standardization strategies and regional sourcing decisions.
Market Dynamics
The servo-electric conversion of indexing mechanisms is compressing mechanical component demand while elevating control system specification complexity across beverage and pharmaceutical packaging lines. Equipment builders must now source precision motion controllers and safety-rated PLCs from a consolidating supplier base, reshaping procurement leverage and platform architecture decisions.
Growth Catalysts
- EU Machinery Directive CE conformity:Mandatory risk assessment documentation for European sales is filtering out low-capability regional assemblers and consolidating specification authority with tier-one equipment builders.
- Pharmaceutical serialization mandates:Track-and-trace requirements under FDA cGMP and EU FMD are forcing secondary packaging line upgrades that integrate case-level aggregation with upstream bottle coding systems.
- Robotic delta architectures:Articulated arm and parallel kinematic designs are capturing changeover-intensive dairy and personal care operations where format flexibility outweighs pure speed metrics.
Market Restraints
- Servo motor supply concentration:Precision motion components concentrate among Japanese and German suppliers, exposing lead time vulnerability for equipment builders without captive inventory or alternative sourcing.
- Stainless steel alloy volatility:Grade 304 and 316L price swings directly compress margin on washdown-rated machinery specified for meat, poultry, and ready-to-eat food environments.
- Pneumatic system retrofit inertia:Compressed air infrastructure investments at legacy plants create switching costs that slow full electrification despite energy efficiency advantages of servo-driven alternatives.
Strategic Opportunities
- India food processing expansion:FSSAI enforcement of packaged food safety standards and PLI scheme incentives for cold chain infrastructure are creating first-mover advantage for case packing equipment with validated sanitary design.
- Modular lane reconfiguration:Standardized mechanical subassemblies that reconfigure without tooling changes address contract packager demand for same-day format switches between SKU batches.
- China dual carbon alignment:NMPA and MIIT energy efficiency benchmarks for manufacturing equipment are advantaging servo-electric designs with regenerative power recovery over traditional pneumatic indexing.
Industry Challenges
- Functional safety engineering scarcity:ISO 13849 and IEC 62061 compliance documentation requires specialized talent pools that equipment builders compete for against automotive and semiconductor automation sectors.
- Legacy control architecture integration:Proprietary fieldbus protocols from 1990s-era packaging lines create interoperability friction with modern Ethernet/IP and OPC-UA connectivity standards.
- Validation protocol execution:FDA cGMP IQ/OQ/PQ documentation for pharmaceutical installations extends project timelines and strains commissioning resource availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Side Load Case Packing Machines Market |
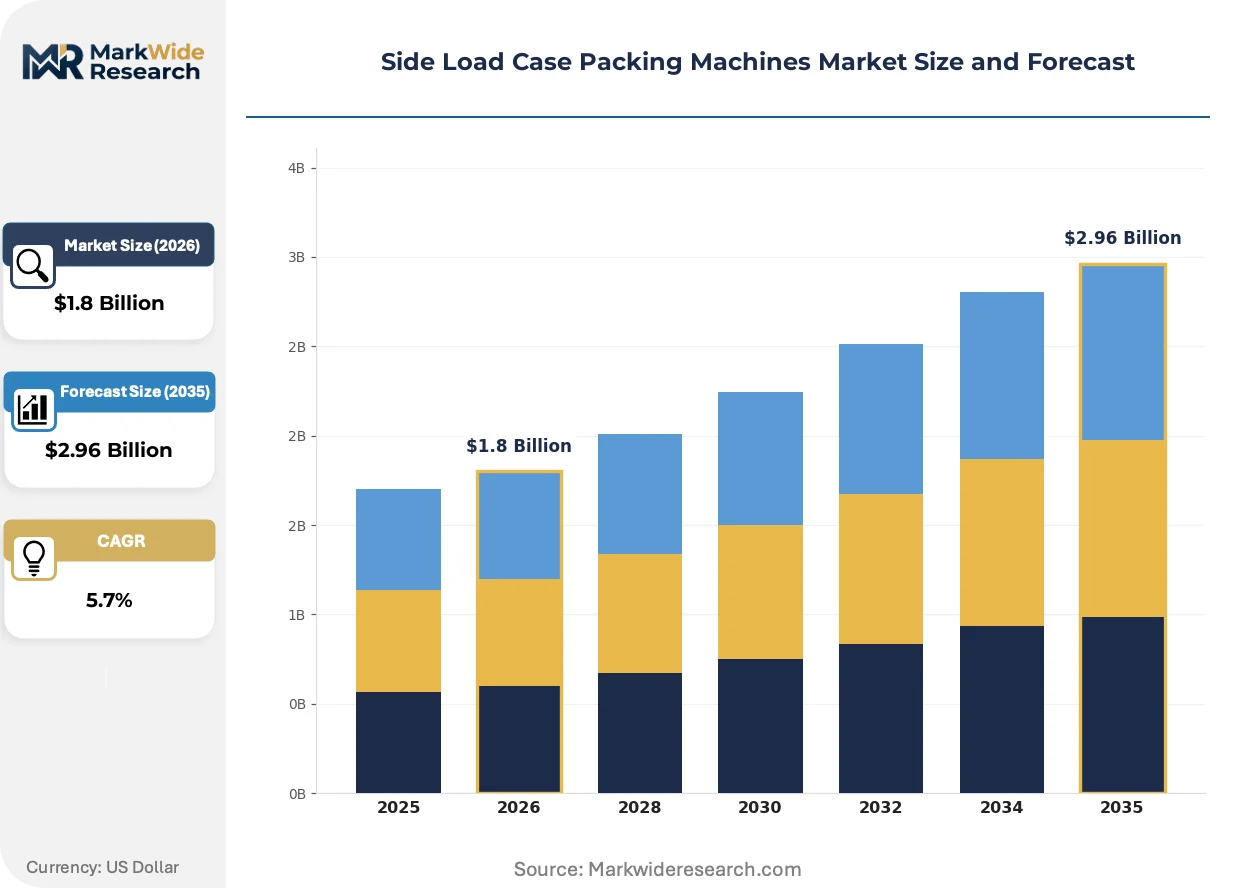
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Robotic Technology: Mechanical, Pneumatic, Electrical, Hybrid End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Installation Type: Standalone, Integrated, Mobile, Modular |
| Companies Covered | Bosch Packaging Technology, Douglas Machine Inc., Massman Automation Designs, ADCO Manufacturing, Schneider Packaging Equipment Company, Cama Group, Tetra Pak International S.A., IMA Group, Krones AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Side Load Case Packing Machines Market Evolving Landscape
Digital twin simulation of case packing lines is compressing commissioning risk and enabling virtual format changeover validation before physical installation. Equipment builders and end users alike are deploying these tools to reduce startup downtime and accelerate regulatory documentation.
Collaborative robot loading stations are decentralizing fixed mechanical lane architectures in mid-speed operations. Contract packagers in cosmetics and nutraceuticals are adopting these configurations to absorb SKU proliferation without dedicated changeover tooling. The technology is decentralizing capital allocation from centralized high-speed lines toward distributed, reconfigurable cells that adapt to demand volatility.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-dependent cooling system redesigns in dairy and beverage packaging environments. Cold chain integrity requirements now specify low-global-warming-potential alternatives that demand revised heat exchanger and compressor specifications. European dairy cooperatives and German brewing operations are front-running compliance through 2025 equipment procurement cycles to avoid retrofit liability.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-tier beverage bottlers. Third-party financing vehicles now bundle machinery, maintenance, and format changeover support into per-case throughput charges. This shift concentrates most visibly in United States regional craft brewing and private-label water operations where balance sheet constraints favor operating expense treatment.
Side Load Case Packing Machines Market Segmentation
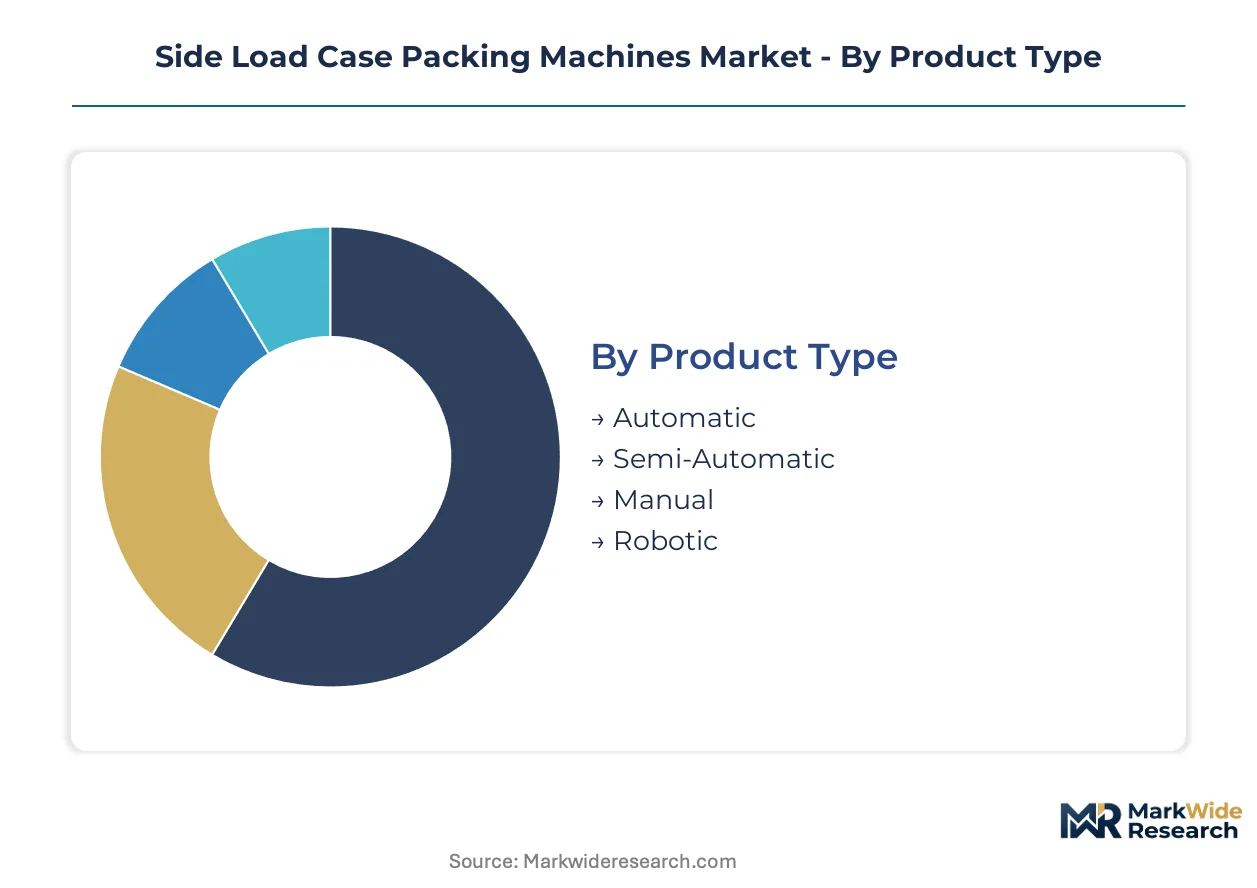
Side load case packing machines serve divergent operational requirements across packaging environments, from high-volume beverage bottling to validated pharmaceutical cleanrooms. Segmentation reveals how specification complexity, regulatory burden, and throughput demands fragment procurement patterns across end-use categories.
Product Type:
CE conformity documentation under the EU Machinery Directive and FDA cGMP validation protocols impose tiered compliance costs across product configurations, filtering supplier participation by certification capability.
- Automatic:Servo-driven indexing mechanisms achieve 50-70 cases per minute in continuous beverage operations. Demand concentrates in Germany and United States bottling facilities where labor cost pressures justify capital intensity and 24/7 uptime requirements.
- Robotic:Articulated arm and delta kinematic architectures enable sub-10-minute changeovers between SKU formats. Personal care contract packagers in cosmetics and nutraceuticals adopt these systems to absorb product proliferation without dedicated tooling investments.
- Semi-Automatic:Operator-assisted loading stations bridge throughput gaps for mid-tier food processors with intermittent production schedules.
- Manual:Basic case erecting and sealing units serve micro-breweries and artisanal food producers with batch volumes below automated break-even thresholds.
Leading the category by volume: Automatic. Growing fastest: Robotic.
Technology:
Energy efficiency benchmarks from China's MIIT and regenerative power recovery specifications are rebalancing technology selection criteria for equipment procurement teams.
- Electrical:Precision servo motors with regenerative drives deliver positioning accuracy within ±0.5mm for pharmaceutical aggregation lines. NMPA energy efficiency certifications favor these configurations in Chinese dairy and beverage installations seeking dual carbon alignment.
- Hybrid:Combined pneumatic actuation with electrical servo control preserves force characteristics for heavy-gauge corrugated handling while reducing compressed air consumption. Meat and poultry processors specify these systems for washdown-rated environments where Grade 316L stainless steel construction meets USDA sanitation requirements.
- Mechanical:Cam-driven indexing mechanisms dominate legacy installed bases in mature beverage markets with established maintenance protocols.
- Pneumatic:Compressed air systems persist in plants with sunk infrastructure investments, though EU F-Gas Regulation phase-downs accelerate displacement in refrigerated dairy packaging.
Highest margin concentration: Hybrid. Steepest expansion trajectory: Electrical.
End User:
Validation protocol intensity and serialization mandate timelines create divergent specification roadmaps across downstream industries.
- Food & Beverage:High-speed secondary packaging lines for bottled water, carbonated soft drinks, and ready-to-eat meals require stainless steel construction and IP65 washdown ratings. FSSAI enforcement in India and PLI scheme incentives are accelerating sanitary design investments in cold chain infrastructure.
- Pharmaceuticals:FDA cGMP and EU FMD track-and-trace mandates demand IQ/OQ/PQ documentation, material traceability, and case-level aggregation with upstream bottle coding. Serialization compliance extends project timelines and elevates control system specification complexity.
- Personal Care:SKU volatility in cosmetics and nutraceuticals drives demand for rapid format changeover without tooling changes.
- Household Products:Detergent and cleaning chemical packaging prioritizes corrosion-resistant materials and chemical compatibility over speed metrics.
Dominant demand source: Food & Beverage. Fastest regulatory-driven upgrade cycle: Pharmaceuticals.
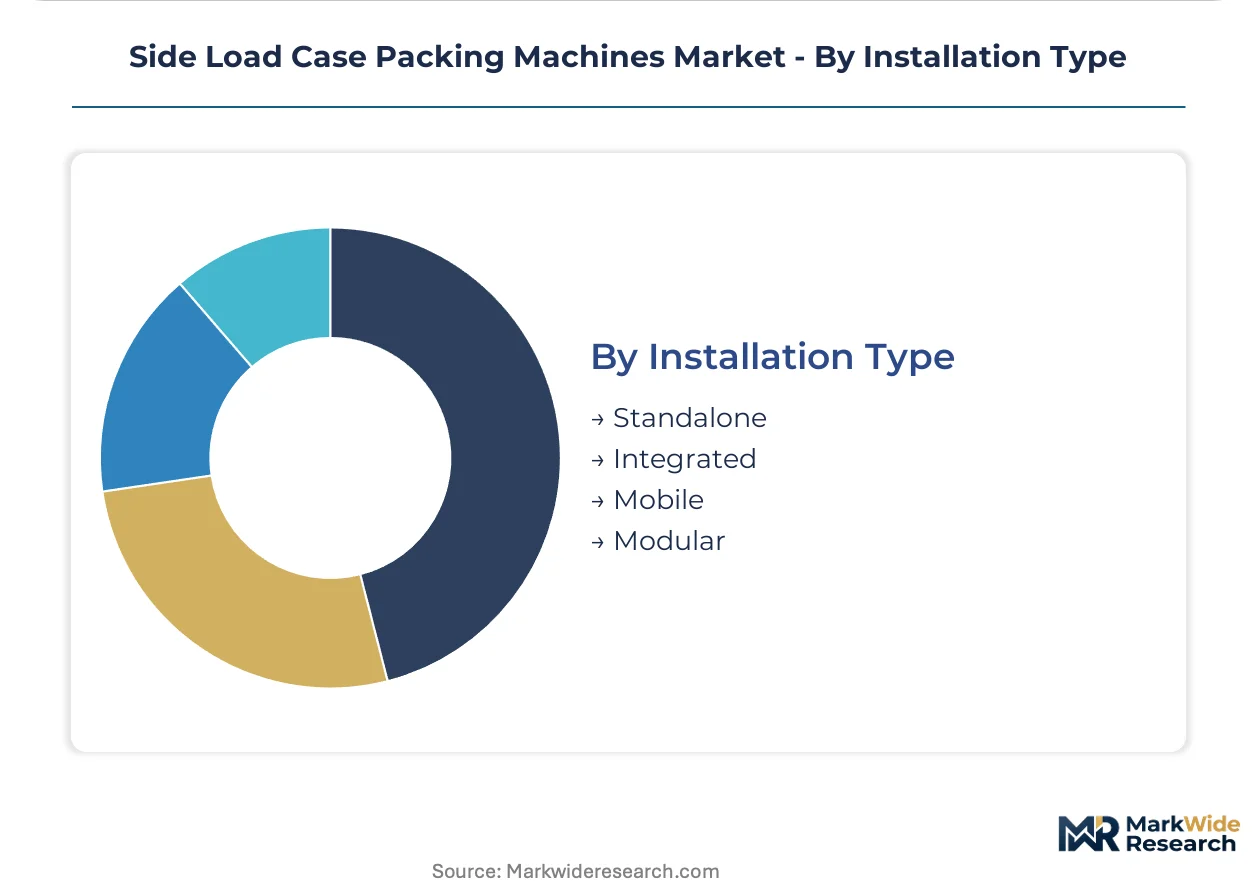
Installation Type:
Capital deployment flexibility and line integration depth segment procurement patterns between greenfield installations and brownfield retrofits.
- Integrated:Direct coupling with upstream filling and downstream palletizing lines maximizes overall equipment effectiveness in large-scale German and United States beverage operations. Proprietary fieldbus protocol migration challenges complicate legacy control architecture integration.
- Modular:Standardized mechanical subassemblies reconfigure without tooling changes, addressing contract packager demand for same-day format switches between SKU batches.
- Standalone:Decoupled units serve regional bottlers and private-label operations with limited line integration requirements.
- Mobile:Castor-mounted configurations enable seasonal production flexibility and temporary capacity augmentation in agricultural processing.
Primary revenue concentration: Integrated. Gaining share fastest: Modular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for side load case packing machines concentrates in Germany, China, and the United States where large-scale bottling and processed food operations sustain capital investment in automated secondary packaging infrastructure.
Germany
Beverage cooperatives and dairy processing clusters in Bavaria and North Rhine-Westphalia drive equipment replacement cycles. The EU Machinery Directive's CE conformity requirements filter supplier participation toward tier-one equipment builders with notified body relationships. The Munich-Stuttgart industrial corridor hosts concentrated pharmaceutical packaging operations requiring validated case-level aggregation systems.
China
NMPA energy efficiency benchmarks and MIIT dual carbon alignment protocols favor servo-electric machine configurations in Yangtze River Delta dairy plants. GB standards and SAMR oversight impose certification layers that advantage domestic equipment fabricators with established regulatory relationships. Shanghai and Suzhou manufacturing zones concentrate beverage bottling capacity requiring high-speed secondary packaging lines.
United States
FDA cGMP validation protocols and pharmaceutical serialization mandates force secondary packaging line upgrades integrating case-level aggregation. Wisconsin and California food processing belts sustain demand for washdown-rated stainless steel machinery. Regional craft brewing operations in Colorado and Pacific Northwest states are adopting equipment-as-a-service contracting models.
India
FSSAI enforcement of packaged food safety standards and PLI scheme incentives for cold chain infrastructure create first-mover opportunities for sanitary design equipment. Maharashtra and Gujarat food processing corridors are expanding automated packaging capacity to serve domestic retail and export markets. Mumbai-Pune industrial clusters concentrate contract packaging operations requiring rapid format changeover capabilities.
Japan
METI energy efficiency guidelines and aging workforce demographics accelerate robotic case packing adoption in Kanto region beverage operations. JIS standards compliance shapes procurement specifications for pharmaceutical and personal care packaging lines. Osaka-Kyoto industrial zones maintain precision equipment demand for cosmetics and nutraceutical contract manufacturing.
Side Load Case Packing Machines Market Competitive Landscape
German producers anchor one tier; United States specialists hold differentiated positions in washdown-rated and pharmaceutical-validated segments. The vendor base stratifies across three capability tiers: multinational packaging system integrators with captive control technology, mid-scale regional fabricators with modular engineering flexibility, and niche specialists in sanitary or validated equipment categories. Dominant competitive moves include backward integration into precision motion control supply and geographic expansion through local assembly partnerships in Asian growth markets.
Within the multinational system integrator tier, Bosch Packaging Technology and Krones AG exemplify scale-driven positions anchored by vertical control over upstream automation components. Douglas Machine Inc. occupies a specialist position representing the washdown-rated machinery archetype for food processing environments. Cama Group and IMA Group sit within the European mid-tier fabricator segment where engineering flexibility and regional regulatory relationships sustain competitive differentiation.
| Leading Market Players |
|---|
| Bosch Packaging Technology |
| Douglas Machine Inc. |
| Massman Automation Designs |
| ADCO Manufacturing |
| Schneider Packaging Equipment Company |
| Cama Group |
| Tetra Pak International S.A. |
| IMA Group |
| Krones AG |
| Others |
Value Network & Pricing Analysis
Grade 304 and 316L stainless steel price volatility cascades through equipment cost structures, compressing margins on washdown-rated machinery while forcing tier-one builders to absorb input swings through captive sourcing arrangements that tier-two fabricators cannot match.
Pricing Analysis
High-volume automatic configurations command premium positioning against robotic and semi-automatic alternatives. Three-tier pricing structure across premium, standard, and economy levels separates CE-validated pharmaceutical systems from food-grade washdown units and basic mechanical indexing equipment. Cost compression in mid-tier configurations is intensifying because Japanese and German servo motor supply concentration exposes equipment builders without alternative sourcing to margin pressure. Contract packagers in cosmetics and nutraceuticals exhibit highest price sensitivity due to SKU volatility and capital constraints, while pharmaceutical manufacturers prioritize validation capability over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale beverage bottler demand in Germany and the United States, while regional fabricators in China and India serve mid-tier food processors through distributor networks. Precision motion controllers and safety-rated PLCs concentrate supply among Japanese and German component houses, exposing lead time vulnerability for equipment builders without captive inventory. Distribution runs through machinery dealers with local service capabilities in emerging markets, though tier-one builders increasingly bypass intermediaries for large-scale integrated installations. Single-source vulnerability in servo motor supply chains represents the dominant structural risk, compounded by stainless steel alloy price volatility that feeds directly into equipment pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into precision motion control supply has become the defining competitive race, with tier-one builders capturing margin pools that tier-two competitors cannot access without equivalent upstream leverage.
For Market Incumbents: Deploy captive control system production to defend against emerging Asian fabricators with government-backed certification support. Consolidate specification authority through notified body relationships in Germany and SAMR alignment in China. Reinforce aftermarket service revenue streams as equipment-as-a-service contracting displaces traditional capital purchases among mid-tier beverage bottlers. For New Entrants and Emerging Players: Begin with modular lane reconfiguration capabilities targeting contract packagers in India's Maharashtra and Gujarat corridors, where FSSAI enforcement creates first-mover advantage for sanitary design equipment. White-space exists in rapid format changeover systems for SKU-volatile personal care operations. Partner with regional distributors possessing local regulatory relationships rather than competing directly for integrated line contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European fabricators with engineering flexibility and established CE conformity documentation, particularly those serving pharmaceutical serialization upgrade cycles. Long-term viability hinges on platform standardization strategies that navigate divergent FDA cGMP and EU Machinery Directive requirements. Monitor NMPA energy efficiency benchmark enforcement as inflection indicator for servo-electric design adoption in Chinese manufacturing zones.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motion Control | Captures margin pools concentrated among Japanese and German component suppliers. |
| CE Conformity Documentation Investment | Filters supplier participation toward tier-one builders with notified body relationships in Germany. |
| Equipment-as-a-Service Contracting | Addresses balance sheet constraints among United States regional craft brewing operations. |
| Modular Lane Reconfiguration Development | Absorbs SKU proliferation without dedicated changeover tooling for contract packagers. |
| Local Assembly Partnerships in Asia | Navigates GB standards and SAMR certification layers for imported machinery in China. |
Research Methodology
Trade association filings, customs records, and SEC 10-K disclosures formed the secondary backbone, supplemented by primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers at equipment builders. Bottom-up and top-down triangulation validated volume estimates across automatic, robotic, semi-automatic, and manual product configurations.
Bottom-up modeling of installed base replacement cycles and greenfield capacity additions across the projection horizon anchored value estimates. Segmentation dimensions included technology type, end-use industry, installation configuration, and regional regulatory cluster. CAGRs derived from equipment shipment data, capital expenditure disclosures by major bottlers, and pharmaceutical serialization mandate timelines. Industry-specific forecast inputs incorporated servo motor supply lead times and stainless steel alloy price indices.
Underlying measurement precision varies by segment; automatic configurations in mature beverage markets carry tighter precision than emerging robotic installations in changeover-intensive operations. Forecasts reflect assumptions regarding regulatory enforcement timelines and commodity price trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Cosmetic Packaging Machinery Market
Packaging Machinery
Form-Fill-Seal Equipment Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Food Packaging Machinery Market
Packaging Machinery
Metal Banding Machine Market
Packaging Machinery
Sleeve Wrapping Machine Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Filling Machinery Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Screw Capping Machines Market
Packaging Machinery
Plastic Blow Molding Machine Market
Packaging Machinery
Tray Forming Machine Market
Packaging Machinery
Blow Fill Seal (BFS) Technology Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Pouch Packaging Machine Market