
 Single Lip Bags Market | 2026-2036
Single Lip Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Single Lip Bags Market Analytics
The divergence between premium and commodity tiers is shifting as food-grade certified single lip bags command wider spreads over standard industrial grades. Amcor plc leverages its global manufacturing footprint to sustain supply security for pharmaceutical and food clients. Mondi Group anchors its position through paper-based and composite material leadership. Dana Poly specializes in custom polyethylene formulations that differentiate its offering for regional industrial packaging accounts.
Single lip bags are flexible pouches featuring one extended sealing edge designed for automated filling lines and manual closure, typically manufactured through blown film extrusion or cast film processes with thicknesses ranging from 1.5 to 6 mil depending on barrier requirements. Gusseted bags occupy the structural high ground in retail and food service applications where expanded volume capacity supports shelf presentation. Barrier bags lead margin pools through multi-layer coextrusion and aluminum lamination that extends product shelf life for pharmaceutical and specialty food end users. Biodegradable bags represent the fastest-growing material trajectory as compostable resin formulations gain production scale.
FDA food contact regulations and EU REACH compliance frameworks govern material migration limits and additive approvals for single lip bags serving food and pharmaceutical channels. The EU Packaging and Packaging Waste Regulation recast tightens extended producer responsibility and recycled content mandates that reshape supplier qualification requirements. California's SB 54 plastics pollution reduction law imposes parallel state-level compliance burdens for manufacturers distributing into the United States. Stakeholders must monitor evolving recyclability labeling standards and chemical disclosure thresholds to preserve market access across jurisdictions.
Market Dynamics
EU Packaging and Packaging Waste Regulation recast is forcing resin suppliers and converters to requalify entire product portfolios for extended producer responsibility compliance, compressing qualification timelines while expanding recycled content mandates across Central European manufacturing corridors.
Growth Catalysts
- EU REACH compliance frameworks:Food-grade certification requirements under ECHA migration limits are pulling pharmaceutical and specialty food buyers toward higher-barrier single lip bag specifications, expanding addressable premium segments.
- Blown film extrusion automation:German and Austrian packaging OEMs are deploying servo-driven sealing systems that cut changeover times, enabling shorter production runs for customized single lip bag dimensions.
- Compostable resin formulations:Industrial buyers in France and Italy are specifying biodegradable single lip bags for organic food distribution, accelerating volume shifts away from conventional polyethylene.
Market Restraints
- LLDPE resin price volatility:Feedstock cost swings tied to naphtha and ethylene supply tightness compress converter margins, particularly for commodity-grade single lip bag producers without long-term supply agreements.
- Aluminum foil supply concentration:High-barrier lamination depends on limited European foil rolling capacity centered in Germany and Greece, creating bottleneck risks for pharmaceutical-grade single lip bag output.
- Mechanical recycling contamination thresholds:EU recyclability labeling standards impose strict limits on multi-layer coextrusion structures, constraining design flexibility for barrier-enhanced single lip bags.
Strategic Opportunities
- Poland and Czech Republic food processing:Underpenetrated Central European markets present white space as regional dairy and meat processors modernize packaging lines for automated single lip bag filling.
- EU Green Deal circular economy incentives:National green procurement mandates and EPR fee reductions for recycled content are creating preferential market access for post-consumer recycled polyethylene single lip bags.
- Digital printing integration:Hybrid flexo-digital presses are converging with on-demand extrusion, enabling lot-specific variable data printing for pharmaceutical serialization compliance without plate costs.
Industry Challenges
- Migration testing laboratory capacity:Bottlenecks at EFSA-notified bodies extend food contact compliance timelines from 8 to 14 weeks, delaying new single lip bag product launches.
- Legacy filling line retrofit complexity:Pharmaceutical and food manufacturers face integration friction when adapting existing form-fill-seal equipment for thinner-gauge biodegradable films with different sealing profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Lip Bags Market |
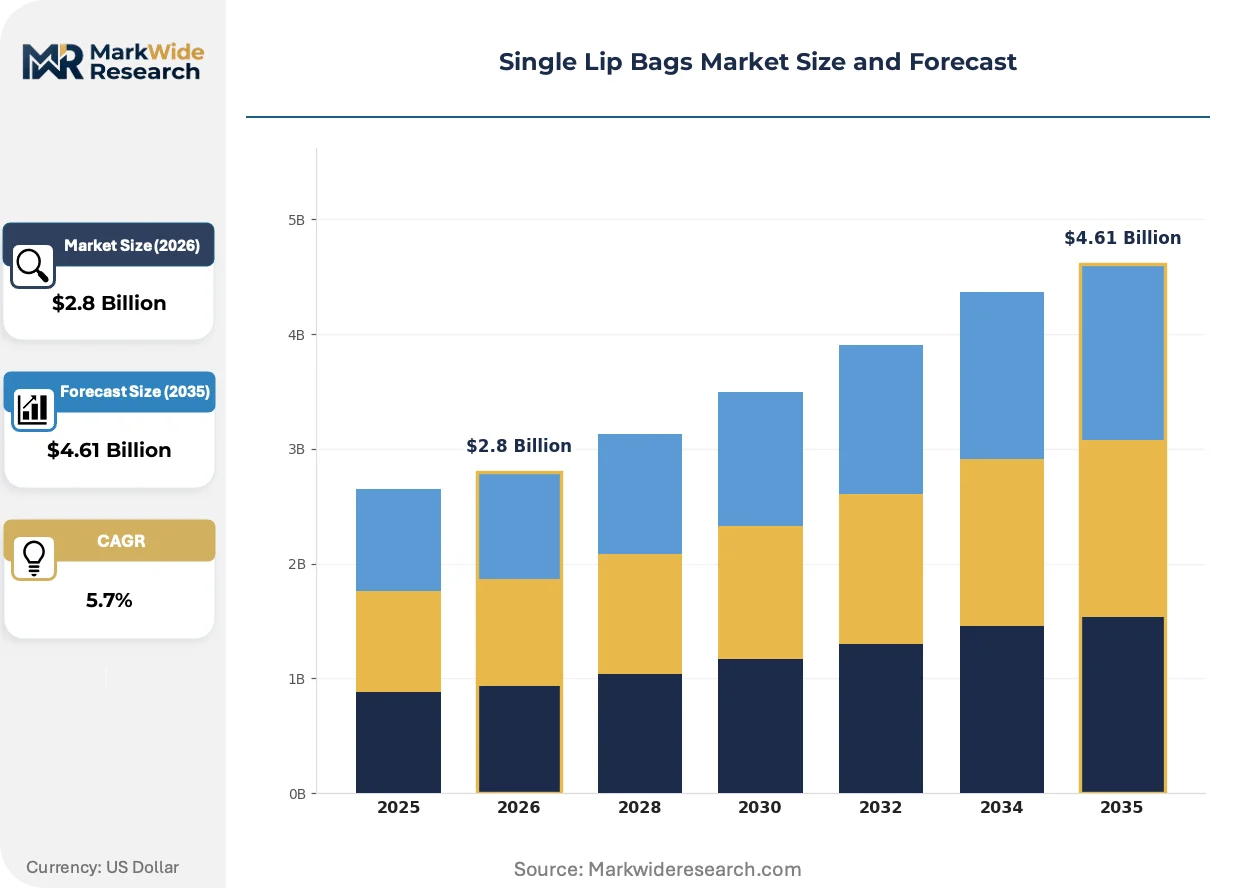
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Barrier Bags, Biodegradable Bags Material: Plastic, Paper, Aluminum, Composites End User: Food Industry, Pharmaceutical Industry, Industrial Packaging, Retail Packaging Closure Type: Zip Lock, Heat Seal, Adhesive Seal, Others |
| Companies Covered | Amcor plc, International Plastics, Emerald Packaging, Rutan Poly Industries, EZ Products, North Coast Plastics, Mondi Group, Ampac Holdings, Dana Poly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Lip Bags Market Evolving Landscape
Active barrier technologies and digital manufacturing integration are compressing development cycles while expanding functional differentiation possibilities for single lip bag converters serving regulated end-uses.
Multi-layer coextrusion with active oxygen scavenging layers is expanding into ready-to-eat meat and pharmaceutical tablet packaging as German and Swiss buyers specify 18-24 month shelf life extensions without preservative additives. The technology enables thinner overall film gauges while maintaining barrier performance, reducing material intensity per unit.
EU Packaging and Packaging Waste Regulation recast tightens extended producer responsibility thresholds and mandates 35% recycled content in plastic packaging by 2030. Industrial buyers are now requiring mass-balance certified recycled polyethylene documentation for single lip bag supply agreements, forcing converters to requalify resin streams and audit supply chains for compliance traceability.
Buyer consolidation among Central European food retail cooperatives is compressing supplier rosters and shifting procurement toward framework agreements with technical specification ownership. Smaller single lip bag converters face exclusion as purchasing shifts to direct mill relationships with extrusion and printing capabilities, particularly visible in German discount retail channel restructuring.
Single Lip Bags Market Segmentation
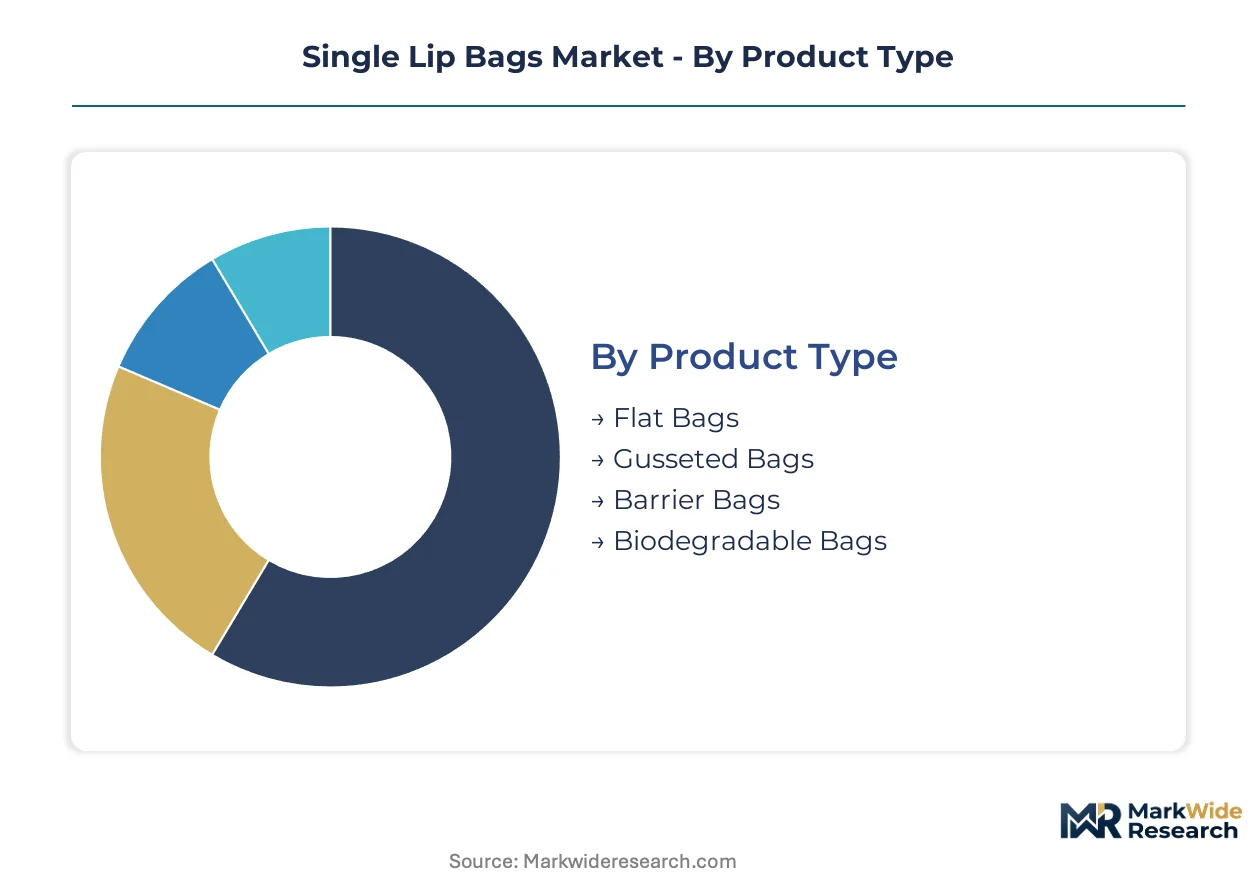
Single lip bag converters configure product portfolios around barrier performance thresholds, automation compatibility, and regulatory compliance tiers that diverge sharply across food, pharmaceutical, and industrial channels. Segmentation choices directly determine margin structure, capital intensity, and vulnerability to EU packaging waste regulation recast obligations.
Product Type:
Buyers differentiate primarily by volume capacity requirements and shelf-life extension needs rather than unit economics alone.
- Flat Bags:Simple two-dimensional construction suits high-speed form-fill-seal lines for dry goods and hardware. German discount retailers specify flat bags for cost-optimized private label distribution where minimal barrier suffices.
- Gusseted Bags:Side or bottom gussets expand cubic capacity for irregular products while maintaining shelf presentation. Central European meat processors deploy gusseted single lip bags for portion-controlled fresh protein packs where vertical display matters.
- Barrier Bags:Multi-layer coextrusion with aluminum lamination or EVOH cores delivers oxygen and moisture barriers for pharmaceutical tablets and specialty foods. Swiss and German buyers mandate 18-24 month shelf life specifications without preservative additives.
- Biodegradable Bags:Compostable resin formulations from PLA, PBAT, or starch blends serve organic food distribution in France and Italy where national green procurement preferences apply.
Flat bags lead volumes today; biodegradable bags are gaining share fastest.
Material:
Material selection locks in compliance pathway and recycling destiny under EU extended producer responsibility frameworks.
- Plastic:LLDPE and LDPE dominate through blown film extrusion with thicknesses from 1.5 to 6 mil. Recycled content mandates under EU Packaging and Packaging Waste Regulation recast are forcing mass-balance certification requirements for polyethylene streams.
- Paper:Kraft and glassine grades serve dry food and pharmaceutical insert applications where fiber-based disposal appeals. Mondi Group anchors European supply through integrated pulp-to-bag operations.
- Aluminum:Foil lamination provides near-zero oxygen transmission for high-barrier pharmaceutical and specialty food pouches. Rolling capacity concentrates in Germany and Greece, creating supply bottlenecks.
- Composites:Paper-plastic or paper-aluminum hybrids balance barrier performance with fiber content for recyclability claims. Design complexity rises as EU recyclability labeling standards tighten.
Plastic retains volume dominance; composites show the steepest expansion trajectory.
End User:
End-use channel determines regulatory burden intensity and technical specification ownership structure.
- Food Industry:Dairy, meat, and bakery processors in Germany, Poland, and the Czech Republic drive automated filling line demand. EFSA migration limits and HACCP compliance frame material qualification timelines.
- Pharmaceutical Industry:Tablet and medical device packaging demands EMA-compliant barrier performance with serialization-ready print surfaces. German and Swiss buyers specify oxygen scavenging layers for 24-month stability.
- Industrial Packaging:Chemical, automotive, and electronics manufacturers use commodity-grade polyethylene for parts protection and batch containment. Price sensitivity limits specification complexity.
- Retail Packaging:Private label and branded consumer goods require shelf-ready graphics and reclosure features. Central European retail cooperative consolidation is compressing supplier rosters.
Food industry channels anchor current volumes; pharmaceutical specifications command the widest margin spreads.
Closure Type:
Closure mechanism selection balances re-use convenience against line speed and seal integrity requirements.
- Zip Lock:Interlocking plastic tracks enable repeated opening for refrigerated foods and pharmaceutical compliance samples. French organic distributors specify zip lock biodegradable bags for consumer convenience.
- Heat Seal:Thermal fusion creates hermetic seals for vacuum and modified atmosphere packaging. German meat processors favor heat seal single lip bags for extended shelf life without preservatives.
- Adhesive Seal:Pressure-sensitive strips suit single-use medical and diagnostic kit packaging where reclosure is unnecessary. Austrian laboratory suppliers specify adhesive seal for sterile field compatibility.
- Others:Tin ties, hook-and-loop, and slider mechanisms serve niche bakery and specialty retail applications where differentiation commands premium positioning.
Heat seal dominates production volumes; zip lock configurations show the strongest growth momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's food processing corridor generates denser single lip bag demand than France's organic distribution networks, though both markets face identical EU Packaging and Packaging Waste Regulation compliance deadlines.
Germany
Dairy and meat processors in Lower Saxony and Bavaria drive automated filling line upgrades for portion-controlled packaging. EFSA migration limits under EU REACH frameworks govern material qualification timelines for food-grade specifications. The Rhine-Ruhr manufacturing belt concentrates blown film extrusion capacity serving Central European retail cooperatives.
France
Organic food distributors specify biodegradable single lip bags for national green procurement compliance. ANSM oversees pharmaceutical packaging material approvals for barrier-enhanced specifications. The Lyon-Auvergne-Rhône-Alpes corridor hosts compostable resin formulation scale-up for PLA and PBAT blends.
Poland
Regional dairy processors modernize packaging lines for automated single lip bag filling as retail channel standards tighten. EU Green Deal circular economy incentives reduce extended producer responsibility fees for recycled content. The Łódź industrial zone attracts extrusion investment from German converters seeking cost-optimized production.
Switzerland
Swissmedic regulates pharmaceutical-grade barrier specifications demanding 24-month shelf life without preservative additives. Specialty food buyers mandate oxygen scavenging layers for premium product positioning. The Basel pharmaceutical cluster sources high-barrier lamination from adjacent German foil rolling capacity.
Italy
National organic certification programs accelerate biodegradable single lip bag adoption for fresh produce distribution. ECHA compliance frameworks restrict additive approvals for food contact applications. The Emilia-Romagna food processing belt integrates compostable packaging for export-oriented cured meat producers.
Single Lip Bags Market Competitive Landscape
Top-tier vendors anchor premium barrier and pharmaceutical-grade segments, while mid-scale converters populate commodity polyethylene tiers. The market structure stratifies across three archetypes: integrated multinational packaging groups, regional blown film specialists, and niche biodegradable material innovators. Consolidation pressure intensifies as retail buyer frameworks favor direct mill relationships. Competitive moves center on recycled content qualification and extrusion-printing integration.
Within the integrated multinational tier, Amcor plc and Mondi Group exemplify scale-driven positions spanning material science and geographic coverage. Dana Poly occupies a specialist archetype focused on custom polyethylene formulations for regional industrial accounts. These three entities represent contrasting strategic postures: global supply security, paper-based and composite material leadership, and formulation differentiation respectively.
| Leading Market Players |
|---|
| Amcor plc |
| International Plastics |
| Emerald Packaging |
| Rutan Poly Industries |
| EZ Products |
| North Coast Plastics |
| Mondi Group |
| Ampac Holdings |
| Dana Poly |
| Others |
Value Network & Pricing Analysis
Backward integration into resin compounding anchors both supply security and margin control for single lip bag converters serving EU food and pharmaceutical channels. German and Austrian extrusion specialists with captive polyethylene formulation capabilities command wider pricing bands than toll-dependent competitors, particularly as EU Packaging and Packaging Waste Regulation recast tightens recycled content traceability requirements.
Pricing Analysis
Capacity additions in Poland and the Czech Republic are reshaping price floors for commodity-grade polyethylene single lip bags. Three-tier pricing structure across food-grade certified, industrial standard, and economy tiers separates converters by migration testing documentation and barrier performance specifications. Pricing pressure stems from LLDPE resin volatility tied to naphtha feedstock swings, compressing margins for toll extruders without long-term supply agreements. Industrial packaging buyers exhibit highest price sensitivity, while pharmaceutical and organic food channels absorb premiums for EMA-compliant and biodegradable specifications.
Supply Chain Analysis
Dual-sourcing mandates from Central European retail cooperatives force converters to qualify secondary extrusion partners for supply continuity. Raw material flows concentrate in Germany, Poland, and the Netherlands for LLDPE resin, with aluminum foil lamination dependent on rolling capacity in Germany and Greece. Supply chain risk centers on single-source vulnerability for high-barrier pharmaceutical grades where EVOH and foil specifications limit qualified suppliers. Distribution runs through direct mill relationships with automated filling line OEMs, bypassing traditional distribution layers as buyer consolidation accelerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The single lip bags market functions as a stable compounder anchored by regulatory-driven packaging refresh cycles across EU food and pharmaceutical sectors. Extended producer responsibility mandates and recycled content thresholds create predictable demand for compliant material specifications.
For Market Incumbents: Extend barrier technology leadership through active oxygen scavenging layer investments that pharmaceutical buyers in Germany and Switzerland specify for 24-month shelf life requirements. Secure mass-balance certification for recycled polyethylene streams ahead of EU Packaging and Packaging Waste Regulation enforcement timelines. Capacity expansion in Poland and the Czech Republic captures cost-advantaged production for Central European food processing modernization. For New Entrants and Emerging Players: Begin with biodegradable single lip bag production for French and Italian organic food distributors where national green procurement preferences create protected demand pockets. Target underpenetrated Polish and Czech dairy processors upgrading to automated filling lines as retail channel standards tighten. Lead with compostable resin formulation partnerships rather than commodity polyethylene toll extrusion to avoid direct price competition with integrated multinationals. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale blown film specialists because EU extended producer responsibility fees and compliance complexity favor scaled converters with in-house testing and certification capabilities. Focus acquisition screening on German and Austrian extruders with servo-driven sealing automation and pharmaceutical-grade cleanroom capacity. Watch migration testing laboratory queue lengths at EFSA-notified bodies as an inflection signal for product launch delays that compress valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Qualification | Mass-balance certification unlocks preferential EPR fee structures under EU Packaging and Packaging Waste Regulation recast. |
| Active Barrier Technology Investment | Oxygen scavenging layers command 18-24 month pharmaceutical shelf life specifications from Swissmedic-regulated buyers. |
| Compostable Resin Scale-Up | PLA and PBAT formulation partnerships capture French and Italian organic food distribution mandates. |
| Digital Printing Integration | Hybrid flexo-digital presses enable lot-specific pharmaceutical serialization without plate changeover costs. |
| Central European Capacity Expansion | Polish and Czech extrusion investment serves underpenetrated dairy and meat processing modernization demand. |
Research Methodology
Multiple input streams — extrusion equipment OEM technical specifications, EU regulatory filing databases, and Central European food processor procurement records — were reconciled to build demand and supply estimates. Primary interviews with blown film plant managers, pharmaceutical packaging engineers, and retail cooperative category buyers were cross-validated against secondary sources including ECHA substance registrations, EFSA food contact opinions, and customs trade flow data. Bottom-up unit economics and top-down sectoral demand triangulation anchored volume and value projections.
Historical capacity utilization patterns were cross-referenced against panel input from resin suppliers and converter engineering teams to build the analytical framework. Segmentation modeling spanned product type, material grade, end-use channel, and closure mechanism across the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points, with specific inputs including EPR fee schedule implementations and pharmaceutical serialization compliance deadlines.
Several conditions sit outside the modeled scope, including abrupt LLDPE resin price spikes beyond historical volatility bands and unilateral national packaging bans ahead of EU harmonized timelines. Forecasts reflect assumptions about laboratory testing capacity expansion and compostable resin production scale-up that may lag projected timelines. Deviation in EU Packaging and Packaging Waste Regulation enforcement intensity or recycled content threshold adjustments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bag Clips Market
Bags and Containers
Lawn and Leaf Bags Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Zipper Bags Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
Textile Bags Market
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Global Household Food Storage Containers Market
Bags and Containers
Anti-Static Collapsible Tote Bins Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Freezer Bags Market
Bags and Containers
Trash Bags Market
Bags and Containers
Global Polypropylene Woven Bags and Sacks Market
Bags and Containers
Plastic Bags and Sacks Market
Bags and Containers
Bag-On-Valve Laminates Market