
 Kraft Paper Machines Market | 2026-2036
Kraft Paper Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Kraft Paper Machines Market Insights
The EU Packaging and Packaging Waste Regulation is repositioning capital allocation across European kraft paper machine fleets, compelling producers to retrofit for higher recycled fiber throughput. Valmet leverages its automation-integrated rebuild portfolio to capture this upgrade cycle, while Voith Group sustains dominance in high-speed wet-end configurations through proprietary shoe press technology. Andritz AG competes aggressively on energy recovery systems that cut drying section steam demand.
Kraft paper machines form engineered pulp-handling systems that convert wood fibers into unbleached, high-strength paper webs through continuous Fourdrinier or gap-forming processes, typically operating at basis weights between 80 and 350 grams per square meter for corrugated medium and linerboard applications. Wet machines retain the largest installed base but face margin compression as recycled paper machines capture the fastest growth trajectory driven by post-consumer fiber availability mandates. Digital technology segments remain nascent in this equipment category, though mechanical forming configurations still anchor the majority of revenue pools across emerging Asian installations.
EPA effluent guidelines in the United States and REACH chemical restrictions in Europe jointly constrain machine chemistry choices, while China's MEE enforces stricter wastewater discharge limits on pulp and paper clusters. India's BIS certification requirements for imported paper machinery create non-tariff barriers that favor local assembly partnerships. Stakeholders must monitor how divergent recycling contamination standards across these jurisdictions reshape machine specification sheets and aftermarket service contracts.
Market Dynamics
Capital allocation across kraft paper machine fleets is pivoting toward recycled fiber compatibility as the EU Packaging and Packaging Waste Regulation tightens post-consumer content mandates, compelling retrofits that can process higher furnish ratios without sacrificing line speeds.
Growth Catalysts
- E-commerce fulfillment automation:Asia-Pacific distribution centers are accelerating orders for high-speed kraft paper machines to replace plastic void fill in automated packaging lines.
- REACH chemical restrictions:European converters face binding limits on certain process chemicals, creating demand for machines with closed-loop chemistry management systems.
- India's single-use plastic ban:The central government's prohibition has triggered domestic kraft linerboard capacity additions requiring new machine installations.
Market Restraints
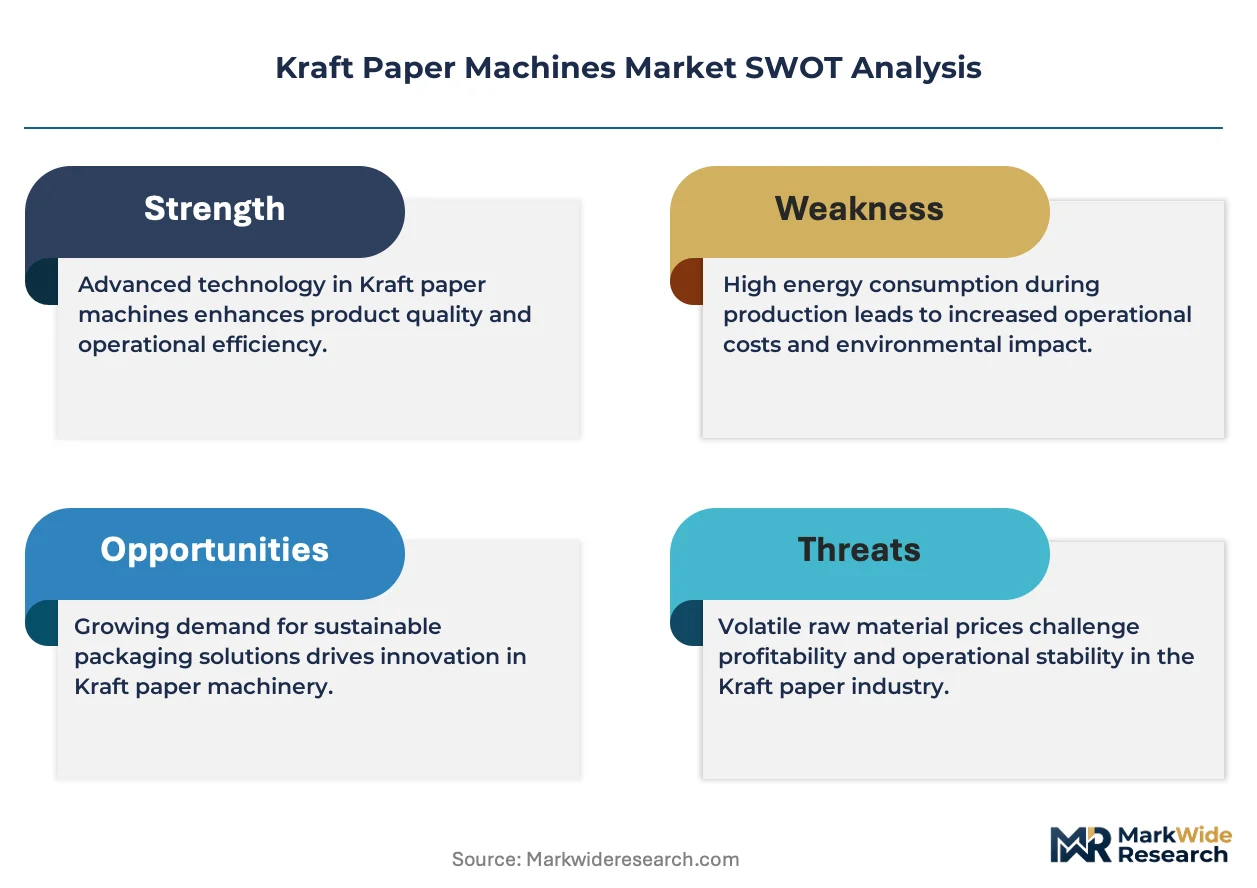
- Recovered fiber price volatility:Old corrugated container availability fluctuates with retail shipping cycles, compressing margins for machines optimized around consistent virgin furnish.
- European supplier concentration:Wet-end component fabrication clusters in Germany and Finland create vulnerability to regional energy cost spikes.
- Shoe press retrofit complexity:Legacy Fourdrinier machines require extensive foundation work to accommodate modern pressing configurations, extending downtime windows.
Strategic Opportunities
- Vietnam packaging corridor:Underpenetrated converting capacity near Ho Chi Minh City offers first-mover positioning for machines serving ASEAN export manufacturing.
- Digital twin integration:Convergence of IoT sensors with predictive maintenance platforms enables remote optimization of forming section consistency.
- EU Green Deal capital subsidies:Member state recovery funds earmark co-financing for energy-efficient drying section upgrades.
Industry Challenges
- Control systems integration:Legacy DCS architectures from the 1990s resist seamless connection to modern quality measurement frameworks.
- Specialized technician scarcity:Wet-end optimization expertise concentrates among retiring European mill engineers, complicating knowledge transfer to emerging market installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kraft Paper Machines Market |
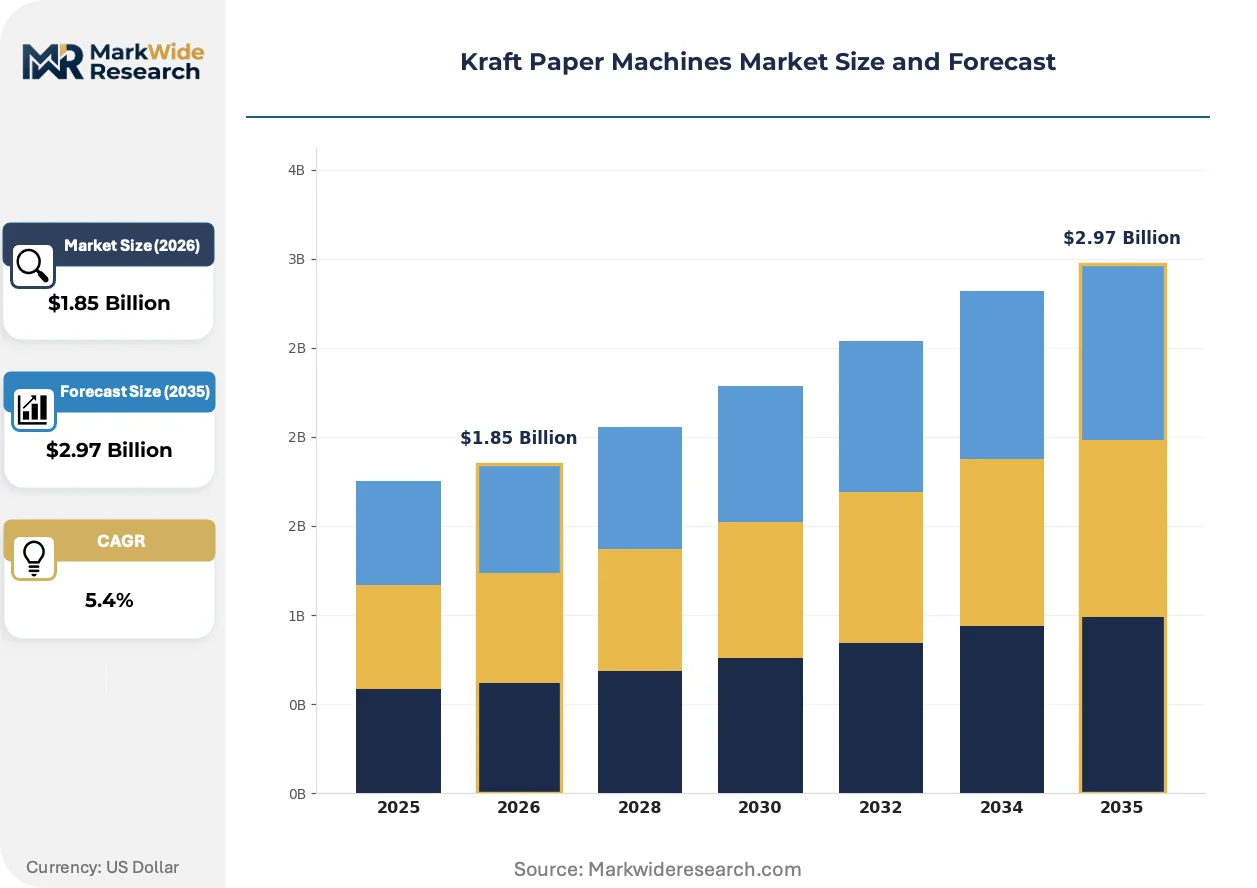
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Wet Machines, Dry Machines, Recycled Paper Machines, High-Speed Machines End User Industry: Packaging, Printing, Stationery, Industrial Technology: Conventional, Mechanical, Chemical, Digital Product Form: Rolls, Sheets, Pulp, Boards |
| Companies Covered | Valmet, Voith Group, Andritz AG, A.Celli Group, Toscotec, Kadant Inc., Mitsubishi Heavy Industries, BHS Corrugated, Fosber Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kraft Paper Machines Market Trends and Innovations
Machine architecture is bifurcating between premium electrified configurations and cost-optimized mechanical alternatives as energy pricing and carbon accounting reshape total cost of ownership calculations.
Advanced induction drying technology is electrifying heat delivery to the paper web, eliminating direct fossil fuel combustion in the drying section. Nordic linerboard producers are piloting these systems at commercial scale. This electrification is compressing the operating cost gap between gas-fired and all-electric machine configurations.
EPA effluent guidelines are tightening permissible discharge loads from pulp and paper clusters, forcing wet-end chemistry recirculation investments. American mills face capital decisions between end-of-pipe treatment and process-integrated closed loops. Containerboard grades with high recycled content encounter the steepest compliance cost escalation.
After-sales service unbundling is accelerating as converter procurement teams separate hardware acquisition from maintenance contracts. Third-party technical service providers are capturing lubrication system and roll grinding work previously captive to OEMs. This fragmentation is most pronounced among independent Indian mills lacking in-house mechanical departments.
Kraft Paper Machines Market Segmentation
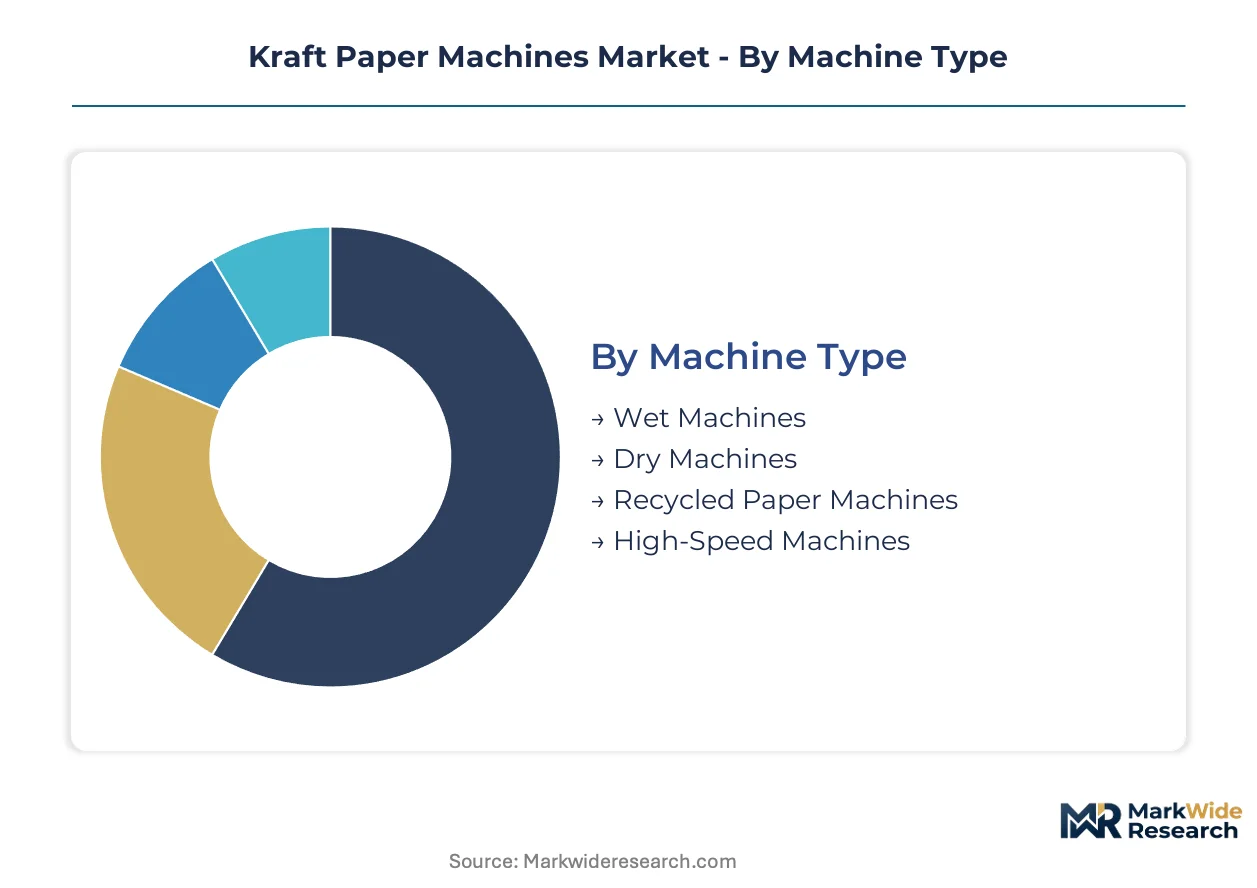
Kraft paper machines serve distinct operational profiles across virgin fiber, recycled furnish, and hybrid configurations. Buyer priorities diverge sharply between energy-intensive wet-end systems and compact dry machines for specialty grades.
Machine Type:
Capital deployment intensity separates purchasers in this dimension, with energy recovery capabilities and line speed tolerance driving specification divergence.
- Wet Machines:These systems process raw pulp through continuous Fourdrinier or gap-forming wet ends, requiring substantial steam infrastructure for drying sections. Demand clusters among Indian linerboard producers responding to the central government's single-use plastic ban, though legacy installations face margin pressure from rising recovered fiber price volatility.
- Recycled Paper Machines:Engineered for higher furnish ratios and post-consumer fiber variability, these configurations incorporate advanced cleaning and deinking stages. European converters under EU Packaging and Packaging Waste Regulation mandates are accelerating retrofit orders to meet tightening recycled content requirements without sacrificing throughput.
- Dry Machines:Compact units bypass traditional wet-end forming for specific specialty applications.
- High-Speed Machines:Automated configurations serve Asia-Pacific e-commerce fulfillment centers replacing plastic void fill.
Wet machines lead volumes today; recycled paper machines are gaining share fastest.
End User Industry:
Volume scale and specification tolerance distinguish procurement patterns across these verticals.
- Packaging:Corrugated medium and linerboard production dominates machine utilization, with basis weights between 80 and 350 grams per square meter. Vietnam's underpenetrated converting corridor near Ho Chi Minh City attracts first-mover installations serving ASEAN export manufacturing.
- Printing:Unbleached kraft grades for flexographic and offset applications require precise formation consistency.
- Stationery:Lower-tonnage applications favor compact machine footprints with quick grade change capability.
- Industrial:Protective wrapping and dunnage specifications tolerate wider quality variance.
Packaging commands the largest installed base; industrial applications show steepest expansion trajectory.
Technology:
Automation integration depth and chemistry management sophistication differentiate buyer segments here.
- Mechanical:Traditional forming configurations anchor emerging Asian installations where capital constraints favor proven architectures over electrified alternatives.
- Digital:IoT-enabled quality measurement and predictive maintenance platforms remain nascent but are piloting at Nordic linerboard producers for remote optimization of forming section consistency.
- Conventional:Established control architectures from the 1990s resist seamless modern framework connection.
- Chemical:Closed-loop chemistry management systems respond to EPA effluent guidelines and REACH restrictions.
Mechanical systems retain dominance; digital segments are climbing the fastest.
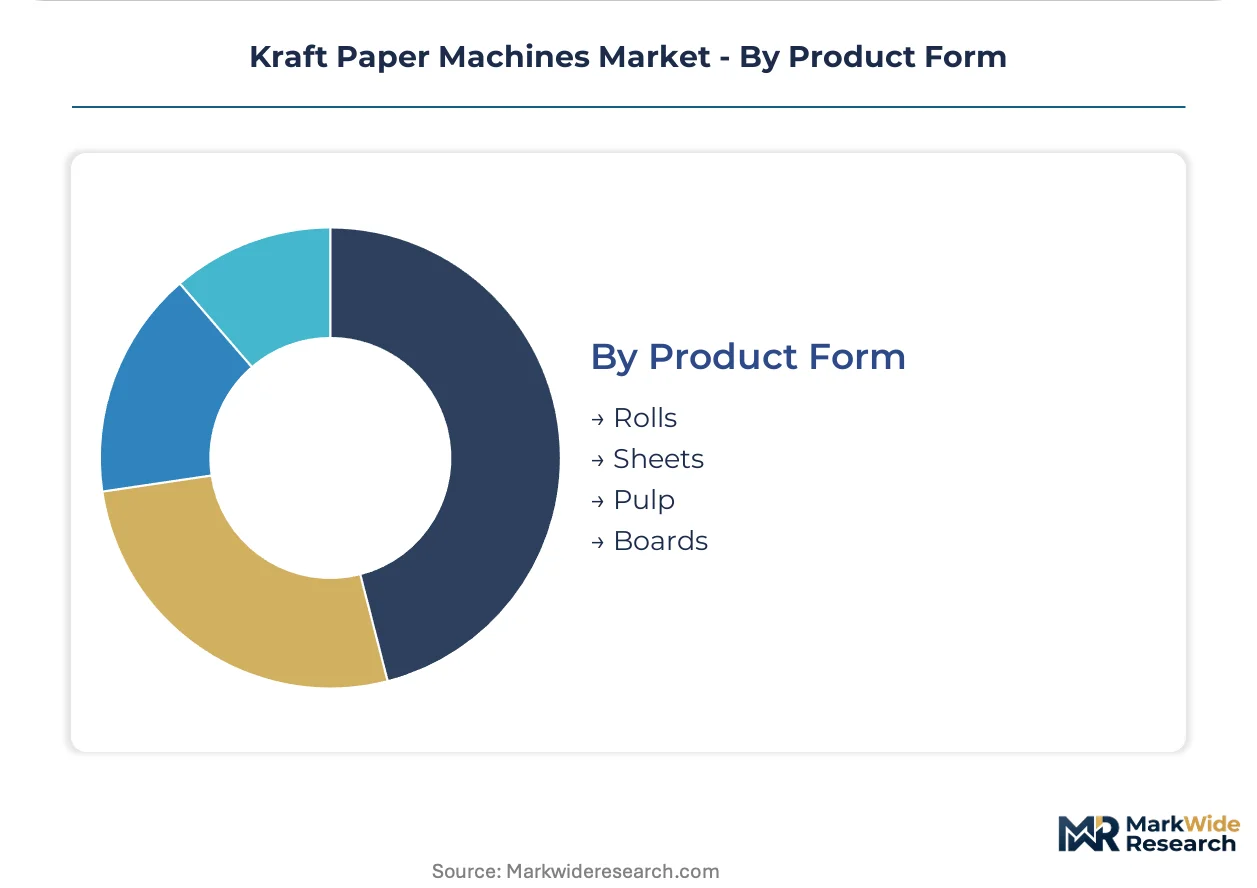
Product Form:
Downstream converting compatibility and logistics efficiency shape machine output specifications.
- Rolls:Continuous web output for corrugators and automated packaging lines dominates containerboard production.
- Sheets:Cut-size formats serve printing and stationery converters requiring precise dimensional stability.
- Pulp:Intermediate furnish for integrated mills with captive papermaking capacity.
- Boards:Heavy-duty grades for industrial protective applications.
Rolls lead volumes today; sheets are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kraft paper machine manufacturing traces its industrial roots to 19th-century European engineering centers, where continuous Fourdrinier forming technology first achieved commercial scale. Today's production geography reflects this legacy while shifting toward Asian demand centers.
Germany
High-precision wet-end component fabrication and shoe press technology development concentrate in Baden-Württemberg and Bavaria engineering clusters. REACH chemical restrictions from ECHA constrain process chemistry choices for machines exported to EU converters. The Karlsruhe-Heilbronn corridor hosts specialized suppliers serving rebuild projects across European linerboard producers.
United States
Containerboard capacity expansions in the Southeast and Pacific Northwest drive demand for high-speed recycled fiber configurations. EPA effluent guidelines tighten permissible discharge loads from pulp and paper clusters, forcing wet-end chemistry recirculation investments. The Georgia-Alabama corridor anchors brownfield retrofit activity as mills modernize drying sections for energy compliance.
India
Domestic kraft linerboard capacity additions accelerate following the central government's single-use plastics ban. BIS certification requirements for imported machinery create non-tariff barriers favoring local assembly partnerships. The Vapi-Ankleshwar industrial belt in Gujarat concentrates new machine installations serving western India packaging demand.
China
Dual carbon goals and MEE wastewater discharge limits reshape machine specification requirements for domestic mills. Yangtze River Delta and Pearl River Delta clusters upgrade forming sections for higher recycled furnish ratios. Shandong Province pulp and paper clusters face the steepest compliance cost escalation for containerboard grades with high post-consumer content.
Vietnam
Underpenetrated converting capacity near Ho Chi Minh City attracts first-mover machine installations serving ASEAN export manufacturing. E-commerce fulfillment automation spreads from distribution centers to upstream corrugator investments. The southern packaging corridor lacks sufficient domestic linerboard supply, creating import substitution opportunities for integrated kraft machine projects.
Kraft Paper Machines Market Competitive Landscape
Premium-margin players sit above commodity-margin players across automation integration and energy recovery capabilities, with the former commanding pricing power on rebuild portfolios and the latter competing on mechanical reliability for emerging market greenfield sites. The supplier base consolidates around three strategic archetypes: full-line system integrators with automation-integrated portfolios, wet-end specialists with proprietary pressing technology, and energy recovery-focused fabricators competing on drying section efficiency. Dominant competitive moves include strategic partnerships for local assembly in India and technology licensing agreements for digital twin integration.
Among European-based engineering groups, Valmet, Voith Group, and Andritz AG exemplify the three archetype positions. Valmet represents the automation-integrated system integrator tier. Voith Group occupies the wet-end specialist position with proprietary shoe press configurations. Andritz AG anchors the energy recovery-focused competitor set. Each sits within distinct margin bands based on technology differentiation depth and aftermarket service contract penetration.
| Leading Market Players |
|---|
| Valmet |
| Voith Group |
| Andritz AG |
| A.Celli Group |
| Toscotec |
| Kadant Inc. |
| Mitsubishi Heavy Industries |
| BHS Corrugated |
| Fosber Group |
| Others |
Pricing and Supply Chain Analysis
Recovered fiber price volatility cascades through kraft paper machine procurement tiers, compressing margins for virgin-optimized configurations while elevating recycled-fiber-capable systems to premium positioning across European and Indian buyer segments.
Pricing Analysis
Project-based capital equipment contracting dominates kraft paper machine transactions, with pricing stratifying across automation-integrated premium rebuilds, standard wet-end configurations, and economy-grade mechanical alternatives. Price differentiation hinges on energy recovery system sophistication and local assembly partnership depth in India. Cost compression in economy tiers intensifies because Chinese fabricators compete aggressively on drying section components. Independent Indian mills exhibit highest price sensitivity; Nordic linerboard producers demonstrate lowest sensitivity due to EU Green Deal subsidy capture.
Supply Chain Analysis
Single-source vulnerability sits with German and Finnish wet-end component fabrication clusters, where specialized shoe press manufacturing concentrates. Machine assembly draws from steel foundries in China, precision instrumentation from Japan, and control systems from Germany. Tariff exposure looms over EU-sourced components imported into India under BIS certification requirements. Distribution runs through OEM direct sales for premium rebuilds and local assembly partnerships for emerging market greenfield installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: European energy costs and REACH compliance burdens push production technology sourcing toward Indian assembly partnerships and Vietnamese end-user demand clusters.
For Market Incumbents: Extend automation-integrated rebuild portfolios into EU member state recovery fund pipelines before subsidy windows narrow. Defend margin position by deepening captive aftermarket service contracts in India where third-party technical providers fragment lubrication and roll grinding work. Threat: Voith Group's proprietary shoe press technology sustains wet-end dominance through knowledge concentration among retiring European mill engineers. For New Entrants and Emerging Players: Digital twin integration for predictive maintenance platforms offers technology-first wedge into Nordic linerboard pilot programs before Valmet consolidates IoT-enabled quality measurement. Target Vietnam's underpenetrated converting corridor near Ho Chi Minh City where domestic linerboard supply shortages create first-mover machine installation opportunities. Go-to-market angle: partner with ASEAN export manufacturers for integrated kraft machine projects replacing plastic void fill in e-commerce fulfillment automation. For Investors and Strategic Acquirers: Consolidation pressure builds where energy recovery system expertise concentrates among European engineering groups unable to scale Indian local assembly partnerships independently. Long-term viability favors full-line system integrators with automation depth and aftermarket contract penetration. Acquisition target archetype: energy recovery-focused fabricators with drying section efficiency patents and stranded European customer relationships. Signal to watch: BIS certification requirement tightening that forces foreign OEMs into mandatory joint ventures with domestic Indian assembly partners.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Partnership | BIS certification mandates in India compel foreign OEM joint ventures with domestic fabricators. |
| Energy Recovery System Patent Acquisition | Andritz AG's drying section steam demand reduction technology anchors competitive differentiation. |
| Digital Twin Platform Integration | IoT sensor convergence enables remote optimization of forming section consistency at Nordic mills. |
| EU Green Deal Subsidy Pipeline Access | Member state recovery funds earmark co-financing for energy-efficient drying section upgrades. |
| ASEAN Export Manufacturing Corridors | Vietnam packaging demand clusters near Ho Chi Minh City attract first-mover machine installations. |
Research Methodology
Bottom-up packaging demand modeling reconciled against top-down machine shipment tracking forms the analytical core of this study. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads at linerboard producers across Germany, India, China, and Vietnam combined with secondary validation from customs records, SEC filings of publicly traded paper machinery suppliers, trade association capacity databases, and national packaging waste regulation filings. Triangulation between end-use demand signals and supply-side installation data ensures cross-verification of market sizing.
Input-output matrices segment the forecast across machine type, furnish configuration, automation integration depth, and regional regulatory cluster. Growth trajectory derivation incorporates recycled fiber availability mandates, e-commerce fulfillment automation penetration, and energy pricing differentials across the projection horizon. Industry-specific forecast inputs include old corrugated container price volatility indices and EU Packaging and Packaging Waste Regulation compliance cost curves.
The model holds under stable regulatory enforcement timelines and continued single-use plastic ban implementation; deviation in recovered fiber supply shocks or trade restriction escalations would shift capacity addition schedules. Forecasts reflect documented assumptions about technology adoption curves and subsidy program continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Global Volumetric Cup Fillers Market
Packaging Machinery
Stacking Machine Market
Packaging Machinery
Paper Napkins Converting Machines Market
Packaging Machinery
EPS Pre-Expander Machines Market
Packaging Machinery
Glue Machine Market
Packaging Machinery
Cosmetic Packaging Machinery Market
Packaging Machinery
North America Printing Machinery Market
Packaging Machinery
Europe Blow Molding Machine Market
Packaging Machinery
Global Paper Napkin Making Machine Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Bundling Machine Market
Packaging Machinery
Horizontal Flow Wrapping Machines Market
Packaging Machinery
Tube Sealing Machines Market
Packaging Machinery
Vertical Bagging Machine Market
Packaging Machinery
Screw Capping Machines Market
Packaging Machinery
CCL Laminating Machine Market