
 Shrink Sleeve Labeling Equipment Market | 2026-2036
Shrink Sleeve Labeling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Shrink Sleeve Labeling Equipment Market Analytics
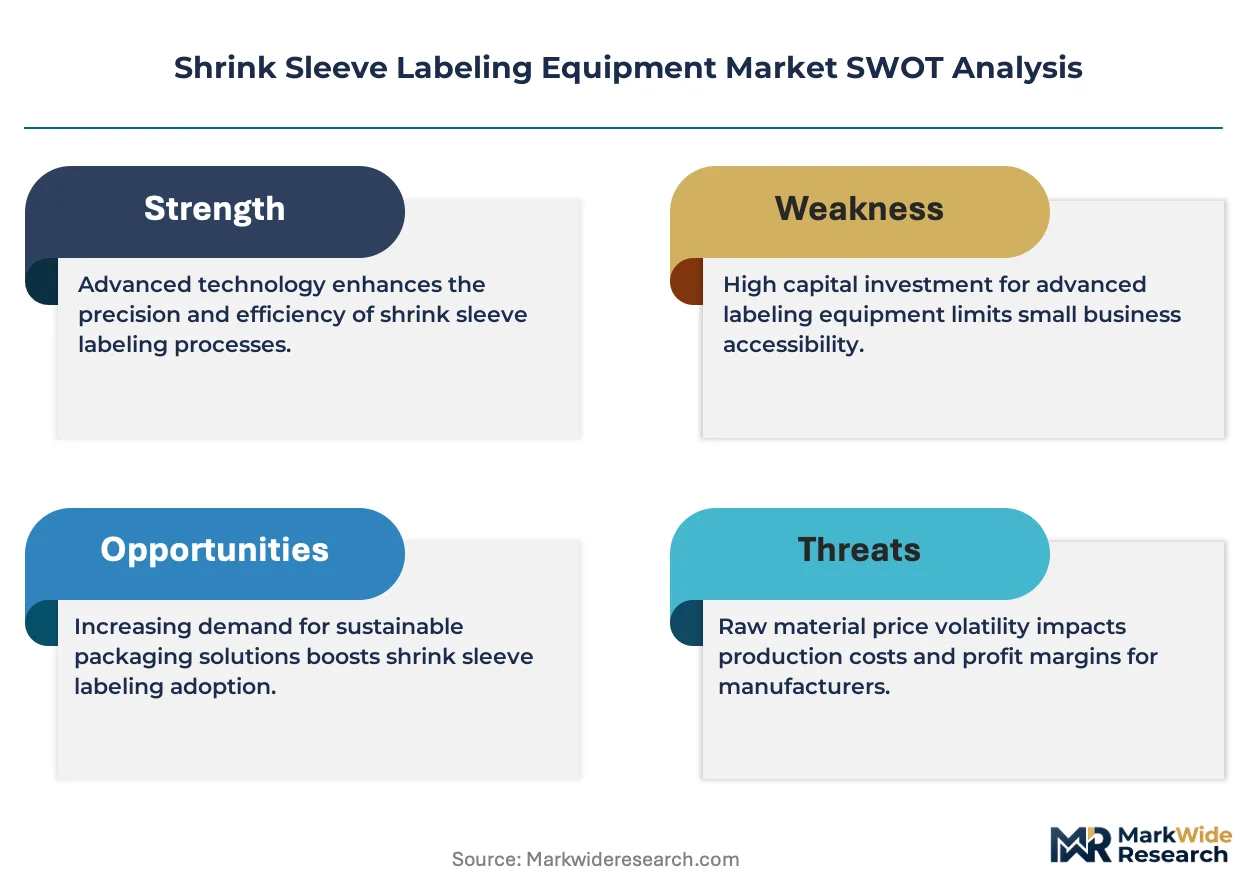
Germany's precision machinery corridor is narrowing the performance gap between European and Asian equipment standards. Krones AG leverages integrated filling-labeling-shrinking lines to dominate high-throughput beverage installations. Fuji Seal International anchors polymer film supply relationships that sustain shrink-sleeve adoption across Japanese personal-care brands. ProMach competes through modular system architectures that accommodate mid-speed craft beverage producers without full line replacement.
Shrink sleeve labeling equipment applies heat-reactive polymer sleeves to containers, then shrinks them via steam, hot-air tunnel, or infrared radiation to form conforming 360-degree labels with tamper-evident bands. Automatic shrink sleeve systems lead capital deployment in dairy and soft-drink bottling halls where line speeds exceed 400 containers per minute. Heat tunnel technology occupies the largest installed base, though steam shrink configurations are gaining share in heat-sensitive pharmaceutical and personal-care applications where substrate distortion risks escalate.
FDA food-contact substance notifications and EU REACH compliance on polymer additives shape film formulation choices and equipment validation protocols for pharmaceutical and food end users. OSHA lockout/tagout standards and CE machinery directives govern guard design and operator access points, adding engineering cost but reducing liability exposure for installed bases. Stakeholders must monitor evolving extended-producer-responsibility frameworks, as sleeve material recyclability will increasingly determine specification wins in tender processes across European and North American bottling procurement.
Market Dynamics
Recycled-content mandates under EU Packaging and Packaging Waste Regulation and California's SB 54 are forcing beverage bottlers to retrofit existing lines with sleeve-compatible PET handling systems, compressing equipment replacement cycles from seven years to four.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recycled-content thresholds for beverage containers accelerate sleeve-labeled PET adoption across German and French bottling corridors.
- Steam shrink technology:Heat-sensitive pharmaceutical and personal-care applications shift from hot-air tunnels to steam configurations, opening new equipment categories.
- Polymer film supply relationships:Japanese personal-care brands anchor long-term sleeve adoption through integrated film-equipment procurement partnerships.
Market Restraints
- Resin price volatility:PETG and PLA film feedstock costs swing with crude oil indices, squeezing converter margins and delaying equipment orders.
- Equipment validation protocols:FDA food-contact substance notifications and EU REACH compliance add six-to-nine-month certification timelines for pharmaceutical installations.
- Mechanical pressure-sensitive labels:Lower-capital wraparound systems retain share in water and bulk dairy segments where 360-degree decoration adds limited shelf impact.
Strategic Opportunities
- Modular system architectures:Mid-speed craft beverage producers in the US and Germany retrofit existing lines without full corridor replacement, expanding addressable base.
- Extended-producer-responsibility frameworks:Sleeve material recyclability will determine specification wins in European and North American tender processes.
- Infrared radiation shrinking:Convergence with precision temperature control enables pharmaceutical applications previously blocked by substrate distortion risks.
Industry Challenges
- Control systems integration:Legacy filling lines lack Ethernet/IP connectivity required for Industry 4.0 sleeve applicator synchronization, forcing costly PLC upgrades.
- Validation documentation:Pharmaceutical buyers demand IQ/OQ/PQ protocol packages that stretch OEM service engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shrink Sleeve Labeling Equipment Market |
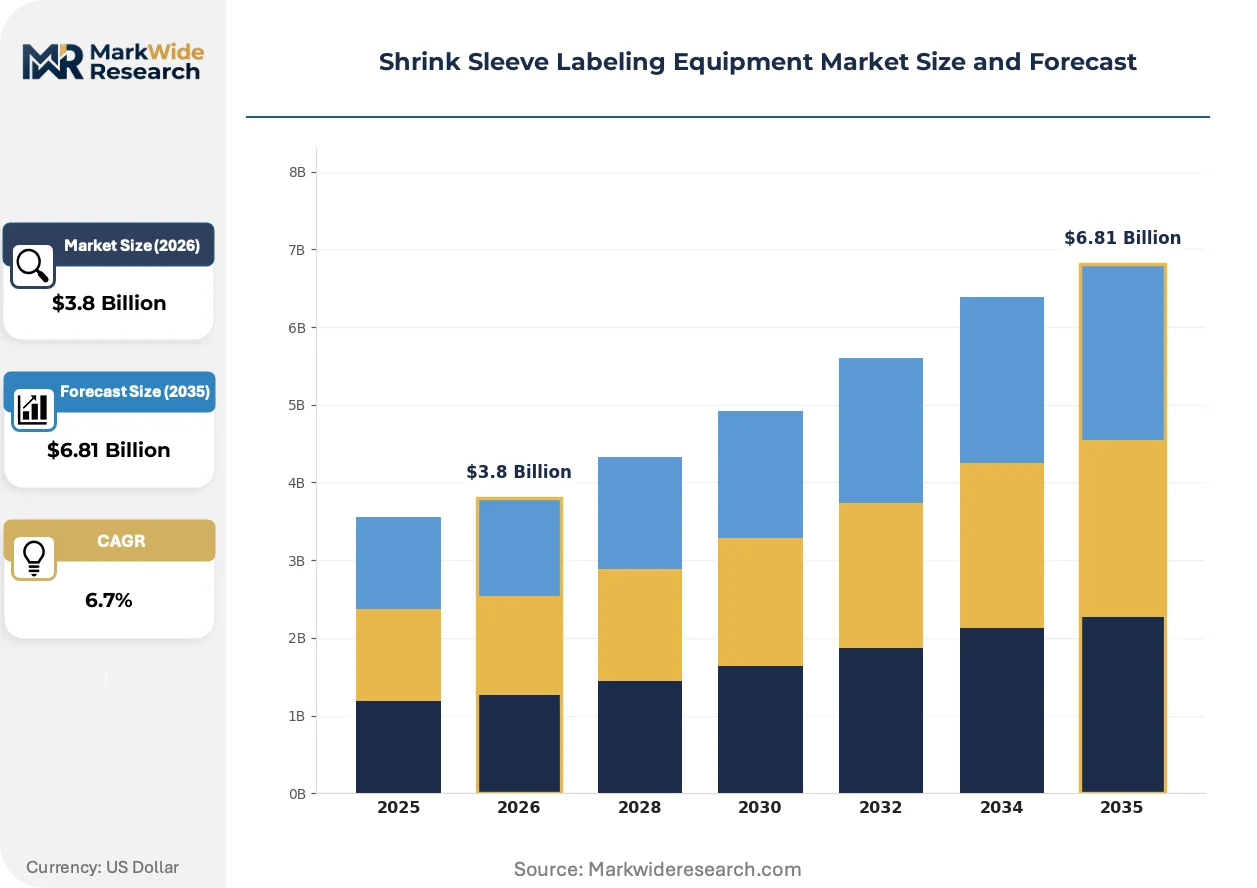
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Shrink Sleeve, Manual Shrink Sleeve, Semi-Automatic Shrink Sleeve, Compact Shrink Sleeve Technology: Steam Shrink, Heat Tunnel, Electric Shrink, Infrared Shrink End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Application: Bottling, Canning, Container Labeling, Product Bundling |
| Companies Covered | Krones AG, Fuji Seal International, ProMach, Accraply, PDC International, Sleever International, Pack Leader Machinery, BW Integrated Systems, Axon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shrink Sleeve Labeling Equipment Market Evolving Landscape
Heat tunnel configurations face displacement as steam and infrared systems capture pharmaceutical and premium cosmetic installations where temperature precision outweighs throughput maximization.
Steam shrink technology applies saturated vapor to polymer sleeves, achieving uniform shrinkage without thermal stress. Pharmaceutical contract packagers in Switzerland and Germany adopt steam tunnels for biologic container labeling where hot-air distortion risks batch rejection. The technology is migrating from niche pharmaceutical applications toward mainstream personal-care lines as film formulations stabilize.
EU REACH compliance on polymer additives restricts phthalate plasticizers and heavy-metal pigments in sleeve films. Equipment manufacturers must validate steam and infrared systems against reformulated lower-shrink-force substrates. Food and pharmaceutical end users in Germany and France now require additive disclosure documentation upstream of equipment procurement.
After-sales service unbundling separates maintenance contracts from initial capital sales. Beverage bottlers in California and Bavaria negotiate standalone technical support agreements with third-party service providers, compressing OEM recurring revenue streams. This pattern concentrates among high-throughput dairy and soft-drink installations where in-house maintenance teams lack shrink-tunnel calibration expertise.
Shrink Sleeve Labeling Equipment Market Segmentation
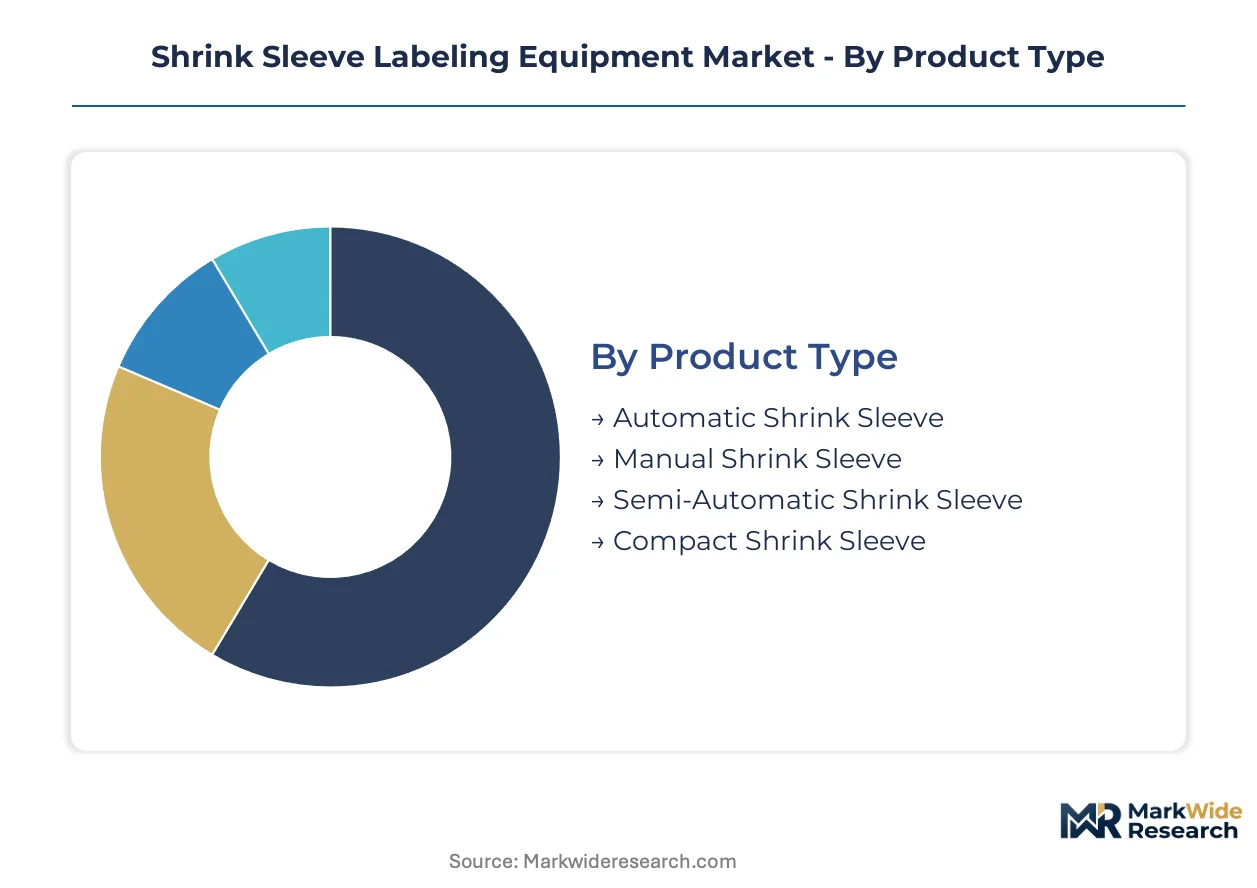
Equipment segmentation in the shrink sleeve labeling market reflects divergent capital deployment strategies across high-volume beverage corridors and craft-scale installations. Technology choices separate heat-intensive throughput maximizers from precision-temperature pharmaceutical packagers. End-user concentration in beverage bottling and pharmaceutical contract manufacturing drives specification divergence around validation protocols and line speed requirements.
Product Type:
Mature automatic systems anchor beverage bottling halls while compact and manual configurations serve emerging craft producers and pilot-line applications.
- Automatic Shrink Sleeve:High-speed servo-driven applicators synchronize with filling lines exceeding 400 containers per minute. Demand concentrates in German and Bavarian dairy and soft-drink corridors where Krones AG turnkey installations dominate capital deployment.
- Manual Shrink Sleeve:Hand-fed applicators with batch-fed sleeve magazines serve microbreweries and specialty food startups in California and Oregon. Capital constraints and sub-50-container-per-minute throughput requirements sustain niche procurement despite labor intensity.
- Semi-Automatic Shrink Sleeve:Operator-assisted loading with automated shrink tunnel integration bridges pilot-scale and production volumes.
- Compact Shrink Sleeve:Floor-space-optimized units retrofit existing packaging lines without corridor reconfiguration.
Automatic Shrink Sleeve retains volume leadership; Compact Shrink Sleeve holds the steepest expansion curve.
Technology:
Cost tier differentiation separates capital-intensive steam and infrared precision systems from established heat tunnel infrastructure with lower engineering complexity.
- Heat Tunnel:Convective hot-air systems maintain the largest installed base across beverage bottling. Temperature uniformity challenges limit adoption in pharmaceutical applications where substrate distortion risks escalate.
- Steam Shrink:Saturated vapor delivery achieves uniform polymer contraction without thermal stress. Swiss and German pharmaceutical contract packagers adopt steam tunnels for biologic container labeling where batch rejection costs dominate equipment selection criteria.
- Electric Shrink:Resistance-heating elements serve mid-speed applications with moderate temperature precision requirements.
- Infrared Shrink:Precision wavelength control enables pharmaceutical applications previously blocked by substrate distortion risks.
Heat Tunnel retains volume leadership; Infrared Shrink gains share fastest in premium cosmetic and pharmaceutical installations.
End User:
Application-specific validation requirements and throughput specifications create distinct procurement patterns across food, pharmaceutical, and personal-care verticals.
- Food & Beverage:High-throughput PET bottle and can labeling drives automatic system deployment. EU Packaging and Packaging Waste Regulation recycled-content mandates accelerate sleeve-labeled line retrofits in German and French bottling corridors.
- Pharmaceuticals:FDA food-contact substance notifications and EU REACH compliance on polymer additives shape film formulation choices and equipment validation protocols. IQ/OQ/PQ documentation requirements stretch OEM service engineering capacity.
- Personal Care:Heat-sensitive substrates and premium cosmetic positioning favor steam and infrared configurations over convective systems.
- Household Products:Aggressive chemical resistance requirements in cleaning product labeling sustain solvent-based adhesive alternatives to sleeve technology.
Food & Beverage retains volume leadership; Pharmaceuticals holds the steepest expansion curve.
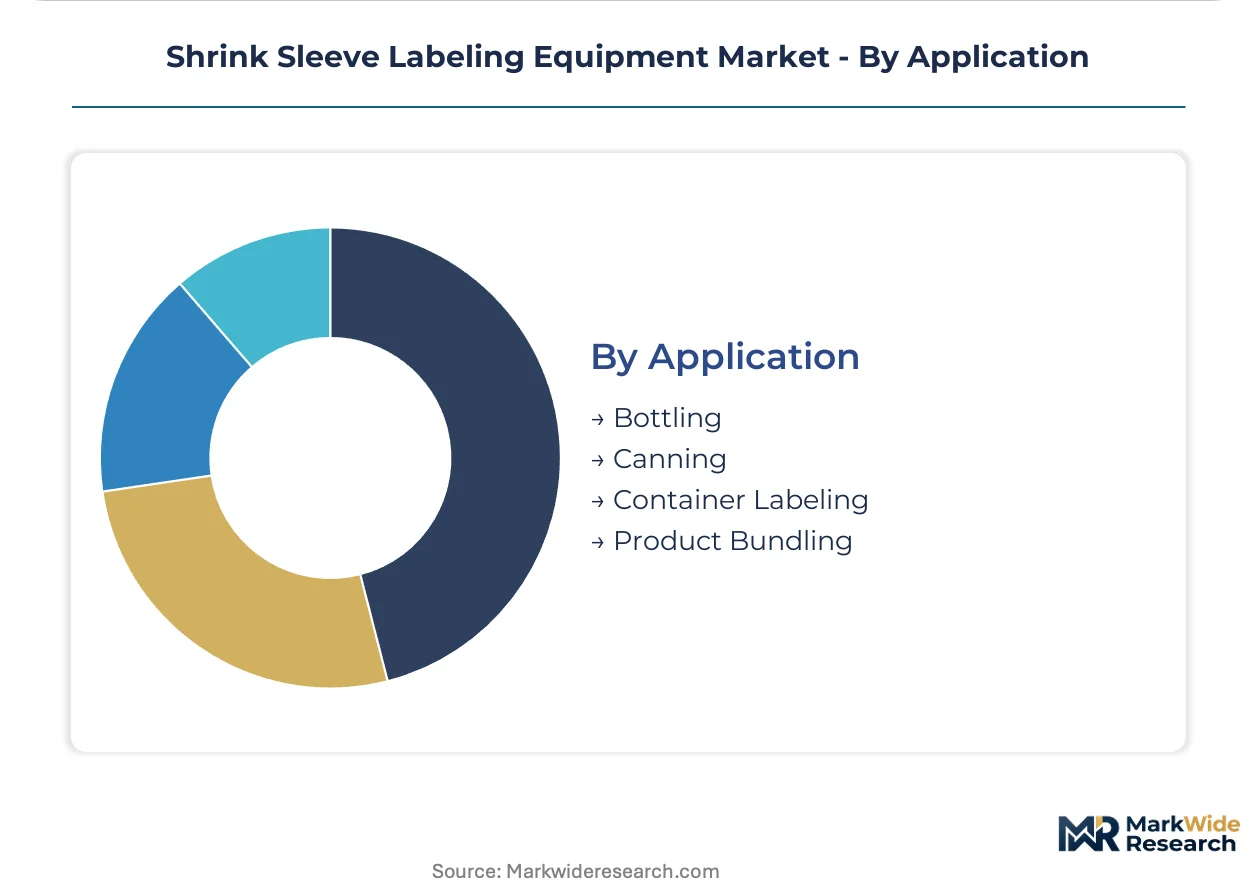
Application:
Volume scale and container geometry complexity determine technology matching across bottling, canning, and bundling operations.
- Bottling:PET and glass container sleeve application dominates capital deployment. German export corridors supply Middle Eastern and African markets with turnkey filling-labeling-shrinking lines.
- Container Labeling:360-degree decoration with tamper-evident band integration serves premium positioning requirements in personal-care and pharmaceutical segments.
- Canning:Aluminum beverage can sleeve compatibility requires modified applicator geometries and heat distribution profiles.
- Product Bundling:Multi-pack sleeve configurations serve promotional and retail-ready packaging requirements with lower speed demands than primary labeling.
Bottling retains volume leadership; Container Labeling holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision machinery exporters anchor supply-side concentration for shrink sleeve labeling systems, while regulatory mandates in North America and Europe compress equipment replacement cycles and redirect procurement toward sleeve-compatible PET handling retrofits.
United States
California beverage bottlers retrofit sleeve-labeled PET lines to meet SB 54 recycled-content thresholds, compressing replacement cycles from seven to four years. OSHA lockout/tagout standards govern guard design modifications for legacy filling line integrations. Craft beverage producers in Oregon and the Pacific Northwest sustain demand for compact semi-automatic configurations amid capital constraints.
Germany
Bavarian dairy and soft-drink corridors deploy high-speed turnkey filling-labeling-shrinking installations for export to Middle Eastern and African markets. EU Packaging and Packaging Waste Regulation recycled-content mandates accelerate specification wins for sleeve-compatible systems in bottling procurement tenders. Krones AG anchors the precision machinery corridor in Neutraubling, narrowing performance gaps against Asian equipment standards through integrated line architectures.
Japan
Personal-care brands anchor long-term sleeve adoption through integrated film-equipment procurement partnerships with polymer suppliers. METI industrial standards shape validation protocols for pharmaceutical and cosmetic installations. Fuji Seal International sustains polymer film supply relationships that stabilize converter margins amid resin price volatility.
Switzerland
Pharmaceutical contract packagers in Basel and Zurich adopt steam shrink tunnels for biologic container labeling where batch rejection costs dominate equipment selection criteria. Swissmedic validation requirements stretch OEM service engineering capacity for IQ/OQ/PQ documentation packages. Precision temperature control specifications favor steam and infrared configurations over convective heat tunnel systems.
France
Bottling corridors in Île-de-France and Hauts-de-France accelerate sleeve-labeled line retrofits under EU Packaging and Packaging Waste Regulation compliance timelines. ANSM disclosure requirements for polymer additives upstream of equipment procurement reshape film formulation choices. Food and pharmaceutical end users now mandate additive documentation before capital commitment.
Shrink Sleeve Labeling Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in film supply and applicator subsystems. The vendor base separates between consolidated turnkey providers serving high-throughput beverage installations and fragmented modular specialists addressing mid-speed craft producers. Three archetypes dominate: precision machinery exporters with integrated filling-labeling corridors, polymer film suppliers backward into equipment partnerships, and modular system architects enabling line retrofit without full replacement. Competitive moves concentrate on M&A for technology licensing access and strategic partnerships bridging film formulation with equipment validation protocols.
Among German precision machinery exporters, Krones AG exemplifies the integrated platform archetype through its Neutraubling-based turnkey operations. Fuji Seal International occupies a position linking polymer film supply with equipment procurement partnerships among Japanese personal-care brands. ProMach represents the modular system tier, serving mid-speed craft beverage producers in the United States and Germany with retrofit-compatible architectures that avoid full corridor replacement.
| Leading Market Players |
|---|
| Krones AG |
| Fuji Seal International |
| ProMach |
| Accraply |
| PDC International |
| Sleever International |
| Pack Leader Machinery |
| BW Integrated Systems |
| Axon |
| Others |
Value Network & Pricing Analysis
Neutraubling's precision machinery cluster dictates downstream pricing power through captive control over high-speed turnkey line configurations. Bavarian OEMs bundle validation documentation and after-sales calibration services into multi-year contracts, compressing third-party converter margins.
Pricing Analysis
EU REACH compliance dictates the pricing tier structure across pharmaceutical and food-contact installations. Three-tier pricing separates FDA-validated steam shrink systems from standard heat tunnel configurations and compact semi-automatic units for craft producers. Price differentiation rests on IQ/OQ/PQ documentation packages and additive disclosure certification. Cost compression in mid-speed equipment is intensifying because resin price volatility squeezes converter procurement budgets. Craft beverage producers in Oregon and Bavaria exhibit highest price sensitivity; Swiss pharmaceutical contract packagers show lowest.
Supply Chain Analysis
Tariff exposure between Germany and Middle Eastern export destinations dominates supply chain risk assessment for turnkey line shipments. Component sourcing draws from German servo-drive manufacturers, Japanese polymer film suppliers, and Chinese infrared heating element producers. Raw material dependencies include PETG resin, PLA feedstock, and precision temperature sensors. Single-source vulnerability concentrates in high-speed applicator subsystems. Distribution runs through OEM-direct channels for beverage bottling corridors and specialized distributor networks for craft-scale installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shrink sleeve labeling equipment functions as a service-attach opportunity where standalone technical support agreements and validation documentation packages expand faster than hardware unit sales. After-sales service unbundling among California and Bavarian bottlers signals recurring revenue capture potential.
For Market Incumbents: Pre-empt modular system specialists by embedding compact retrofit configurations within existing high-speed platform architectures. Additive disclosure documentation requirements under EU REACH and ANSM mandates create certification barriers that favor incumbents with established validation engineering capacity. Backward integration into polymer film supply partnerships defends margin position against resin price volatility.
For New Entrants and Emerging Players: Pursue mid-speed craft beverage producers in Oregon and the Pacific Northwest where capital constraints exclude turnkey line purchases. Steam shrink technology for heat-sensitive pharmaceutical applications remains underpenetrated relative to hot-air tunnel installed base. Go-to-market positioning should emphasize standalone validation documentation services that stretch incumbent OEM engineering capacity.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because extended-producer-responsibility frameworks and recycled-content mandates structurally expand sleeve-compatible equipment demand. Acquisition targets include modular system architects with retrofit-compatible architectures and third-party service providers with shrink-tunnel calibration expertise. The signal to watch is tender specification language around sleeve material recyclability requirements in European and North American bottling procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Film Supply | Fuji Seal International's captive film relationships stabilize converter margins amid PETG volatility. |
| Modular System Architecture Development | ProMach's retrofit-compatible designs capture craft beverage producers without full corridor replacement. |
| IQ/OQ/PQ Validation Documentation Packages | Swissmedic requirements stretch OEM service engineering capacity and create recurring revenue streams. |
| Steam Shrink Technology Migration | Basel pharmaceutical packagers adopt saturated vapor systems where batch rejection costs dominate selection criteria. |
| Third-Party Service Provider Partnerships | California bottlers negotiate standalone technical support agreements that compress OEM recurring revenue. |
Research Methodology
A standing panel of plant engineers, aftermarket service heads, OEM procurement teams, and polymer film converters provided ongoing calibration across primary fieldwork and secondary validation. Equipment specification databases, FDA food-contact substance notifications, EU REACH additive registries, and customs trade records supplied triangulation anchors. Bottom-up unit economics and top-down corridor deployment assessments converged on volume and value estimates.
Scenario-bracketing around regulatory compliance timelines and resin price volatility bands bounded projection uncertainty across the analysis window. Segmentation modeling incorporated equipment type, shrink technology, end-use vertical, and application geometry. CAGRs derived from line retrofit cycle compression and export corridor expansion patterns. Pharmaceutical validation protocol timelines and craft beverage capital formation cycles served as industry-specific forecast inputs.
Sensitivities concentrate around EU Packaging and Packaging Waste Regulation enforcement acceleration and PETG feedstock cost trajectories. Forecasts reflect documented assumptions on replacement cycle compression and steam shrink technology adoption curves. Material shifts in extended-producer-responsibility framework implementation or polymer additive restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Cannabis Packaging Equipment Market
Packaging Equipment
Labeling Equipment Market
Packaging Equipment
Diaper Packaging Machines Market
Packaging Equipment
Heat Sealing Equipment Market
Packaging Equipment
Basket Granulator Extruder Market
Packaging Equipment
Global Reverse Vending Machine Market
Packaging Equipment
Industrial Heat Sealers Market
Packaging Equipment
Corrugated Equipment Market
Packaging Equipment
Hot Melt Equipment Market
Packaging Equipment
Refrigerated Display Cases Market
Packaging Equipment
Hot Fill Packaging Market
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Loading Spout Market
Packaging Equipment
Thermal Impulse Sealers Market
Packaging Equipment
Sack Tip Stations Market
Packaging Equipment
Blow Molding Tools Market