
 Plastic Extruding Equipment Market | 2026-2036
Plastic Extruding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Extruding Equipment Market Insights
Subscription-based predictive maintenance and software-defined process control is hardening as a core revenue layer for extrusion equipment vendors. KraussMaffei leverages its digital twin platform to anchor long-term service contracts across European film blowing installations. Coperion competes through intensive R&D in co-rotating twin screw configurations for compounded biopolymers. Davis-Standard sustains its North American position through specialized aftermarket parts logistics and remote diagnostics capabilities.
Plastic extruding equipment comprises machinery that forces thermoplastic or thermoset polymer through a shaped die to produce continuous profiles, typically operating at barrel temperatures between 150°C and 400°C with screw speeds from 50 to 1,200 rpm depending on material viscosity and output requirements. Twin screw extruders dominate high-value compounding applications where devolatilization and reactive processing justify capital intensity, while single screw variants retain cost advantages in commodity film and pipe production. Gear pump technology segments command premium positioning by stabilizing melt pressure for precision sheet and medical tubing outputs, and servo motor drive adoption is displacing hydraulic systems in energy-sensitive European installations.
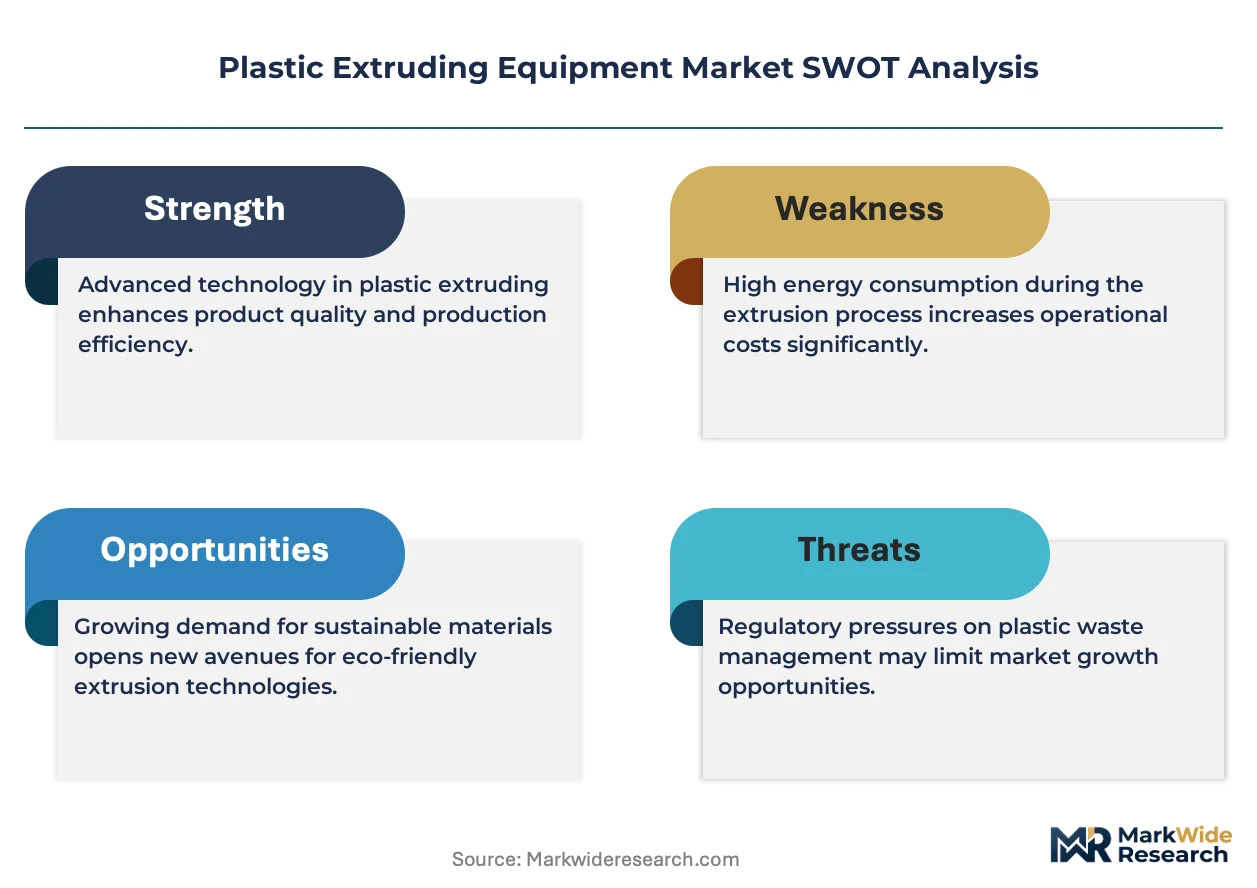
The EU Green Deal and REACH framework restrict virgin polymer intensities and mandate energy labeling, compelling equipment upgrades toward lower specific energy consumption measured in kWh per kilogram of output. FDA regulations in the United States govern contact-layer extrusion for medical tubing and food packaging, creating compliance barriers for non-validated machinery imports. ISO standards for screw geometry and safety interlocks further condition cross-border equipment acceptance. Stakeholders must monitor how polymer recycling mandates in major economies reshape extruder specifications for post-consumer feedstock handling.
Market Dynamics
The EU Green Deal and REACH framework are forcing equipment makers to reengineer extrusion lines for lower specific energy consumption, while packaging manufacturers in Asia-Pacific scale capacity for recycled-content films. This dual regulatory and demand pressure is restructuring capital allocation across the value chain.
Growth Catalysts
- REACH compliance mandates:European chemical safety regulations require machinery upgrades that reduce emissions and improve devolatilization capabilities, pulling replacement demand from compounders handling post-consumer feedstock.
- Biopolymer compounding expansion:Reactive processing requirements for PLA and PHA blends favor twin screw configurations with intensive cooling and venting stages, expanding the addressable equipment base.
- China:Domestic film and pipe producers are scaling localized supply chains to reduce import dependency, concentrating greenfield investments in Jiangsu and Zhejiang provinces.
Market Restraints
- Copper and rare earth magnet costs:Servo motor drives depend on neodymium-iron-boron magnets and high-conductivity windings, exposing equipment margins to commodity volatility in Chinese processing centers.
- German gearbox concentration:Precision gear pump technology relies on a narrow supplier base concentrated in Baden-Württemberg and Bavaria, creating single-source vulnerability for medical tubing lines.
- Post-consumer feedstock inconsistency:Variable melt flow indices and contamination levels in recycled polymers limit output rates and die stability, compressing effective throughput versus virgin resin systems.
Strategic Opportunities
- India:The PLI scheme for specialty chemicals and packaging materials is attracting extrusion equipment investments into Gujarat and Maharashtra, with local assembly partnerships reducing landed cost.
- Predictive maintenance platforms:Software-defined process control and digital twin integration enable subscription revenue streams that extend customer lifetime value beyond hardware margins.
- Medical tubing precision:FDA validation requirements for contact-layer extrusion create premium positioning for gear pump-stabilized lines serving minimally invasive device manufacturers.
Industry Challenges
- Reactive extrusion engineering talent:Devolatilization and polymerization kinetics expertise remains scarce, extending commissioning timelines for biopolymer compounding installations.
- ISO screw geometry certification:Cross-border equipment acceptance requires documented compliance with safety interlock and barrel pressure standards, adding documentation burden for Asian exporters.
- Legacy hydraulic system retrofit:Energy-sensitive European installations face integration complexity when upgrading to servo motor drives without full line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Extruding Equipment Market |
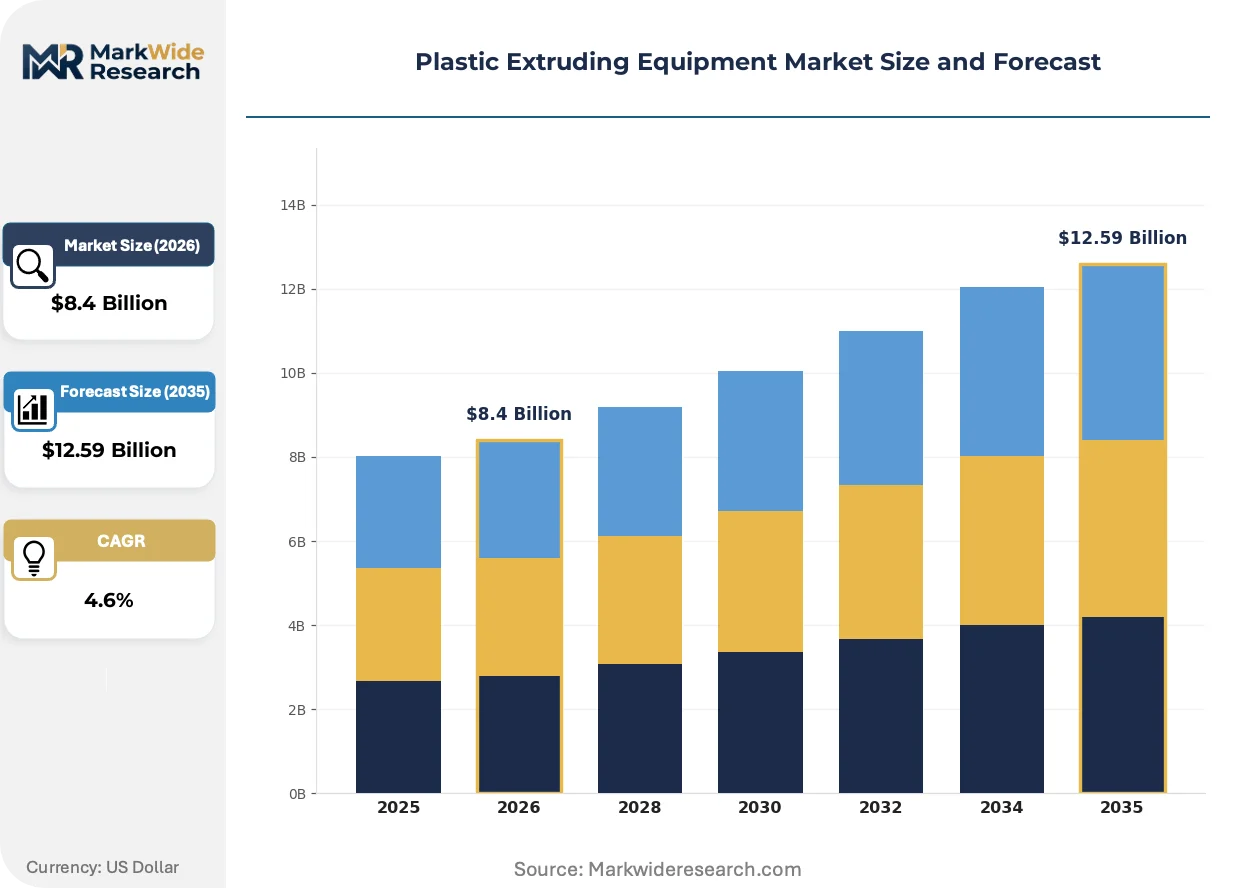
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Screw Extruders, Twin Screw Extruders, Co-rotating, Counter-rotating, Multi-screw Extruders Technology: Gear Pump Technology, Direct Drive, Hydraulic Drive, Servo Motor Drive, Vacuum Venting Application: Film Blowing, Pipe Making, Sheet Extrusion, Profile Extrusion, Wire & Cable Coating, Tubing Production End User Industry: Packaging Manufacturers, Electrical & Electronics Manufacturers, Construction Material Producers, Medical Device Fabricators, Consumer Goods Assemblers |
| Companies Covered | KraussMaffei, Coperion, Leistritz Extrusionstechnik, Bausano, Reifenhäuser Group, Davis-Standard, The Japan Steel Works, Kabra Extrusiontechnik, Milacron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Extruding Equipment Market Trends and Innovations
Digital twin platforms and software-defined process control are automating extrusion line management, while regulatory frameworks tighten material and energy specifications. These forces are compressing equipment replacement cycles and elevating service contract economics.
Machine learning-based die gap control is automating thickness uniformity in blown film operations. Packaging converters in Germany and the Netherlands are deploying these systems to reduce material give-away and scrap rates. The technology is automating quality assurance workflows that previously required manual gauge sampling, compressing labor intensity per ton of output.
The EU F-Gas Regulation and associated energy labeling mandates are restricting refrigerant choices for extrusion cooling systems and establishing disclosure requirements for specific energy consumption. Equipment vendors must now certify kWh per kilogram performance to access European tenders. Medical and food-contact segments face the steepest compliance timelines due to叠加 FDA and EFSA validation requirements.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts into discrete modules for remote diagnostics, spare parts logistics, and on-site technical support. North American processors are purchasing diagnostics-only tiers while retaining in-house mechanical capabilities. This pattern is most pronounced among mid-cap film producers in the US Midwest seeking to reduce fixed service expenditures.
Plastic Extruding Equipment Market Segmentation
Equipment selection in plastic extrusion hinges on polymer rheology, output precision requirements, and energy constraints. Segmentation reveals where capital deployment concentrates and which configurations command premium positioning.
Product Type:
Capital intensity varies sharply across screw configurations, with multi-screw systems demanding the highest upfront investment but delivering superior devolatilization economics.
- Single Screw Extruders:A solitary rotating screw within a heated barrel melts and conveys polymer at lower capital cost. Film and pipe producers in China favor these units for commodity output where throughput outweighs precision requirements.
- Twin Screw Extruders:Intermeshing screws enable intensive mixing, devolatilization, and reactive processing for engineering polymers and biopolymer compounding. German compounders leverage these configurations to meet REACH emissions mandates.
- Co-rotating:Screws rotate in the same direction for high-shear dispersive mixing. Medical tubing fabricators specify these for tight residence time control.
- Counter-rotating:Opposing screw rotation generates calendering effects ideal for PVC profile stability.
- Multi-screw Extruders:Triple or quadruple screw arrays address ultra-high-viscosity elastomers and continuous polymerization reactions.
Most installed capacity flows through single screw extruders. Expansion is steepest in twin screw configurations.
Technology:
Drive technology selection determines energy efficiency trajectories and maintenance cost structures across the equipment lifecycle.
- Gear Pump Technology:Precision melt pressure stabilization enables micron-level thickness control in medical tubing and optical sheet. FDA validation requirements in the United States restrict sourcing to certified suppliers.
- Servo Motor Drive:Permanent magnet synchronous motors cut specific energy consumption versus hydraulic alternatives. European installations adopt these to comply with EU energy labeling mandates.
- Direct Drive:Motor-to-screw coupling eliminates gearbox losses and backlash for high-torque compounding.
- Hydraulic Drive:Proportional valve systems retain cost advantages in emerging markets despite higher operating energy.
- Vacuum Venting:Multi-stage degassing removes volatiles and moisture from recycled feedstocks.
Gear pump and servo motor combinations command the highest price tiers. Vacuum venting is gaining share fastest in post-consumer recycling lines.
Application:
Application segments diverge by die complexity, cooling requirements, and downstream automation integration intensity.
- Film Blowing:Annular dies with internal bubble cooling produce biaxially oriented packaging films. Machine learning-based gauge control is compressing labor intensity at German converters.
- Pipe Making:Spiral mandrel dies with vacuum calibration tanks serve infrastructure-grade pressure piping. Indian producers scale capacity under PLI scheme incentives.
- Sheet Extrusion:Wide T-dies with roll stack cooling deliver thermoforming feedstock for food packaging.
- Profile Extrusion:Complex die geometries produce window frames and building trim with tight dimensional tolerances.
- Wire & Cable Coating:Crosshead dies apply insulation and jacketing layers around conductor cores.
- Tubing Production:Precision medical tubing demands gear pump stabilization and cleanroom extrusion environments.
Film blowing hosts the largest installed base. Medical tubing production is expanding most quickly.
End User Industry:
End-user procurement patterns range from price-sensitive volume purchasing to validation-intensive premium sourcing.
- Packaging Manufacturers:Film converters and thermoformers dominate equipment demand, with Asia-Pacific producers scaling recycled-content capacity.
- Medical Device Fabricators:Minimally invasive device manufacturers specify validated extrusion lines with documented FDA compliance.
- Electrical & Electronics Manufacturers:Wire and cable producers require flame-retardant compounding capabilities for insulation systems.
- Construction Material Producers:Pipe and profile extruders serve infrastructure replacement cycles.
- Consumer Goods Assemblers:Appliance and furniture manufacturers source decorative and structural profiles.
Packaging manufacturers absorb the majority of annual equipment shipments. Medical device fabricators are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement migrates toward jurisdictions where regulatory compliance costs diverge most sharply from output premiums, with compounders arbitraging REACH-mandated upgrades against Asian manufacturing scale.
China
Domestic film and pipe producers in Jiangsu and Zhejiang provinces are scaling localized supply chains to reduce import dependency. MIIT industrial upgrading directives favor domestic equipment procurement for post-consumer recycling lines. Suzhou and Ningbo clusters concentrate greenfield twin-screw investments serving biopolymer compounding demand.
Germany
REACH emissions mandates and EU Green Deal energy labeling are forcing wholesale line replacements across Baden-Württemberg compounders. ECHA devolatilization requirements pull premium demand toward vacuum-vented configurations. Stuttgart and Munich industrial zones anchor precision gear pump manufacturing for medical tubing export markets.
India
PLI scheme incentives for specialty chemicals and packaging materials are attracting extrusion equipment investments into Gujarat and Maharashtra. BIS energy efficiency standards for plastics machinery tighten import specifications. Ahmedabad and Pune districts host emerging local assembly partnerships reducing landed costs for mid-cap film producers.
United States
FDA validation requirements for medical tubing and food-contact extrusion create compliance barriers favoring certified domestic suppliers. EPA emissions guidelines for polymer processing affect equipment specification in Texas and Ohio manufacturing corridors. Minneapolis and Chicago clusters sustain specialized aftermarket parts logistics for legacy hydraulic system retrofits.
Japan
METI carbon neutrality roadmaps accelerate servo motor drive adoption in energy-sensitive Kansai installations. JIS screw geometry certification requirements condition cross-border equipment acceptance for Osaka and Nagoya precision manufacturers. Yokohama medical device fabricators specify validated gear pump-stabilized lines for minimally invasive device production.
Plastic Extruding Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium validated equipment consolidating around European engineering houses while Asian fabricators capture volume-driven commodity procurement. The vendor base organizes into three functional tiers: precision medical specialists, integrated process technology platforms, and regional assembly partnerships. Consolidation pressure concentrates in aftermarket service capabilities and predictive maintenance software layers. Geographic expansion and technology licensing represent the dominant competitive vectors as vendors seek to anchor long-term service contracts.
Among Germany-based engineering groups, KraussMaffei GmbH and Coperion GmbH occupy positions exemplifying the integrated process technology archetype, with Leistritz Extrusionstechnik GmbH representing precision twin-screw specialization. These entities anchor European premium positioning through digital twin platforms and co-rotating screw R&D. Davis-Standard LLC exemplifies North American aftermarket-focused positioning, while The Japan Steel Works, Ltd. and Kabra Extrusiontechnik Ltd. represent Asia-Pacific manufacturing scale. Each occupies a distinct tier within the competitive structure without overlapping strategic positioning.
| Leading Market Players |
|---|
| KraussMaffei |
| Coperion |
| Leistritz Extrusionstechnik |
| Bausano |
| Reifenhäuser Group |
| Davis-Standard |
| The Japan Steel Works |
| Kabra Extrusiontechnik |
| Milacron |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FDA-validated medical lines and commodity film equipment manifests in both pricing premiums and supply chain fragmentation, with REACH-compliant European configurations commanding 40-60% hardware margins against Chinese single-screw units while sourcing precision gear pumps exclusively from Baden-Württemberg.
Pricing Analysis
Distributor margins absorb 15-25% of equipment value in European medical tubing channels, compressing to 8-12% for direct OEM procurement of standard film lines. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and after-sales bundling intensity, with servo motor configurations in Germany facing cost compression from neodymium magnet volatility. Mid-cap packaging converters in the US Midwest exhibit highest price sensitivity, while Japanese medical device fabricators prioritize validation documentation over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Suzhou, and Chicago anchor hub-and-spoke patterns for aftermarket parts logistics, with critical components drawing from German gearbox specialists, Chinese rare earth processing centers, and Indian assembly partnerships. Precision screw manufacturing rests on Baden-Württemberg engineering houses, while servo motor windings source from Chinese copper smelters. Single-source vulnerability concentrates in medical-grade gear pump supply. Distribution runs through authorized service networks for validated equipment and direct OEM relationships for commodity lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment procurement arbitrage opportunities concentrate where REACH-mandated upgrade costs in Germany diverge from PLI-subsidized greenfield economics in India, enabling margin capture through geographic manufacturing footprint optimization.
For Market Incumbents: Anticipate margin compression in commodity single-screw segments by anchoring long-term service contracts through predictive maintenance platforms, while defending premium positioning via FDA validation documentation and digital twin integration. Capacity consolidation in Baden-Württemberg precision manufacturing reinforces supply security for medical tubing lines.
For New Entrants and Emerging Players: Regional assembly partnerships in Gujarat and Maharashtra offer the most penetrable entry vector, targeting mid-cap Indian film producers under PLI scheme coverage with localized servo motor drive configurations. Aftermarket parts logistics unbundling creates white-space for diagnostics-only service tiers.
For Investors and Strategic Acquirers: Consolidation pressure builds where predictive maintenance software capabilities fragment across regional equipment vendors, favoring platforms with integrated digital twin architectures. Acquisition targets cluster among precision twin-screw specialists with documented REACH compliance and established medical validation pathways. Monitor biopolymer compounding capacity announcements as inflection signal for reactive processing equipment demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gear Pump Manufacturing | Reduces single-source dependency on Baden-Württemberg suppliers for medical tubing lines. |
| Predictive Maintenance Platform Launch | Enables subscription revenue anchoring at KraussMaffei and Coperion European installations. |
| Local Assembly Partnership in India | Captures PLI scheme benefits while reducing landed cost for Gujarat packaging producers. |
| Biopolymer Compounding Capacity Expansion | Addresses PLA and PHA reactive processing demand from German REACH-mandated compounders. |
| FDA Validation Documentation Investment | Creates compliance barrier for non-certified imports into US medical tubing segments. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and technical R&D directors at compounding facilities. Secondary validation draws from MIIT industrial upgrading directives, ECHA emissions filings, FDA 510(k) equipment validations, and SEC 10-K disclosures from listed machinery vendors. Cross-referencing customs data on extruder imports with regional production capacity surveys enables triangulation between shipment volumes and installed base estimates.
Historical trendline analysis across screw configuration adoption, drive technology replacement cycles, and regional regulatory implementation timelines informs projection mechanics. Segmentation dimensions span product type, technology tier, application complexity, and end-user industry vertical. CAGRs derive from curve-fitting equipment replacement patterns against polymer demand forecasts and energy efficiency mandate phase-in schedules. Specific inputs include neodymium magnet price indices, REACH compliance cost surveys, and PLI scheme disbursement trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biopolymer adoption rates, rare earth supply disruptions, and recycling mandate enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Volumetric Filling Machines Market
Packaging Machinery
Global Volumetric Cup Fillers Market
Packaging Machinery
Meter-Mix Dispensing Machine Market
Packaging Machinery
Thermal Film Laminating Machines Market
Packaging Machinery
Orbital Wrapping Machine Market
Packaging Machinery
North America Printing Machinery Market
Packaging Machinery
Lidding Machines Market
Packaging Machinery
Side Load Case Packing Machines Market
Packaging Machinery
Case Packaging Machinery Market
Packaging Machinery
Packaging Conveyors Market
Packaging Machinery
Screw Capping Machines Market
Packaging Machinery
Sack Fillers Market
Packaging Machinery
Bag in Box Packaging Machine Market
Packaging Machinery
Stacking Machine Market
Packaging Machinery
Volumetric Boom Filling Machine Market
Packaging Machinery
Extrusion Press Market