
 Capsule Filling Machines Market | 2026-2036
Capsule Filling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Capsule Filling Machines Market Analysis
The split between fully automatic and semi-automatic capsule filling tiers is repositioning how vendors allocate engineering resources, with high-speed rotary systems commanding premium pricing while manual units face margin compression. ACG Worldwide leverages integrated capsule and machine portfolios to anchor its position across emerging Asian pharmaceutical hubs. Harro Hofliger sustains dominance in isolator-integrated containment systems for potent compound handling. Syntegon competes through modular platform architectures that reduce changeover downtime for contract manufacturers.
Capsule filling machines are precision dosing systems engineered to dispense powders, pellets, or liquids into empty gelatin or vegetable-derived shells at rates exceeding 200,000 units per hour, with weight variation tolerances typically held within ±5 percent to ensure pharmacopeial compliance. Fully automatic rotary systems lead installed capacity across commercial pharmaceutical operations, while isolator-integrated configurations represent the fastest-growing technology segment as containment requirements tighten for high-potency APIs. Manual and semi-automatic equipment retains stable demand in research laboratories and early-stage clinical manufacturing where batch flexibility outweighs throughput economics.
FDA cGMP regulations and EU MDR conformity requirements shape equipment validation protocols, forcing manufacturers to document continuous process verification and electronic batch records. The EPA and OSHA frameworks in the United States impose containment standards for operator exposure to active pharmaceutical ingredients, directly influencing isolator adoption rates. Stakeholders must weigh total cost of ownership against regulatory audit readiness when selecting between established European suppliers and emerging Asian equipment platforms.
Market Dynamics
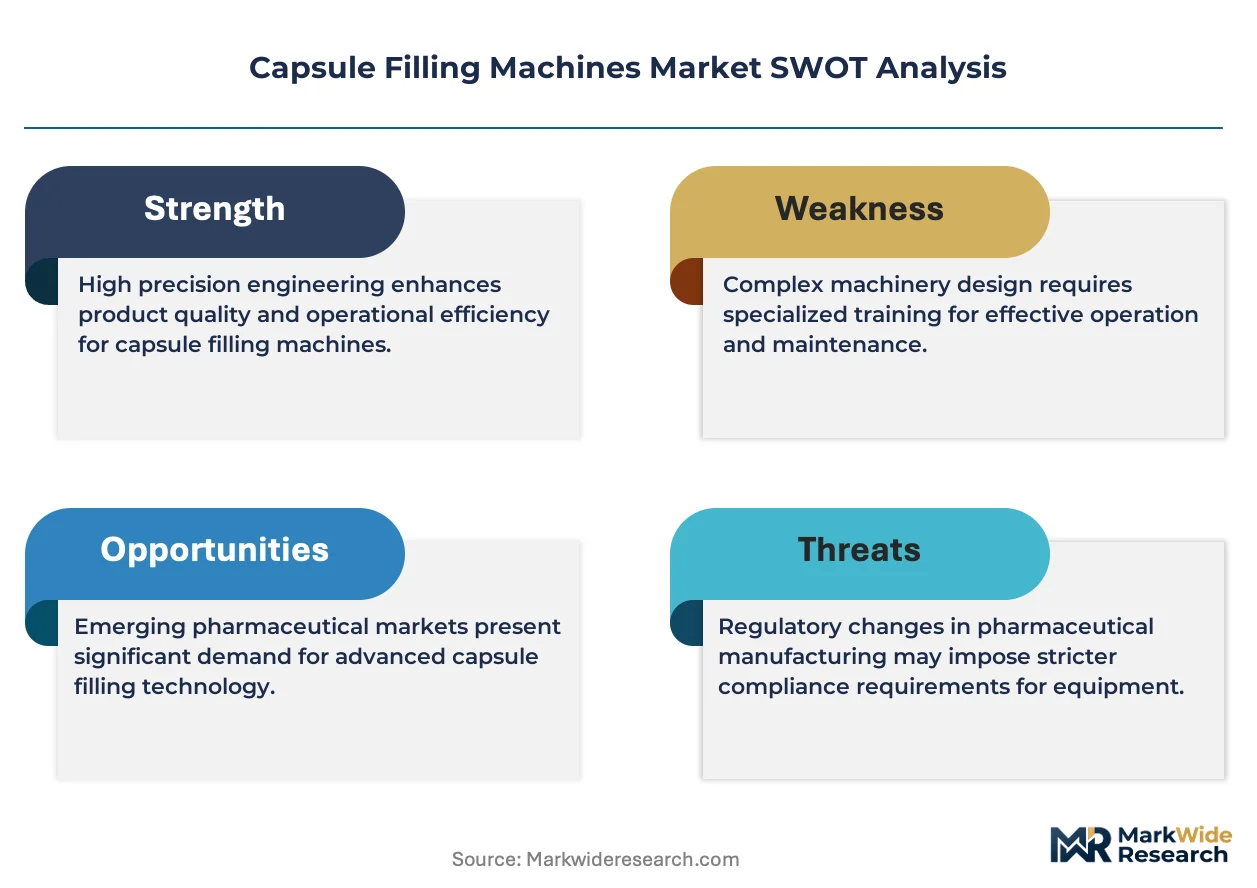
Rotary isolator integration is compressing equipment replacement cycles as pharmaceutical manufacturers confront tighter containment mandates for high-potency active pharmaceutical ingredients.
Growth Catalysts
- EU MDR conformity requirements:Medical device regulations are accelerating validation documentation investments and forcing equipment upgrades across European contract manufacturing organizations.
- Oral solid dosage expansion:Pharmaceutical companies are scaling capsule production capacity to serve rising demand for patient-compliant drug delivery formats in chronic disease therapies.
- Frankfurt-Leverkusen manufacturing cluster:German contract manufacturers are aggregating pan-European supply chain demand and driving concentrated procurement of high-speed filling systems.
Market Restraints
- Stainless steel and precision component volatility:Input cost fluctuations for pharmaceutical-grade alloys and servo-drive systems are compressing vendor margins and extending quote validity periods.
- European supplier concentration:Critical isolator and containment subsystem sourcing remains concentrated among German and Swiss specialists, creating procurement bottlenecks during capacity expansions.
- Changeover complexity:Multi-product facilities face technical limitations in rapid format switching between powder, pellet, and liquid dosing configurations without extended downtime.
Strategic Opportunities
- India CDMO infrastructure buildout:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are underinvested in isolator-integrated systems and represent greenfield installation demand.
- Continuous manufacturing convergence:Real-time release testing and process analytical technology integration with capsule filling lines is enabling quality-by-design adoption.
- US EPA containment mandates:Operator exposure limit regulations for potent compounds are creating regulatory tailwinds for isolator retrofit and replacement programs.
Industry Challenges
- Mechatronics and pharmaceutical engineering skill scarcity:The intersection of precision dosing mechanics, isolator containment physics, and cGMP compliance requires specialized talent pools that remain shallow.
- IQ/OQ/PQ validation timelines:Installation qualification, operational qualification, and performance qualification protocols for FDA-regulated facilities extend project durations and delay revenue recognition.
- Legacy SCADA integration:Brownfield facilities face execution friction connecting modern rotary systems to existing supervisory control architectures without full line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capsule Filling Machines Market |
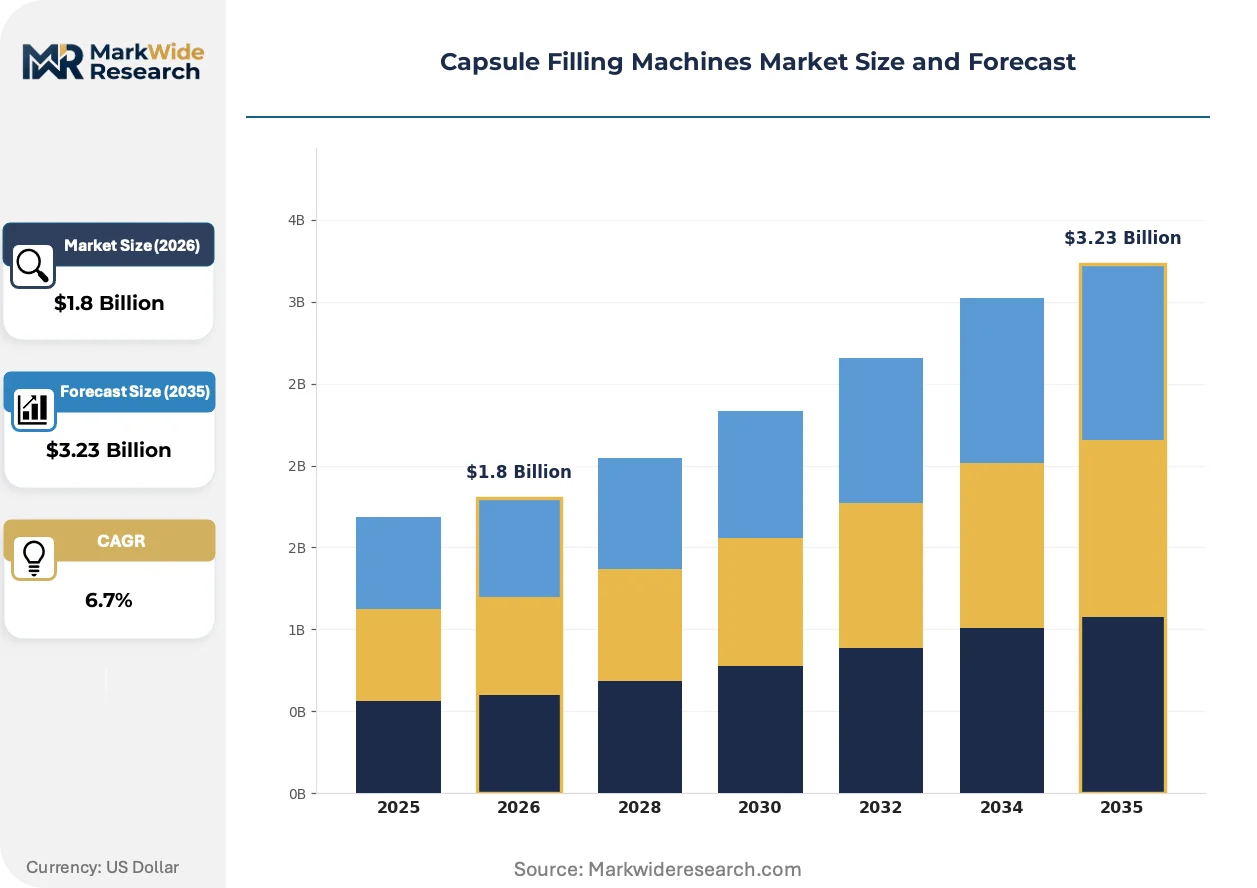
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Automatic, Fully Automatic, Manual, Isolator End User: Pharmaceutical Companies, Nutraceutical Companies, Contract Manufacturers, Research Laboratories Technology: Rotary, Inline, Auger, Volumetric Application: Hard Capsules, Soft Capsules, Gelatin Capsules, Vegetarian Capsules |
| Companies Covered | ACG Worldwide, Harro Hofliger, IMA Group, Sejong Pharmatech, Schaefer Technologies, Syntegon, Qualicaps, China Canaan, MG2, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capsule Filling Machines Market Emerging Trajectories
Equipment architectures are converging around modular platforms that compress changeover intervals and enable flexible batch sizing for contract manufacturers serving fragmented drug pipelines.
Single-use containment technologies are unifying product contact surfaces with disposable polymer barriers that eliminate cross-contamination risks between potent and non-potent compounds. Multi-product facilities in North America are adopting these systems at accelerated pace to avoid dedicated line capital expenditure. This unification is compressing the economic threshold for isolator investment and displacing traditional stainless steel hard-wall configurations in mid-scale operations.
REACH substance restrictions and the EU Green Deal chemical sustainability frameworks are forcing reformulation of lubricants, sealants, and cleaning agents used in pharmaceutical equipment maintenance. Industrial consequence includes accelerated supplier qualification cycles for compliant consumables and documentation burden for existing installed base. High-speed rotary manufacturers serving European markets are responding with pre-validated material compatibility packages.
After-sales service unbundling is fragmenting traditional full-service contracts into discrete modules for spare parts, remote diagnostics, and on-site technical support. Contract manufacturers are selecting à la carte service tiers based on internal maintenance capabilities and equipment criticality ratings. This pattern is most visible in German pharmaceutical clusters where procurement functions have matured total cost of ownership modeling.
Capsule Filling Machines Market Segmentation
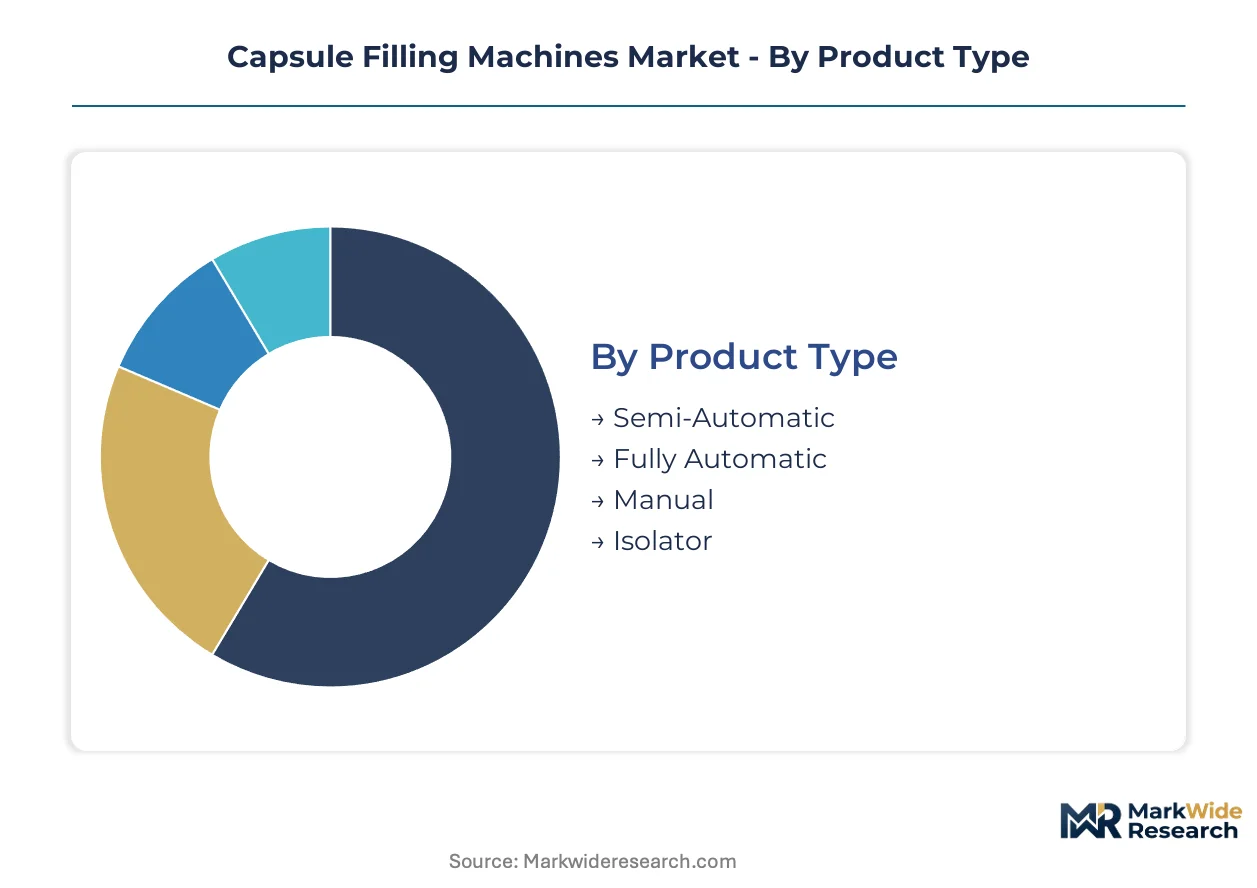
Capsule filling machine procurement decisions hinge on containment requirements, throughput economics, and validation complexity. Each segment carries distinct certification burdens and total cost of ownership profiles that reshape vendor selection criteria across pharmaceutical manufacturing networks.
Product Type:
FDA cGMP and EU MDR documentation intensity varies sharply across automation tiers, with fully automatic rotary systems demanding exhaustive IQ/OQ/PQ protocols while manual units face lighter regulatory scrutiny.
- Fully Automatic:Rotary turret architectures achieve throughput exceeding 200,000 capsules per hour with weight variation held within ±5 percent. German contract manufacturers around Leverkusen and Frankfurt concentrate procurement here to serve pan-European pharmaceutical supply chains under EMA oversight.
- Isolator:Integrated containment systems with HEPA-filtered unidirectional airflow and glove port access protect operators from high-potency APIs. Demand concentrates in North American facilities confronting EPA occupational exposure mandates for cytotoxic compounds.
- Semi-Automatic:Benchtop units bridge clinical and commercial manufacturing with changeover flexibility.
- Manual:Hand-operated systems serve research laboratories with minimal validation overhead.
Fully automatic systems sit at the top of the volume ranking, with isolator configurations climbing the fastest as containment regulations tighten.
End User:
Capital deployment cycles and equipment utilization rates diverge dramatically between integrated pharmaceutical manufacturers and outsourced service providers.
- Contract Manufacturers:Multi-product facilities prioritize modular platforms with compressed changeover intervals to maximize asset turns across fragmented client pipelines. Indian CDMOs in Hyderabad and Ahmedabad represent concentrated greenfield demand for isolator-integrated lines.
- Pharmaceutical Companies:Captive manufacturing operations favor dedicated high-speed lines with electronic batch record integration for FDA-regulated commercial supply. North American and European integrated firms drive replacement cycles as cGMP guidelines evolve.
- Nutraceutical Companies:Dietary supplement producers seek mid-tier automation with reduced validation documentation.
- Research Laboratories:Early-stage development sites require batch flexibility over throughput economics.
Contract manufacturers command the largest installed base expansion, with research laboratories posting the steepest growth trajectory in absolute unit terms.
Technology:
Precision dosing mechanics determine which pharmacopeial standards each platform can satisfy, with rotary and auger systems dominating commercial pharmaceutical applications.
- Rotary:Turret-based indexing with multiple dosing stations enables simultaneous powder, pellet, and liquid filling. This architecture anchors commercial pharmaceutical operations seeking continuous process verification under FDA cGMP.
- Auger:Screw-feed mechanisms excel with cohesive powders and granules that challenge gravity-fed systems. Nutraceutical applications in the United States leverage auger technology for mineral and botanical formulations.
- Inline:Linear transport systems suit lower-volume production with simplified mechanical complexity.
- Volumetric:Cup-and-piston dosing serves soft capsule liquid fills with viscosity-tolerant accuracy.
Rotary technology dominates current capacity, while auger systems gain share fastest in specialty dosage niches.
Application:
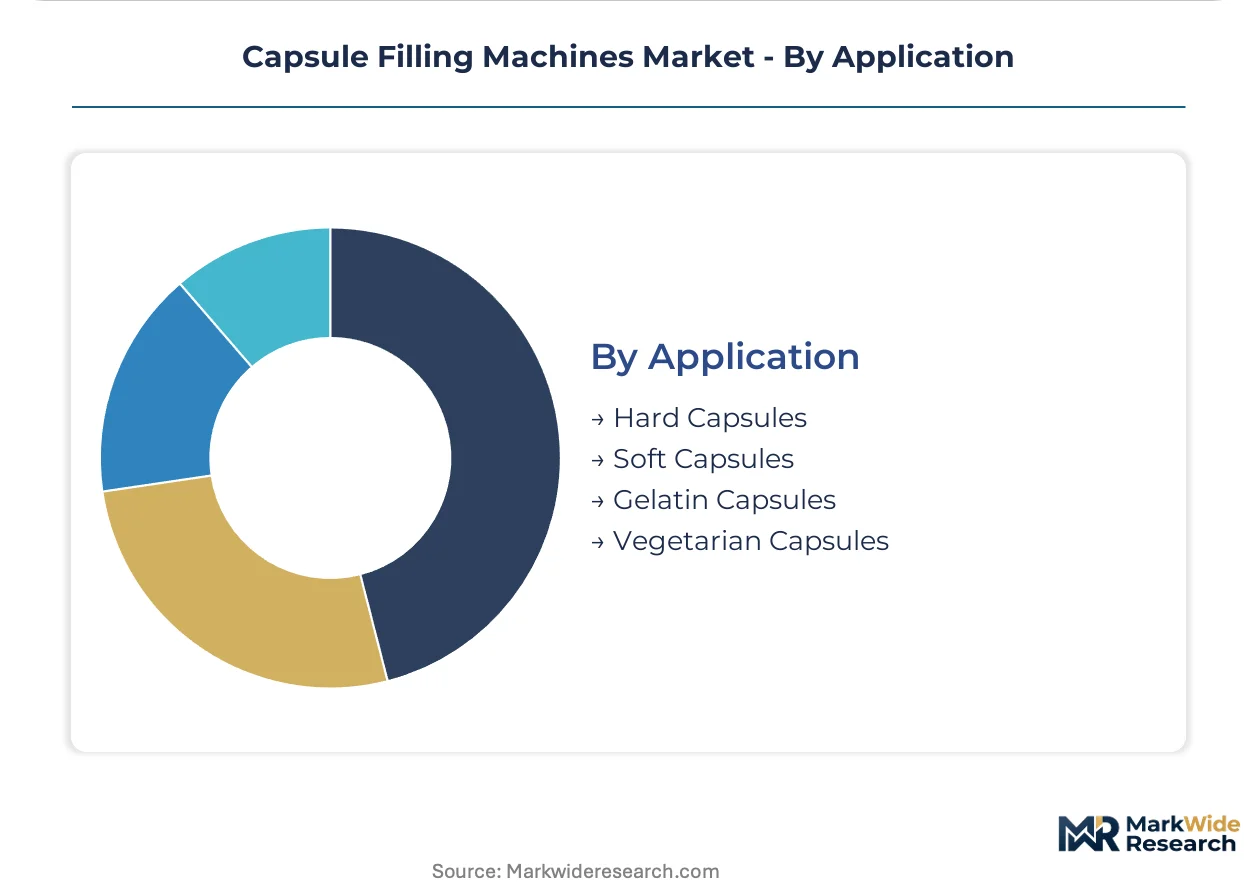
Shell material selection triggers distinct supply chain and regulatory pathways, with gelatin and vegetarian capsules following separate qualification protocols.
- Hard Capsules:Two-piece gelatin or HPMC shells accommodate powders, pellets, and multiparticulates with tamper-evident sealing. Oral solid dosage expansion for chronic disease therapies in Germany and the United States concentrates demand here.
- Vegetarian Capsules:HPMC and pullulan alternatives address religious dietary restrictions and bovine spongiform encephalopathy concerns. European markets under EFSA oversight show accelerating preference as clean-label positioning intensifies.
- Soft Capsules:Rotary die encapsulation of liquids and semi-solids serves lipid-based formulations.
- Gelatin Capsules:Traditional bovine and porcine-derived shells retain cost advantages in emerging markets.
Hard capsules hold the volume leadership position, with vegetarian alternatives expanding most quickly on sustainability positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates more isolator-integrated capacity than any other European state, while India accelerates greenfield installations at double the pace of mature Western markets.
United States
EPA occupational exposure mandates for high-potency APIs drive isolator retrofit programs across commercial pharmaceutical facilities. FDA cGMP guidelines for continuous process verification shape equipment validation protocols. New Jersey and Massachusetts pharmaceutical clusters anchor replacement demand for rotary systems with electronic batch record integration.
Germany
Contract manufacturers around Frankfurt and Leverkusen aggregate pan-European supply chain demand for high-speed filling systems. EU MDR conformity requirements accelerate documentation investments and equipment upgrades. Bavaria-based pharmaceutical engineering specialists concentrate containment subsystem supply for regional OEMs.
India
Hyderabad and Ahmedabad CDMOs underinvest in isolator-integrated lines and represent concentrated greenfield installation demand. CDSCO pharmaceutical manufacturing regulations tighten equipment qualification standards for export-oriented facilities. Gujarat's specialty chemical-pharma corridor attracts machinery procurement for integrated oral solid dosage expansion.
China
NMPA pharmaceutical equipment registration rules reshape import substitution strategies for domestic machinery platforms. Yangtze River Delta pharmaceutical manufacturers scale capsule production for chronic disease therapies. Shanghai-Zhangjiang biopharma cluster drives demand for modular platforms with compressed changeover intervals.
Switzerland
Swissmedic oversight of high-potency compound manufacturing elevates containment specification requirements for precision dosing systems. Basel-centered pharmaceutical operations prioritize isolator-integrated configurations for cytotoxic API handling. Swiss precision engineering specialists supply critical servo-drive and dosing station components to regional OEMs.
Capsule Filling Machines Market Vendor Landscape
Top-tier vendors anchor premium-tier isolator and high-speed rotary segments, while mid-scale fabricators compete on modular platform flexibility and regional service proximity. The vendor base stratifies across three archetypes: integrated pharmaceutical equipment conglomerates, precision containment specialists, and emerging Asian machinery platforms. Competitive positioning hinges on M&A activity consolidating dosing technology IP and strategic partnerships bridging Western containment expertise with Asian manufacturing scale.
Within the integrated conglomerate tier, ACG Worldwide and IMA Group exemplify portfolio breadth spanning capsule supply and precision filling machinery. Syntegon occupies a position among German-engineered platform specialists emphasizing modular architectures. Harro Hofliger anchors the containment specialist archetype with isolator-integrated system expertise. Sejong Pharmatech represents Korean precision machinery capabilities, while China Canaan sits within the emerging Asian equipment platform segment serving cost-sensitive procurement in domestic and export markets.
| Leading Market Players |
|---|
| ACG Worldwide |
| Harro Hofliger |
| IMA Group |
| Sejong Pharmatech |
| Schaefer Technologies |
| Syntegon |
| Qualicaps |
| China Canaan |
| MG2 |
| Others |
Supply Flow & Price Mechanics
German contract manufacturers around Frankfurt and Leverkusen command disproportionate pricing leverage through concentrated procurement of isolator-integrated rotary systems, compressing quote validity periods as stainless steel and precision servo-drive costs fluctuate. Equipment vendors respond with unbundled service architectures that separate hardware, validation documentation, and aftermarket support into discrete purchase decisions.
Pricing Analysis
Unbundled service contracts are displacing traditional full-service agreements as contract manufacturers in Germany select à la carte tiers based on internal maintenance capabilities. Three-tier pricing structure across premium isolator-integrated, standard rotary, and economy manual configurations reflects certification grade and containment specification rather than throughput alone. Cost compression in mid-tier rotary systems is intensifying because Indian and Korean equipment platforms compete on modular flexibility. Research laboratories exhibit highest price sensitivity due to minimal validation overhead requirements, while North American pharmaceutical companies confronting EPA exposure mandates absorb premium isolator pricing without volume negotiation.
Supply Chain Analysis
Direct-to-OEM channels handle demand from integrated pharmaceutical manufacturers, while regional distributors serve mid-scale contract manufacturers requiring localized technical support. Critical containment subsystems draw from German and Swiss precision engineering specialists, with servo-drive components sourcing from Japan and South Korea. Pharmaceutical-grade stainless steel and HEPA filtration media hinge on mill capacity concentrated in Germany, Austria, and Japan. Single-source vulnerability in isolator glove port and HEPA filter supply creates procurement bottlenecks during capacity expansion cycles. Distribution runs through OEM direct sales for large rotary systems and specialized pharmaceutical equipment distributors for semi-automatic and manual tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The capsule filling machines market represents a late-cycle quality story as regulatory containment mandates for high-potency APIs shift procurement toward isolator-integrated configurations with exhaustive validation documentation. This specification escalation favors vendors with integrated containment expertise over pure-play machinery fabricators.
For Market Incumbents: Cement isolator technology leadership through backward integration into HEPA filtration and glove port subsystems, reducing dependency on Swiss and German component specialists. Expand captive service networks in Hyderabad and Ahmedabad to capture Indian CDMO greenfield demand before Korean and domestic Chinese platforms establish local presence. Prioritize CDSCO and NMPA pre-certification investments to accelerate regulatory approval pathways for export-oriented Asian facilities.
For New Entrants and Emerging Players: The price-point gap between premium European isolator systems and economy Asian manual equipment creates white-space opportunity for mid-tier modular rotary platforms with compressed changeover intervals. Target underinvested Indian CDMO infrastructure in Gujarat's specialty chemical-pharma corridor, where isolator-integrated capacity remains below Western penetration rates. Pursue partnership-based go-to-market models with regional pharmaceutical engineering consultants who influence procurement specifications for first-time buyers.
For Investors and Strategic Acquirers: Pharmaceutical equipment conglomerates seeking dosing technology IP are the most active acquirer in this space, consolidating containment and precision mechanics capabilities under unified platforms. Five-to-ten year viability hinges on regulatory tailwinds for isolator retrofit programs and continuous manufacturing convergence. Monitor EPA enforcement intensity for occupational exposure limits as the primary inflection indicator for North American replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Retrofit Program | EPA enforcement of operator exposure limits accelerates containment upgrades across US commercial facilities. |
| Modular Platform Architecture | Syntegon-style changeover compression enables contract manufacturers to maximize asset turns across fragmented pipelines. |
| CDSCO Pre-Certification Investment | Early qualification for Indian export-oriented facilities captures Hyderabad-Ahmedabad greenfield installation demand. |
| Backward Integration into Containment Subsystems | In-house HEPA and glove port production reduces Swiss-German supplier concentration risk. |
| Continuous Manufacturing Convergence | PAT integration with rotary lines enables real-time release testing under FDA cGMP quality-by-design frameworks. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with pharmaceutical equipment procurement managers, plant engineers at contract manufacturing organizations, regulatory affairs specialists, and aftermarket service directors with secondary validation. FDA 483 inspection observations, EMA manufacturing authorization records, CDSCO equipment registration filings, and SEC 10-K disclosures from listed pharmaceutical equipment vendors provided foundational data. Bottom-up capacity estimates from identified installed base inventories were triangulated against top-down demand projections derived from oral solid dosage expansion announcements.
Segment-weighting approaches applied differential growth assumptions across automation tiers, containment integration levels, and end-user archetypes throughout the forecast period. The analytical framework modeled technology adoption curves for isolator-integrated configurations separately from standard rotary and manual equipment replacement cycles. CAGRs were derived from regression analysis of historical procurement patterns against regulatory milestone timelines. Industry-specific inputs included EPA enforcement intensity indices for occupational exposure limits and EMA manufacturing authorization expansion rates for high-potency compound handling.
Caveats apply where EPA enforcement relaxation, EU MDR implementation delays, or stainless steel commodity volatility could materially shift the outlook. Forecasts reflect assumptions about regulatory trajectory continuity and pharmaceutical capital expenditure commitment levels. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Automatic Filling Machine Market
Packaging Machinery
Automatic Thermoforming Vacuum Machine Market
Packaging Machinery
Vial Filling and Capping Machines Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Tissue Paper Embosser Machine Market
Packaging Machinery
Asia-Pacific Pharmaceutical Packaging Machinery Market
Packaging Machinery
Plastic Blow Molding Machine Market
Packaging Machinery
Product Dispensing Machinery Market
Packaging Machinery
Case Packing Machines Market
Packaging Machinery
Binding & Lamination Machines Market
Packaging Machinery
Medicine Decoction and Packing Machines Market
Packaging Machinery
Global Volumetric Cup Fillers Market
Packaging Machinery
Barcode Labeller Machine Market
Packaging Machinery
Vertical Strapping Machines Market
Packaging Machinery
Pre-Made Pouch Packaging Machines Market
Packaging Machinery
Multi-Head Filling Machines Market