
 Global Vitamin Ingredients Market | 2026-2036
Global Vitamin Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vitamin Ingredients Market Foresight
Functional food producers is redrawing procurement priorities across the vitamin ingredients value chain, pulling volume away from traditional supplement channels toward fortified beverages and fortified dairy. Koninklijke DSM N.V. leverages its biotechnology platforms to sustain long-term supply contracts with major food brands. BASF SE anchors its position through backward integration into petrochemical precursors for synthetic vitamin production. Lonza Group specializes in fermentation-derived vitamin B complexes for pharmaceutical-grade applications.
Vitamin ingredients comprise isolated or synthesized organic compounds essential for metabolic functions, typically produced through chemical synthesis, microbial fermentation, or extraction from natural biomass, with purity grades ranging from feed-grade to United States Pharmacopeia-certified pharmaceutical grade. The Vitamin B Complex category dominates volume due to its essential role in energy metabolism and widespread fortification mandates, while Vitamin D registers accelerated demand from pharmaceutical firms developing prescription-strength deficiency treatments. Dietary Supplements retains the largest revenue pool, though Functional Foods captures expanding margin as beverage brands seek differentiated fortification claims.
The FDA's Current Good Manufacturing Practice regulations and the EMA's quality guidelines for active pharmaceutical ingredients enforce batch-level traceability and potency verification across vitamin supply chains. China's NMPA and SAMR impose GB standard compliance on imported vitamin concentrates, creating market access barriers for uncertified suppliers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP standards to avoid formulation reformulation costs and regulatory delays.
Market Dynamics
Pharmaceutical-grade purity mandates are compressing supplier margins while concentrating procurement among fermentation specialists with captive quality infrastructure. The shift from feed-grade to USP-certified vitamin concentrates is forcing capital redeployment across European and Asian production bases.
Growth Catalysts
- FDA cGMP traceability mandates:Batch-level serialization requirements are locking in long-term supply contracts with verified fermentation houses capable of pharmaceutical-grade documentation.
- Fortified beverage formulations:Functional drink brands are diverting volume from traditional supplement channels toward differentiated vitamin water and dairy fortification applications.
- China's GB standard harmonization:Import purity thresholds for vitamin concentrates are filtering uncertified suppliers and consolidating market access among pre-qualified producers.
Market Restraints
- Petrochemical precursor volatility:Synthetic vitamin production depends on acetone and acetic anhydride feedstocks subject to energy-price transmission.
- Fermentation capacity concentration:Large-scale vitamin B complex facilities cluster in Germany and China, creating geographic single-point vulnerability.
- Natural extraction yield ceilings:Plant-derived vitamin E and carotenoid production faces biomass availability constraints that chemical synthesis bypasses.
Strategic Opportunities
- India's PLI scheme for fermentation:Contract manufacturing incentives are attracting pharmaceutical-grade vitamin investment away from legacy European bases.
- Precision fermentation platforms:Cell-culture vitamin production converges with synthetic biology to enable rare vitamin analog synthesis at commercial scale.
- Direct-to-brand distribution:Ingredient suppliers are bypassing traditional distributors to capture margin through dedicated technical service relationships with food multinationals.
Industry Challenges
- Pharmacopeial harmonization timelines:Divergent USP, EP, and ChP potency verification methods force redundant testing and reformulation cycles.
- Clean-label certification complexity:Non-GMO, organic, and allergen-free vitamin claims require parallel supply chain segregation and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vitamin Ingredients Market |
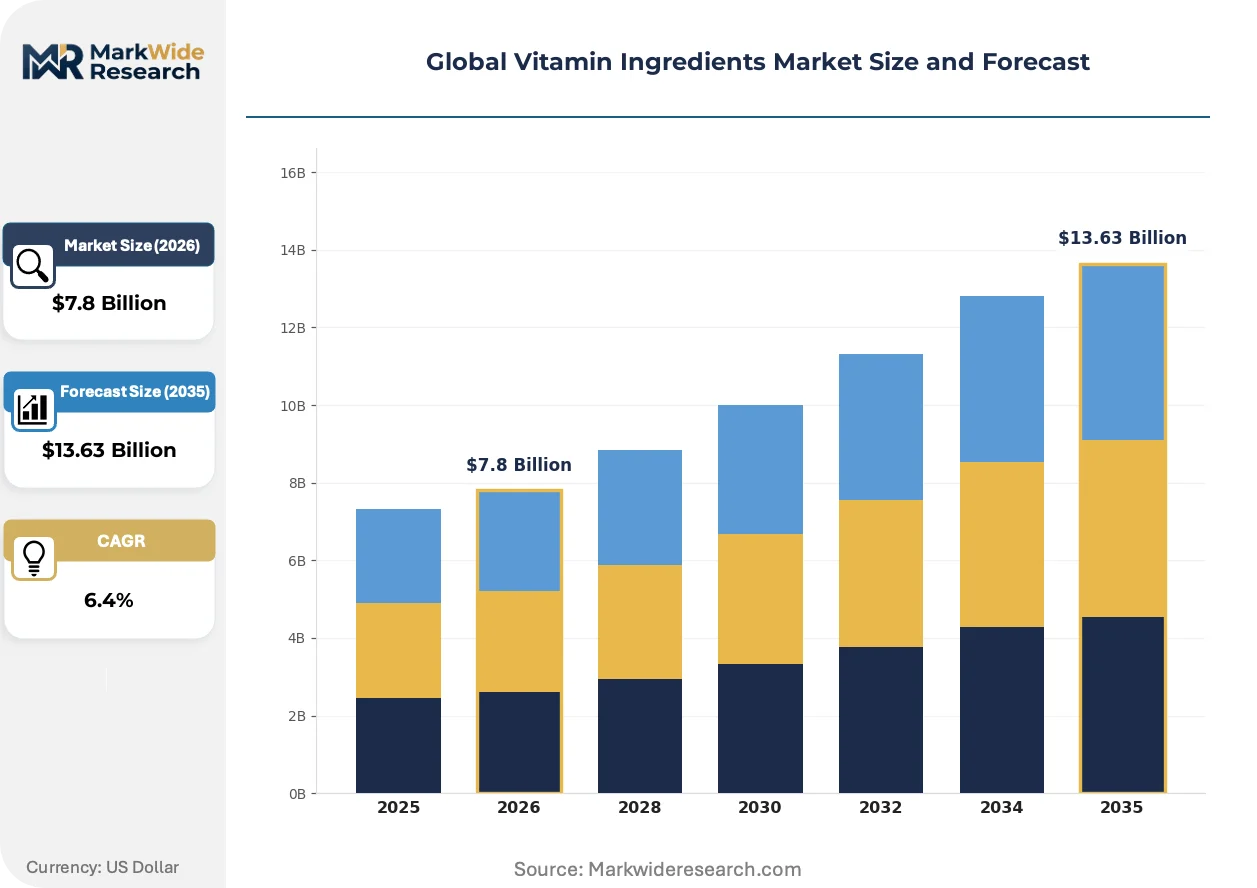
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Vitamin A, Vitamin B Complex, Vitamin C, Vitamin D, Vitamin E, Vitamin K Form: Powder, Liquid, Tablet, Capsule, Soft Gel, Granules Application: Dietary Supplements, Functional Foods, Animal Nutrition, Personal Care, Pharmaceuticals, Infant Nutrition End User: Supplement Manufacturers, Food & Beverage Producers, Cosmetic Companies, Pharmaceutical Firms, Animal Feed Companies, Infant Formula Makers |
| Companies Covered | BASF SE, Koninklijke DSM N.V., Glanbia Plc, Lonza Group, Archer Daniels Midland Company, Bluestar Adisseo Company, Abbott Laboratories, Nestlé S.A., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vitamin Ingredients Market Shifts & Advancements
Continuous processing technology and modular bioreactor designs are shortening vitamin production campaign cycles. Quality-by-design protocols are replacing end-point testing with real-time analytical control.
Precision fermentation for vitamin B12 and K2 is fragmenting the historical synthetic-versus-natural dichotomy. Nutraceutical brands in Germany and Switzerland are adopting these bioidentical formats for premium positioning. The technology is fragmenting procurement patterns as buyers split volumes across chemical, fermentation, and cell-culture sources rather than single-origin commitments.
REACH authorization requirements for vitamin synthesis intermediates are tightening substance volume tracking across EU manufacturing sites. ECHA's updated guidance on chemical safety assessment is extending documentation burdens to vitamin precursors previously exempt. Pharmaceutical-grade vitamin producers are responding by consolidating precursor production in-house to control substance flow data.
Brand-direct technical partnerships are displacing distributor-mediated ingredient sourcing for mid-scale functional food manufacturers. Large beverage and dairy processors are embedding vitamin technologists within their innovation teams to accelerate fortification claim development. This pattern is most visible in the Netherlands and Denmark, where cooperative dairy giants operate centralized ingredient specification functions.
Global Vitamin Ingredients Market Segmentation
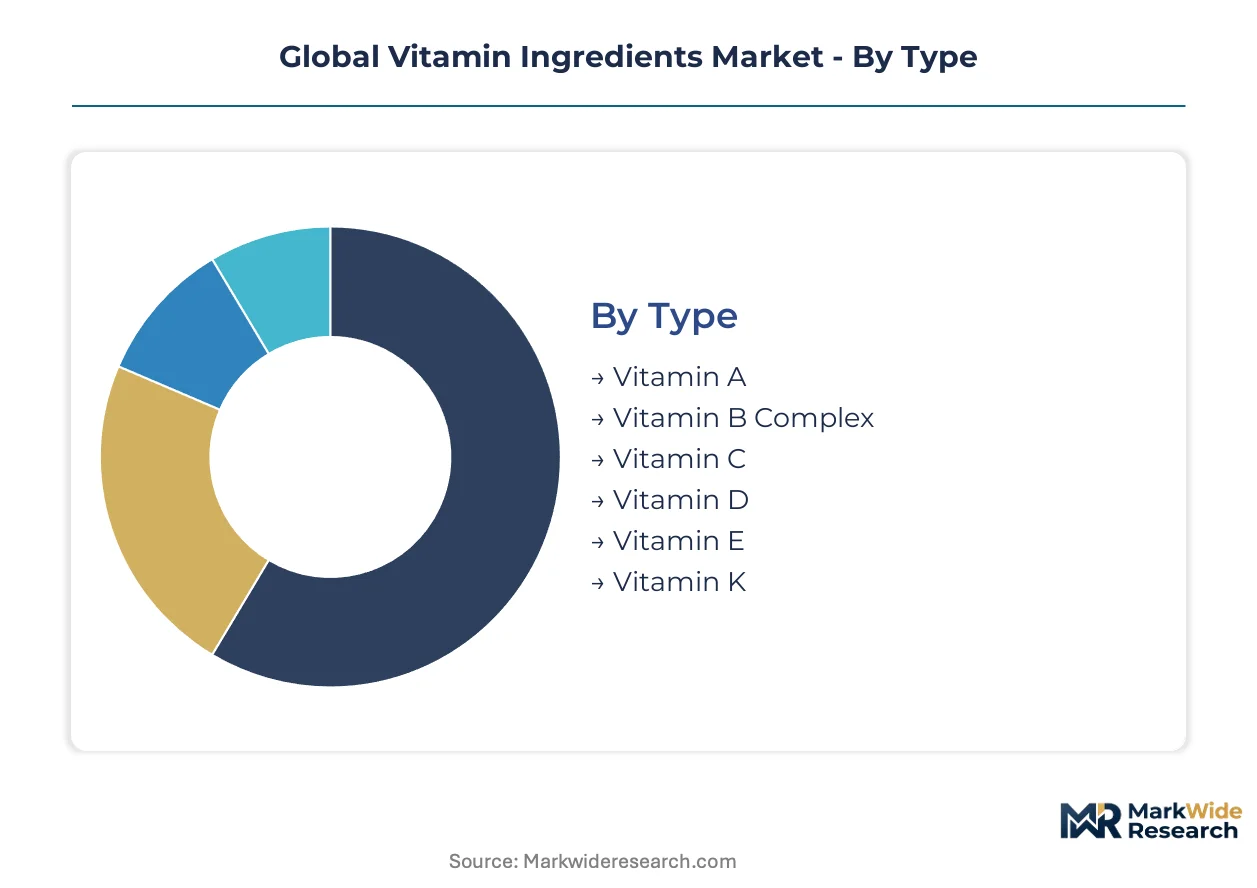
Vitamin ingredient procurement splits across purity grades, delivery formats, and end-use specifications that dictate fermentation scale and documentation burden. Segmentation clarity enables suppliers to align capacity investments with the divergent margin profiles of pharmaceutical versus feed-grade demand.
Type:
Synthetic chemistry and microbial fermentation face divergent substitution pressures as precision cell-culture methods encroach on traditional production routes.
- Vitamin B Complex:Water-soluble compounds including thiamine, riboflavin, niacin, and cobalamin produced predominantly through bacterial fermentation. DSM and BASF operate large-scale facilities in Germany serving European nutraceutical and pharmaceutical customers with USP-certified grades.
- Vitamin D:Ergocalciferol and cholecalciferol forms experiencing accelerated demand from pharmaceutical firms developing prescription-strength deficiency treatments. China's NMPA tightening of import purity thresholds is filtering uncertified suppliers from this high-margin segment.
- Vitamin A:Retinol and beta-carotene variants synthesized from petrochemical precursors with acetone feedstock exposure.
- Vitamin C:Ascorbic acid produced through the Reichstein-Grüssner process or two-step fermentation, facing price pressure from Chinese capacity concentration.
- Vitamin E:Tocopherol and tocotrienol compounds split between synthetic petrochemical routes and natural extraction from vegetable oils with yield constraints.
- Vitamin K:Phylloquinone and menaquinone forms where precision fermentation is fragmenting historical synthetic-versus-natural procurement patterns.
Vitamin B Complex anchors the volume base while Vitamin D gains share at the steepest rate.
Form:
Processing intensity and stability requirements divide manufacturing economics between bulk intermediates and finished dosage-ready formats.
- Powder:Crystalline or spray-dried vitamin concentrates serving as the foundational input for tablet compression, capsule filling, and food fortification. Powder specifications dominate pharmaceutical-grade procurement due to batch-level potency verification and extended stability under cGMP documentation.
- Liquid:Oil-soluble or emulsified vitamin solutions enabling uniform dispersion in beverage matrices and soft gel encapsulation. Functional drink brands in the Netherlands and Denmark are diverting procurement toward liquid formats for differentiated vitamin water applications.
- Tablet:Direct-compression or granulated vitamin formulations requiring excipient compatibility and dissolution profile optimization.
- Capsule:Hard-shell gelatin or HPMC encapsulation for powdered vitamin blends with taste-masking requirements.
- Soft Gel:Gelatin-based liquid fill formats for oil-soluble vitamins with bioavailability enhancement claims.
- Granules:Agglomerated particles for sachet applications and direct-to-mouth dispersible formats in infant nutrition.
Powder commands the largest production volume while Liquid formats climb fastest on functional beverage demand.
Application:
Regulatory stringency and margin structure separate pharmaceutical-grade channels from feed-grade commodity flows.
- Dietary Supplements:Capsule, tablet, and soft gel finished products retaining the largest revenue pool despite volume diversion toward food channels. FDA cGMP traceability mandates are locking in long-term supply contracts with verified fermentation houses capable of pharmaceutical-grade documentation.
- Functional Foods:Fortified beverages, dairy, and bakery applications capturing expanding margin as beverage brands seek differentiated fortification claims. EFSA health claim authorization requirements in Europe create formulation barriers that technical partnerships with ingredient suppliers help navigate.
- Pharmaceuticals:Prescription-grade vitamin formulations subject to EMA quality guidelines for active pharmaceutical ingredients and USP potency verification.
- Animal Nutrition:Feed-grade vitamin premixes for livestock and aquaculture with lower purity thresholds and price-sensitive procurement.
- Personal Care:Topical vitamin applications in cosmeceuticals with stability challenges in emulsion matrices.
- Infant Nutrition:Formula fortification with stringent microbiological and heavy metal specifications under Codex Alimentarius and national food safety regimes.
Dietary Supplements retains the volume anchor while Functional Foods expands most quickly on brand-direct technical partnerships.
End User:
Scale concentration and specification expertise determine which customer categories command supplier attention and dedicated service relationships.
- Pharmaceutical Firms:Prescription drug manufacturers requiring USP-certified vitamin concentrates with batch-level serialization and pharmacopeial harmonization between USP, EP, and ChP standards. These buyers are consolidating procurement among fermentation specialists with captive quality infrastructure.
- Food & Beverage Producers:Large beverage and dairy processors embedding vitamin technologists within innovation teams to accelerate fortification claim development. Cooperative dairy giants in Denmark operate centralized ingredient specification functions that bypass traditional distributors.
- Supplement Manufacturers:Branded and private-label dietary supplement companies with formulation flexibility but squeezed margins on commodity vitamin inputs.
- Animal Feed Companies:Integrated livestock operations and premix blenders with volume-driven, price-sensitive procurement of feed-grade vitamins.
- Cosmetic Companies:Personal care formulators requiring micronized or encapsulated vitamin variants for stability in emulsion systems.
- Infant Formula Makers:Specialized nutrition producers with the most stringent contaminant thresholds and documentation requirements.
Pharmaceutical Firms anchor premium volume while Food & Beverage Producers drive the fastest procurement relationship restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fermentation houses export vitamin B complex concentrates to European pharmaceutical formulators under tightening GB standard compliance requirements. German chemical conglomerates ship synthetic vitamin precursors to Indian contract manufacturers expanding under PLI scheme incentives. This trade architecture concentrates regulatory scrutiny at three customs frontiers.
China
Domestic fermentation capacity supplies bulk vitamin C and B complexes to global pharmaceutical and feed-grade buyers. NMPA and SAMR enforce GB standard purity thresholds that filter uncertified suppliers from high-margin export segments. Shandong Peninsula chemical parks host concentrated acetone-based vitamin A synthesis operations serving Asian nutraceutical processors.
Germany
Large-scale vitamin B complex fermentation facilities anchor European pharmaceutical-grade supply chains for DSM and BASF. EMA quality guidelines for active pharmaceutical ingredients mandate batch-level traceability that locks in long-term supply contracts. North Rhine-Westphalia industrial clusters concentrate backward-integrated petrochemical precursor production for synthetic vitamin routes.
United States
Pharmaceutical firms expand vitamin procurement for prescription-grade deficiency treatments under FDA cGMP traceability mandates. Dietary supplement manufacturers face batch-level serialization requirements that favor verified fermentation houses with pharmaceutical-grade documentation. New Jersey and Pennsylvania pharmaceutical corridors concentrate finished dosage formulation demand.
India
PLI scheme incentives for fermentation infrastructure attract pharmaceutical-grade vitamin investment away from legacy European bases. CDSCO alignment with USP and EP standards enables contract manufacturing for regulated export markets. Maharashtra and Gujarat industrial zones concentrate emerging fermentation capacity for vitamin B complex derivatives.
Switzerland
Nutraceutical brands adopt precision-fermented vitamin B12 and K2 formats for premium positioning in bioidentical segments. Swissmedic pharmaceutical-grade enforcement creates market access barriers that favor pre-qualified fermentation specialists. Basel-Zurich corridor clusters precision fermentation technology development for rare vitamin analog synthesis.
Global Vitamin Ingredients Market Competitive Landscape
Listed leaders compete with private specialists across documentation intensity and purity-grade certification tiers. The vendor base stratifies between fermentation houses with captive quality infrastructure and chemical synthesis operators exposed to petrochemical feedstock volatility. Three archetypes dominate: backward-integrated petrochemical players, fermentation specialists with pharmaceutical-grade certification, and precision fermentation technology developers. Competitive moves center on M&A to secure fermentation capacity and strategic partnerships to embed technical service relationships with food multinationals.
Within the fermentation-specialist tier, Koninklijke DSM N.V. and Lonza Group exemplify pharmaceutical-grade positioning through biotechnology platforms and bacterial fermentation expertise. BASF SE represents the backward-integrated petrochemical archetype with synthetic vitamin production anchored in precursor control. These three entities occupy positions across the purity-grade spectrum from feed-grade commodity supply to USP-certified pharmaceutical concentrates.
| Leading Market Players |
|---|
| BASF SE |
| Koninklijke DSM N.V. |
| Glanbia Plc |
| Lonza Group |
| Archer Daniels Midland Company |
| Bluestar Adisseo Company |
| Abbott Laboratories |
| Nestlé S.A. |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
Large-scale fermentation capacity utilization in Germany and China establishes minimum viable scale thresholds that filter sub-scale producers and anchor price floors for USP-certified vitamin concentrates. Pharmaceutical-grade documentation burdens compound fixed-cost absorption, concentrating margin pressure on uncertified suppliers while locking in premium tiers for verified fermentation houses.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels dominates procurement contracts, with FDA cGMP batch-level serialization and USP potency verification commanding substantial premiums over commodity feed-grade volumes. Price differentiation hinges on certification tier and captive fermentation infrastructure, with backward-integrated petrochemical players exposed to acetone and acetic anhydride feedstock volatility. Cost compression in synthetic vitamin routes is intensifying because energy-price transmission affects precursor economics. Animal feed companies exhibit highest price sensitivity, while pharmaceutical firms accept premium pricing for pharmacopeial-harmonized documentation.
Supply Chain Analysis
Strategic stockpiling of vitamin B complex concentrates prevails among European pharmaceutical formulators facing China's GB standard compliance windows, while just-in-time procurement governs feed-grade commodity flows. Supply concentrates in Shandong Peninsula chemical parks for acetone-based vitamin A synthesis, North Rhine-Westphalia industrial clusters for petrochemical precursors, and Maharashtra-Gujarat zones for emerging fermentation capacity. Raw material dependencies include acetone feedstocks, corn-derived fermentation substrates, and gelatin for soft gel encapsulation. Single-source vulnerability clusters around large-scale vitamin B complex facilities in Germany and China. Distribution runs through brand-direct technical partnerships displacing traditional distributor mediation for functional food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among pharmaceutical firms and cooperative dairy giants, with procurement consolidation forcing supplier capitulation on documentation burdens and long-term contract terms.
For Market Incumbents: Secure fermentation capacity expansion in India under PLI scheme incentives to offset geographic single-point vulnerability in Germany and China. Lock in brand-direct technical partnerships with beverage multinationals before precision fermentation platforms fragment procurement patterns further. Backward integration into petrochemical precursors remains critical for synthetic vitamin producers facing feedstock volatility. For New Entrants and Emerging Players: Lead with precision fermentation capabilities for rare vitamin analogs like B12 and K2 where bioidentical positioning commands premium pricing. Target Swiss and German nutraceutical brands adopting cell-culture formats for clean-label differentiation. Partner with Indian contract manufacturers seeking pharmaceutical-grade certification for regulated export markets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation specialists with captive quality infrastructure and long-term pharmaceutical supply contracts. Five-to-ten-year viability favors assets with USP-EP-ChP harmonization capabilities and modular bioreactor technology. Watch for FDA cGMP enforcement intensity as inflection signal for documentation-burden escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Enables commercial production of bioidentical vitamin B12 and K2 for premium nutraceutical positioning. |
| Backward Integration into Precursors | Controls acetone and acetic anhydride substance flow data for REACH compliance in EU manufacturing. |
| Pharmaceutical-Grade Certification Investment | Secures USP-certified supply contracts with FDA-mandated batch-level serialization requirements. |
| Brand-Direct Technical Partnership | Embeds vitamin technologists within cooperative dairy innovation teams in Netherlands and Denmark. |
| India PLI Scheme Capacity Expansion | Attracts fermentation investment away from legacy European bases with contract manufacturing incentives. |
Research Methodology
Desk research of pharmacopeial standards documentation, customs trade records, and SEC filings preceded structured interviews with fermentation plant managers, pharmaceutical procurement leads, regulatory affairs directors, and functional food innovation executives. Primary fieldwork combined with secondary validation from FDA cGMP guidance, EMA quality guidelines, and China's GB standard repositories. Bottom-up capacity modeling triangulated against top-down demand segmentation across purity grades and end-use applications.
Variance decomposition across the projection horizon isolates volume drivers by vitamin type, purity grade tier, delivery format, and regional regulatory cluster. CAGRs derive from segmented growth rate aggregation weighted by revenue contribution. Forecast inputs incorporate fermentation capacity utilization rates, petrochemical precursor price indices, and pharmacopeial harmonization timeline assumptions.
The analysis sits within stated boundaries; outcomes outside sustained FDA cGMP enforcement intensity, China's GB standard compliance stability, and precision fermentation technology cost curves would require recalibration. Forecasts reflect documented assumptions regarding regulatory trajectory and feedstock economics. Revision becomes warranted when pharmaceutical-grade purity mandate adoption crosses threshold penetration in emerging manufacturing bases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Guar Gum Market
Ingredients
Meat Tenderizer Powder Market
Ingredients
Rose Extract Market
Ingredients
South America Vegetable Oil Market
Ingredients
Grape Skin Extract Market
Ingredients
Edible Halal Gelatin Market
Ingredients
Cocoa Liquor Market
Ingredients
Soy Lecithin Market
Ingredients
Wheat Malt Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
Vegan Ingredients Market
Ingredients
Banana Essence Market
Ingredients
Asia-Pacific Plant Protein Ingredients Market
Ingredients
Sunflower Protein Market
Ingredients
Pomegranate Peel Polyphenol Complex Market
Ingredients
Hydrolyzed Animal Protein Market