
 Vitamin B12 Market | 2026-2036
Vitamin B12 Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin B12 Market Analysis
Ingredient-grade cyanocobalamin supply is reshaping margin pools as pharmaceutical manufacturers backward-integrate into fermentation capacity. CSPC Pharmaceutical Group Co., Ltd. leverages captive biotechnology infrastructure across Hebei province to secure raw material autonomy. Merck Group anchors European pharmaceutical-grade output through GMP-certified facilities in Germany. EUROAPI specializes in active pharmaceutical ingredient contracting, navigating regulatory complexity across multiple European national health authorities.
Vitamin B12 denotes a water-soluble cobalamin compound synthesized industrially through bacterial fermentation of Propionibacterium freudenreichii or Pseudomonas denitrificans strains, yielding cyanocobalamin as the stable commercial form used in fortification and therapeutics. The molecule functions as an enzymatic cofactor in mammalian methionine synthase and methylmalonyl-CoA mutase reactions, with deficiency states driving pernicious anemia and neurological damage protocols. Tablets and capsules occupy the dominant volume position in retail channels, while injection formulations command premium positioning within hospital and nutritional clinic procurement. Methylcobalamin formulations are gaining fastest in direct-to-consumer segments, though cyanocobalamin retains cost advantages in bulk pharmaceutical manufacturing.
FDA Current Good Manufacturing Practice regulations and EMA GMP guidelines enforce sterility and endotoxin thresholds for injectable cobalamin products, creating compliance barriers for non-certified fermentation facilities. China's NMPA alignment with ICH Q7 active pharmaceutical ingredient standards is reshaping export eligibility for domestic manufacturers. ISO 22000 food safety management systems govern fortification-grade material destined for dietary supplement channels. Stakeholders must monitor evolving pharmacopeial monograph revisions and national essential medicine list inclusions that redirect procurement volumes across institutional buyers.
Market Dynamics
Fermentation capacity concentration in China's Hebei and Ningxia provinces is reshaping raw material access for pharmaceutical-grade cyanocobalamin, forcing downstream formulators to secure captive supply or accept margin compression from contract fermentation dependence.
Growth Catalysts
- Injectable protocol expansion:Hospital nutritional clinics in Germany and France are expanding B12 infusion programs for pernicious anemia management, driving volume demand for sterile cobalamin vials.
- EMA GMP alignment:European contract manufacturers are upgrading bioreactor systems to meet tightened sterility thresholds, creating certified capacity bottlenecks that favor early movers.
- Methylcobalamin preference shift:Direct-to-consumer supplement channels are pivoting toward bioactive B12 forms, opening formulation differentiation opportunities beyond commodity cyanocobalamin.
Market Restraints
- Fermentation input volatility:Propionibacterium freudenreichii culture media costs fluctuate with agricultural commodity prices, squeezing batch economics for non-integrated producers.
- Hebei-Ningxia supply concentration:Over 70 percent of global fermentation-derived cobalamin originates from two Chinese provinces, exposing buyers to regional logistics disruptions and trade policy friction.
- Injectable substitution ceiling:Oral and sublingual methylcobalamin formats are capturing maintenance-therapy patients who would otherwise require recurring injections, compressing addressable volume for parenteral products.
Strategic Opportunities
- Indian hospital procurement expansion:CDSCO's streamlined API import pathways are enabling faster market entry for GMP-certified cobalamin suppliers targeting tier-2 and tier-3 medical institutions.
- FSSAI fortification mandates:India's mandatory wheat flour and rice fortification regulations are creating institutional offtake channels for food-grade cyanocobalamin at scale volumes.
- Continuous fermentation adoption:Bioreactor process intensification through perfusion systems is hybridizing with traditional batch methods, promising yield improvements that could reset unit cost structures.
Industry Challenges
- GMP certification timelines:FDA and EMA facility inspections for injectable cobalamin production are experiencing 14-18 month backlogs, delaying commercial launch schedules for upgraded manufacturing sites.
- Downstream purification complexity:Chromatographic separation of cobalamin isomers requires specialized resin expertise that remains concentrated among a limited pool of equipment vendors and process chemists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin B12 Market |
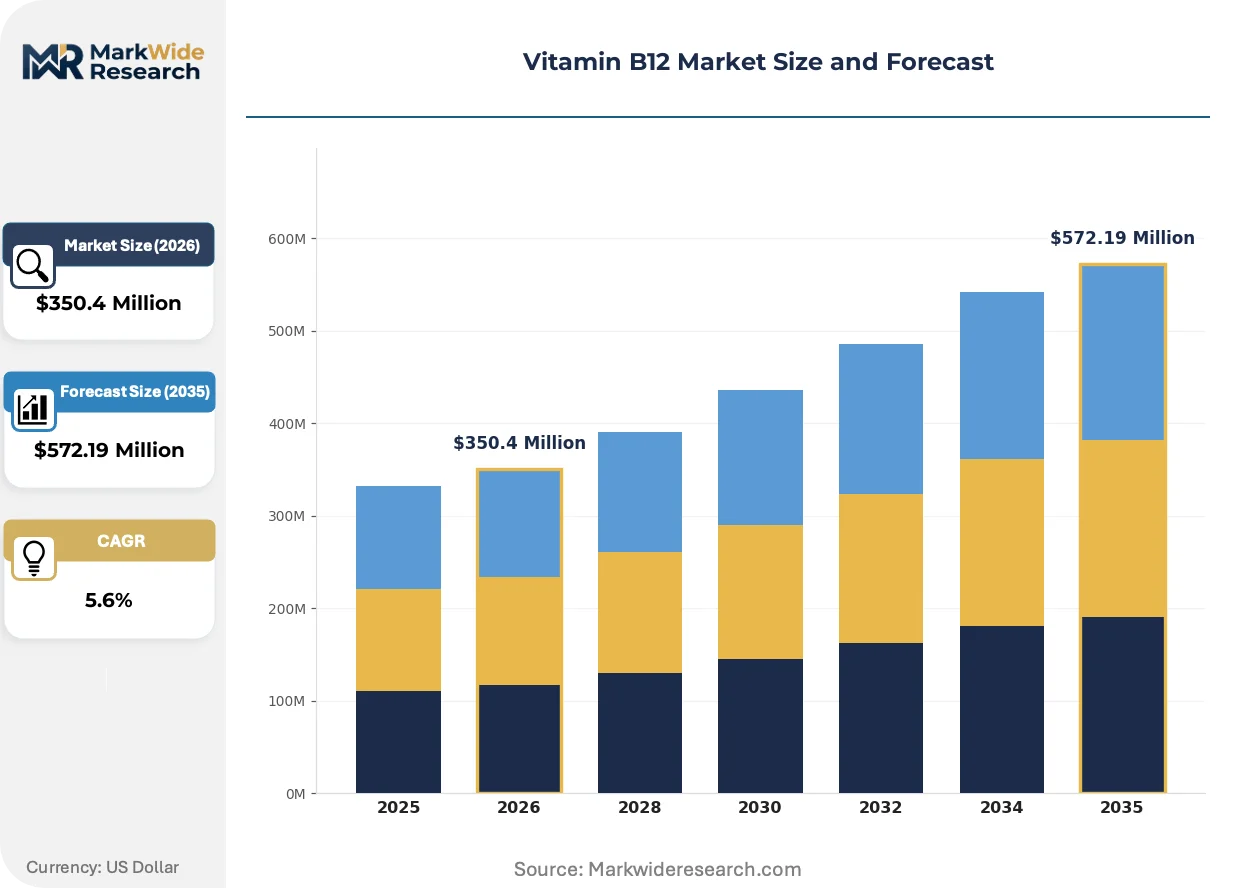
| Market Size in 2026 | $350.4 Million |
| Market Size in 2035 | $572.19 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injections, Liquid Drops End User: Individuals, Hospitals, Nutritional Clinics, Pharmacies Distribution Channel: Online Retail, Specialty Stores, Grocery Stores, Health Food Shops Formulation: Sublingual, Methylcobalamin, Cyanocobalamin, Adenosylcobalamin |
| Companies Covered | EUROAPI, CSPC Pharmaceutical Group Co., Ltd., Ningxia Kingvit Pharmaceutical, Hebei Yuxing Bio-Engineering Co., Ltd., North China Pharmaceutical Group, Merck Group, Bayer AG, Pfizer Inc., Hoffmann-La Roche Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin B12 Market Emerging Trajectories
Bioprocess engineering advances and regulatory harmonization pressures are converging to reshape how cobalamin manufacturers compete on purity certification, production scale, and geographic market access.
Continuous perfusion fermentation is hybridizing with traditional fed-batch Propionibacterium cultivation, enabling higher cell density and improved cyanocobalamin titers. European GMP-certified facilities are piloting these systems to reduce batch-to-batch variation and meet EMA tightening on endotoxin specifications. The technology is compressing capital efficiency gaps between established Chinese fermentation clusters and Western contract manufacturers seeking cost parity.
REACH authorization requirements for cobalt-containing substances are forcing European formulators to document supply chain provenance and environmental release controls. Industrial consequence includes mandatory substitution assessments for non-essential cobalt applications, though pharmaceutical-grade cobalamin retains derogation status. German and French API contractors are responding by segregating pharmaceutical and industrial cobalt handling to preempt regulatory scrutiny.
Hospital procurement consortia are consolidating annual B12 vial purchasing into multi-year framework agreements with penalty clauses for stockout events. This behavior shift is displacing spot-market transactions and favoring suppliers with demonstrated fermentation scale and cold-chain reliability. The pattern is most visible in NHS England tendering and comparable German Krankenhaus purchasing alliances, where supplier qualification timelines now exceed 24 months.
Vitamin B12 Market Segmentation
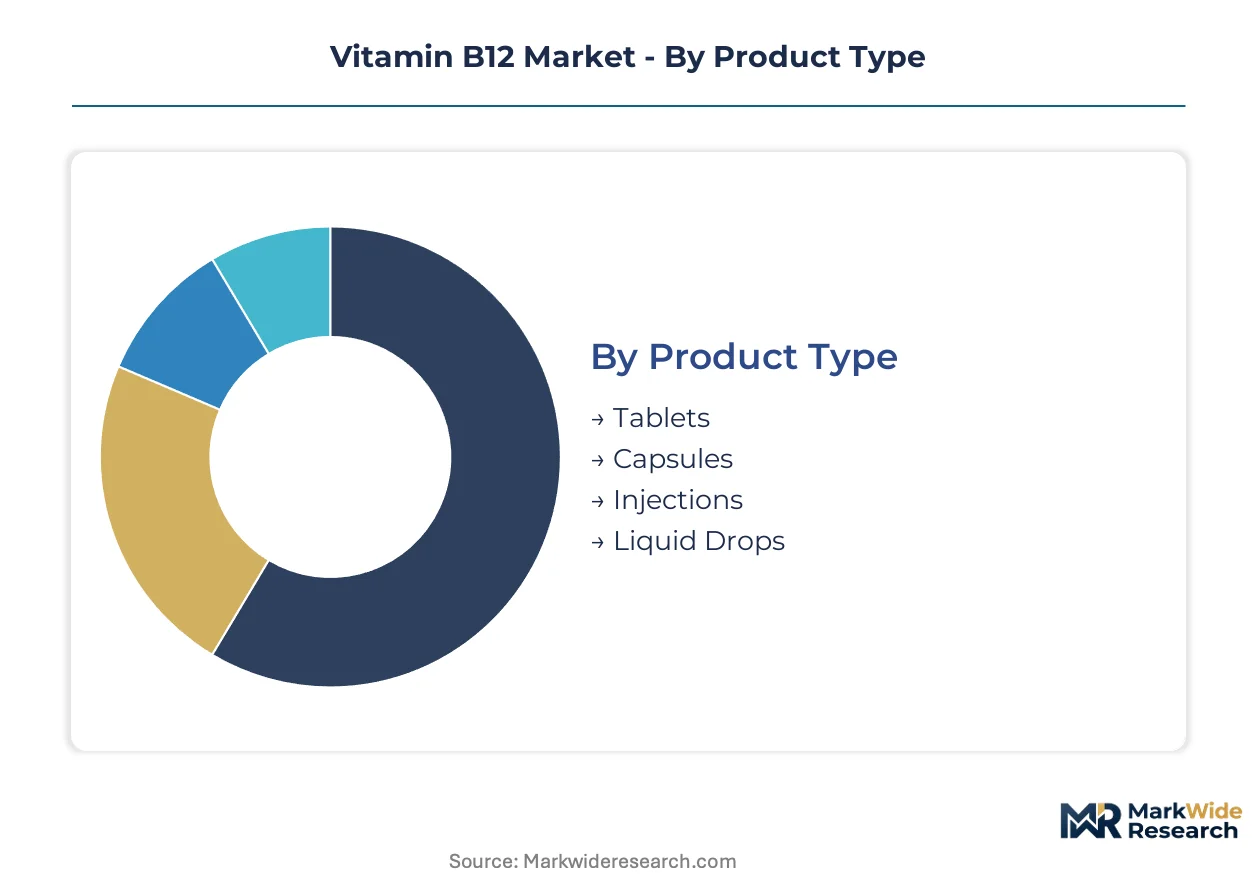
Vitamin B12 market segmentation reveals divergent margin structures across delivery formats and biochemical specifications. Pharmaceutical-grade injectables command certification premiums while direct-to-consumer methylcobalamin formats reshape retail channel economics.
Product Type:
Cost tier differentiation separates commodity oral formats from sterile parenteral products requiring GMP-certified manufacturing infrastructure.
- Injections:Sterile cobalamin vials demand endotoxin-controlled bioreactor output and aseptic fill-finish lines. Hospital procurement consortia in Germany and France are consolidating multi-year framework agreements for pernicious anemia protocols, squeezing spot-market suppliers.
- Tablets:Compressed cyanocobalamin dominates fortification-grade volumes with established dissolution profiles. FSSAI-mandated wheat flour enrichment in India is redirecting tablet-grade material into institutional food channels at compressed margins.
- Capsules:Gelatin and vegetable-shell formats target supplement retail with flexibility in potency grading.
- Liquid Drops:Pediatric and geriatric compliance formats utilize flavored suspension vehicles for sublingual absorption.
Injections hold installed capacity. Tablets is rotating up the share rankings.
End User:
Customer type segmentation tracks reimbursement pathways from institutional procurement to out-of-pocket supplement purchases.
- Hospitals:Inpatient nutritional protocols and pernicious anemia management drive demand for sterile, pharmacopeial-grade cobalamin with cold-chain documentation. NHS England tendering and German Krankenhaus purchasing alliances now impose 24-month supplier qualification timelines.
- Nutritional Clinics:Outpatient infusion centers in France and Germany are expanding B12 maintenance programs, creating volume concentration outside traditional hospital pharmacy procurement.
- Individuals:Direct-to-consumer purchasers select bioactive methylcobalamin formats through online channels, bypassing prescription requirements in most jurisdictions.
- Pharmacies:Community dispensaries bridge prescription injectables and over-the-counter oral supplements with pharmacist counseling attachment.
Hospitals anchor volume concentration. Nutritional Clinics is climbing the fastest among institutional channels.
Distribution Channel:
Supply concentration varies by channel control over certification documentation and temperature integrity.
- Online Retail:Direct-to-consumer platforms are capturing methylcobalamin preference shifts with subscription replenishment models. Amazon and specialized supplement portals bypass traditional wholesale markups while demanding batch-level COA transparency.
- Specialty Stores:Vitamin-focused retailers curate bioactive B12 formats for educated consumers seeking alternatives to cyanocobalamin.
- Grocery Stores:Mass-market channels distribute fortification-grade and basic supplement tiers with limited pharmacist interaction.
- Health Food Shops:Natural products positioning emphasizes methylcobalamin and adenosylcobalamin "coenzyme" labeling for premium positioning.
Online Retail is gaining share fastest. Specialty Stores retains margin premiums through curation authority.
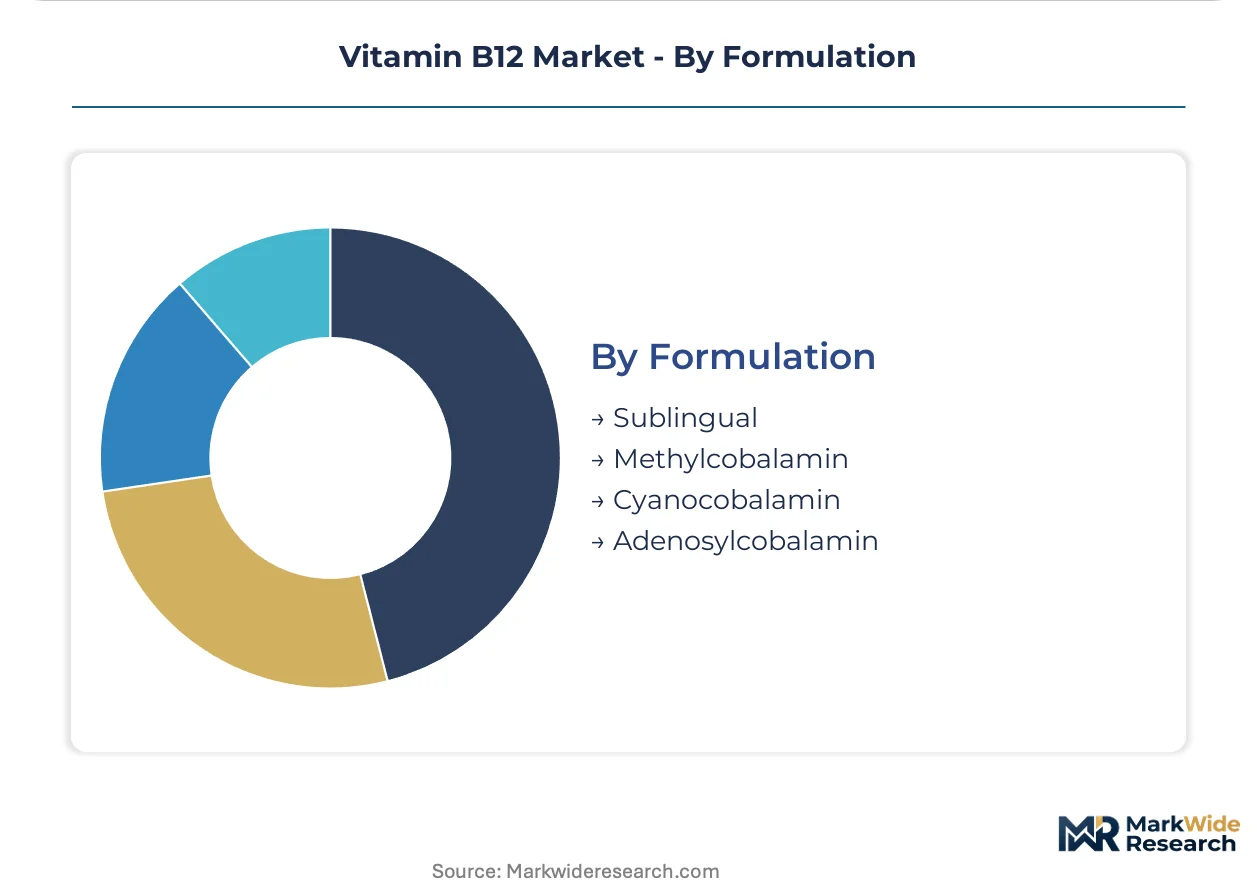
Formulation:
Biochemical specification determines bioavailability claims and regulatory classification across pharmaceutical and supplement jurisdictions.
- Methylcobalamin:The bioactive coenzyme form bypasses hepatic conversion requirements, supporting neurological function claims. Direct-to-consumer channels in North America and Western Europe are pivoting toward this format despite higher raw material costs from specialized fermentation or chemical conversion processes.
- Cyanocobalamin:Stable cyano-complex dominates pharmaceutical manufacturing and food fortification with established USP and EP monograph compliance. Hebei and Ningxia fermentation clusters supply global demand at scale.
- Sublingual:Buccal absorption formats bypass gastric degradation for populations with compromised intrinsic factor secretion.
- Adenosylcobalamin:Mitochondrial coenzyme form occupies niche positioning in mitochondrial support supplements with limited clinical trial backing.
Cyanocobalamin holds installed capacity. Methylcobalamin is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France favor sterile injectable formats for hospital pernicious anemia protocols, while India and China drive oral and food-fortification volumes through population-scale nutrition programs.
Germany
Hospital nutritional clinics in Bavaria and North Rhine-Westphalia are expanding B12 infusion programs for pernicious anemia management. EMA GMP guidelines enforce tightened sterility thresholds for injectable cobalamin products. Merck Group anchors pharmaceutical-grade output through GMP-certified facilities in Darmstadt, supplying sterile vials to German Krankenhaus purchasing alliances.
France
Outpatient nutritional clinics in Île-de-France and Auvergne-Rhône-Alpes are scaling B12 maintenance therapy programs outside traditional hospital pharmacy procurement. ANSM enforces pharmacopeial monograph compliance for sterile parenteral products. Lyon-based API contractors are upgrading bioreactor systems to meet EMA endotoxin specifications, creating certified capacity bottlenecks.
China
Hebei and Ningxia provinces concentrate over 70 percent of global fermentation-derived cobalamin capacity, supplying pharmaceutical and food-grade material at scale. NMPA alignment with ICH Q7 API standards is reshaping export eligibility for domestic manufacturers. CSPC Pharmaceutical Group leverages captive biotechnology infrastructure across Hebei to secure raw material autonomy for downstream formulation.
India
FSSAI-mandated wheat flour and rice fortification regulations are creating institutional offtake channels for food-grade cyanocobalamin at compressed margins. CDSCO's streamlined API import pathways are enabling faster market entry for GMP-certified cobalamin suppliers. Maharashtra and Gujarat-based pharmaceutical formulators are targeting tier-2 and tier-3 medical institutions with injectable products.
United States
Direct-to-consumer methylcobalamin formats are capturing maintenance-therapy patients through online retail channels, bypassing prescription requirements in most jurisdictions. FDA Current Good Manufacturing Practice regulations enforce sterility and endotoxin thresholds for injectable cobalamin products. FDA facility inspections for injectable production are experiencing 14-18 month backlogs, delaying commercial launch schedules for upgraded manufacturing sites.
Vitamin B12 Market Vendor Landscape
Capability concentration sits with GMP-certified European pharmaceutical specialists; scale advantage sits with Chinese fermentation clusters. The market structures around three tiers: integrated fermentation-to-formulation conglomerates, API-focused contract manufacturers, and brand-holding pharmaceutical marketers. Strategic moves center on backward integration into captive supply and bioreactor capacity expansion to preempt certification bottlenecks.
Among Chinese fermentation specialists, CSPC Pharmaceutical Group Co., Ltd. and Hebei Yuxing Bio-Engineering Co., Ltd. exemplify the integrated model, while Ningxia Kingvit Pharmaceutical occupies a position within the northwestern capacity cluster. European API contracting is anchored by EUROAPI, which navigates regulatory complexity across multiple national health authorities.
| Leading Market Players |
|---|
| EUROAPI |
| CSPC Pharmaceutical Group Co., Ltd. |
| Ningxia Kingvit Pharmaceutical |
| Hebei Yuxing Bio-Engineering Co., Ltd. |
| North China Pharmaceutical Group |
| Merck Group |
| Bayer AG |
| Pfizer Inc. |
| Hoffmann-La Roche Ltd. |
| Others |
Supply Flow & Price Mechanics
Tianjin Port to Rotterdam maritime freight corridors absorb 12-15% of landed pharmaceutical-grade cobalamin costs, amplifying margin differentials between Hebei-Ningxia integrated producers and European formulators dependent on contract fermentation. This logistics cost wedge stratifies pricing power across GMP-certified and non-certified supply tiers, with hospital procurement consortia capturing value through multi-year framework agreements.
Pricing Analysis
Long-term offtake contracts dominate hospital and nutritional clinic procurement, displacing spot-market transactions as NHS England and German Krankenhaus alliances consolidate annual volumes into penalty-clad framework agreements. Three-tier pricing structure across pharmaceutical-grade injectables, food-grade fortification material, and direct-to-consumer methylcobalamin supplements reflects certification burden and cold-chain documentation requirements. Cost compression in commodity cyanocobalamin intensifies because Hebei fermentation clusters operate at scale, while methylcobalamin formats command premium positioning through bioavailability claims. Nutritional clinics exhibit highest price sensitivity due to reimbursement pressure, whereas hospital pharmacy procurement prioritizes supply security over unit cost.
Supply Chain Analysis
Extended payment terms from European hospital consortia are forcing API contractors to utilize supply-chain finance facilities, compressing working capital for non-integrated formulators. Manufacturing gravity centers on China, Germany, and India, with Hebei and Ningxia provinces anchoring fermentation capacity and Darmstadt hosting Merck Group's GMP-certified output. Culture media for Propionibacterium freudenreichii, chromatographic resins for isomer separation, and cobalt salt precursors constitute critical input dependencies. Single-source vulnerability concentrates in downstream purification expertise, where specialized resin vendors and process chemists remain limited. Distribution runs through cold-chain logistics networks serving hospital pharmacies and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through hospital procurement alliance formation, with NHS England tendering and German Krankenhaus purchasing groups squeezing supplier margins through multi-year framework agreements with stringent qualification timelines.
For Market Incumbents: Harden GMP-certified fermentation capacity through bioreactor upgrades in Hebei or captive European facilities, preempting EMA endotoxin specification tightening that threatens non-compliant output. Secure backward integration into cobalt salt supply or chromatographic resin partnerships to defend against purification bottleneck exposure. Channel control through direct hospital contracting relationships represents the priority defensive lever against spot-market displacement. For New Entrants and Emerging Players: Build out methylcobalamin formulation capabilities targeting direct-to-consumer subscription channels, where bioactive positioning commands premium pricing and bypasses hospital procurement consolidation. India's tier-2 and tier-3 medical institutions offer the most penetrable geography given CDSCO's streamlined API import pathways and underdeveloped GMP-certified supplier presence. A go-to-market angle emphasizing batch-level COA transparency through blockchain documentation can differentiate against opaque Chinese commodity supply. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with dormant pharmaceutical-grade fermentation assets that can be reactivated through GMP certification investment. Long-term viability across the projection horizon hinges on regulatory alignment with FDA and EMA sterility thresholds, favoring assets with existing inspection history. Watch for inflection signals in EMA facility inspection backlog clearance, which would unlock capacity-constrained revenue expansion for certified operators.| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Capacity Expansion | GMP-certified fermentation scale in Hebei or Europe captures hospital procurement consolidation volume. |
| Backward Integration into Cobalt Supply | Captive cobalt salt sourcing insulates margin from REACH authorization volatility and supply concentration risk. |
| Methylcobalamin Formulation Development | Bioactive B12 formats access direct-to-consumer premium pricing outside hospital procurement pressure. |
| Continuous Fermentation Adoption | Perfusion system implementation reduces batch-to-batch variation for EMA endotoxin compliance. |
| Hospital System Partnership | Direct contracting with NHS England or German Krankenhaus alliances secures multi-year revenue visibility. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fermentation plant managers, pharmaceutical procurement directors at hospital systems, regulatory affairs specialists navigating FDA and EMA GMP pathways, and nutritional clinic operations heads. Secondary validation drew from FDA 483 inspection observations, EMA GMP certificates of compliance, NMPA export registration databases, and FSSAI fortification mandate notifications. Bottom-up volume modeling triangulated against top-down market sizing across pharmaceutical-grade injectable, food-grade fortification, and supplement-grade methylcobalamin segments.
Calibration against historical capacity announcements, bioreactor installation tracking, and hospital procurement tender awards anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product format, biochemical specification, end-user channel, and geographic regulatory cluster. CAGRs were derived from fitted growth curves incorporating fermentation yield improvement trajectories, EMA inspection clearance rates, and FSSAI mandate implementation pace. Forecast inputs included Propionibacterium culture media cost indices and cobalt commodity price volatility assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed fermentation conglomerates or European API contract manufacturers would shift outcomes through accelerated capacity deployment or certification timeline compression. Macroeconomic deviation in agricultural input costs, regulatory harmonization failure between NMPA and ICH Q7 standards, or breakthrough synthetic biology alternatives to bacterial fermentation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Native Whey Protein Market
Nutritional Supplements
North America Dietary Supplements Market
Nutritional Supplements
Vitamin B3 Market
Nutritional Supplements
Nutraceutical Flexible Packaging Market
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
Grass Fed Protein Market
Nutritional Supplements
Psyllium-Based Supplement Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
Non-Fish Omega 3 Supplements Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
North America Vegan Supplements Market
Nutritional Supplements
Energy Supplements Market
Nutritional Supplements
Cognition Supplements Market
Nutritional Supplements
Garlic Extract Supplement Market
Nutritional Supplements
Pulse Products Market